
 Industrial Electronics Packaging Market | 2026-2036
Industrial Electronics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Electronics Packaging Market Outlook
Market Overview
Specialized tooling engineer availability is bifurcating the competitive landscape between precision-mold specialists and commodity converters. DS Smith leverages its European fiber-based infrastructure to serve automotive electronics tier ones with recyclable enclosure platforms. Amcor sustains polymer film leadership through captive R&D in high-barrier laminates for moisture-sensitive components. Sealed Air Corporation differentiates via automated void-fill systems integrated into semiconductor backend logistics.
Product and Technology Landscape
Industrial electronics packaging encompasses protective housings, interconnection systems, and power distribution substrates engineered to shield sensitive circuitry from thermal cycling, particulate intrusion, and electromagnetic interference, typically fabricated from engineered polymers, aluminum alloys, or ceramic composites with IP ratings from IP54 to IP69K. Enclosures dominate value capture due to customization intensity and thermal management integration, while cable assemblies represent the fastest-expanding segment driven by electric vehicle powertrain electrification and robotics density gains. Injection molding anchors volume production for plastic connectors and housings, though 3D printing is displacing tool-up costs for aerospace-qualified low-run power supply chassis.
Regulatory Environment
RoHS and REACH in Europe restrict cadmium, lead, and certain phthalates in polymer formulations and surface finishes, forcing compounders to reformulate halogen-free flame retardants. The EPA in the United States enforces TSCA Section 5 premanufacture notifications for novel nanocomposite barrier films, while China's GB standards mandate recyclability labeling on industrial electronics shipments. Stakeholders must monitor evolving extended producer responsibility schemes and carbon border adjustment mechanisms that will restructure material sourcing economics and regional manufacturing placement decisions.
Market Dynamics
Semiconductor backend integration is compressing packaging procurement cycles as Taiwan and South Korea fabs demand cleanroom-compatible enclosures delivered direct to wafer-level assembly floors, collapsing traditional distributor buffers.
Growth Catalysts
- EU Green Deal material mandates:REACH and RoHS thresholds are forcing compounders to certify halogen-free flame retardants, creating first-mover premiums for compliant substrate suppliers serving European automotive electronics tier ones.
- Electric vehicle powertrain electrification:Cable assembly demand from EV battery management systems and motor inverters is pulling high-temperature silicone-overmolded interconnects into volume production.
- Robotics density gains:Industrial automation deployments in German and Japanese manufacturing corridors are specifying IP69K-rated power distribution housings with integrated EMI shielding.
Market Restraints
- Engineered polymer feedstock volatility:High-performance polyamide and PBT resin prices fluctuate with benzene chain disruptions, squeezing converter margins on fixed-price automotive contracts.
- Precision mold tooling concentration:Multi-cavity hot runner systems for micro-connector housings are dominated by Austrian and Swiss toolmakers, creating 16-20 week lead time bottlenecks.
- Thermal management substitution:Aluminum die-cast enclosures with conformal coatings are displacing polymer solutions in high-power IGBT modules above 150°C junction temperatures.
Strategic Opportunities
- India PLI scheme electronics manufacturing:Subsidized semiconductor assembly and test facilities in Gujarat and Tamil Nadu are creating demand for localized packaging procurement with domestic content requirements.
- 3D printing for aerospace power supplies:Laser powder bed fusion of aluminum-silicon-magnesium alloys is enabling lot sizes below 500 units for avionics chassis without hard tooling amortization.
- Extended producer responsibility schemes:France's AGEC law and similar frameworks in Netherlands and Italy are mandating recyclability labeling that rewards fiber-based and mono-material enclosure platforms.
Industry Challenges
- Specialized tooling engineer scarcity:Mold flow simulation expertise for thin-wall electronics housings is concentrated among aging workforces in Stuttgart and Nagoya, constraining new facility ramp rates.
- Multi-standard certification timelines:Simultaneous UL 94 flammability, IEC 60529 ingress protection, and automotive AEC-Q200 qualification stretches product development cycles to 18-24 months.
- Cleanroom logistics integration:Semiconductor fabs demand ISO Class 7-compatible packaging with particle documentation, forcing converters to reconfigure warehouse and transport protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Electronics Packaging Market |
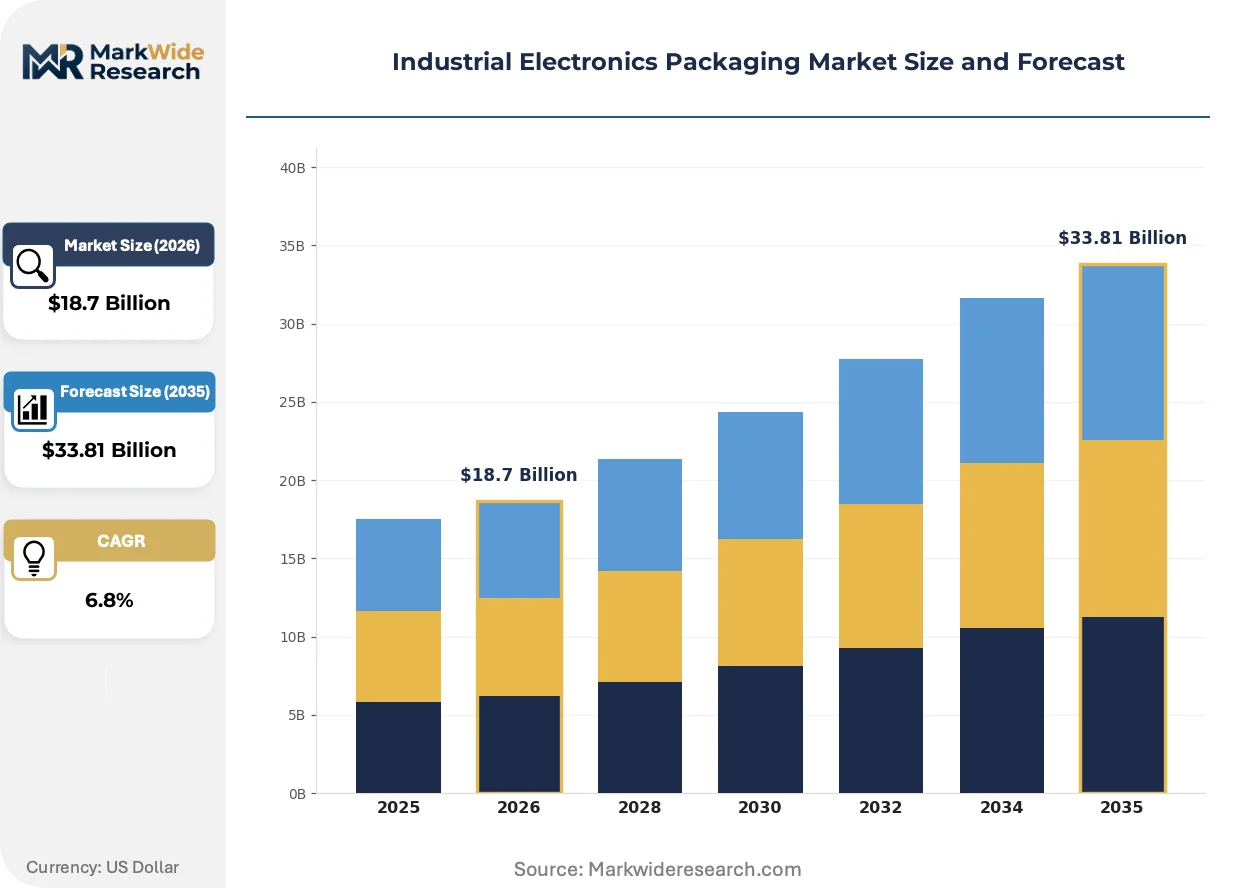
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enclosures, Connectors, Cable Assemblies, Power Supplies Material: Plastic, Metal, Composite, Ceramic End User: Manufacturing, Telecommunications, Automotive, Aerospace Technology: 3D Printing, Injection Molding, CNC Machining, Laser Cutting |
| Companies Covered | DS Smith, Smurfit Kappa Group, Amcor, UFP Technologies, DuPont de Nemours, Sealed Air Corporation, Mondi Group, Greif, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Electronics Packaging Market Strategic Shifts
Additive manufacturing workflows are fragmenting the traditional injection-mold volume hierarchy, while regulatory material bans and buyer consolidation are rewriting supplier qualification protocols across East Asian electronics corridors.
Thermally conductive polymer composites loaded with boron nitride or aluminum oxide fillers are decomposing the metal-dominant thermal management paradigm in medium-power industrial drives. German and Japanese servo motor manufacturers are qualifying these materials for 80-120 watt heat dissipation regimes. The technology is decomposing the historical trade-off between EMI shielding effectiveness and weight reduction in motion control enclosures.
REACH Annex XIV authorization requirements for certain phthalate plasticizers are forcing reformulation of PVC cable jacketing compounds used across European industrial automation installations. Compounders must submit substitution plans to ECHA or secure time-limited authorizations for continued use. Medical and food-contact electronics segments are accelerating migration to TPU and TPE alternatives ahead of automotive and general industrial adopters.
Direct procurement contracts between semiconductor fabs and packaging converters are eliminating traditional electronics distributor intermediaries for cleanroom-grade enclosure categories. TSMC and Samsung Foundry backend facilities in Hsinchu and Pyeongtaek are mandating vendor-managed inventory with dock-to-line delivery. Taiwan and South Korea manufacturing clusters exhibit the most advanced integration, with similar patterns emerging in Intel's Arizona and Ohio fab developments.
Industrial Electronics Packaging Market Segmentation
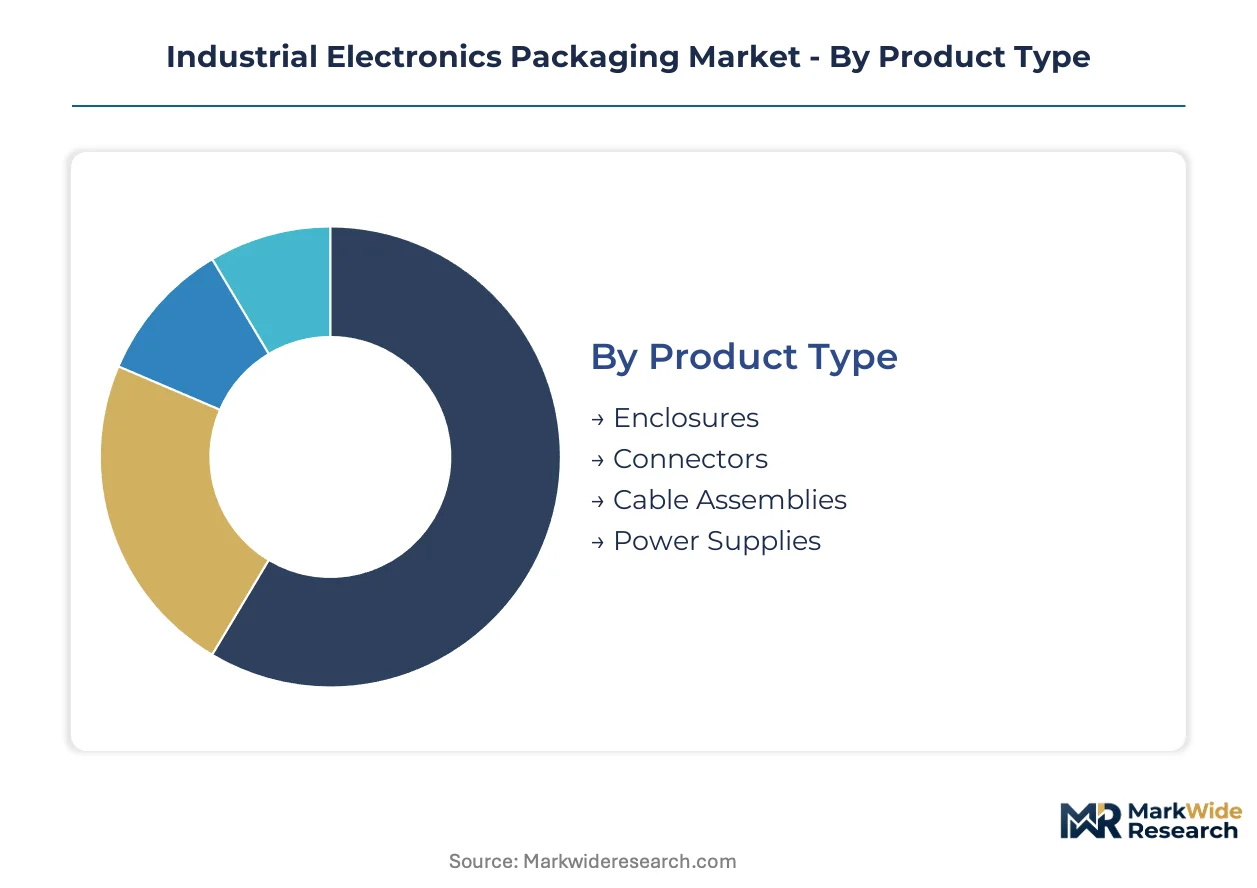
Segmentation in industrial electronics packaging reveals divergent supply chain architectures. Product categories split between high-volume automotive procurement and precision aerospace programs. Material choices increasingly trace regulatory boundaries rather than pure performance optimization.
Product Type:
Domestic consumption dominates enclosure and connector procurement in East Asian manufacturing corridors, while cable assemblies and power supplies sustain substantial export flows to European automotive tier ones.
- Enclosures:Engineered polymer and aluminum housings with integrated thermal management channels protect circuitry from particulate intrusion and electromagnetic interference. German and Japanese servo motor manufacturers specify IP69K-rated variants with boron nitride composites for 80-120 watt heat dissipation regimes.
- Cable Assemblies:High-temperature silicone-overmolded interconnects bundle power and signal transmission for electric vehicle battery management systems and motor inverters. South Korean EV battery plants pull these into volume production with just-in-time delivery mandates.
- Connectors:Multi-cavity micro-housings for industrial automation backplanes.
- Power Supplies:Avionics-qualified chassis with conformal coatings for aerospace applications.
Enclosures command the established base. The steepest expansion runs through cable assemblies.
Material:
Cost tiers separate commodity converters from precision-mold specialists, with metal and ceramic solutions capturing premium positioning against polymer volume plays.
- Plastic:High-performance polyamide and PBT resins form injection-molded connectors and housings through hot runner systems. REACH Annex XIV phthalate restrictions are forcing compounders to certify halogen-free flame retardants for European automotive electronics.
- Metal:Aluminum die-cast enclosures with conformal coatings displace polymer solutions in high-power IGBT modules above 150°C junction temperatures. Taiwanese semiconductor fabs specify these for cleanroom-compatible wafer-level assembly floors.
- Composite:Ceramic-polymer hybrids for thermal cycling resistance.
- Ceramic:Alumina substrates for extreme temperature power distribution.
Plastic anchors volume production. Metal gains share fastest in thermal-critical applications.
End User:
Application intensity varies sharply: manufacturing and automotive drive standardized procurement, while telecommunications and aerospace demand customized qualification protocols.
- Manufacturing:Industrial automation deployments in German and Japanese corridors specify IP69K-rated power distribution housings. Robotics density gains pull packaging procurement toward integrated EMI shielding and motion control compatibility.
- Automotive:EV powertrain electrification consumes high-temperature cable assemblies and battery management enclosures. Tier one suppliers face fixed-price contracts squeezed by engineered polymer feedstock volatility.
- Telecommunications:Base station infrastructure with outdoor ingress protection requirements.
- Aerospace:Low-run avionics chassis qualified through laser powder bed fusion without hard tooling amortization.
Manufacturing commands the established base. Automotive climbs the fastest on electrification pull-through.
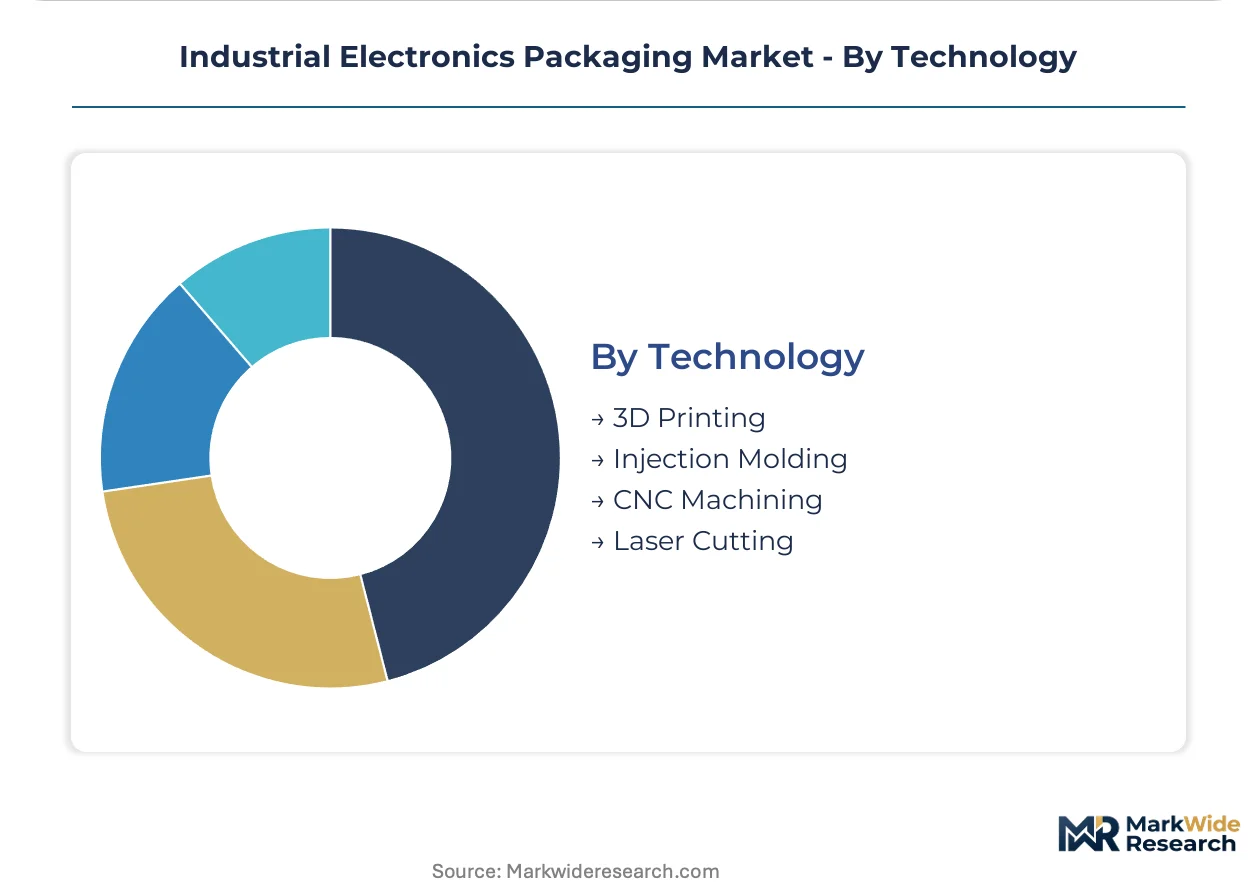
Technology:
Volume scale separates injection molding dominance from emerging additive workflows, with CNC machining and laser cutting occupying precision mid-volume niches.
- Injection Molding:Multi-cavity hot runner systems anchor volume production for plastic connectors and housings. Austrian and Swiss toolmakers concentrate mold flow simulation expertise, creating 16-20 week lead time bottlenecks for new facility ramps.
- 3D Printing:Laser powder bed fusion of aluminum-silicon-magnesium alloys enables lot sizes below 500 units for aerospace power supply chassis. The technology eliminates tool-up costs while meeting FAA qualification protocols.
- CNC Machining:Precision aluminum housings for medical electronics with tight tolerance requirements.
- Laser Cutting:Thin-gauge metal enclosure fabrication with rapid prototyping turnaround.
Injection molding commands the established base. 3D printing gains share fastest in sub-500 unit aerospace programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and RoHS directives in Europe are tightening material compliance thresholds, while semiconductor fabrication clusters in East Asia are compressing procurement cycles through direct vendor-managed inventory contracts.
Taiwan
TSMC backend facilities in Hsinchu demand ISO Class 7-compatible enclosures with particle documentation for wafer-level assembly floors. The island's semiconductor regulator enforces strict cleanroom logistics protocols. Packaging converters in Taichung and Tainan are reconfiguring warehouse operations to meet dock-to-line delivery mandates from foundry customers.
South Korea
Samsung Foundry operations in Pyeongtaek are eliminating traditional distributor intermediaries for cleanroom-grade enclosure procurement. The Korean Ministry of Trade, Industry and Energy supports domestic packaging localization through industrial cluster subsidies. Busan-Ulsan manufacturing corridors exhibit advanced integration between semiconductor assembly and packaging supply chains.
Germany
Industrial automation deployments in Stuttgart and Nagoya-equivalent manufacturing corridors specify IP69K-rated power distribution housings with integrated EMI shielding. The KBA enforces automotive electronics certification standards that stretch product development timelines. Bavarian servo motor manufacturers are qualifying thermally conductive polymer composites for 80-120 watt heat dissipation regimes.
United States
Intel's Arizona and Ohio fab developments are replicating East Asian direct procurement patterns for cleanroom-compatible packaging. The EPA enforces TSCA Section 5 premanufacture notifications for novel nanocomposite barrier films. Southwest semiconductor clusters are mandating vendor-managed inventory with collapsing traditional distributor buffers.
India
Subsidized semiconductor assembly and test facilities in Gujarat and Tamil Nadu are creating demand for localized packaging procurement with domestic content requirements. The PLI scheme incentivizes electronics manufacturing investment in designated corridors. Mumbai-Pune and Chennai-Bengaluru industrial belts are attracting packaging converters seeking to serve backend fab operations.
Industrial Electronics Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the industrial electronics packaging market. Precision-mold specialists command premium positioning through thin-wall housing expertise and thermal management integration, while commodity converters compete on polyamide and PBT resin volume throughput. The competitive structure splits between fiber-based sustainable packaging platforms and high-barrier polymer film laminates. Dominant competitive moves include strategic partnerships with semiconductor fabs for cleanroom logistics integration and capacity expansion in East Asian manufacturing corridors to capture direct procurement contracts.
Within the diversified packaging conglomerate tier, DS Smith exemplifies European fiber-based infrastructure deployment for recyclable enclosure platforms, while Amcor occupies a position representing polymer film leadership through captive R&D investment in moisture-sensitive component protection. Sealed Air Corporation anchors the automated logistics integration archetype, serving semiconductor backend operations with void-fill systems.
| Leading Market Players |
|---|
| DS Smith |
| Smurfit Kappa Group |
| Amcor |
| UFP Technologies |
| DuPont de Nemours |
| Sealed Air Corporation |
| Mondi Group |
| Greif |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Aluminum die-cast enclosure substitution for polymer solutions in high-power IGBT modules simultaneously shifts procurement geography toward Taiwanese and South Korean semiconductor corridors and compresses margin structures for European compounders facing REACH-mandated reformulation costs.
Pricing Analysis
East Asian manufacturing clusters command 15-25% price premiums over European converters for cleanroom-compatible enclosures, with differentiation anchored in ISO Class 7 certification tiers and dock-to-line delivery integration. Three-tier pricing structure across premium certified, standard industrial, and economy commodity levels stratifies the market, with automotive tier ones squeezing converter margins through fixed-price contracts despite engineered polyamide feedstock volatility. Cost compression in standard-grade polymer housings is intensifying because Austrian and Swiss toolmaker concentration creates 16-20 week lead time premiums. Automotive electronics procurement teams exhibit highest price sensitivity, while semiconductor fabs prioritize qualification speed over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication and backend assembly operations, drawing from high-performance polyamide and PBT resin feedstocks, boron nitride thermal fillers, and Austrian precision mold tooling. Single-source vulnerability concentrates in multi-cavity hot runner systems for micro-connector housings, where Stuttgart and Nagoya-based mold flow simulation expertise constrains new facility ramp rates. Distribution runs through direct vendor-managed inventory contracts between foundry customers and packaging converters, eliminating traditional electronics distributor intermediaries for cleanroom-grade categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as thermally conductive polymer composites displace metal-dominant thermal management in medium-power industrial drives, threatening established aluminum enclosure platforms.
For Market Incumbents: Compound certification advantages by securing simultaneous UL 94, IEC 60529, and AEC-Q200 qualifications ahead of REACH Annex XIV phthalate restriction deadlines. Deepen backward integration into halogen-free flame retardant compound formulation to capture first-mover premiums from European automotive electronics tier ones facing reformulation mandates. Defend against additive manufacturing encroachment in sub-500 unit aerospace programs through dedicated low-volume production cells with accelerated qualification protocols. For New Entrants and Emerging Players: Differentiate on cleanroom logistics integration capabilities to serve TSMC and Samsung Foundry backend facilities demanding ISO Class 7-compatible enclosures with particle documentation. Target India's PLI-subsidized semiconductor assembly corridors in Gujarat and Tamil Nadu, where domestic content requirements create procurement localization opportunities absent established converter relationships. Pursue dock-to-line delivery partnerships as the primary go-to-market mechanism, replicating East Asian direct procurement patterns. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision-mold specialists holding thin-wall electronics housing expertise and captive thermal management integration capabilities. Long-term viability hinges on 5-10 year positioning for extended producer responsibility scheme compliance, where France's AGEC law and Netherlands recyclability mandates reward fiber-based and mono-material enclosure platforms. Watch for Intel's Arizona and Ohio fab procurement pattern replication as the signal indicating North American direct procurement contract normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Logistics Integration | Semiconductor fabs in Hsinchu and Pyeongtaek mandate ISO Class 7-compatible dock-to-line delivery protocols. |
| Halogen-Free Flame Retardant Certification | REACH and RoHS thresholds create first-mover premiums for compliant substrate suppliers serving European automotive tier ones. |
| Additive Manufacturing Qualification | Laser powder bed fusion of aluminum-silicon-magnesium alloys enables sub-500 unit aerospace chassis without tooling amortization. |
| India PLI Localization | Subsidized semiconductor assembly facilities in Gujarat and Tamil Nadu impose domestic content requirements on packaging procurement. |
| Extended Producer Responsibility Compliance | France's AGEC law and Netherlands frameworks mandate recyclability labeling rewarding fiber-based enclosure platforms. |
Study Parameters
A spread of perspectives from semiconductor fab procurement directors, automotive electronics tier one supply chain managers, precision mold tooling engineers, polymer compounder R&D leads, and cleanroom logistics operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs and trade data, EPA TSCA Section 5 premanufacture notification records, and ECHA substitution plan submissions. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates against semiconductor backend capacity expansion announcements and EV battery plant commissioning timelines.
Segmentation dimensions modeled span product type, material composition, end-use application, and manufacturing technology across the projection horizon. The analytical framework derives CAGRs from wafer-level assembly floor expansion rates, electric vehicle powertrain electrification content per vehicle trajectories, and robotics density deployment curves in German and Japanese manufacturing corridors. Forecast inputs incorporate semiconductor fab direct procurement contract penetration rates and extended producer responsibility scheme implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained East Asian semiconductor capital expenditure, stable engineered polymer feedstock availability, and consistent REACH enforcement would require recalibration. Forecasts reflect documented assumptions regarding cleanroom logistics standardization and aluminum-polymer substitution thresholds in thermal management applications. Recalibration cycles align with material shifts in EU Green Deal implementation, India PLI scheme expansion, and Intel fab procurement pattern maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market