
 Global Display Packaging Market | 2026-2036
Global Display Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Display Packaging Market Analysis
A shift from single-source paperboard contracts toward multi-material supplier panels is repositioning procurement strategy across the display packaging value chain. Mondi leverages integrated pulp-to-board operations across Central European mills to sustain cost visibility on kraft liner grades. Amcor competes through pre-press design studios in the United States and Australia that anchor brand-agency relationships for shrink sleeve campaigns. Smurfit Kappa controls corrugated display logistics through pan-European box plant networks that dominate retail-ready shelf formats.
Display packaging denotes engineered secondary containers and point-of-sale structures fabricated from paperboard, plastic films, or rigid substrates to merchandise products while protecting contents through distribution. Folding cartons constitute the mature volume base, with converters running 6- to 8-color offset lines at speeds exceeding 15,000 sheets per hour for mass cosmetics and over-the-counter pharmaceutical applications. Blister packs capture concentrated margin pools in pharmaceutical compliance packaging where child-resistance specifications and thermoformed cavity precision command premium pricing. Shrink sleeves represent the fastest-expanding format as full-body decoration replaces applied labels on contoured beverage containers and personal care bottles.
FDA regulations on pharmaceutical labeling and child-resistant packaging directly shape blister pack design standards and testing protocols for US-bound production. The EU Green Deal and REACH chemical restrictions are forcing substrate transitions away from certain PVC formulations toward PET-G and paperboard alternatives in European consumer goods. China's SAMR packaging waste rules and GB standards for food-contact materials govern import compliance for multinational brands manufacturing in Asia. Stakeholders must monitor evolving extended producer responsibility frameworks to decide whether regional specification hubs or centralized global design centers offer superior compliance agility.
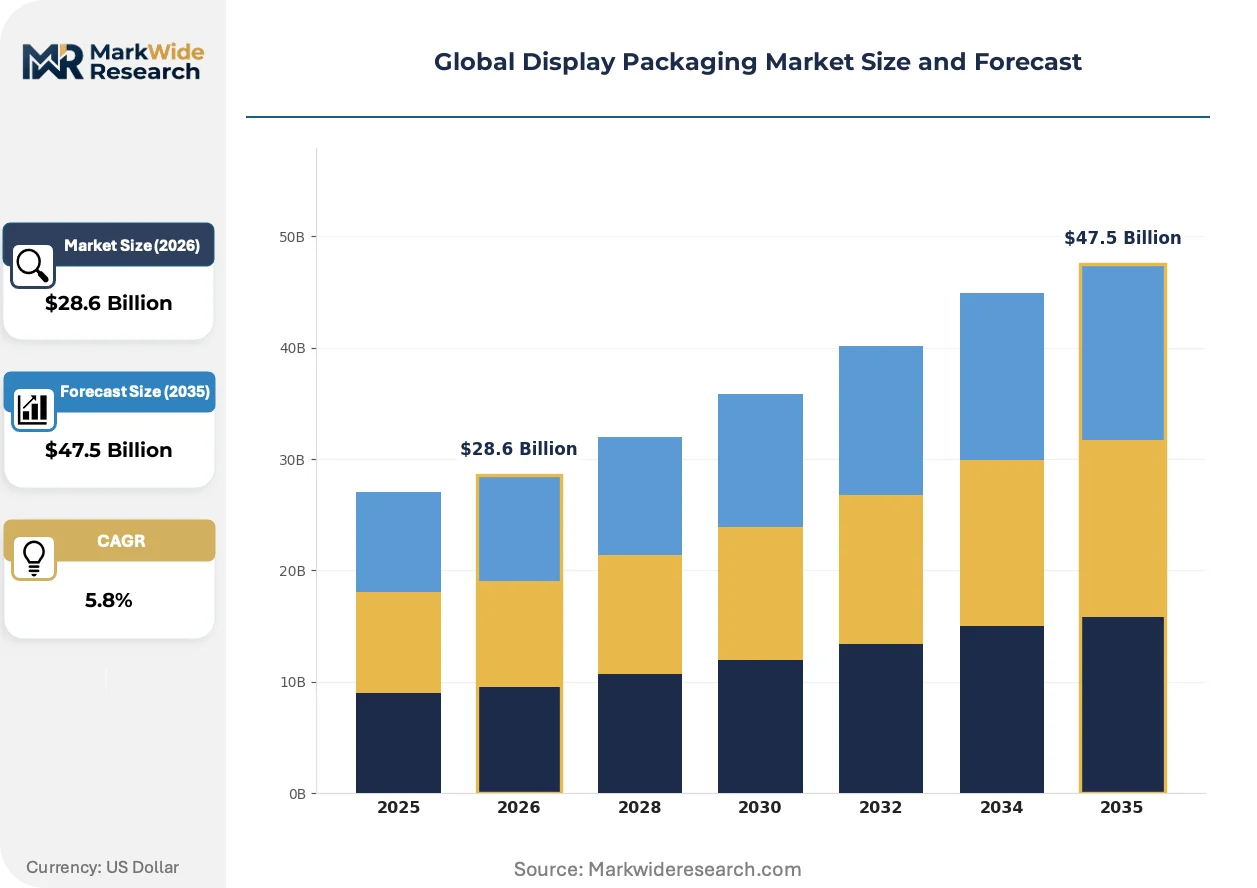
Market Dynamics
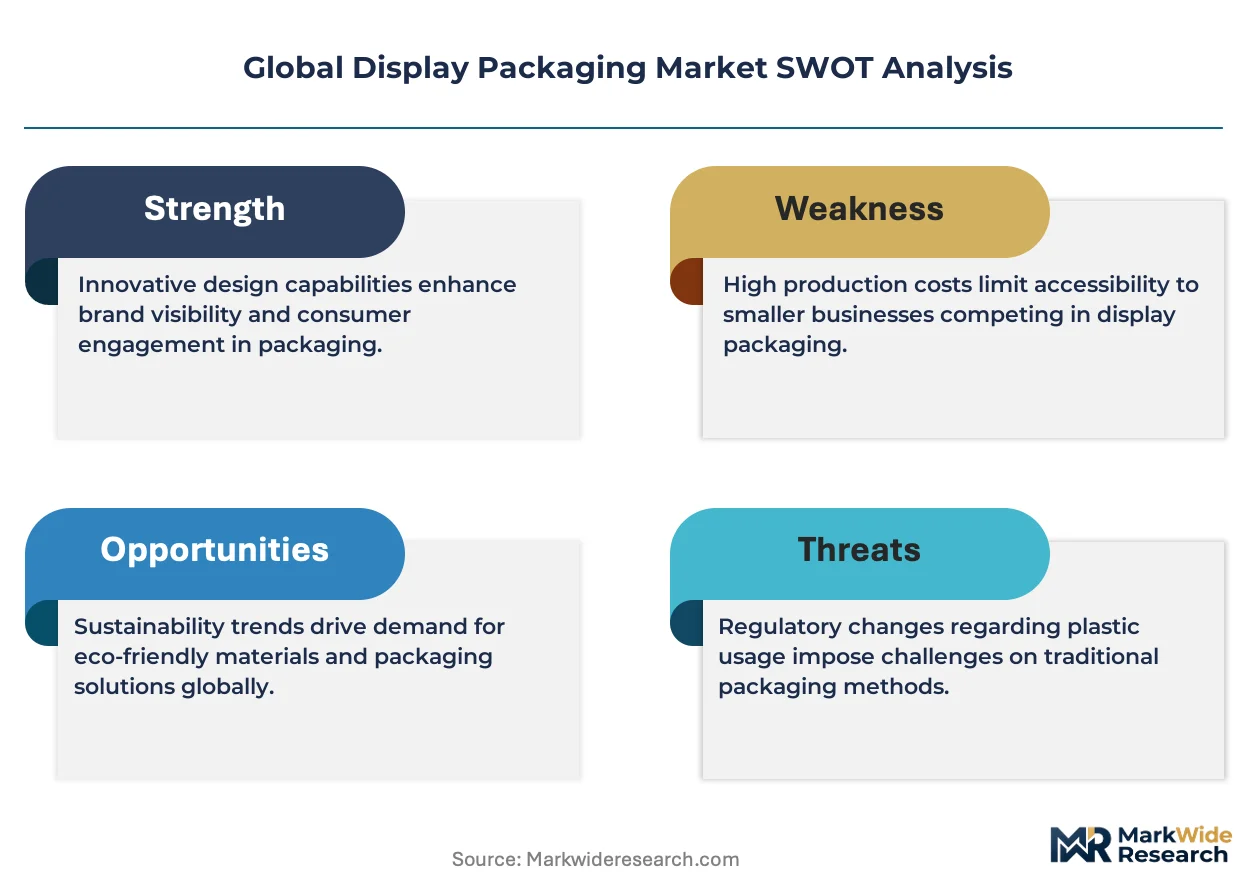
EU Green Deal packaging waste targets are forcing substrate transitions across the display packaging value chain, with converters in Germany's Rhine-Ruhr corridor accelerating paperboard folding carton capacity to serve cosmetics houses and domestic retail chains.
Growth Catalysts
- REACH chemical restrictions:European regulators are phasing out certain PVC formulations, creating pull-through demand for PET-G and paperboard alternatives in consumer goods packaging.
- Shrink sleeve technology:Full-body decoration on contoured beverage containers and personal care bottles is displacing applied labels, expanding addressable surface area for brand messaging.
- Rhine-Ruhr manufacturing corridor:Concentrated converter capacity in this German cluster enables just-in-time supply to both domestic retail chains and export-oriented cosmetics houses.
Market Restraints
- Pulp cost volatility:Kraft liner grade prices fluctuate with energy costs at Central European integrated mills, compressing margin visibility for converters.
- Pharmaceutical compliance timelines:FDA child-resistance specifications and thermoformed cavity precision requirements extend qualification periods for blister pack entrants.
- China SAMR import rules:GB standards for food-contact materials and packaging waste regulations create compliance friction for multinational brands manufacturing in Asia.
Strategic Opportunities
- Extended producer responsibility frameworks:Evolving EPR schemes in Europe reward regional specification hubs over centralized global design centers for compliance agility.
- Corrugated retail-ready formats:Pan-European box plant networks can capture shelf-ready display logistics as retailers consolidate inbound SKUs.
- Pre-press design services:Brand-agency anchoring through dedicated studios creates switching costs for shrink sleeve campaign contracts.
Industry Challenges
- Multi-material supplier panel management:Procurement teams must coordinate across paperboard, plastic film, and rigid substrate sources without single-source contract simplicity.
- 6- to 8-color offset line qualification:Mass cosmetics and OTC pharmaceutical applications require speeds exceeding 15,000 sheets per hour, demanding capital-intensive press upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Display Packaging Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Folding Cartons, Blister Packs, Shrink Sleeves, Rigid Boxes Material: Paperboard, Plastic, Glass, Metal End Use Industry: Consumer Electronics, Food & Beverages, Cosmetics, Pharmaceuticals Design Style: Minimalist, Eco-friendly, Luxury, Interactive |
| Companies Covered | Mondi, Ball Corporation, Amcor, CCL Industries, Constantia Flexibles, Sealed Air, Smurfit Kappa, Huhtamaki Oyj, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Display Packaging Market Emerging Trajectories
Digital pre-press workflows and automated die-cutting are compressing design-to-shelf cycles, while regulatory substrate mandates and retail consolidation reshape specification priorities across the value chain.
Smart packaging integration is unifying NFC-enabled authentication with conventional display structures. Luxury cosmetics houses in France and Switzerland are piloting connected folding cartons for supply chain traceability. This convergence is unifying physical protection with digital engagement layers, collapsing the traditional separation between packaging and marketing technology budgets.
The EU Green Deal's packaging waste reduction targets are accelerating mono-material design requirements. REACH restrictions on additives are forcing reformulation of legacy plastic films toward recyclable alternatives. Pharmaceutical and food-contact segments in Germany and the Netherlands are responding with dedicated compliance teams embedded in design centers.
Brand procurement teams are consolidating supplier relationships around converters offering integrated structural design and logistics optimization. Retail chains in the United Kingdom and France are replacing fragmented label-printing contracts with full-service display packaging partnerships. This concentration is most visible in the mass personal care sector, where shelf-ready formats now dictate upstream specification decisions.
Global Display Packaging Market Segmentation
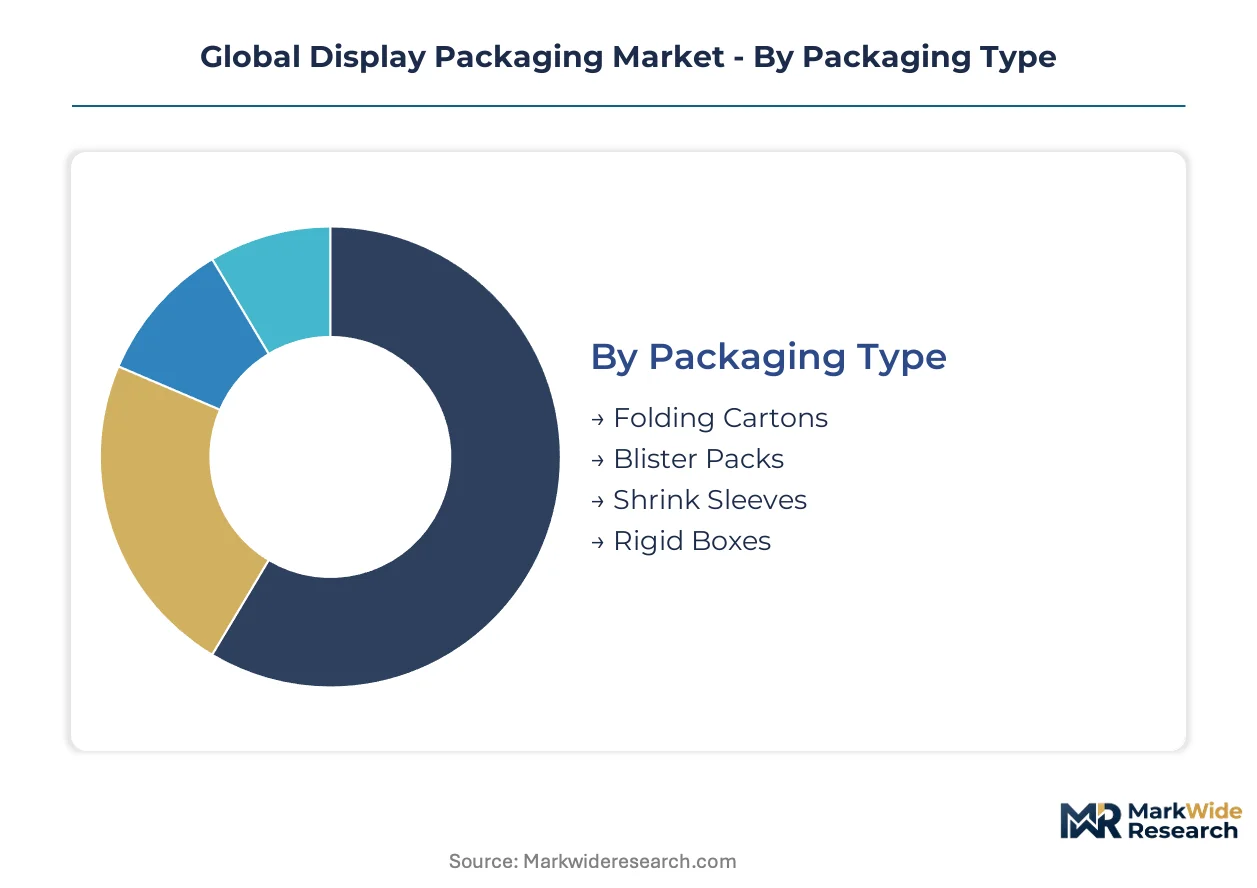
Display packaging buyers select formats based on shelf visibility requirements, regulatory compliance burdens, and substrate sustainability profiles. Segmentation reveals how procurement teams balance cost structures against brand positioning mandates across divergent end-use specifications.
Packaging Type:
Converters differentiate buyers by speed-to-shelf requirements and decoration complexity tolerance.
- Folding Cartons:These paperboard containers run on 6- to 8-color offset lines exceeding 15,000 sheets per hour. Mass cosmetics and over-the-counter pharmaceutical applications in Germany's Rhine-Ruhr corridor concentrate demand as brands meet EU Green Deal packaging waste targets.
- Shrink Sleeves:Full-body PET-G or PVC films conform to contoured beverage containers and personal care bottles. The format displaces applied labels across North American craft breweries and Asian functional drink manufacturers seeking 360-degree brand surface area.
- Blister Packs:Thermoformed cavities with lidding foil serve pharmaceutical compliance packaging where FDA child-resistance specifications command premium pricing.
- Rigid Boxes:Thick paperboard or composite structures protect luxury cosmetics and high-end electronics through distribution.
Folding cartons lead volumes today; shrink sleeves are gaining share fastest.
Material:
Raw material selection tracks regulatory pressure intensity and circular economy commitments by geography.
- Paperboard:Kraft liner and folding boxboard grades dominate EU personal care conversions. REACH chemical restrictions and extended producer responsibility frameworks in the Netherlands and France accelerate substitution away from plastic alternatives.
- Plastic:PET-G, PVC, and polystyrene films retain pharmaceutical blister and shrink sleeve applications. China's SAMR packaging waste rules and GB standards for food-contact materials govern import compliance for multinational brands manufacturing in Asia.
- Glass:Premium spirits and fragrance houses specify molded bottles with applied display cartons.
- Metal:Tinplate and aluminum support specialty confectionery and promotional gift sets.
Paperboard leads volumes today; plastic alternatives are expanding most quickly in regulated pharmaceutical segments.
End Use Industry:
Industry verticals separate buyers by validation timeline tolerance and shelf-life protection requirements.
- Cosmetics:Western European brands prioritize paperboard folding cartons for skincare and color cosmetics. Procurement teams in France and Switzerland pilot NFC-enabled connected packaging for supply chain traceability.
- Pharmaceuticals:Blister packs with thermoformed cavity precision serve FDA-regulated compliance packaging. US-bound production faces extended qualification periods for child-resistance specifications.
- Food & Beverages:Shrink sleeves and corrugated retail-ready formats dominate mass-market beverage applications in the United Kingdom and United States.
- Consumer Electronics:Rigid boxes and molded pulp inserts protect high-value devices through e-commerce distribution.
Cosmetics leads volumes today; pharmaceuticals are climbing the fastest on compliance-driven substrate upgrades.
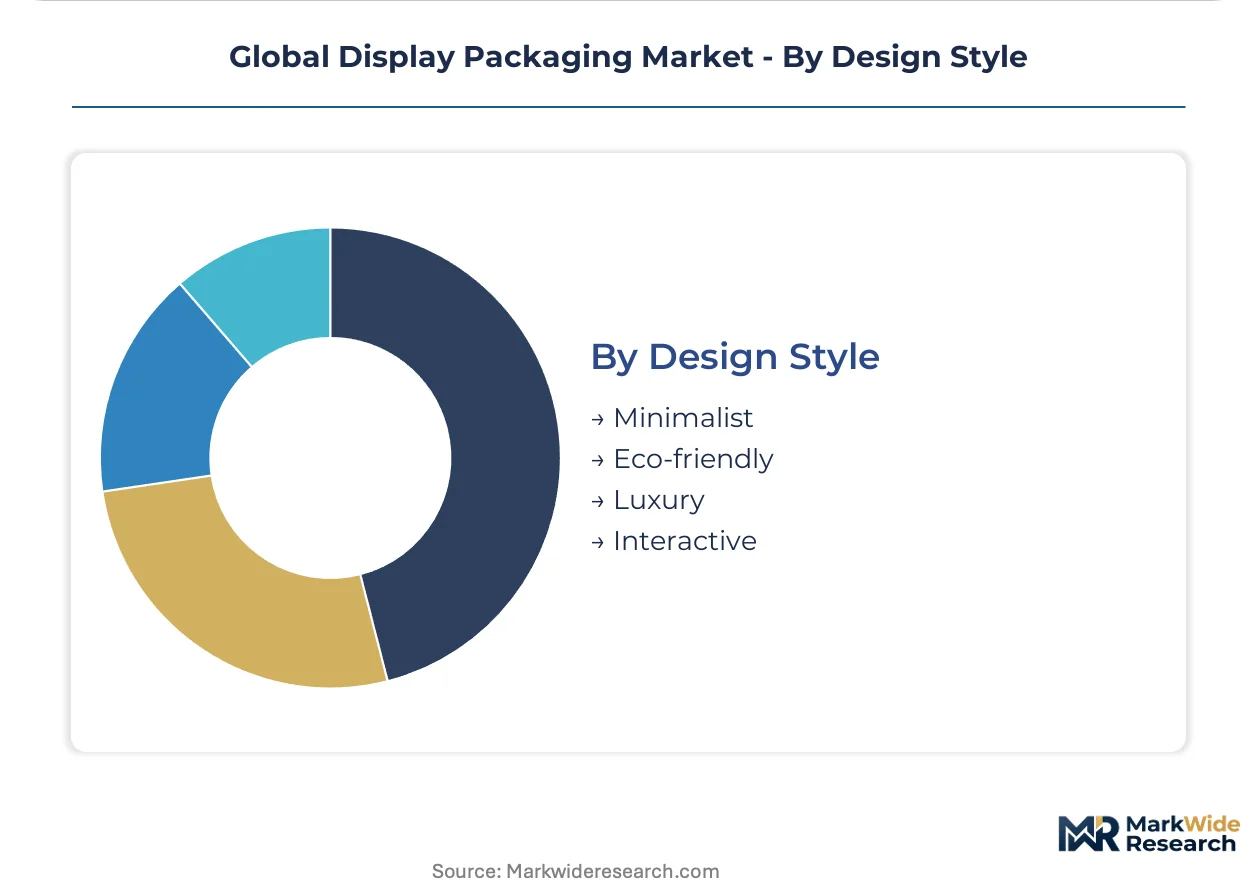
Design Style:
Aesthetic positioning separates buyers by marketing budget allocation and consumer engagement strategy.
- Eco-friendly:Mono-material specifications and recyclable substrates respond to EU Green Deal mandates. German and Dutch pharmaceutical and food-contact segments embed dedicated compliance teams in design centers.
- Luxury:Embossed rigid boxes, metallic hot-stamping, and soft-touch laminations serve fragrance and premium skincare houses in France and Switzerland.
- Minimalist:Reduced ink coverage and unbleached paperboard appeal to clean-label food brands and indie cosmetics.
- Interactive:QR codes, augmented reality triggers, and NFC tags merge physical packaging with digital engagement layers.
Luxury leads volumes today; eco-friendly specifications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting display packaging production toward jurisdictions with clearer extended producer responsibility frameworks and lower compliance-friction costs. Germany's Rhine-Ruhr corridor and China's Yangtze River Delta currently absorb the bulk of capacity migration as converters chase substrate-transition incentives.
Germany
Personal care brands headquartered in Hamburg and Düsseldorf are expanding paperboard folding carton contracts to meet EU Green Deal packaging waste targets. REACH chemical restrictions on PVC additives are accelerating PET-G and recyclable film conversions across the Rhine-Ruhr manufacturing belt. Converters in Düsseldorf and Cologne operate 6- to 8-color offset lines serving both domestic retail chains and export-oriented cosmetics houses.
United States
FDA child-resistance specifications for pharmaceutical blister packs command premium pricing from thermoformed cavity specialists. Extended qualification timelines for compliance packaging favor established converters with pre-validated tooling libraries. Chicago and New Jersey corridor facilities supply mass-market cosmetics and over-the-counter pharmaceutical applications to national retail chains.
China
SAMR packaging waste rules and GB standards for food-contact materials govern import compliance for multinational brands manufacturing in Guangdong and Zhejiang. Yangtze River Delta converters are expanding shrink sleeve capacity for functional beverage exporters targeting Southeast Asian markets. Shanghai design studios anchor brand-agency relationships for 360-degree decoration campaigns.
France
Luxury cosmetics houses in Paris and Lyon are piloting NFC-enabled connected folding cartons for supply chain traceability. ANSM pharmaceutical packaging regulations align with EU MDR requirements for compliance-ready blister formats. Île-de-France design centers embed dedicated teams for mono-material specification under EU Green Deal mandates.
India
BIS standards for food-contact paperboard and FSSAI labeling requirements are elevating specification complexity for domestic FMCG brands. Maharashtra and Gujarat converters are installing automated die-cutting lines to compress design-to-shelf cycles for mass personal care applications. Mumbai procurement teams are consolidating supplier relationships around integrated structural design capabilities.
Global Display Packaging Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue smart packaging integration and mono-material design services. The market structures around three distinct maturity tiers: integrated pulp-to-board operators, specialized pre-press design studios, and regional corrugated logistics networks. Two dominant competitive moves define current positioning: backward integration into captive pulp supply and geographic expansion through pan-European box plant acquisitions. Strategic partnerships between converters and brand design agencies are creating switching costs for campaign-contract renewals.
Within the integrated-materials tier, Mondi and Stora Enso exemplify operators with captive pulp-to-board visibility across Central European mill networks. Amcor occupies a position among design-forward specialists leveraging pre-press studios in multiple geographies to anchor brand-agency relationships. Smurfit Kappa represents the logistics-integrated archetype, with corrugated display capacity distributed through pan-European box plant networks that dominate retail-ready shelf formats.
| Leading Market Players |
|---|
| Mondi |
| Ball Corporation |
| Amcor |
| CCL Industries |
| Constantia Flexibles |
| Sealed Air |
| Smurfit Kappa |
| Huhtamaki Oyj |
| Stora Enso |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA-validated pharmaceutical blister packs and commodity folding cartons manifests in both margin structures and supplier qualification timelines. Premium thermoformed cavity precision commands extended tooling investment cycles, while mass-market paperboard runs on transactional spot purchasing anchored to kraft liner energy costs.
Pricing Analysis
Distributor margin layers absorb 12-18 point spreads between converter gate pricing and retail chain procurement desks. Three-tier pricing structure across premium, standard, and economy levels separates pharma-validated blister formats from mass cosmetics cartons and promotional gift sets. Pricing pressure stems from pulp cost volatility at Central European integrated mills, compressing visibility for kraft liner dependent converters. Mass personal care brands exhibit highest price sensitivity, while pharmaceutical compliance packaging buyers tolerate premium positioning for pre-validated child-resistance specifications.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification across paperboard, PET-G film, and rigid substrate categories for tier-one cosmetics houses. Geographic supply concentrates in Germany, China, and the United States, with Rhine-Ruhr converters serving EU Green Deal transitions and Yangtze River Delta facilities feeding Asian functional beverage exports. Raw material dependencies center on kraft liner grades, thermoformed PET-G films, and aluminum lidding foils. Single-source vulnerability persists in pharmaceutical tooling libraries where FDA-validated cavity designs lock buyers into incumbent relationships. Distribution runs through pan-European box plant networks and direct-to-retailer logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The display packaging market functions as a regulatory compounder where EU Green Deal packaging waste targets and REACH chemical restrictions continuously reshape substrate specifications and procurement priorities.
For Market Incumbents: Deploy captive pulp supply integration to defend margin position against energy-cost volatility at Central European mills. Backward integration into kraft liner production insulates cost visibility while mono-material design capabilities capture EPR framework incentives. Threat substitution from connected packaging specialists demands pre-press studio expansion to anchor brand-agency relationships for NFC-enabled folding carton campaigns. For New Entrants and Emerging Players: Begin with corrugated retail-ready formats in the United Kingdom and France where retailer SKU consolidation creates white-space for integrated structural design services. Target mass personal care applications where shelf-ready specifications now dictate upstream procurement decisions. Go-to-market angle centers on compressed design-to-shelf cycles through automated die-cutting and digital pre-press workflows. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional converters lack compliance team embedding for EU Green Deal substrate transitions. Long-term viability favors operators with pan-European box plant networks and captive pulp-to-board visibility across multiple geographies. Acquisition target archetype: mid-cap converters with validated pharmaceutical tooling libraries and underutilized 6- to 8-color offset capacity. Signal to watch: EPR framework implementation velocity in the Netherlands and France as inflection indicator for paperboard substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive kraft liner production at Central European mills insulates converters from energy-cost volatility. |
| Pre-Press Design Studio Expansion | Dedicated studios in multiple geographies anchor brand-agency relationships for shrink sleeve campaigns. |
| Mono-Material Design Capability Investment | Recyclable substrate expertise captures EU Green Deal EPR framework incentives in Germany and France. |
| Pan-European Box Plant Acquisition | Corrugated retail-ready logistics networks dominate shelf-format supply to consolidating retail chains. |
| Smart Packaging Integration Partnership | NFC-enabled authentication merges physical protection with digital engagement for luxury cosmetics traceability. |
Methodological Framework
Direct dialogue with converter operations managers, brand procurement leads at cosmetics houses, retail category buyers, and pharmaceutical packaging engineers grounded qualitative findings in operational reality. Secondary validation drew from EU Green Deal implementation documents, FDA pharmaceutical packaging guidance, SAMR GB standards filings, and trade association substrate consumption data. Bottom-up and top-down triangulation cross-checked converter capacity announcements against end-use demand modeling.
Bottom-up volume builds aggregated individual format forecasts across folding cartons, shrink sleeves, blister packs, and rigid boxes. Top-down macro constraints applied EU packaging waste reduction targets and REACH chemical phase-out schedules. Segmentation dimensions spanned packaging type, material substrate, end-use industry vertical, and design style tier. CAGRs derived from regression analysis of historical substrate consumption against regulatory milestone implementation curves, with pulp cost indices and pharmaceutical validation timelines as industry-specific forecast inputs.
Caveats apply where pulp energy cost spikes, EPR framework implementation delays, or pharmaceutical qualification timeline extensions could materially shift the outlook. Deviation in EU Green Deal enforcement velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market
Electronics Packaging
Power Module Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Consumer Electronics Packaging Market