
 Pain Relief Oil Market | 2026-2036
Pain Relief Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Pain Relief Oil Market Insights
Direct-to-consumer e-commerce channels is reshaping how pain relief oil brands reach households, bypassing traditional pharmacy and general trade networks. Emami Ltd. leverages its extensive rural distribution infrastructure to sustain shelf dominance across India's tier-2 and tier-3 cities. Himalaya Wellness Company anchors its competitive position through pharmacy-centric positioning in Southeast Asian and Middle Eastern markets. Patanjali Ayurved competes aggressively on price while navigating quality perception gaps in regulated export destinations.
Pain relief oil comprises topical formulations typically containing menthol, camphor, eucalyptus, or herbal extracts in carrier oil bases, designed for transdermal absorption to alleviate musculoskeletal discomfort through counterirritant or vasodilatory mechanisms. The product typically achieves therapeutic effect at application concentrations of 1-10% active ingredients, with manufacturing processes involving cold-press extraction or solvent-based concentration of botanical actives followed by homogenization with mineral or vegetable oil carriers. Menthol oil and eucalyptus oil variants occupy the largest volume share due to established consumer familiarity and lower per-unit pricing, while CBD oil commands premium positioning where regulatory frameworks permit its inclusion in topical products. Roll-on and spray delivery modes represent the fastest-expanding format category as consumers prioritize convenience and mess-free application in active lifestyles.
India's Ministry of AYUSH mandates Good Manufacturing Practice compliance and ingredient disclosure standards for Ayurvedic pain relief oils, while the US FDA regulates topical analgesics under Over-the-Counter Drug Monograph requirements that specify permissible active concentrations and labeling claims. The EU REACH framework governs chemical safety assessments for imported botanical extracts, creating compliance cost barriers for smaller exporters. Stakeholders must monitor evolving cannabinoid regulations across jurisdictions, as CBD inclusion status will determine which product portfolios gain market access in high-value Western European and North American channels.
Market Dynamics
Direct-to-consumer e-commerce channels is reshaping how pain relief oil brands reach households, bypassing traditional pharmacy and general trade networks. India's Ministry of AYUSH regulations on Ayurvedic product labeling and the US FDA's oversight of topical analgesic claims are tightening quality benchmarks across manufacturing bases.
Growth Catalysts
- Sports medicine expansion:Athletic recovery protocols at physiotherapy centers and sports clinics are creating institutional procurement pipelines for transdermal analgesic formulations.
- REACH compliance maturation:EU chemical safety assessments for botanical extracts are filtering out substandard suppliers and consolidating market access for quality-certified exporters.
- Diaspora channel activation:Domestic Ayurvedic brands are scaling export operations to capture concentrated South Asian consumer populations across North America and the Middle East.
Market Restraints
- Botanical input volatility:Cold-press extraction yields for menthol and eucalyptus oils fluctuate with monsoon patterns across Kerala and Karnataka growing belts.
- Regulatory fragmentation:CBD inclusion status varies across jurisdictions, blocking portfolio standardization for brands targeting Western European and North American channels.
- Substitution pressure:Oral NSAID formulations and transdermal patches compete for the same musculoskeletal discomfort indications with established reimbursement pathways.
Strategic Opportunities
- Rural distribution penetration:Tier-2 and tier-3 Indian cities remain underpenetrated by organized pharmacy chains, favoring brands with extensive general trade infrastructure.
- Delivery format innovation:Roll-on and spray application modes are capturing active lifestyle consumers seeking mess-free portability.
- PLI scheme alignment:India's production-linked incentive schemes for pharmaceutical manufacturing are reducing capital intensity for domestic API-to-finished-goods integration.
Industry Challenges
- Formulation talent scarcity:Homogenization of botanical actives with carrier oils requires specialized expertise in transdermal absorption optimization that outstrips current training pipeline output.
- Dual compliance burden:Manufacturers must simultaneously satisfy AYUSH Good Manufacturing Practice mandates and FDA Over-the-Counter Drug Monograph specifications for export-bound production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pain Relief Oil Market |
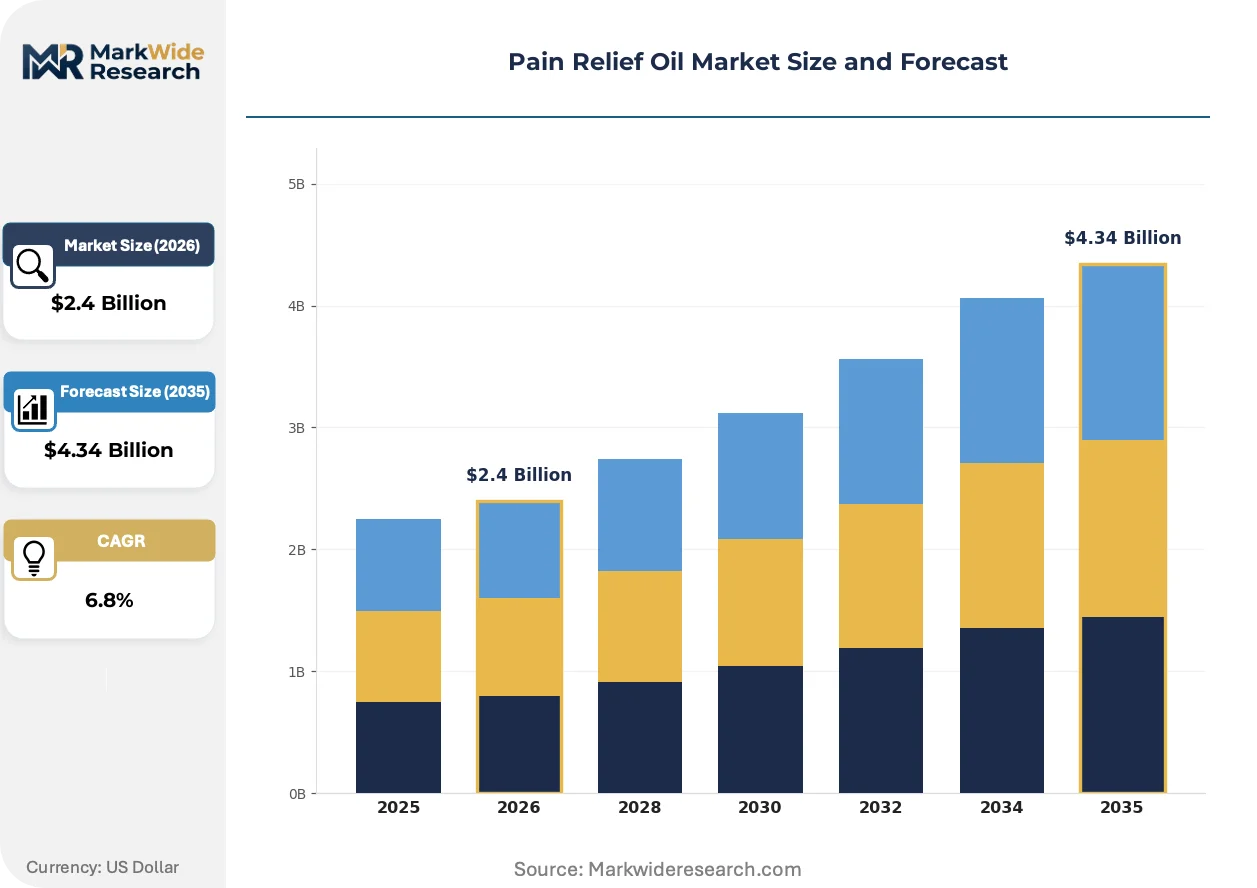
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CBD Oil, Menthol Oil, Eucalyptus Oil, Clove Oil Delivery Mode: Roll-On, Spray, Dropper, Cream Application: Muscle Pain, Joint Pain, Arthritis Relief, Headache Relief End User: Individuals, Athletes, Elderly, Health Enthusiasts |
| Companies Covered | Emami Ltd., Himalaya Wellness Company, Patanjali Ayurved, Dabur India Ltd., Amrutanjan Health Care Ltd., Haw Par Corporation, Sanofi, Reckitt Benckiser Group, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pain Relief Oil Market Trends and Innovations
Digital shelf analytics and influencer-driven discovery are compressing traditional brand-building timelines in topical analgesics. Formulation science and regulatory technology are converging to accelerate market access for novel botanical actives.
Nanoemulsion technology is virtualizing the bioavailability limitations of conventional oil-based carriers. Sports medicine clinics and athletic recovery centers are adopting these formulations for faster onset of counterirritant effects. The technology is virtualizing the competitive barrier between premium-positioned clinical brands and mass-market alternatives by democratizing efficacy claims.
EU REACH framework updates are tightening chemical safety documentation requirements for imported botanical extracts. Manufacturers must now submit comprehensive toxicological dossiers for each concentrated active ingredient. Ayurvedic exporters to Germany and France are responding by investing in in-house analytical laboratories capable of generating REACH-compliant safety data.
Subscription-based replenishment models are displacing episodic pharmacy purchases among chronic pain management users. Direct-to-consumer platforms are capturing recurring revenue from arthritis and fibromyalgia patient populations. This behavioral shift is most visible in US and UK metropolitan markets where same-day delivery logistics support just-in-time inventory patterns.
Pain Relief Oil Market Segmentation
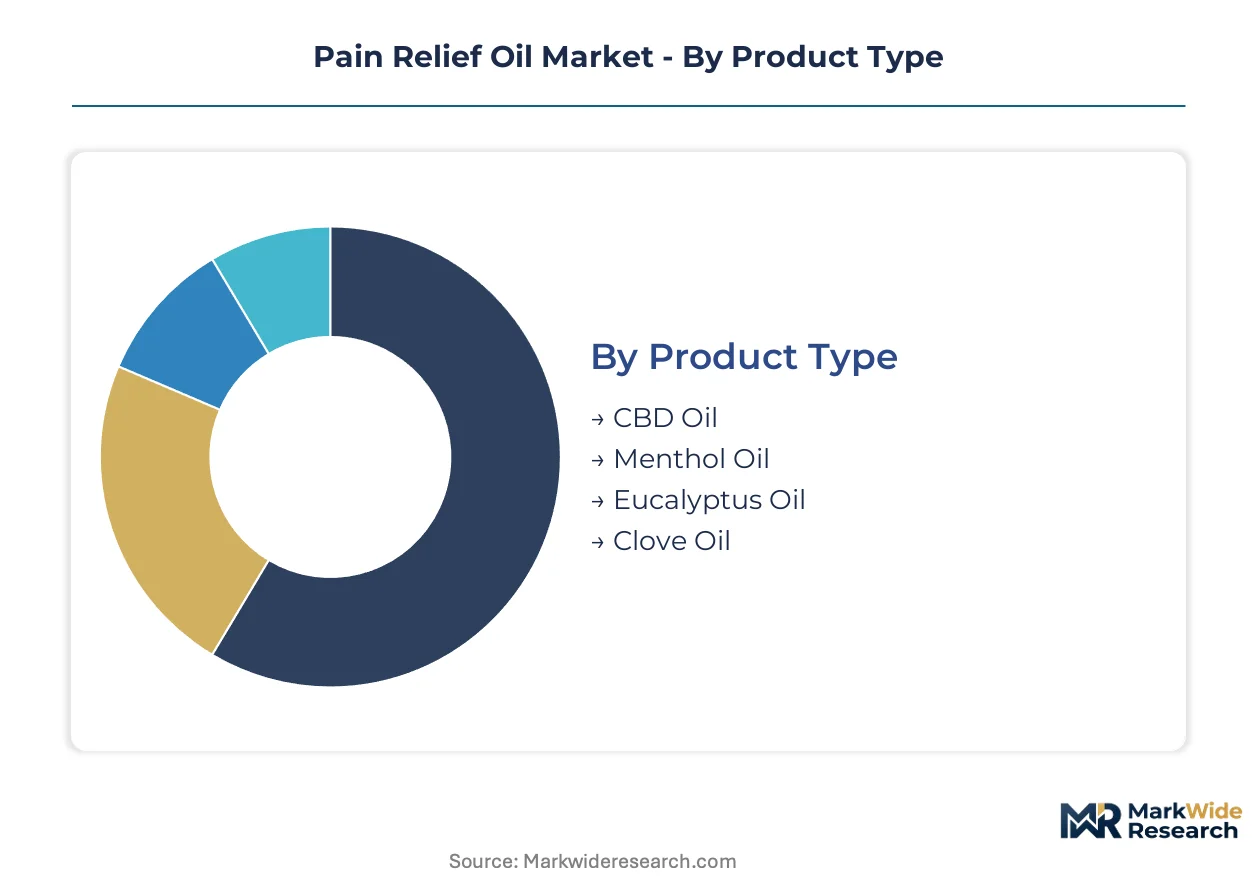
Pain relief oil segmentation reveals distinct velocity profiles across product chemistry, application mechanics, and user physiology. Cycle times vary dramatically: fast-moving delivery formats turn inventory weekly while specialized botanical extracts sit in channel for months awaiting regulatory clearance.
Product Type:
Inventory velocity diverges sharply between commodity botanicals and regulated novel actives, with cold-pressed extracts turning faster than cannabinoid formulations awaiting jurisdictional approval.
- Menthol Oil:Synthetic and natural menthol formulations deliver counterirritant effects through TRPM8 receptor activation at 1-5% concentrations. Demand concentrates in India's tier-2 and tier-3 pharmacy networks where Emami's rural distribution infrastructure maintains shelf dominance. The segment benefits from established US FDA monograph recognition and minimal regulatory friction across export markets.
- Eucalyptus Oil:Cineole-rich eucalyptus globulus extracts provide vasodilatory and mild analgesic effects through topical application. Kerala and Karnataka growing belts supply raw material to domestic Ayurvedic manufacturers scaling Middle Eastern export operations. Monsoon-dependent harvest yields create input cost volatility that compresses margins during poor rainfall cycles.
- CBD Oil:Cannabinoid-infused formulations command premium positioning where regulatory frameworks permit inclusion, though EU REACH compliance and US state-level variation block standardized portfolio deployment.
- Clove Oil:Eugenol-based clove bud extracts offer warming counterirritant properties with established traditional medicine acceptance across South Asian diaspora populations.
Menthol oil anchors the volume base while CBD oil gains share at the steepest rate where regulatory access permits commercialization.
Delivery Mode:
Format economics stratify across convenience premiums, with portable application systems commanding manufacturing complexity that smaller Ayurvedic brands struggle to replicate at scale.
- Roll-On:Ball-bearing applicator systems enable targeted, mess-free delivery to contoured body surfaces. Sports medicine clinics and physiotherapy centers in Germany and France are standardizing these formats for athletic recovery protocols. The design requires precision-molded plastic components and leak-proof sealing that elevates unit economics above traditional bottle formats.
- Spray:Aerosol and pump-dispersion systems distribute fine-mist coverage across large muscle groups. US metropolitan direct-to-consumer platforms report strongest subscription replenishment attachment for this format among fibromyalgia patient populations. Propellant selection and valve engineering determine shelf stability and transport classification complexity.
- Dropper:Glass pipette systems dominate traditional Ayurvedic positioning but face displacement from convenience-oriented alternatives in urban Indian markets.
- Cream:Emulsion-based carriers compete with oil formulations for pharmacy shelf space, particularly in Southeast Asian markets where Himalaya Wellness Company has anchored pharmacy-centric positioning.
Spray formats capture the steepest demand expansion trajectory among chronic pain management users prioritizing coverage efficiency.
Application:
Clinical indication targeting determines reimbursement pathway access and professional channel penetration, with sports-related applications bypassing traditional pharmacy gatekeepers.
- Muscle Pain:Acute and delayed-onset muscle soreness formulations target fitness enthusiasts and occupational physical stress. Athletes represent the fastest-expanding buyer segment as recovery protocols professionalize across India's emerging sports infrastructure. Counterirritant concentrations of 2-10% menthol or camphor deliver perceptible thermal feedback that reinforces usage compliance.
- Joint Pain:Osteoarthritis and inflammatory joint discomfort applications compete directly with oral NSAID and transdermal patch alternatives. Elderly populations in Japan and South Korea demonstrate strong repeat purchase behavior for warming herbal formulations. Penetration depth limitations of oil-based carriers constrain efficacy claims against prescription alternatives.
- Arthritis Relief:Chronic inflammatory joint management requires sustained application protocols that subscription commerce models increasingly capture.
- Headache Relief:Temporal and tension headache applications occupy niche positioning with limited clinical validation relative to established analgesic categories.
Muscle pain applications anchor the volume base while joint pain indications climb fastest through aging demographic tailwinds.
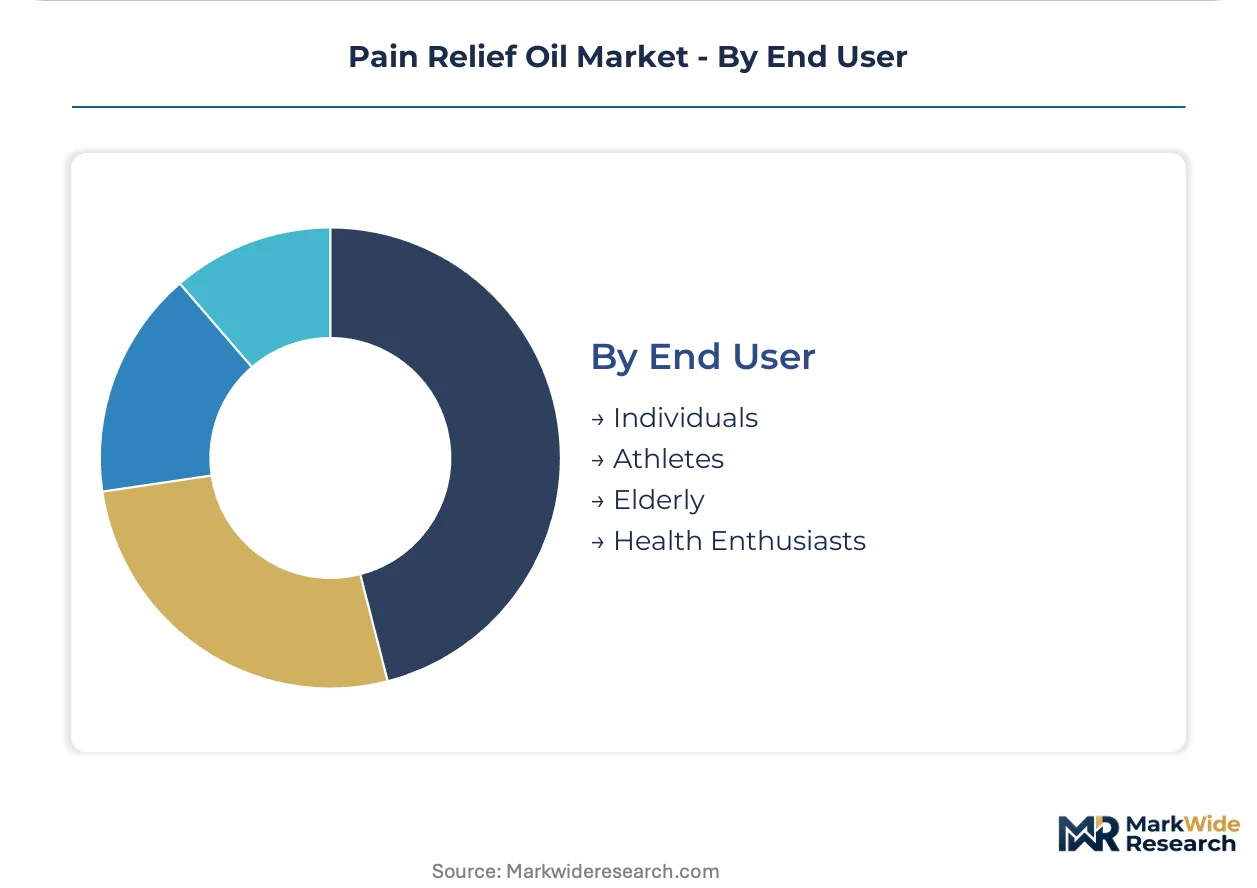
End User:
User physiology and activity intensity create distinct formulation requirements, with high-frequency athletes demanding rapid absorption and elderly users prioritizing gentler sensory profiles.
- Athletes:Competitive and recreational sports participants require rapid-onset, residue-free formulations compatible with training schedules. India's physiotherapy center expansion and sports medicine clinic proliferation are creating institutional procurement pipelines. Nanoemulsion technology adoption concentrates in this segment for bioavailability advantages during acute recovery windows.
- Elderly:Age-related musculoskeletal degeneration drives chronic application needs with sensitivity to skin barrier integrity. Germany and France's aging populations import Ayurvedic formulations through diaspora channel activation. Reduced epidermal permeability in geriatric skin challenges conventional absorption assumptions.
- Individuals:General household consumers purchase episodically through traditional trade, representing price-sensitive volume.
- Health Enthusiasts:Wellness-oriented prevention users demonstrate premium willingness for certified organic and clean-label positioning.
Individual households anchor the volume base while athletes expand most quickly through institutional channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port in Dubai anchors transshipment flows for Ayurvedic pain relief oils bound for European and African markets, while the Port of Hamburg serves as the primary EU entry point for Indian botanical extract shipments.
India
Domestic Ayurvedic brands scale export operations to capture diaspora consumers across North America and the Middle East. India's Ministry of AYUSH mandates Good Manufacturing Practice compliance and ingredient disclosure standards that filter substandard suppliers. Mumbai and Ahmedabad industrial clusters concentrate cold-press extraction facilities for menthol and eucalyptus oil production.
United States
Sports medicine clinics and physiotherapy centers create institutional procurement pipelines for transdermal analgesic formulations. The US FDA regulates topical analgesics under Over-the-Counter Drug Monograph requirements specifying permissible active concentrations. Miami and Houston distribution hubs handle bulk imports from Indian manufacturers for diaspora channel activation.
Germany
Aging populations import Ayurvedic formulations through activated diaspora channels concentrated in metropolitan areas. The EU REACH framework governs chemical safety assessments for imported botanical extracts, creating compliance cost barriers. Frankfurt and Düsseldorf serve as regulatory compliance centers where Ayurvedic exporters invest in analytical laboratories for toxicological dossier generation.
United Arab Emirates
South Asian expatriate populations drive concentrated demand for traditional pain relief formulations in retail pharmacy networks. The UAE's Ministry of Health and Prevention oversees product registration requirements for imported Ayurvedic goods. Dubai's Jebel Ali Free Zone hosts regional distribution headquarters for Indian manufacturers targeting GCC markets.
United Kingdom
Subscription-based replenishment models displace episodic pharmacy purchases among chronic pain management users in London and Birmingham metropolitan markets. The Medicines and Healthcare products Regulatory Agency applies EU-legacy standards for topical analgesic safety documentation. Slough and Southall industrial zones concentrate packaging and labeling operations for UK-specific regulatory compliance.
Pain Relief Oil Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction and active ingredient supply. The vendor base stratifies across three tiers: multinational consumer health conglomerates with pharmacy-centric positioning, domestic Ayurvedic houses with rural distribution depth, and emerging direct-to-consumer brands leveraging digital shelf analytics. Two dominant competitive moves define current dynamics: geographic expansion through diaspora channel activation and delivery format innovation toward roll-on and spray systems.
Within the domestic Ayurvedic tier, Emami Ltd. and Himalaya Wellness Company exemplify divergent strategic positioning. Emami leverages extensive rural distribution infrastructure to sustain shelf dominance across India's tier-2 and tier-3 cities. Himalaya anchors pharmacy-centric positioning in Southeast Asian and Middle Eastern markets where regulatory compliance capabilities determine market access. Patanjali Ayurved occupies a price-aggressive position while navigating quality perception gaps in regulated export destinations.
| Leading Market Players |
|---|
| Emami Ltd. |
| Himalaya Wellness Company |
| Patanjali Ayurved |
| Dabur India Ltd. |
| Amrutanjan Health Care Ltd. |
| Haw Par Corporation |
| Sanofi |
| Reckitt Benckiser Group |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Mumbai and Ahmedabad industrial clusters concentrate cold-press extraction capacity for menthol and eucalyptus oils, with monsoon-dependent harvest yields in Kerala and Karnataka creating input cost volatility that compresses margins during poor rainfall cycles and elevates pricing power for integrated manufacturers with captive botanical supply.
Pricing Analysis
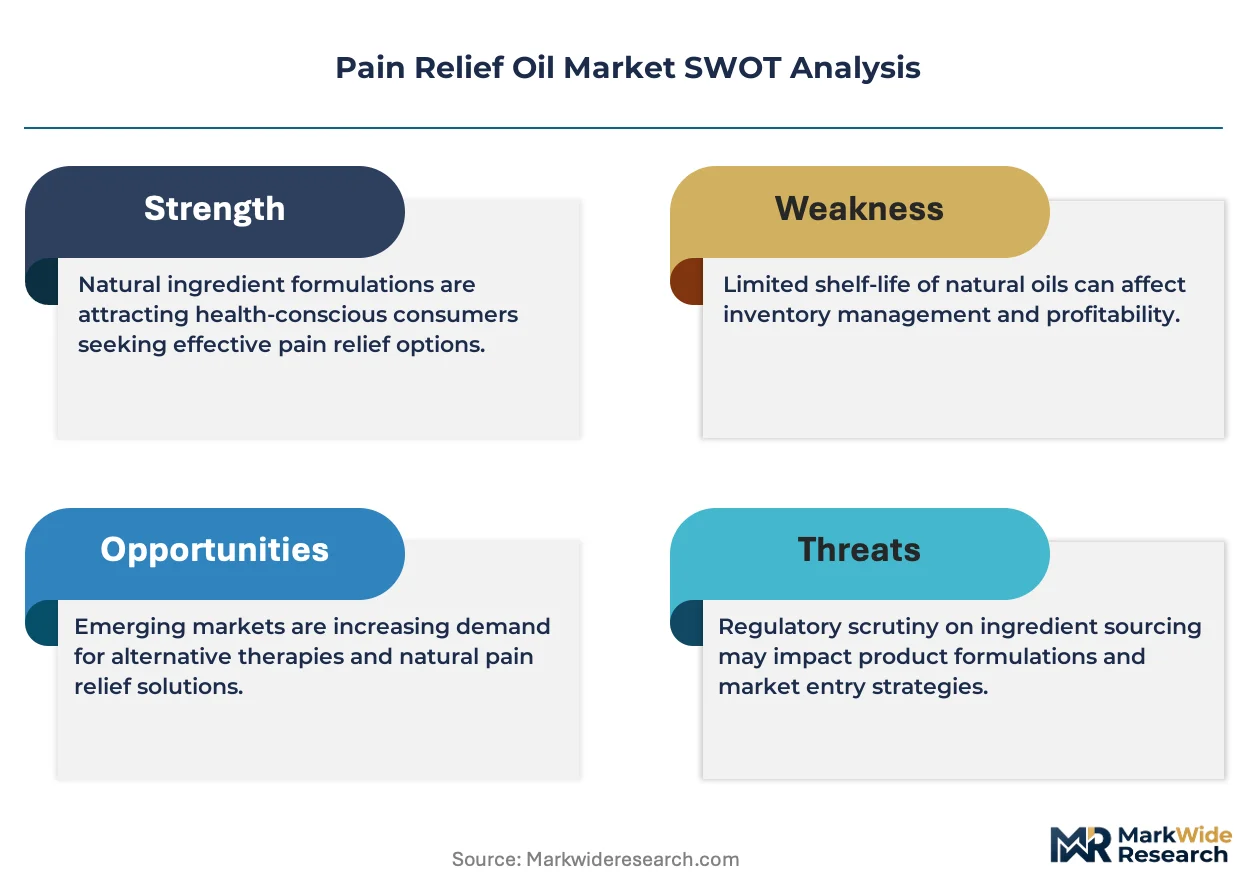
Three-tier pricing structure across premium, standard, and economy levels separates nanoemulsion clinical formulations from conventional Ayurvedic oils and commodity menthol variants. Price differentiation rests on certification grade (AYUSH GMP, FDA OTC monograph compliance) and volume scale, with institutional procurement at sports medicine clinics commanding favorable unit economics. Cost compression in economy tiers is intensifying because of substitution pressure from oral NSAIDs and transdermal patches. Individual households through traditional trade exhibit highest price sensitivity; athletes and institutional buyers demonstrate lowest sensitivity due to efficacy prioritization.
Supply Chain Analysis
Contract manufacturing concentration among domestic Ayurvedic houses with in-house extraction capabilities anchors capacity, with Emami Ltd. and Himalaya Wellness Company maintaining integrated operations from botanical sourcing to finished goods. Geographic supply concentration centers on India for cold-press extraction, China for synthetic menthol feedstock, and Germany for REACH-compliant analytical testing. Raw material dependencies include eucalyptus globulus from Karnataka, mentha arvensis from Uttar Pradesh, and specialized carrier oils from Southeast Asian palm and coconut plantations. Single-source vulnerability in monsoon-dependent harvests creates supply chain risk. Distribution runs through pharmacy-centric networks in urban markets and general trade infrastructure in tier-2 and tier-3 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against oral NSAID formulations and transdermal patches competing for musculoskeletal discomfort indications with established reimbursement pathways.
For Market Incumbents: Build regulatory certification moats through simultaneous AYUSH GMP and FDA OTC monograph compliance for export-bound production lines. Deepen backward integration into Kerala and Karnataka growing belts to secure menthol and eucalyptus supply against monsoon volatility. Capture institutional procurement pipelines at physiotherapy centers and sports medicine clinics before generic competitors replicate nanoemulsion formulations. For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities remain underpenetrated by organized pharmacy chains, offering white-space expansion for brands with general trade infrastructure. Roll-on and spray delivery formats capture active lifestyle consumers seeking mess-free portability, with manufacturing complexity that smaller Ayurvedic brands struggle to replicate. Target diaspora channel activation in North American and Middle Eastern markets through direct-to-consumer platforms bypassing traditional pharmacy gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms capturing chronic pain management users in US and UK metropolitan markets. Long-term viability across the projection horizon favors manufacturers with dual compliance capabilities and nanoemulsion technology portfolios. Acquisition target archetype: mid-cap Ayurvedic exporters with analytical laboratory investments for REACH-compliant toxicological dossier generation. Monitor CBD regulatory harmonization across Western European and North American jurisdictions as inflection indicator for premium portfolio expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Nanoemulsion Technology Adoption | Sports medicine clinics in Germany and France standardize fast-onset formulations for athletic recovery protocols. |
| REACH Compliance Investment | Ayurvedic exporters to EU markets invest in Frankfurt and Düsseldorf analytical laboratories for toxicological dossier generation. |
| Diaspora Channel Activation | Indian manufacturers establish Miami and Houston distribution hubs for North American South Asian consumer capture. |
| Subscription Commerce Launch | Direct-to-consumer platforms in London and Birmingham metropolitan markets displace episodic pharmacy purchases among chronic users. |
| Rural Distribution Expansion | Emami Ltd. leverages extensive tier-2 and tier-3 infrastructure to sustain shelf dominance against organized pharmacy chains. |
Research Methodology
A spread of perspectives from AYUSH compliance officers, FDA regulatory consultants, sports medicine clinicians, pharmacy procurement managers, and Ayurvedic formulation scientists converged on the working assumptions. Primary interviews combined with secondary validation from customs records, AYUSH manufacturing license databases, FDA OTC drug monograph filings, and EU REACH registration dossiers. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product chemistry (menthol, eucalyptus, CBD, clove), delivery mode (roll-on, spray, dropper, cream), application indication (muscle pain, joint pain, arthritis relief), and end-user physiology (athletes, elderly, general households). CAGRs derived from regression analysis against demographic aging curves, sports infrastructure investment, and regulatory access expansion. Industry-specific forecast inputs included physiotherapy center proliferation rates and diaspora population concentration indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by transdermal patch manufacturers or oral NSAID marketers would shift outcomes beyond modeled ranges. Regulatory fragmentation on CBD inclusion status, monsoon harvest volatility, and REACH compliance cost escalation represent specific risk factors. Quarterly review of AYUSH enforcement actions, FDA monograph updates, and EU REACH substance restriction proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Medicated Pain Relieving Plasters Market
Pain Management
Pain Management Devices Market
Pain Management
Global Chiropractic Care Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Arthralgia Management Market
Pain Management
Chronic Pain Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Dyspareunia Market
Pain Management
Pain Relievers for Teeth Market
Pain Management
Postoperative Pain Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Opioid Induced Side Effects Treatment Market