
 Global Acrolein Market | 2026-2036
Global Acrolein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrolein Market Foresight
Buyer consolidation among water treatment facilities is repositioning procurement leverage toward municipal and industrial end users with multi-year supply contracts. BASF SE anchors European supply through integrated propylene oxidation infrastructure. Evonik Industries specializes in stabilized acrolein formulations for safety-critical logistics. Hubei Jinghong Chemical dominates captive consumption and regional merchant sales across Asia-Pacific.
Acrolein is an alpha,beta-unsaturated aldehyde (C3H4O) produced primarily via vapor-phase oxidation of propylene over bismuth-molybdate catalysts at 300-400°C, serving as a chemical intermediate for acrylic acid, methionine, and biocidal formulations. Liquid acrolein occupies the largest volume share due to its direct use in water treatment and agrochemical synthesis, while polymer grade acrolein commands premium positioning for high-purity acrylic acid chains. Glycerol dehydration is gaining traction as a bio-based alternative pathway, though oxidation of propylene sustains dominant capacity economics.
EPA registration under FIFRA governs biocidal applications in US water treatment, while REACH compliance in Europe mandates extensive toxicity documentation for acrolein handling and downstream use. China's MEE enforces emission controls on propylene oxidation facilities that constrain regional capacity additions. Stakeholders must monitor regulatory divergence between jurisdictions to align product specifications and avoid market access friction.
Market Dynamics
Water treatment facilities are consolidating procurement into multi-year supply contracts, shifting bargaining power toward municipal and industrial end users while tightening purity specifications under evolving biocidal registration frameworks.
Growth Catalysts
- REACH toxicity documentation mandates:European ECHA compliance requirements are accelerating formaldehyde replacement in water treatment biocides, redirecting formulation demand toward acrolein-based alternatives.
- China acrylic acid capacity expansion:Propylene oxidation infrastructure buildouts in Jiangsu and Shandong provinces are drawing disproportionate acrolein volume for captive consumption and regional merchant supply.
- Stabilized formulation logistics:Safety-critical handling improvements are extending acrolein's viable distribution radius to inland water treatment facilities previously served by less hazardous biocides.
Market Restraints
- Propylene feedstock volatility:Crude oil price fluctuations transmit directly to acrolein production economics, compressing margins for non-integrated producers lacking upstream propylene supply.
- EPA FIFRA registration friction:Biocidal product approval timelines in the United States extend 24-36 months, creating regulatory lag that deters new market entrants and limits formulation innovation.
- Glycerol dehydration pathway economics:Bio-based production from renewable feedstocks remains cost-disadvantaged against propylene oxidation, constraining sustainability-driven substitution despite technical viability.
Strategic Opportunities
- Middle East water infrastructure:Saudi Arabia and UAE desalination capacity buildouts are creating new biocide demand nodes with limited established supplier relationships.
- EU Green Deal chemical sustainability incentives:Carbon border adjustments and renewable content mandates are improving the relative economics of glycerol-derived acrolein for European market access.
- Digital inventory management platforms:Real-time consumption monitoring systems are enabling vendor-managed inventory contracts that lock in long-term offtake agreements with price stability clauses.
Industry Challenges
- Specialized chemical handling certification:Acrolein's toxicity profile requires trained personnel for transport and storage, creating workforce scarcity that constrains logistics network expansion.
- Legacy water treatment facility infrastructure:Municipal systems with dated dosing equipment face capital-intensive retrofit requirements to safely handle stabilized acrolein formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrolein Market |
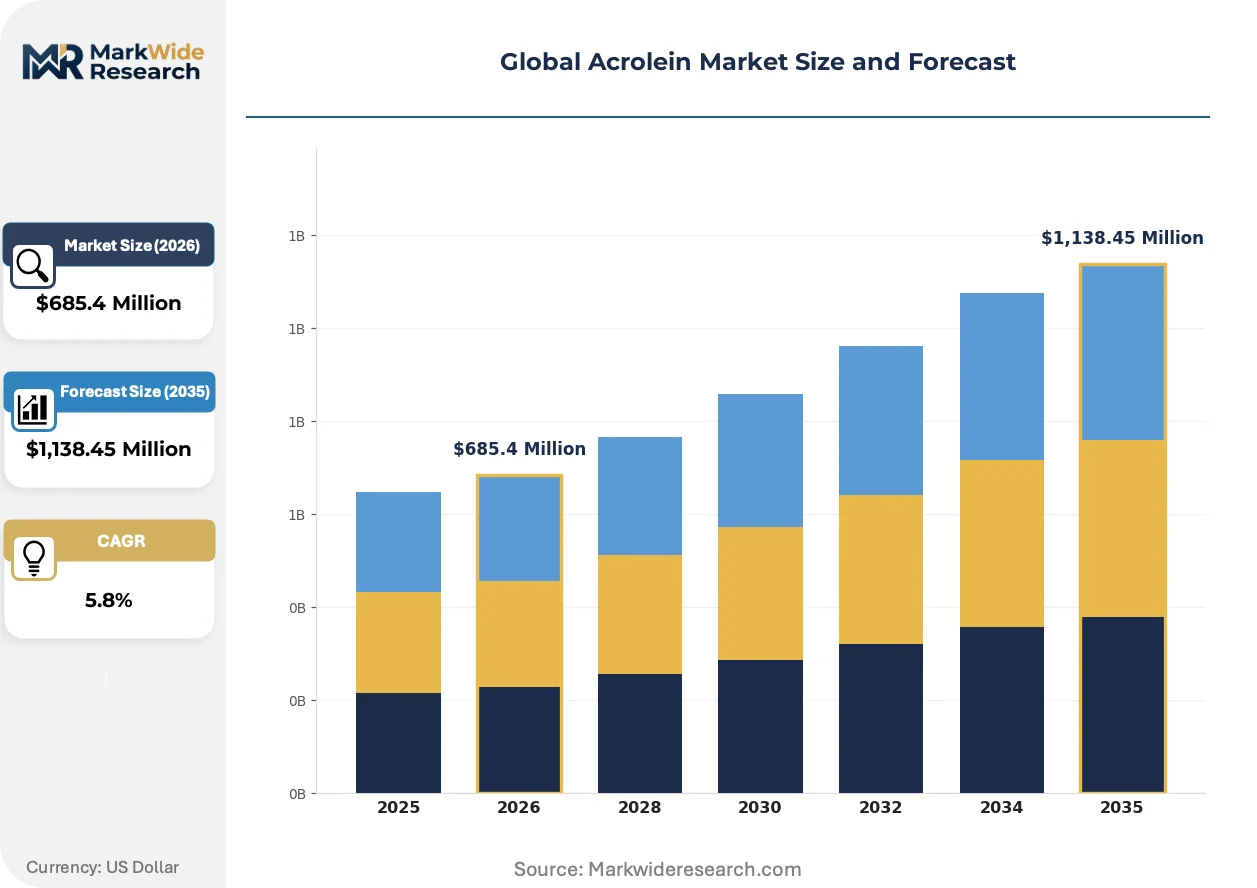
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Acrolein, Stabilized Acrolein, Polymer Grade Acrolein, Purified Acrolein Application: Adhesives, Plasticizers, Pesticides, Acrylic Acid Production, Water Treatment Chemicals End User Industry: Agrochemical Manufacturers, Paints & Coatings Suppliers, Cosmetic Ingredient Producers, Chemical Intermediates, Water Treatment Facilities Production Technology: Oxidation of Propylene, Glycerol Dehydration, Catalytic Oxidation, Vapor Phase Oxidation |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries, Arkema, Shell Chemicals, Mitsui Chemicals, Daicel Corp., Adisseo, Hubei Jinghong Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrolein Market Shifts & Advancements
Production technology and regulatory compliance systems are converging to reshape competitive positioning, with bio-based pathways and digital supply chain tools emerging as distinctive capability differentiators.
Glycerol dehydration catalyst systems are integrating continuous flow reactor designs that improve selectivity and reduce energy intensity compared to batch processing. Specialty chemical producers in Europe and Asia-Pacific are piloting these installations to qualify for renewable content certifications. This technology convergence is integrating carbon accounting directly into production economics, compressing the cost gap with fossil-derived acrolein.
EPA FIFRA registration renewal cycles are tightening data requirements for chronic toxicity and environmental fate studies. Biocidal product manufacturers must submit expanded mammalian toxicology packages that extend approval timelines and increase compliance costs. Water treatment service providers in the United States are responding by consolidating supplier relationships to amortize regulatory overhead across larger contract volumes.
Buyer concentration among municipal water authorities is compressing supplier switching cycles and demanding performance guarantees rather than commodity supply terms. Industrial water treatment operators are unbundling chemical procurement from equipment service contracts, creating direct purchasing relationships with acrolein producers. This pattern is most visible in Germany and the Netherlands, where utility privatization has fragmented procurement authority toward facility-level decision making.
Global Acrolein Market Segmentation
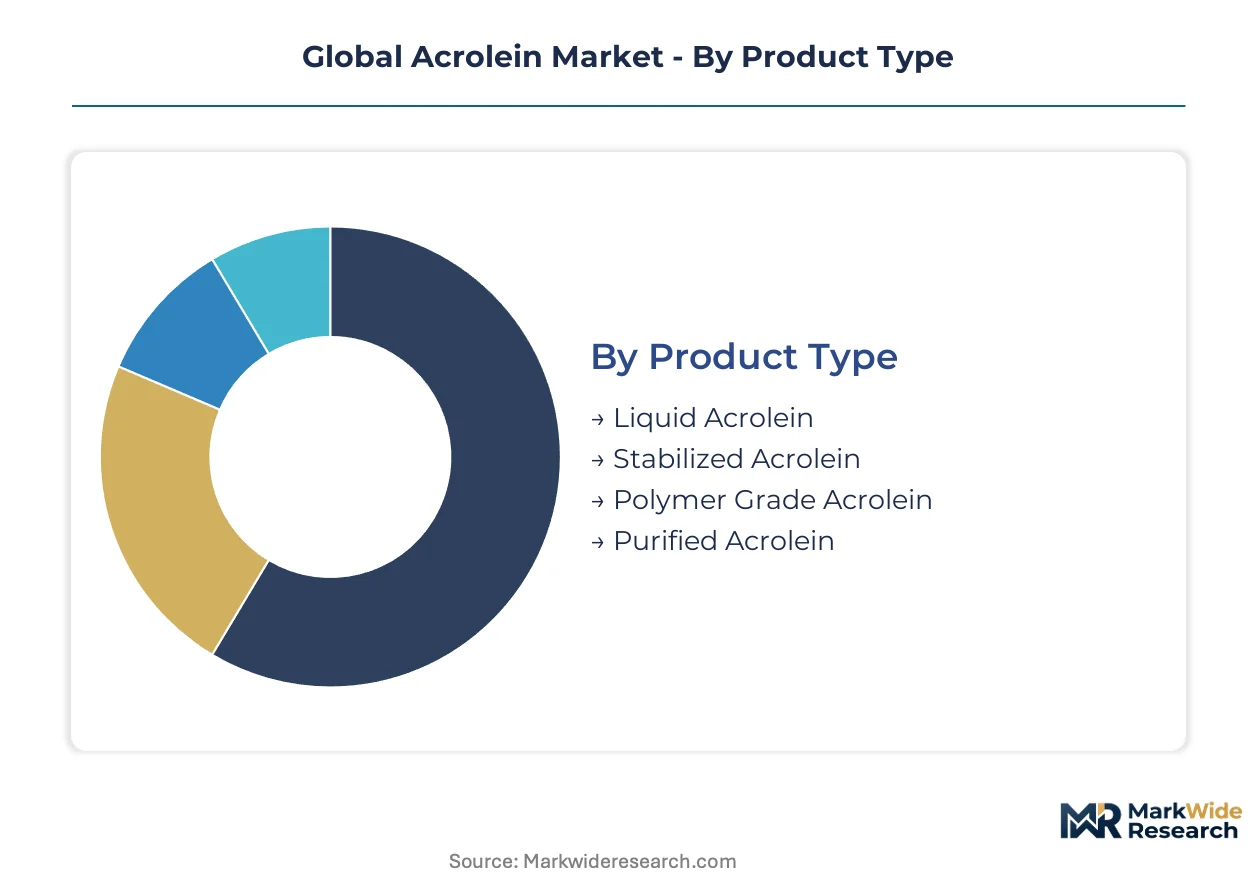
Acrolein segmentation reveals how capital intensity, regulatory compliance burdens, and end-use performance requirements fragment supply strategies. Producers must align product specifications with customer handling capabilities and downstream purity demands.
Product Type:
Capital intensity varies sharply across grades, with stabilization infrastructure and purification trains demanding differential upfront investment.
- Liquid Acrolein:Standard-grade material containing hydroquinone or phenothiazine inhibitors to prevent polymerization during storage. Water treatment facilities in Germany and the Netherlands concentrate procurement here, drawn by direct dosing compatibility and established EPA FIFRA registration pathways.
- Stabilized Acrolein:Formulations with enhanced inhibitor packages enabling extended shelf life and safer inland distribution. Evonik Industries specializes in this segment, extending viable supply radius to municipal utilities previously constrained by toxicity handling limitations.
- Polymer Grade Acrolein:Ultra-high purity specifications for acrylic acid polymerization chains.
- Purified Acrolein:Refined grades for specialty chemical synthesis and pharmaceutical intermediates.
Liquid Acrolein absorbs the bulk of installed capacity; Stabilized Acrolein is expanding most quickly.
Application:
Margin profiles diverge based on regulatory scrutiny intensity and customer consolidation patterns.
- Acrylic Acid Production:Captive consumption by integrated petrochemical complexes in Jiangsu and Shandong provinces. This application draws disproportionate volume as Chinese propylene oxidation capacity scales, though merchant sales remain limited by pipeline economics.
- Water Treatment Chemicals:Biocidal formulations for municipal and industrial cooling systems. REACH formaldehyde displacement mandates are redirecting formulation demand toward acrolein-based alternatives across French and Dutch utilities.
- Pesticides:Intermediate for methionine and herbicide synthesis.
- Plasticizers:Niche applications in polymer modification.
- Adhesives:Crosslinking agent for specialty adhesive systems.
Acrylic Acid Production commands the largest volume share; Water Treatment Chemicals is climbing the fastest.
End User Industry:
Customer type determines contract structure, with consolidated buyers extracting performance guarantees and vendor-managed inventory terms.
- Water Treatment Facilities:Municipal and industrial operators unbundling chemical procurement from equipment service contracts. Procurement consolidation in Germany and the Netherlands is compressing supplier switching cycles and demanding multi-year offtake agreements.
- Agrochemical Manufacturers:Methionine and herbicide producers with captive acrolein requirements. Chinese agrochemical output expansion is drawing regional merchant supply, though integrated producers dominate internal consumption.
- Chemical Intermediates:Specialty chemical producers requiring consistent purity specifications.
- Paints & Coatings Suppliers:Niche applications in polymer crosslinking and modification.
- Cosmetic Ingredient Producers:Limited demand for high-purity grades in specialty formulations.
Water Treatment Facilities represent the most consolidated demand base; Agrochemical Manufacturers are gaining share fastest.
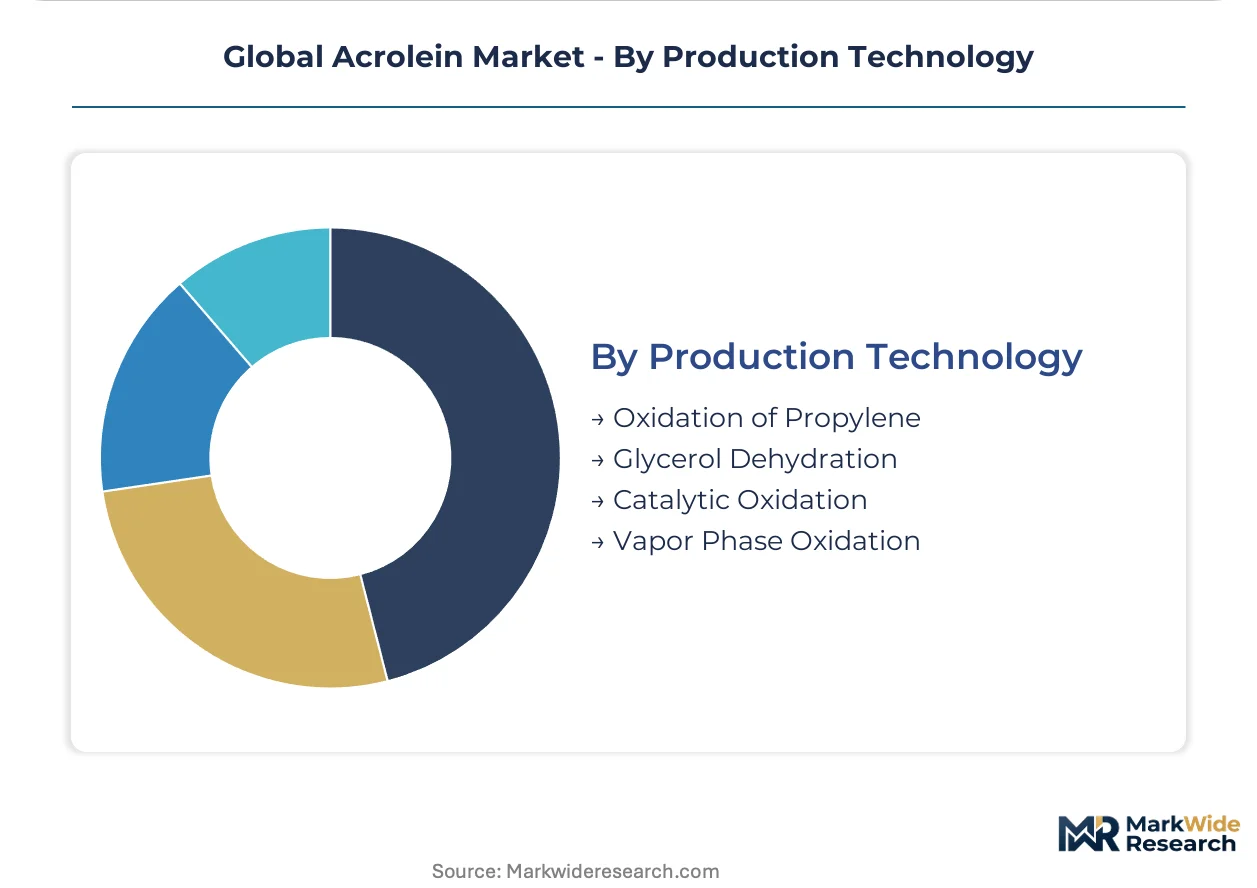
Production Technology:
Technology choice locks in feedstock exposure and carbon intensity positioning for decades.
- Oxidation of Propylene:Vapor-phase process over bismuth-molybdate catalysts at 300-400°C. BASF SE anchors European supply through this pathway, with China's MEE emission controls now constraining regional capacity additions.
- Glycerol Dehydration:Bio-based alternative using renewable feedstocks. EU Green Deal carbon border adjustments are improving relative economics for European producers piloting continuous flow reactor designs.
- Catalytic Oxidation:Alternative catalyst systems for propylene conversion.
- Vapor Phase Oxidation:Process variant with specific reactor configurations.
Oxidation of Propylene dominates installed capacity; Glycerol Dehydration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates disproportionate acrolein demand through its acrylic acid capacity buildouts, while European water treatment utilities redirect procurement toward acrolein-based biocides under REACH formaldehyde displacement mandates. The Middle East desalination expansion and North American EPA registration frameworks complete the geographic demand mosaic.
China
Jiangsu and Shandong provinces host propylene oxidation complexes that consume captive acrolein for acrylic acid polymerization chains. MEE emission controls on oxidation facilities constrain greenfield capacity additions, tightening regional supply availability. The Yangtze River Delta cluster draws merchant acrolein volume to serve agrochemical intermediates production.
Germany
Rhine-Ruhr industrial utilities unbundle chemical procurement from equipment service contracts, consolidating buyer leverage toward multi-year supply agreements. ECHA REACH toxicity documentation mandates accelerate formaldehyde replacement in municipal water treatment biocides. BASF SE anchors European supply through integrated Ludwigshafen propylene oxidation infrastructure.
United States
Gulf Coast petrochemical corridors maintain propylene oxidation capacity serving acrylic acid and methionine synthesis chains. EPA FIFRA registration timelines extending 24-36 months deter new biocidal market entrants and compress supplier switching. Industrial cooling system operators in Texas and Louisiana concentrate procurement through vendor-managed inventory contracts.
Saudi Arabia
Desalination capacity buildouts across the Eastern Province and Red Sea coast create biocide demand nodes with limited established supplier relationships. The country's national water regulator enforces dosing protocol standards that favor stabilized acrolein formulations for safety-critical handling. NEOM infrastructure development draws chemical logistics investment toward northwestern supply corridors.
Netherlands
Rotterdam-Antwerp petrochemical hubs distribute acrolein derivatives across northwest European acrylic acid value chains. Utility privatization fragments procurement authority toward facility-level decision making in water treatment operations. REACH compliance documentation requirements concentrate supplier relationships among biocidal product manufacturers with established ECHA registration portfolios.
Global Acrolein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based pathway differentiation through glycerol dehydration technologies. The market structures around three archetypes: integrated petrochemical majors with captive propylene supply, specialty chemical formulators with stabilized product expertise, and regional merchant suppliers serving agrochemical clusters. Competitive moves concentrate on backward integration into propylene supply and technology licensing for continuous flow reactor designs.
Within the integrated petrochemical tier, BASF SE and Dow Inc. exemplify scale-driven positioning through oxidation infrastructure ownership. Evonik Industries occupies the specialty formulation segment with safety-critical logistics capabilities. Hubei Jinghong Chemical represents the Asia-Pacific regional merchant archetype, anchoring supply relationships across Chinese agrochemical and water treatment demand clusters.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries |
| Arkema |
| Shell Chemicals |
| Mitsui Chemicals |
| Daicel Corp. |
| Adisseo |
| Hubei Jinghong Chemical |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon border adjustments gate qualified supply for European producers while stratifying pricing tiers between fossil-derived and bio-based acrolein grades. REACH-compliant documentation investments and renewable content certifications determine which producers capture premium positioning versus commodity contract rates.
Pricing Analysis
Volume-margin splits concentrate earnings in polymer-grade and stabilized formulations while liquid standard-grade acrolein trades on thin spreads. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered biocidal suppliers from merchant traders and captive integrated producers. Price differentiation hinges on purity certification and inhibitor package sophistication, with water treatment facilities in Germany and the Netherlands extracting volume discounts through multi-year offtake agreements. Cost compression in standard-grade segments is intensifying because propylene feedstock volatility transmits directly to non-integrated merchant producers.
Supply Chain Analysis
Return flows of spent catalyst materials and stabilizer packaging create reverse-logistics complexity for acrolein distributors serving inland municipal utilities. Production gravity centers on China, Germany, and the United States, with Jiangsu and Shandong provinces hosting disproportionate oxidation capacity. Feedstock exposure to propylene and bismuth-molybdate catalyst systems rests on crude oil and specialty metal supply chains. Single-source vulnerability concentrates in Chinese MEE-regulated emission controls that constrain greenfield additions. Distribution runs through pipeline-connected petrochemical corridors and specialized tanker networks for stabilized formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into propylene supply and downstream acrylic acid polymerization chains defines the vertical-integration race, with producers securing captive feedstock access capturing margin stability unavailable to merchant traders.
For Market Incumbents: Anchor European supply positioning through Ludwigshafen-scale oxidation infrastructure ownership while accelerating glycerol dehydration pilot investments to qualify for EU Green Deal renewable content mandates. Glycerol pathway cost compression threatens fossil-derived margin structures. Capacity additions in Middle Eastern desalination corridors extend geographic diversification beyond REACH-constrained European demand. For New Entrants and Emerging Players: Enter via Saudi Arabian and UAE desalination biocide supply nodes where established supplier relationships remain thin and national water regulators favor stabilized formulation safety protocols. White-space concentration appears in vendor-managed inventory contracts for industrial cooling systems in Texas and Louisiana. Digital consumption monitoring platforms offer differentiated go-to-market positioning against incumbent commodity traders. For Investors and Strategic Acquirers: Continuous flow reactor technology licensing announcements from European specialty chemical producers is the leading indicator that glycerol-derived acrolein economics are approaching fossil parity. Long-term viability across the analysis window favors producers with dual-pathway technology optionality and established ECHA registration portfolios. Acquisition targets should demonstrate REACH-compliant biocidal product pipelines and captive propylene supply integration. Monitor EU carbon border adjustment implementation timelines for early signals of bio-based premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | BASF SE's Ludwigshafen complex demonstrates margin insulation against feedstock volatility through captive oxidation infrastructure. |
| Continuous Flow Reactor Technology Licensing | European pilot installations compress glycerol dehydration energy intensity to qualify for EU Green Deal renewable certifications. |
| Long-term Supply Agreement with Municipal Utilities | German and Dutch water treatment facilities unbundle procurement to lock multi-year offtake with price stability clauses. |
| Stabilized Formulation Distribution Network Expansion | Evonik Industries extends viable supply radius to inland utilities previously constrained by toxicity handling limitations. |
| Joint Venture in Middle East Desalination Corridors | Saudi Arabia's Eastern Province buildouts create biocide demand nodes with limited incumbent supplier saturation. |
Research Methodology
Trade databases, ECHA registration filings, and SEC chemical segment disclosures formed the secondary backbone, supplemented by customs records tracking propylene derivative flows. Primary interviews with plant managers at oxidation facilities, procurement leads at German municipal utilities, distribution channel partners specializing in hazardous chemical logistics, and technical R&D directors at glycerol dehydration pilot sites validated production economics and demand patterns. Bottom-up capacity modeling and top-down end-use consumption estimates were triangulated against import-export parity calculations.
Bottom-up modeling aggregated individual production facility capacities across Jiangsu, Shandong, and Rhine-Ruhr clusters, while top-down analysis tracked acrylic acid and methionine derivative demand as acrolein consumption proxies. Segmentation dimensions included grade tier (liquid, stabilized, polymer), end-use industry (water treatment, agrochemical, chemical intermediate), and regional production hub configuration. CAGRs were derived from regression analysis of historical capacity utilization against downstream demand elasticities, incorporating propylene price correlation coefficients and REACH registration cost amortization schedules.
Revisions become necessary when MEE emission controls tighten beyond current constraints, EPA FIFRA registration timelines extend past standard cycles, or glycerol dehydration catalyst selectivity breakthroughs alter bio-based production economics. Practitioners should monitor EU carbon border adjustment implementation progress and continuous flow reactor commercialization announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Methyl Gluceth-10 Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Asia-Pacific Choline Chloride Market
Bulk Chemicals
Calcium Sulfite Market
Bulk Chemicals
Cobalt (II) Sulfate Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Alunite Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Pyrophyllite Powder Market