
 Global Fruit Juice Concentrate Market | 2026-2036
Global Fruit Juice Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fruit Juice Concentrate Market Analysis
Aseptic processing and low-temperature vacuum evaporation is rewriting how fruit juice concentrate preserves flavor volatiles and extends shelf stability without chemical preservatives. Archer Daniels Midland Company leverages backward integration into citrus groves across Brazil and Florida to secure raw material consistency. AGRANA Beteiligungs-AG sustains its position through specialized apple and berry concentrate operations anchored in European orchards. Ingredion Incorporated differentiates via enzyme-assisted extraction technologies that improve yield rates from tropical fruit feedstocks.
Fruit juice concentrate denotes the water-reduced form of fruit juice, typically achieved through thermal evaporation or membrane filtration to reach soluble solids content of 65 to 72 degrees Brix, designed for reconstitution, ingredient blending, and extended bulk storage in food manufacturing. Citrus concentrate dominates volume flows due to established orange and lemon processing infrastructure in Brazil, Florida, and Spain, while tropical concentrate from pineapple and mango sources registers faster growth as beverage brands diversify flavor portfolios. The beverage application segment absorbs the largest share of output, though nutritional supplements are gaining traction as concentrate suppliers develop standardized polyphenol and vitamin retention profiles for functional product lines.
The FDA enforces juice Hazard Analysis and Critical Control Points rules that mandate pathogen reduction steps, directly elevating capital requirements for concentrate facilities supplying the United States. EFSA and EMA frameworks govern maximum residue limits for pesticides in fruit destined for EU concentrate production, creating compliance barriers for exporters from India and Brazil. China's SAMR and GB standards impose additional labeling and additive restrictions that shape formulation decisions for brands targeting East Asian markets. Stakeholders must monitor how evolving national standards on sugar content claims and clean-label definitions will redirect investment toward minimal-processing concentrate technologies.
Market Dynamics
Low-temperature vacuum evaporation is compressing energy costs while preserving volatile flavor compounds that thermal methods destroy, forcing processors to retire legacy multi-effect evaporators before end-of-life. The EU F-Gas Regulation and parallel energy-efficiency mandates in India and China are accelerating this capital cycle.
Growth Catalysts
- EU Green Deal energy standards:Cold-chain efficiency mandates push processors toward mechanical vapor recompression evaporators that cut thermal energy use by half. Equipment retrofits qualify for green financing instruments.
- Beverage brand R&D pipelines:Functional drink developers in India and Southeast Asia are standardizing concentrate bases for immunity-positioned SKUs, creating pull for polyphenol-retentive extraction methods.
- Brazil-Florida citrus belt concentration:Established grove-to-concentrate infrastructure enables 12-month supply continuity that emerging tropical origins cannot yet match.
Market Restraints
- Input cost volatility:Natural gas and electricity price spikes in Europe have doubled evaporator operating costs versus 2019 baselines, squeezing margin at commodity-grade concentrate tiers.
- Supply concentration risk:Brazil and Florida together account for the majority of frozen orange juice concentrate traded internationally; frost or citrus greening in either region disrupts global pricing.
- Regulatory friction:EFSA pesticide maximum residue limits block entry for Indian mango concentrate shipments that meet domestic FSSAI standards but fail EU thresholds.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya show rising branded juice consumption without local concentrate production, creating import-substitution openings for regional processors.
- Regulatory tailwind:India's PLI scheme for food processing offers capital subsidies for cold-chain and aseptic packaging investments that reduce post-harvest fruit loss.
- Technology convergence:Membrane filtration paired with pulsed electric field pasteurization enables ambient-stable concentrates without thermal degradation, unlocking clean-label positioning.
Industry Challenges
- Skill scarcity in process engineering:Vacuum evaporation and membrane system operation require specialized training that existing fruit processing workforces in India and Brazil largely lack.
- Capex intensity for aseptic lines:FDA-mandated 5-log pathogen reduction systems for US-bound concentrate demand seven-figure investments that mid-scale processors struggle to finance.
- Certification timeline compression:Organic and Fairtrade audits for concentrate supply chains now average 14-18 months, delaying new origin market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fruit Juice Concentrate Market |
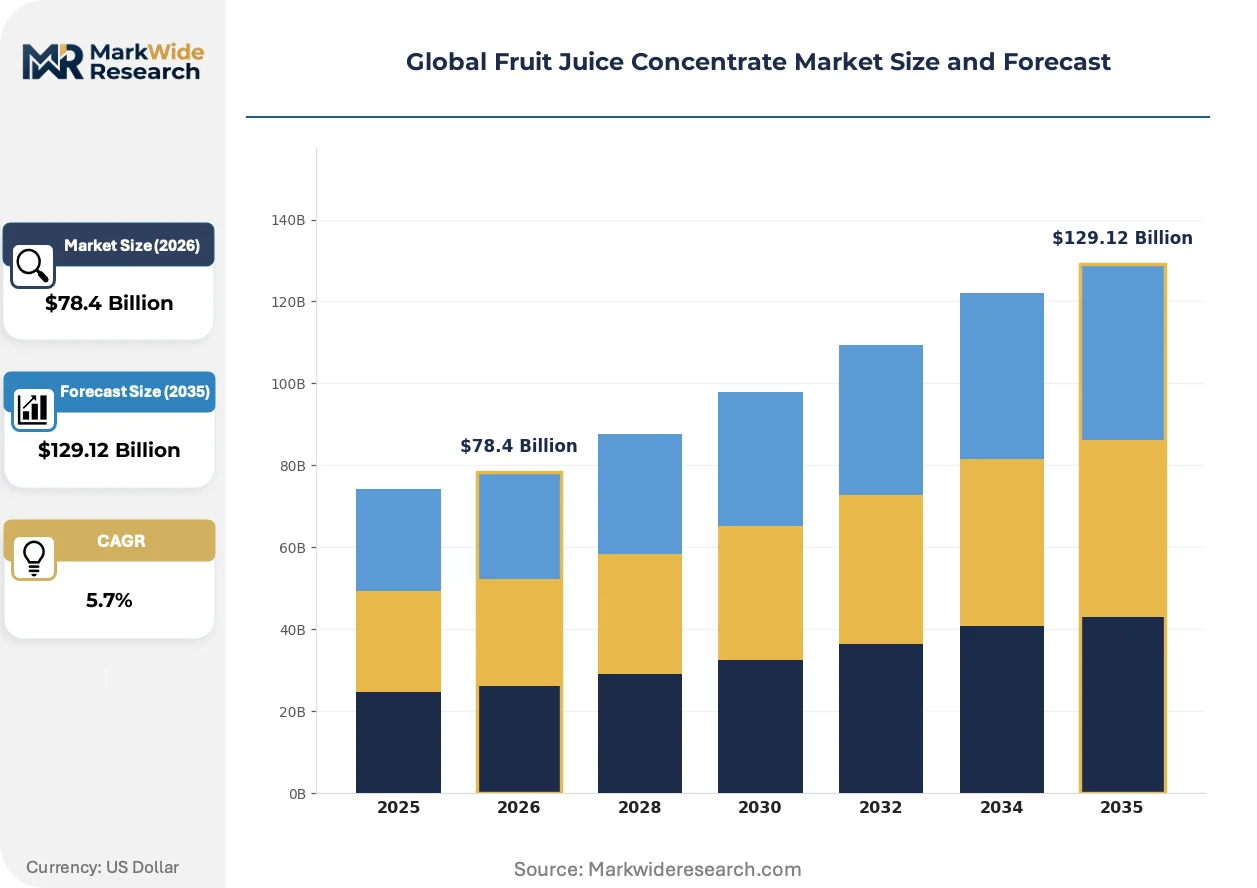
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $129.12 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Concentrate, Berry Concentrate, Tropical Concentrate, Mixed Fruit Concentrate Application: Beverage Industry, Food Processing, Nutritional Supplements, Bakery Products Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Packaging Type: Drum, Bottle, Carton, Pouch |
| Companies Covered | Archer Daniels Midland Company, AGRANA Beteiligungs-AG, Doehler GmbH, Ingredion Incorporated, Lemon Concentrate S.L., SunOpta Inc., SudZucker AG, SVZ International BV, Louis Dreyfus Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fruit Juice Concentrate Market Emerging Trajectories
Concentrate processing is abandoning thermal-first methods in favor of precision separation technologies that preserve functional compounds. This shift reconfigures equipment vendor relationships and raw material sourcing priorities across the supply base.
Membrane filtration systems employing reverse osmosis and nanofiltration stages are replacing thermal evaporation for initial water removal in citrus and apple concentrate production. Premium beverage manufacturers in Western Europe and Japan are specifying membrane-processed concentrate for single-strength reconstitution products. The technology is migrating from niche organic lines to mainstream private-label supply contracts as energy costs render thermal methods uncompetitive.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in concentrate cold storage, compelling warehouse operators to adopt ammonia or CO2 cascade systems. Retrofit costs are concentrating frozen concentrate storage among operators with balance-sheet capacity for infrastructure overhaul. Spanish and Italian processors serving North African export markets face the steepest compliance timelines due to aged facility stock.
Beverage manufacturers are consolidating supplier relationships around concentrate partners who control upstream grove assets and downstream aseptic packaging. This disintermediation of traders and brokers compresses price discovery cycles and shifts quality verification responsibilities to processor laboratories. The pattern is most visible in India, where Reliance Retail and Dabur have established direct procurement ties with Maharashtra and Karnataka pulp processors.
Global Fruit Juice Concentrate Market Segmentation
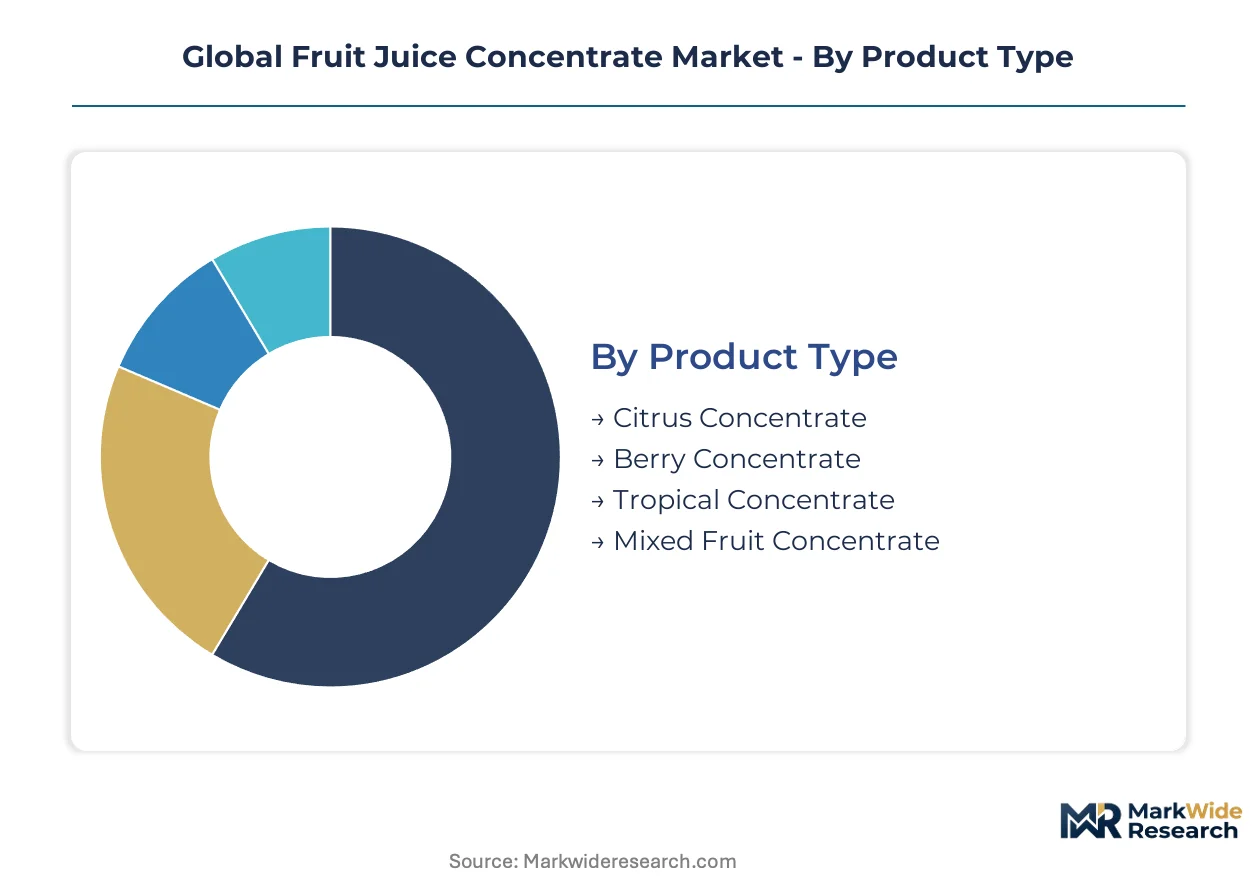
Segmentation in fruit juice concentrate markets reveals how processing technologies, application requirements, and distribution economics create distinct competitive arenas. Each dimension shapes procurement patterns, margin structures, and regulatory exposure differently.
Product Type:
Cost tier differentiation separates commodity-grade thermal concentrates from premium membrane-processed alternatives with volatile compound retention.
- Citrus Concentrate:Orange and lemon concentrates at 65-72 degrees Brix dominate international trade volumes through established Brazil and Florida processing corridors. Beverage manufacturers in India and Southeast Asia standardize procurement around Brazilian frozen concentrated orange juice for 12-month formulation continuity.
- Tropical Concentrate:Pineapple and mango concentrates employ enzyme-assisted extraction to improve yield from fibrous feedstocks. Demand concentrates in India where urban consumers shift from unpackaged to branded concentrate-based beverages, though EFSA pesticide residue limits block EU entry for Indian mango shipments.
- Berry Concentrate:Anthocyanin-retentive low-temperature processing commands premium positioning in functional beverage applications.
- Mixed Fruit Concentrate:Blended profiles enable flavor complexity without multiple single-origin supply contracts.
Citrus concentrate commands the established base. The steepest expansion runs through tropical concentrate.
Application:
Application segmentation tracks how end-use specifications diverge on pathogen reduction standards, shelf stability requirements, and functional compound retention.
- Beverage Industry:Ready-to-drink formulations absorb the largest output share, with concentrate bases enabling standardization across production batches. India's branded juice segment drives procurement volume as Reliance Retail and Dabur establish direct ties with Maharashtra and Karnataka pulp processors.
- Nutritional Supplements:Polyphenol and vitamin standardization requirements demand extraction methods that preserve bioactive compounds. Supplement manufacturers in Japan and Western Europe specify membrane-processed concentrates with documented retention profiles.
- Food Processing:Ingredient blending for sauces and dairy applications prioritizes cost-efficient thermal concentrates.
- Bakery Products:Moisture control and flavor dispersion requirements favor high-Brix concentrates in industrial-scale mixing operations.
Beverage applications anchor volume flows. Nutritional supplements are climbing the fastest as functional positioning penetrates mainstream retail.
Distribution Channel:
Channel segmentation reflects how procurement scale and cold-chain requirements fragment access to different buyer categories.
- Wholesale:Bulk drum and tanker shipments to industrial processors constitute the dominant transaction mode, with pricing indexed to ICE frozen concentrate orange juice futures. Brazilian and Spanish processors consolidate relationships directly with beverage manufacturers, disintermediating traders.
- Online Retail:Small-format concentrates for home reconstitution and craft beverage production are gaining traction in India and Southeast Asia, though cold-chain last-mile costs constrain penetration.
- Supermarkets:Private-label concentrate lines for retail reconstitution occupy shelf space in European and North American markets.
- Convenience Stores:Single-serve concentrate formats target on-the-go consumption in urban India and Nigeria.
Wholesale channels command the established base. Online retail is expanding most quickly as direct-procurement platforms reduce minimum order thresholds.
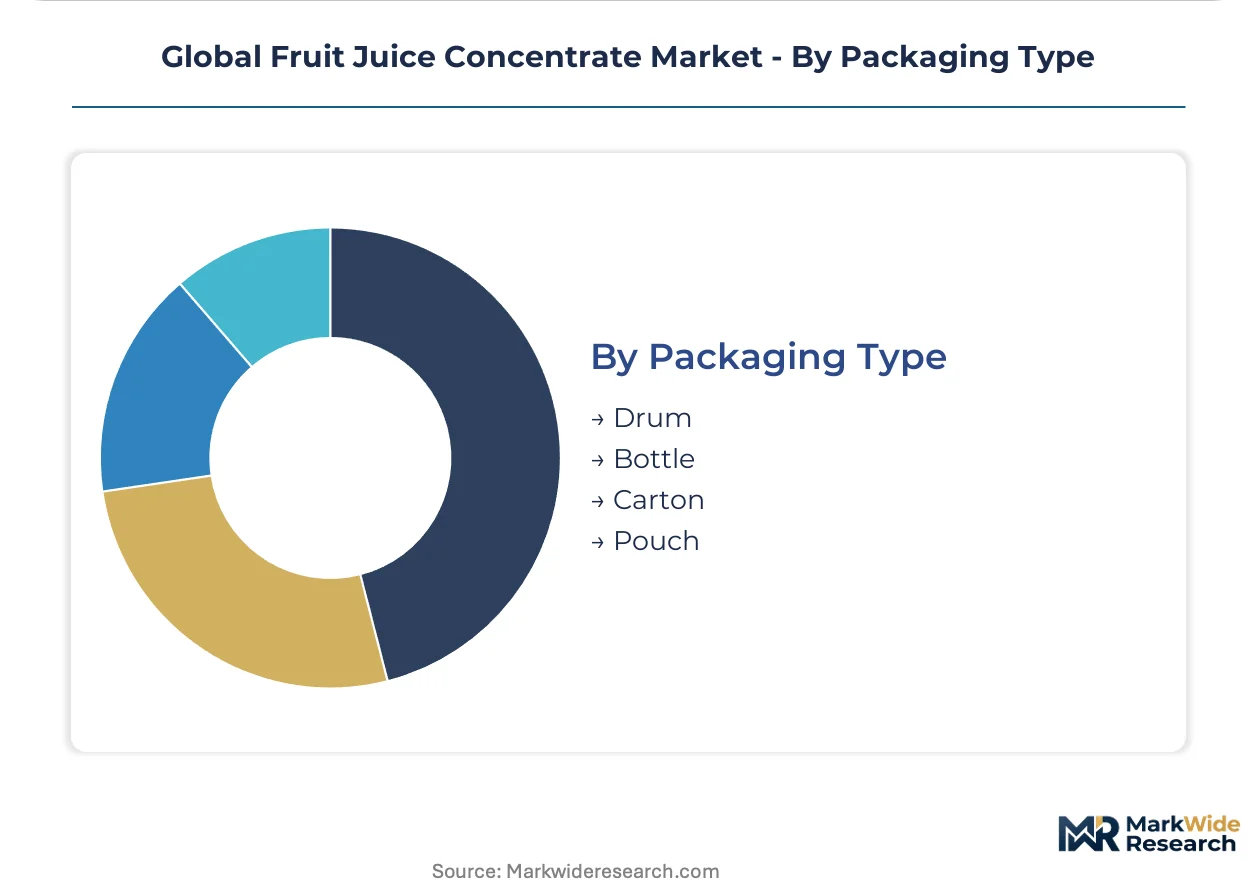
Packaging Type:
Packaging segmentation tracks how aseptic requirements, storage economics, and handling automation shape format selection.
- Drum:Steel and plastic drums with aseptic liners dominate bulk industrial shipments, with FDA-mandated 5-log pathogen reduction systems elevating capital requirements for US-bound supply. Drum formats enable ambient-stable storage when paired with proper aseptic filling.
- Pouch:Flexible aseptic pouches reduce shipping cube and handling costs for tropical concentrate exports from Southeast Asia, though EU F-Gas Regulation cold-storage compliance concentrates frozen pouch inventory among operators with balance-sheet capacity for ammonia refrigeration retrofit.
- Bottle:Retail-ready concentrates for home reconstitution employ oxygen-barrier plastics or glass.
- Carton:Aseptic cartons with extended shelf life target foodservice and institutional buyers.
Drum packaging commands the established base. Pouch formats are gaining share fastest as freight efficiency and handling automation improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage manufacturers in Brazil, India, and the United States drive the bulk of procurement volume, while European processors navigate energy-cost pressures and regulatory compliance timelines. Cold-chain infrastructure investments and government processing subsidies are redrawing competitive positioning across origin markets.
Brazil
São Paulo and Minas Gerais citrus processors supply twelve-month formulation continuity to Indian and Southeast Asian beverage brands. ANVISA enforces pesticide residue monitoring that shapes grove management practices across the citrus belt. Campinas-based processors leverage established port infrastructure at Santos to maintain frozen concentrate export volumes despite frost and citrus greening risks.
India
Maharashtra and Karnataka pulp processors are establishing direct procurement ties with Reliance Retail and Dabur as urban consumers shift from unpackaged to branded concentrate-based beverages. The PLI scheme for food processing offers capital subsidies for cold-chain and aseptic packaging investments. Pune and Bengaluru processing clusters are expanding membrane filtration capacity to serve domestic functional beverage developers.
United States
Florida citrus processors face FDA-mandated 5-log pathogen reduction requirements that elevate capital barriers for concentrate facilities supplying domestic beverage manufacturers. The EPA and OSHA frameworks govern processing emissions and worker safety standards. Orlando-area processing corridors maintain frozen orange juice concentrate futures pricing that indexes global commodity benchmarks.
Germany
Bavarian and Baden-Württemberg fruit processors specialize in apple and berry concentrate operations serving Western European nutritional supplement manufacturers. The EU F-Gas Regulation and EU Green Deal energy standards are accelerating retirement of legacy multi-effect evaporators. Stuttgart-based equipment vendors are supplying mechanical vapor recompression systems that cut thermal energy use by half.
Spain
Valencia and Murcia citrus processors serve North African export markets through established Mediterranean shipping lanes. EFSA pesticide maximum residue limits create compliance barriers for concentrate imports that fail to meet EU thresholds. Barcelona-area cold storage operators face steep retrofit timelines for ammonia refrigeration systems under F-Gas Regulation phase-down schedules.
Global Fruit Juice Concentrate Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement relationships. The vendor base organizes around three structural archetypes: diversified agricultural conglomerates with backward integration into grove assets, specialized concentrate processors anchored in regional orchard clusters, and ingredient technology providers with enzyme-assisted extraction capabilities. Competitive moves concentrate on direct procurement tie formation with beverage manufacturers and equipment retrofit cycles driven by energy-efficiency mandates.
Among diversified agricultural conglomerates, Archer Daniels Midland Company exemplifies the grove-integrated archetype through its Brazilian and Florida citrus operations. AGRANA Beteiligungs-AG occupies a position within the European specialist tier, anchored in Austrian corporate structure and regional orchard supply relationships. Ingredion Incorporated represents the technology-differentiated segment, with US incorporation signaling enzyme-assisted extraction capabilities for tropical fruit feedstocks.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| AGRANA Beteiligungs-AG |
| Doehler GmbH |
| Ingredion Incorporated |
| Lemon Concentrate S.L. |
| SunOpta Inc. |
| SudZucker AG |
| SVZ International BV |
| Louis Dreyfus Company |
| Others |
Supply Flow & Price Mechanics
Brazilian citrus grove concentration hands pricing power to São Paulo processors who index frozen concentrate orange juice contracts to ICE futures, leaving beverage manufacturers in India and Southeast Asia absorbing basis risk while margin pools accumulate with cold-storage operators in Santos and Paranaguá.
Pricing Analysis
Cost-plus contracts with ICE frozen concentrate orange juice futures indexation dominate procurement between Brazilian processors and Asian beverage manufacturers. Price differentiation rests on membrane versus thermal processing grades and organic certification tiers from EU and USDA-accredited bodies. Pricing pressure stems from European natural gas cost spikes that doubled evaporator operating expenses since pre-pandemic baselines. Private-label beverage brands in India exhibit highest price sensitivity, while Japanese functional drink developers accept membrane-processed premiums for documented polyphenol retention profiles.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Brazilian trading houses anchor working capital flows for Indian and Southeast Asian beverage manufacturers. Geographic supply concentrates in Brazil, Florida, and Spain for citrus; India, Thailand, and the Philippines for tropical feedstocks. Raw material dependencies center on citrus fruit, natural gas for thermal evaporation, and aseptic packaging films. Single-source vulnerability runs through the Brazil-Florida citrus belt where frost or citrus greening disease disrupts global availability. Distribution runs through bulk drum shipments to industrial processors, with direct procurement ties displacing trader intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as FDA-mandated 5-log pathogen reduction systems and EFSA pesticide residue compliance create seven-figure capital barriers that lock out unqualified competitors.
For Market Incumbents: Entrench position through backward integration into Maharashtra and Karnataka grove assets to secure tropical concentrate feedstocks against emerging Indian pulp processors. Accelerate mechanical vapor recompression retrofits before EU F-Gas Regulation phase-down deadlines tighten. The priority lever sits with direct procurement tie formation with Reliance Retail and Dabur to disintermediate trader networks. For New Entrants and Emerging Players: Mid-scale membrane filtration capacity serving Nigerian and Kenyan branded juice markets represents the most penetrable entry point given absent local concentrate production and rising import substitution demand. India's PLI scheme capital subsidies for cold-chain investments offer a second white-space avenue. A go-to-market angle through aseptic pouch formats reduces freight cube and handling costs versus legacy drum shipments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European fruit processors facing EU Green Deal energy retrofit timelines and F-Gas Regulation cold-storage compliance costs. Five-to-ten year viability hinges on membrane technology migration and African market expansion execution. The signal to watch is Indian PLI scheme disbursement velocity as an inflection indicator for regional capacity buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Vapor Recompression Retrofit | EU F-Gas Regulation compliance cuts thermal energy use by half at Spanish and Italian processing corridors. |
| Backward Integration into Grove Assets | Archer Daniels Midland's Brazilian citrus operations secure 12-month formulation continuity for Asian beverage brands. |
| Direct Procurement Platform Launch | Reliance Retail and Dabur disintermediate traders through direct ties with Maharashtra pulp processors. |
| Membrane Filtration Capacity Expansion | Pune and Bengaluru clusters serve domestic functional beverage developers with polyphenol-retentive extraction. |
| Aseptic Pouch Format Adoption | Southeast Asian exporters reduce shipping cube and handling costs for tropical concentrate shipments to EU markets. |
Methodological Framework
A standing panel of beverage manufacturing procurement directors, concentrate processing plant managers, cold-storage facility operators, and aseptic packaging equipment vendors provided ongoing calibration against secondary validation from FDA juice HACCP guidance documents, EFSA pesticide residue databases, ANVISA regulatory filings, and ICE frozen concentrate orange juice futures trading records. Primary fieldwork combined structured interviews with downstream formulation chemists and upstream grove operations managers. Bottom-up volume estimates from individual processing facility capacities triangulated against top-down trade flow analysis from customs and port authority data.
Scenario-bracketing around energy cost trajectories and regulatory compliance timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, application specification, distribution channel scale, and packaging format aseptic requirements. CAGRs derived from fitted growth curves applied to baseline volume and value estimates. Industry-specific forecast inputs incorporated PLI scheme subsidy disbursement schedules and EU F-Gas Regulation phase-down compliance timelines.
Practitioners should monitor Brazilian frost patterns, Indian PLI capital subsidy allocation velocity, and EU energy price trajectories for early signals of forecast deviation. Forecasts reflect documented assumptions on technology adoption rates and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Plant Based Beverages Market
Beverages
GCC Fruit Juice Market
Beverages
Coconut Water Market
Beverages
Water Bottle Market
Beverages
Ready to Drink Premixes Market
Beverages
Premium Water Market
Beverages
Hot Beverages Market
Beverages
Oat Based Beverages Market
Beverages
Aloe Vera Juice Market
Beverages
Morocco Bottled Water Market
Beverages
GCC Juice Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Crystal Boba Market
Beverages
Chocolate Malt Drink Market
Beverages
Hot Cocoa Mix Market