
 Commercial Drink Mixers Market | 2026-2036
Commercial Drink Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Drink Mixers Market Outlook
Buyer consolidation among upscale hotel chains is repositioning procurement power toward volume-contracting hospitality groups. Fever-Tree leverages its premium tonic portfolio to anchor supply relationships with these consolidated accounts. Thomas Henry GmbH competes through specialized carbonation systems calibrated for European bar specifications. The Coca-Cola Company extends its fountain equipment dominance into automated mixer dispensers for quick-service restaurant chains.
Commercial drink mixers encompass electromechanical blending, shaking, and dispensing equipment engineered to aerate, emulsify, or chill beverages through controlled motor speeds typically ranging from 15,000 to 30,000 RPM. These machines serve the core commercial purpose of standardizing drink consistency across high-throughput foodservice environments while reducing manual labor. Blenders and shakers occupy the largest installed base among product type segments, though frappe machines command premium pricing due to refrigeration integration complexity. Bars and nightclubs represent the most power-sensitive end user category, driving demand toward 1500W and 2000W units capable of continuous operation during peak service windows.
Foodservice equipment sold across Europe must comply with CE marking requirements under the EU Machinery Directive, while electrical safety certification through IEC standards governs motor assembly exports to multiple jurisdictions. The EU F-Gas Regulation progressively restricts hydrofluorocarbon refrigerants in cooled dispenser units, compelling manufacturers to redesign thermal systems or source alternative coolants. Stakeholders must monitor how evolving energy efficiency labeling schemes and refrigerant phase-down schedules reshape equipment replacement cycles and supplier qualification criteria.
Market Dynamics
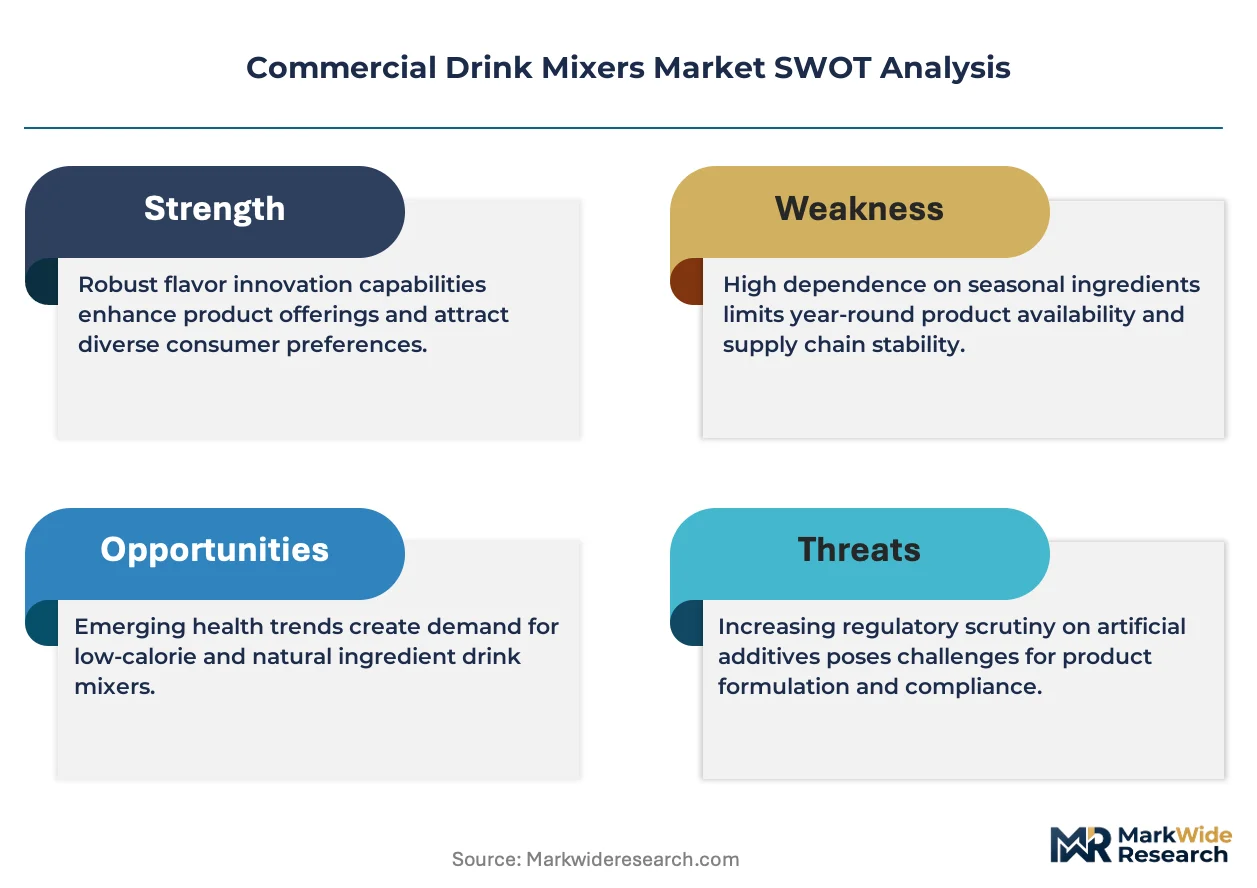
The EU F-Gas Regulation is forcing refrigerant-dependent dispenser manufacturers into accelerated thermal system redesigns, compressing product development cycles and elevating engineering qualification costs across European supply chains.
Growth Catalysts
- Automated Bar Infrastructure:High-throughput cocktail venues in Germany and Spain are retrofitting service stations with programmable dispensing arrays. These installations reduce pour-time variance and labor headcount during peak hours.
- CE Marking Harmonization:Unified machinery safety standards under the EU Machinery Directive eliminate redundant national certifications. Equipment exporters gain faster market access across 27 member states.
- Energy Efficiency Labeling:The EU Ecodesign Framework mandates disclosure of power consumption metrics. Manufacturers investing in brushless motor designs capture preferential positioning in public procurement tenders.
Market Restraints
- Refrigerant Input Volatility:Hydrofluorocarbon phase-down schedules under F-Gas Regulation constrain coolant supply availability. Cooled dispenser production faces intermittent component shortages and price spikes.
- Stainless Steel Concentration:Food-grade 304 and 316 steel sourcing clusters in Chinese and Indian mill networks. European fabricators remain exposed to alloy price fluctuations and ocean freight capacity constraints.
- Electromechanical Durability Ceiling:High-RPM motor assemblies in continuous-use environments exhibit mean-time-between-failures of 8,000 to 12,000 hours. Replacement part logistics burden multi-unit operators.
Strategic Opportunities
- Quick-Service Restaurant Dispenser Integration:Drive-thru beverage programs in the United States are adopting modular mixer-dispenser combinations. Equipment suppliers can anchor multi-year equipment-lease arrangements with fountain system providers.
- Carbon-Neutral Equipment Certification:The EU Green Deal's product environmental footprint criteria reward lifecycle-assessed manufacturing. Early adopters of carbon-accounted production lines qualify for green public procurement preference.
- Cloud-Connected Fleet Management:IoT-enabled usage telemetry allows predictive maintenance contracting. Remote diagnostics reduce technician dispatch frequency for dispersed hotel and casino accounts.
Industry Challenges
- Refrigeration Technician Scarcity:F-Gas-certified service personnel availability lags equipment installation growth in France and Italy. OEMs must internalize training costs or extend warranty exposure.
- Legacy POS Integration:Automated dispensers require API compatibility with property management and point-of-sale systems. Custom middleware development extends deployment timelines for independent hotel operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Drink Mixers Market |
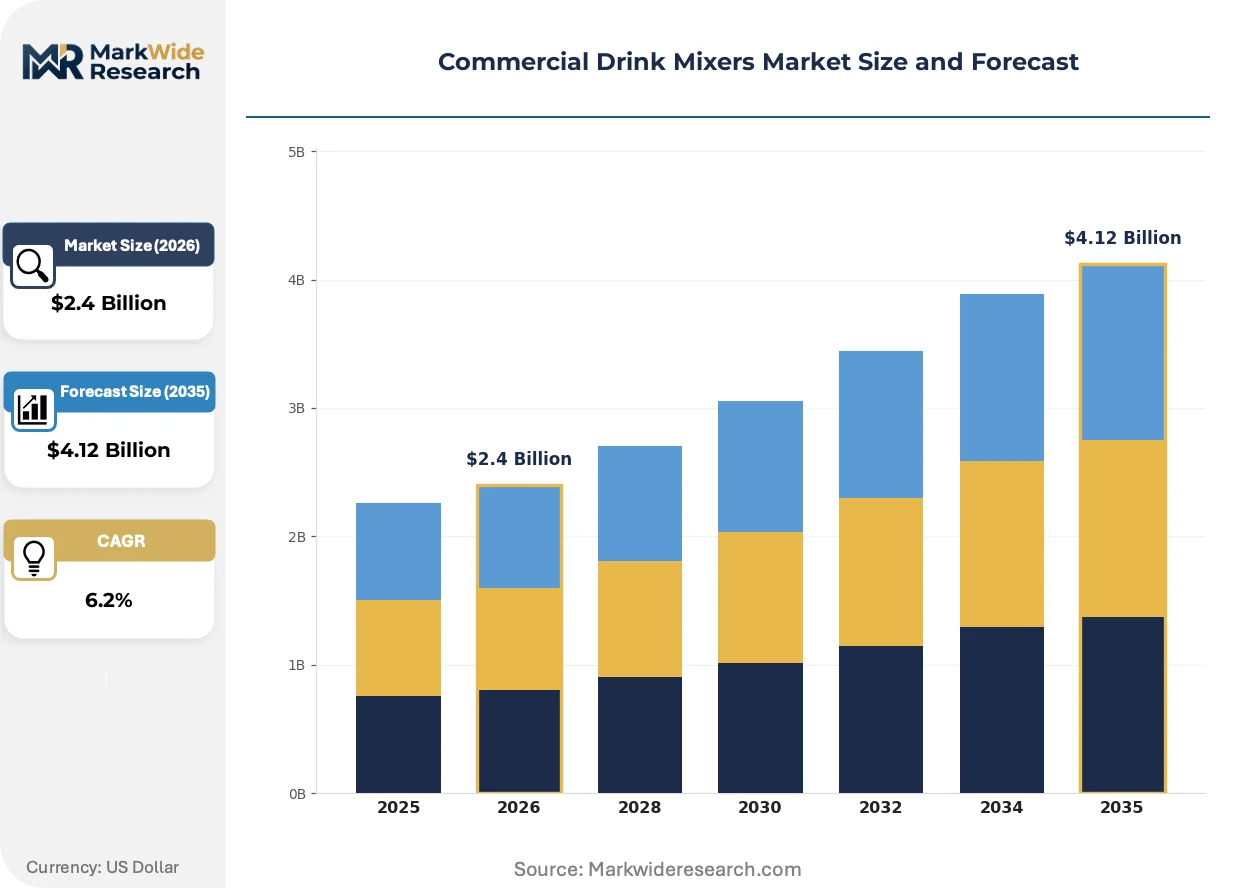
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Shakers, Dispensers, Frappe Machines End User: Restaurants, Bars, Cafes, Nightclubs Power Rating: 500W, 1000W, 1500W, 2000W Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | The London Essence Company, Fentimans, Fever-Tree, East Imperial, Thomas Henry GmbH, The Coca-Cola Company, Britvic, Three Cents, Keurig Dr Pepper, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Drink Mixers Market Strategic Shifts
Electromechanical control systems and refrigerant chemistry are undergoing simultaneous transformation, compressing equipment replacement cycles and elevating the technical threshold for supplier qualification.
Brushless DC motor arrays with variable frequency drives are automating consistency control in high-volume blending operations. Upscale hotel bars and casino beverage stations are retrofitting legacy units at accelerated replacement rates. This automation is compressing the acceptable tolerance range for drink viscosity and temperature, eliminating manual adjustment protocols.
The EU F-Gas Regulation mandates progressive hydrofluorocarbon reduction in refrigeration circuits through 2030. Cooled dispenser manufacturers must redesign thermal exchange systems or adopt hydrocarbon or CO2 alternatives. German and Austrian equipment fabricators are advancing natural refrigerant prototypes ahead of compliance deadlines.
Consolidated hospitality groups are unbundling equipment procurement from syrup and concentrate supply agreements. Volume-contracting hotel chains now negotiate direct mixer sourcing separate from fountain beverage contracts. This decoupling is most visible in North American upscale limited-service segments where procurement functions have centralized.
Commercial Drink Mixers Market Segmentation
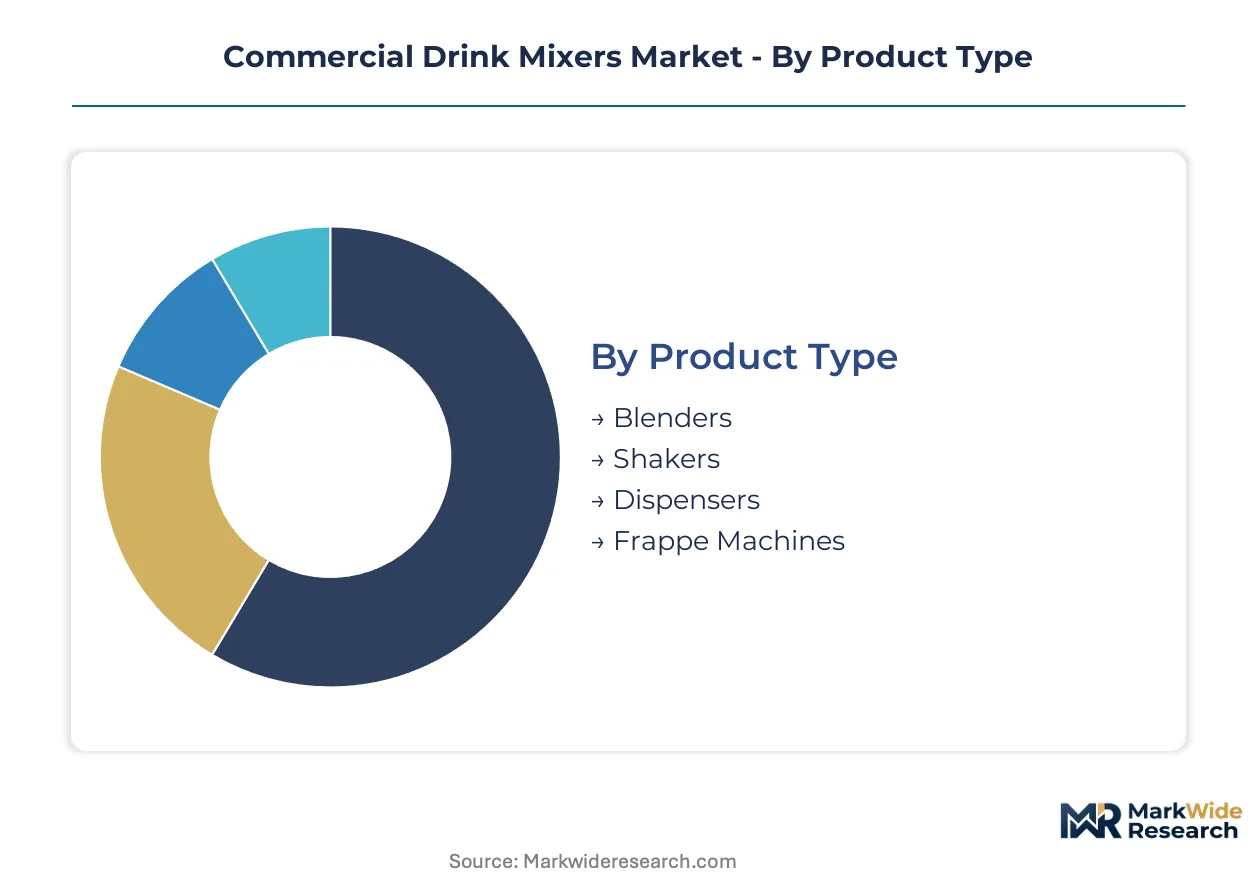
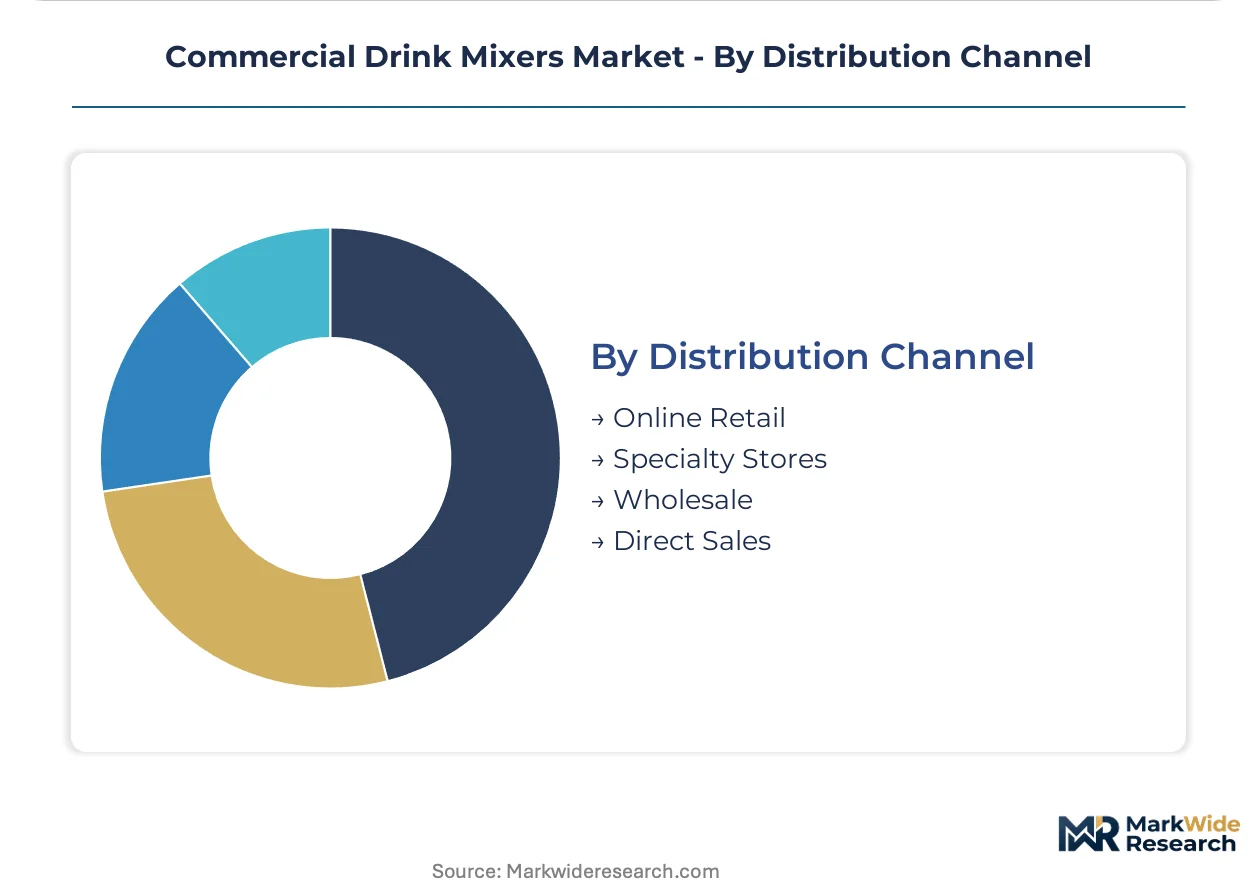
Equipment specification and procurement pathways diverge sharply across commercial drink mixer categories. Bars prioritize motor durability and speed precision, while quick-service operators weight total cost of ownership and vendor service networks. Understanding these segment boundaries clarifies where engineering investment and distribution resources generate returns.
Product Type:
Buyers in this category differentiate by throughput requirements and beverage complexity rather than price sensitivity alone.
- Blenders:Electromechanical units with variable-speed motors from 15,000 to 30,000 RPM dominate frozen cocktail production. German hotel bars and Spanish beachfront venues are retrofitting legacy units with brushless DC arrays to reduce energy draw and maintenance intervals.
- Shakers:Automated shaking mechanisms standardize dilution and aeration for high-volume martini and sour programs. London cocktail bars and Milan aperitivo houses are installing programmable units to eliminate variance during peak service windows.
- Dispensers:Refrigerated or ambient syrup-concentrate systems for fountain beverage programs.
- Frappe Machines:Integrated blending and chilling units with compressor-based thermal management commanding premium positioning.
Blenders lead volumes today; frappe machines are gaining share fastest due to margin premiums on frozen specialty beverages.
End User:
Operational intensity and peak-hour duration separate procurement priorities across venue types.
- Bars:High-throughput cocktail venues demand 1500W and 2000W units rated for continuous duty cycles. Berlin and Barcelona operators are consolidating vendor relationships to secure predictive maintenance contracts and rapid parts availability.
- Nightclubs:Extended operating hours and extreme peak loads drive specification toward industrial-grade motor assemblies with reinforced drive trains.
- Restaurants:Full-service dining rooms with moderate beverage volume prioritize compact footprint and multi-function capability.
- Cafes:Coffee-forward operations with blended beverage menus select lower-wattage units for intermittent use patterns.
Bars anchor installed base today; nightclubs are expanding procurement most aggressively as automated infrastructure spreads.
Power Rating:
Energy cost exposure and duty cycle expectations determine wattage selection across European hospitality operators.
- 1500W:Mid-tier motors balancing throughput and electrical load for standard bar operations. French brasseries and Dutch pub chains are standardizing on this tier to qualify for Ecodesign Framework procurement preferences.
- 2000W:Heavy-duty assemblies engineered for continuous operation in high-volume casino and nightclub environments. Austrian equipment fabricators are advancing natural refrigerant integration in cooled variants ahead of F-Gas Regulation deadlines.
- 500W:Compact units for low-volume or auxiliary beverage stations.
- 1000W:Entry-tier motors for cafes and limited-service restaurants with intermittent blending demand.
1500W leads current installations; 2000W is climbing fastest as automated venues proliferate.
Distribution Channel:
Account scale and technical service requirements shape channel selection more than price transparency.
- Direct Sales:Volume-contracting hotel chains and casino operators negotiate multi-year equipment-lease arrangements with manufacturers. Consolidated hospitality groups in North America are unbundling mixer procurement from fountain beverage contracts to secure direct sourcing terms.
- Wholesale:Foodservice equipment distributors serve independent restaurants and regional bar groups with bundled installation and warranty support.
- Specialty Stores:Catering equipment retailers targeting small operators and replacement part sales.
- Online Retail:E-commerce platforms capturing price-sensitive independent operators and secondary market transactions.
Direct sales dominate value today; wholesale is expanding fastest as mid-tier venue automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled refrigeration technicians and F-Gas-certified service engineers concentrate procurement influence in Germany, Spain, the United Kingdom, France, and Italy. These five markets anchor European equipment specification and drive compliance-driven redesign cycles.
Germany
Berlin and Munich hotel bars are retrofitting legacy units with brushless DC motor arrays to reduce energy draw. The EU F-Gas Regulation compels equipment fabricators in Bavaria to advance natural refrigerant prototypes ahead of 2030 deadlines. Stuttgart-based hospitality equipment distributors now bundle predictive maintenance contracts with 2000W unit sales.
Spain
Barcelona cocktail venues and Madrid nightclub operators are consolidating vendor relationships for rapid parts availability. CE marking harmonization under the EU Machinery Directive accelerates cross-border equipment flows from German suppliers. Valencia's beachfront hospitality clusters are standardizing on 1500W mid-tier motors for frozen beverage programs.
United Kingdom
London cocktail bars are installing programmable shaking mechanisms to eliminate pour-time variance during peak service windows. The UK Retained EU Law Reform Act maintains F-Gas Regulation constraints on refrigerant-dependent dispensers. Manchester and Birmingham hotel groups are unbundling mixer procurement from fountain beverage contracts.
France
Paris brasseries and Lyon hospitality clusters are standardizing on 1500W units to qualify for Ecodesign Framework procurement preferences. ANSM and DGCCRF oversight reinforces food-grade stainless steel certification requirements for commercial blending equipment. Marseille waterfront venues are expanding automated infrastructure at accelerated replacement rates.
Italy
Milan aperitivo houses are adopting programmable dispensing arrays to reduce labor headcount during evening peaks. F-Gas-certified technician scarcity in Rome and Naples extends warranty exposure for cooled dispenser OEMs. Turin-based foodservice equipment distributors are capturing mid-tier venue automation demand through bundled installation services.
Commercial Drink Mixers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: beverage concentrate conglomerates extending fountain equipment dominance, European carbonation specialists with regional bar calibration expertise, and premium tonic portfolio anchors securing consolidated hospitality accounts. Competitive moves concentrate on unbundling procurement from syrup supply agreements and accelerating thermal system redesigns ahead of regulatory deadlines.
Within the premium tonic tier, Fever-Tree and The London Essence Company exemplify portfolio-based supply relationship anchoring. Thomas Henry GmbH represents German-focused carbonation specialization calibrated for European bar specifications. The Coca-Cola Company and Keurig Dr Pepper, Inc. occupy positions as diversified beverage conglomerates extending fountain infrastructure into automated mixer dispensers.
| Leading Market Players |
|---|
| The London Essence Company |
| Fentimans |
| Fever-Tree |
| East Imperial |
| Thomas Henry GmbH |
| The Coca-Cola Company |
| Britvic |
| Three Cents |
| Keurig Dr Pepper, Inc. |
| Others |
Value Chain & Pricing Dynamics
The EU F-Gas Regulation gates both qualified supply and premium-tier pricing access for cooled dispenser manufacturers, forcing thermal system redesign investments that stratify equipment tiers by refrigerant compliance grade and service bundling intensity. Buyers seeking F-Gas-certified units with predictive maintenance contracts face constrained vendor pools and elevated acquisition costs compared to ambient dispenser alternatives.
Pricing Analysis
Bundled equipment-service contracts command premium positioning against unbundled transactional sales, with three-tier pricing structure across premium, standard, and economy levels separating predictive maintenance-inclusive leases from warranty-only purchases and secondary market transactions. Price differentiation rests on CE marking tier and brushless motor certification, with cost compression in economy tiers intensifying due to Chinese mill competition in stainless steel inputs. Independent restaurant operators exhibit highest price sensitivity; casino and hotel chains prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated hospitality groups, while wholesale distributors serve mid-tier venue automation growth. Food-grade 304 and 316 stainless steel sourcing concentrates in Chinese and Indian mill networks, with brushless DC motor arrays and hydrocarbon refrigerant compressors as critical component dependencies. Single-source vulnerability in F-Gas-certified compressor supply exposes European fabricators to intermittent shortages. Distribution runs through Stuttgart-based hospitality equipment distributors and Turin-based foodservice networks for regional market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive maintenance contracting and natural refrigerant premium tiering, with brushless motor standardization driving cost-down trajectories across high-volume installations.
For Market Incumbents: Hedge refrigerant transition exposure by accelerating hydrocarbon and CO2 thermal system prototypes ahead of F-Gas Regulation deadlines. Secure captive supply agreements with F-Gas-certified compressor manufacturers to mitigate technician scarcity risks in France and Italy. Backward integration into brushless motor assembly reduces dependency on Asian electronics suppliers. For New Entrants and Emerging Players: Mid-tier independent hotel operators represent an underserved buyer archetype requiring API-compatible middleware solutions for legacy POS integration. Valencia beachfront hospitality clusters and Marseille waterfront venues offer penetrable geography for 1500W mid-tier motor positioning. Target bundled installation and warranty support through regional wholesale distributors to bypass direct sales channel barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional carbonation specialists with European bar calibration expertise because procurement unbundling from syrup supply agreements creates fragmented vendor targets suitable for platform consolidation. Five-to-ten year viability hinges on natural refrigerant compliance capability and IoT fleet management infrastructure deployment. Monitor F-Gas-certified technician training program expansion as inflection indicator for cooled dispenser market accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Thermal System Redesign | EU F-Gas Regulation compliance secures European market access for cooled dispenser manufacturers. |
| Predictive Maintenance Contracting | IoT-enabled telemetry reduces technician dispatch costs for dispersed hotel and casino accounts. |
| Brushless DC Motor Standardization | Energy efficiency gains qualify manufacturers for Ecodesign Framework procurement preferences. |
| Procurement Unbundling from Syrup Agreements | Direct mixer sourcing terms capture margin from consolidated hospitality group volume contracts. |
| Cloud-Connected Fleet Management | Remote diagnostics capability anchors multi-year equipment-lease arrangements with fountain system providers. |
Study Parameters
Bottom-up hospitality venue modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with bar operations managers, hotel procurement directors, foodservice equipment distributors, F-Gas-certified refrigeration technicians, and aftermarket service heads informed demand-side assumptions. Secondary validation drew from EU Machinery Directive certification databases, CE marking registries, Ecodesign Framework disclosure filings, customs trade data for stainless steel imports, and hospitality equipment distributor sales disclosures.
Input-output matrices map motor wattage tier, end-user venue type, refrigerant compliance grade, and distribution channel structure against regional installation growth patterns across the projection horizon. CAGRs derive from segment-level demand elasticity modeling and replacement cycle acceleration factors. Forecast inputs include F-Gas Regulation phase-down schedules, brushless motor adoption curves in German hotel bar retrofits, and predictive maintenance contract penetration rates in North American casino markets.
Underlying measurement precision varies by segment; 1500W and 2000W motor tiers carry tighter precision than 500W auxiliary units due to disclosed procurement volumes in public tender databases. Forecasts reflect assumptions about refrigerant technology transition timelines and technician training program expansion that periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Italy Probiotic Drinks Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Sparkling Water Machine Market
Beverages
Birch Water Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Morocco Bottled Water Market
Beverages
Fusion Beverages Market
Beverages
Blenders Market
Beverages
Soy Drinks Market
Beverages
North America Cold Pressed Juices Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Carbonate Drink Maker Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Probiotic Beverage Market
Beverages
Powdered Beverages Market