
 Standard Milk Formula Market | 2026-2036
Standard Milk Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Standard Milk Formula Market Analytics
Buyer concentration among urban millennial parents is realigning toward e-commerce platforms and subscription-based replenishment models. Nestlé leverages its direct-to-consumer infrastructure to capture recurring orders. Danone anchors its position through specialized hypoallergenic portfolios. Yili Group competes aggressively on domestic manufacturing scale within China.
Standard milk formula denotes dried or liquid dairy-based nutritional products engineered to approximate human breast milk composition, typically containing adjusted whey-to-casein ratios, added lactose, vegetable oils, and micronutrient fortification for infant or adult dietary supplementation. Powdered formula dominates manufacturing throughput due to extended shelf stability and lower logistics costs, while ready-to-feed products command premium positioning in hospital and travel segments. Organic formulation types are gaining fastest traction among health-conscious buyers, though standard variants retain the largest volume base. Online retailers now represent the fastest-expanding distribution channel, diverting share from traditional supermarkets.
China's SAMR enforces GB standards for infant formula registration and labeling, while the FDA oversees GRAS notifications and facility inspections in the United States. The EU's EFSA sets compositional requirements through its 2006/141/EC directive. Stakeholders must monitor evolving registration pathways and ingredient approval timelines across these jurisdictions to sustain market access.
Market Dynamics
China's SAMR registration requirements for infant formula are compressing market entry timelines while concentrating production among domestic-scale manufacturers. This regulatory tightening is reshaping competitive positioning by privileging vertically integrated suppliers with in-house R&D and testing infrastructure over import-reliant brands.
Growth Catalysts
- E-commerce channel expansion:Urban millennial parents across India's metropolitan corridors are consolidating purchases through subscription-based replenishment models on digital platforms.
- GB standard harmonization:China's updated national food safety standards are tightening ingredient disclosure requirements, creating compliance barriers that favor established domestic manufacturers.
- Hypoallergenic formulation demand:Pediatric allergist recommendations in tier-one Chinese cities are accelerating specialized product development for cow's milk protein sensitivity cases.
Market Restraints
- Dairy input cost volatility:New Zealand and EU dairy auction price swings directly compress margin structures for standard milk formula producers dependent on imported whey and lactose.
- Registration pathway friction:China's SAMR infant formula registration process requires 12-18 month approval timelines, freezing product portfolio refresh cycles for foreign entrants.
- Breastfeeding promotion substitution:WHO-backed national breastfeeding initiatives in Indonesia and Vietnam are displacing first-stage formula demand in public hospital channels.
Strategic Opportunities
- Ready-to-feed hospital penetration:Sterile liquid formats are capturing premium positioning in neonatal intensive care units across China's provincial capital cities.
- Organic certification tailwind:EU organic regulation alignment is opening export pathways for Chinese manufacturers targeting European specialty retailers.
- Adult nutritional extension:Geriatric protein supplementation applications in Japan's aging prefectures are diverting manufacturing capacity toward senior-specific micronutrient fortification.
Industry Challenges
- Formulation scientist scarcity:Qualified pediatric nutrition researchers with human milk oligosaccharide expertise command premium compensation in Shanghai and Beijing labor markets.
- Legacy ERP integration friction:Domestic Chinese manufacturers face 18-24 month digital transformation timelines to achieve SAMR-mandated traceability system compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Standard Milk Formula Market |
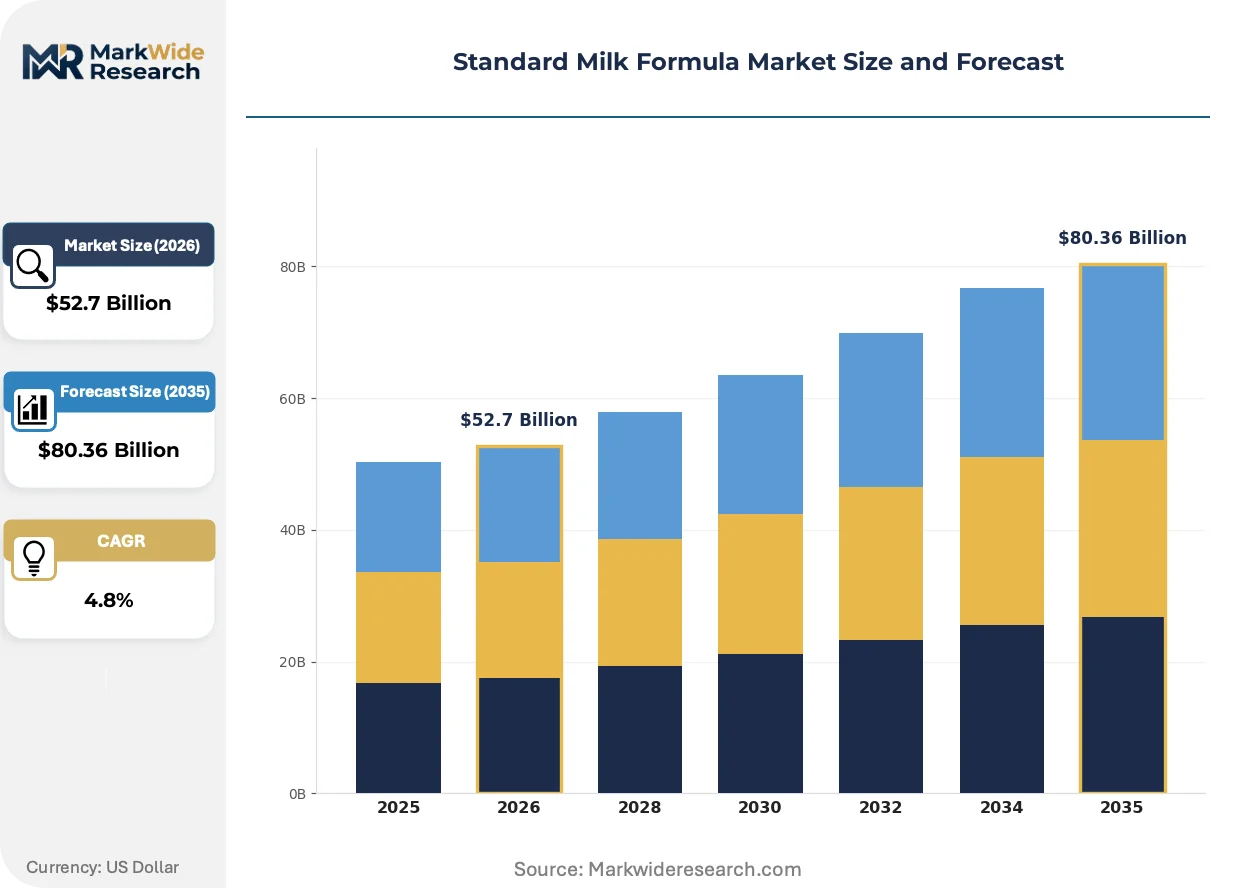
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Formula, Liquid Formula, Ready-to-Feed, Concentrated Formula Age Group: Infants, Toddlers, Children, Adults Formulation Type: Organic, Non-GMO, Hypoallergenic, Standard Distribution Channel: Supermarkets, Online Retailers, Pharmacies, Specialty Stores |
| Companies Covered | Nestlé, Danone, Reckitt Benckiser, Abbott, China Feihe, Yili Group, Ausnutria, FrieslandCampina, Perrigo Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Standard Milk Formula Market Evolving Landscape
Precision fermentation and biosynthetic ingredient platforms are rewriting raw material sourcing economics in standard milk formula production. These biotechnology shifts are compressing traditional dairy commodity dependence while enabling compositional customization previously constrained by agricultural supply cycles.
Precision fermentation-derived lactoferrin and human milk oligosaccharide analogs are rewriting protein and carbohydrate sourcing strategies for premium formulation tiers. Nestlé and Danone pilot facilities in Singapore and the Netherlands are scaling these ingredients for 2025-2026 product launches. This biotechnology transition is compressing the whey protein concentrate spot market while enabling compositional claims unattainable through conventional dairy fractionation.
The EU's 2006/141/EC directive revision proposals are tightening maximum residue limits for environmental contaminants in infant formula. Manufacturing facilities across Ireland and the Netherlands are retrofitting filtration systems to meet anticipated perchlorate and PFAS thresholds. Organic-certified product lines face the steepest compliance costs, accelerating bifurcation between conventional and specialty production assets.
Subscription-based replenishment models are displacing supermarket bulk purchasing among urban Chinese parents with infants under six months. Tmall and JD Health platforms capture recurring orders through AI-driven consumption forecasting tied to pediatric growth milestones. This channel shift concentrates customer data assets with platform operators, compressing brand-direct relationship economics for formula manufacturers.
Standard Milk Formula Market Segmentation
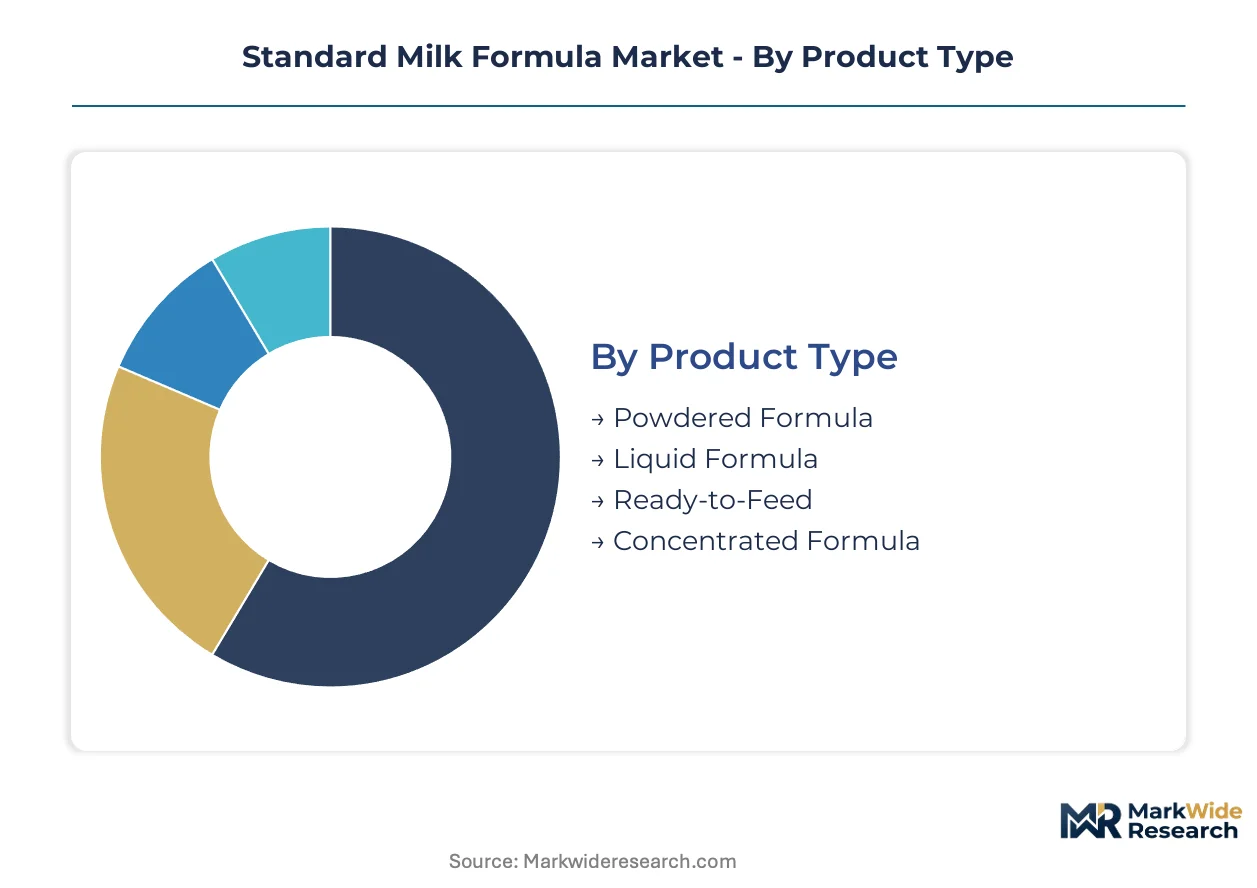
Standard milk formula segmentation reveals divergent margin structures and channel economics across product formats, age targets, and certification tiers. Manufacturers optimize production assets by aligning formulation complexity with distribution reach and regulatory compliance burdens.
Product Type:
Buyers differentiate by convenience threshold versus unit economics, with hospital procurement favoring sterile formats while household purchases prioritize shelf stability and cost per serving.
- Powdered Formula:Dried dairy-based nutritional products with extended shelf stability and lower logistics costs dominate manufacturing throughput. Demand concentrates in China's tier-one cities and India's metropolitan corridors where urban millennial parents prioritize bulk purchasing and storage efficiency.
- Liquid Formula:Reconstituted ready-to-drink formats require refrigerated supply chains and command higher per-serving prices. Neonatal intensive care units across China's provincial capital cities are accelerating sterile liquid procurement for feeding tube compatibility and infection control protocols.
- Ready-to-Feed:Sterile single-serve containers eliminate preparation errors and capture premium positioning in travel and healthcare segments.
- Concentrated Formula:Dilution-required formats balance cost efficiency with reduced storage footprint for high-volume institutional buyers.
Powdered formula leads volumes today; ready-to-feed is gaining share fastest.
Age Group:
Regulatory registration pathways and compositional standards vary sharply across life stages, with infant formulas facing the most stringent SAMR, FDA, and EFSA oversight.
- Infants:First-stage formulations engineered to approximate human breast milk composition with adjusted whey-to-casein ratios and micronutrient fortification. Pediatric allergist recommendations in tier-one Chinese cities are accelerating specialized product development for cow's milk protein sensitivity cases.
- Toddlers:Follow-on formulas with elevated iron and calcium content support developmental transitions. Urban Chinese parents consolidate purchases through Tmall and JD Health subscription models tied to pediatric growth milestones.
- Children:Growth-stage fortification targets cognitive and immune system development with added DHA and prebiotic fibers.
- Adults:Geriatric protein supplementation applications in Japan's aging prefectures are diverting manufacturing capacity toward senior-specific micronutrient fortification.
Infant formulations anchor revenue today; adult nutritional extension climbs the fastest.
Formulation Type:
Certification tier determines raw material sourcing costs, manufacturing facility requirements, and permissible distribution channels with divergent margin profiles.
- Organic:EU organic regulation alignment is opening export pathways for Chinese manufacturers targeting European specialty retailers. Organic-certified product lines face the steepest compliance costs as Ireland and Netherlands facilities retrofit filtration systems to meet anticipated perchlorate and PFAS thresholds.
- Non-GMO:Identity-preserved supply chains exclude genetically modified feed sources for dairy inputs. Verification requirements compress procurement flexibility while commanding shelf price premiums in North American and European markets.
- Hypoallergenic:Extensively hydrolyzed or amino acid-based proteins address cow's milk protein sensitivity. Danone anchors market position through specialized hypoallergenic portfolios.
- Standard:Conventional dairy-derived formulations retain the largest volume base through cost-optimized production and broad retail distribution.
Standard variants dominate volume today; organic certification tiers show steepest expansion trajectory.
Distribution Channel:
Channel selection determines customer data ownership, replenishment predictability, and margin capture with platform operators increasingly intermediating brand relationships.
- Supermarkets:Traditional bulk purchasing venues face share erosion as subscription models displace planned stock-up trips. Shelf space negotiations concentrate leverage with multinational retailers.
- Online Retailers:AI-driven consumption forecasting captures recurring orders through Tmall and JD Health platforms. This channel shift concentrates customer data assets with platform operators, compressing brand-direct relationship economics.
- Pharmacies:Clinical credibility and pharmacist consultation support specialized and medical-grade formula recommendations.
- Specialty Stores:Curated organic and premium assortments serve health-conscious buyer segments with educated staff and sampling programs.
Supermarkets retain volume leadership today; online retailers expand most quickly.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR registration requirements compress foreign entry timelines while domestic manufacturers consolidate share; India's FSSAI enforcement creates parallel compliance barriers that privilege organized sector players over informal suppliers.
China
Urban millennial parents in Shanghai and Beijing drive subscription-based replenishment through Tmall and JD Health platforms. SAMR enforces GB standards for infant formula registration with 12-18 month approval timelines. Production concentrates in Hebei and Inner Mongolia where Yili Group and China Feihe operate vertically integrated dairy complexes.
India
Metropolitan corridors in Mumbai and Delhi-NCR expand e-commerce formula purchases through digital pharmacy networks. FSSAI mandates BIS certification for imported dairy ingredients with stringent labeling requirements. Manufacturing clusters in Gujarat and Maharashtra host domestic blending facilities serving organized retail chains.
United States
Pediatric allergist recommendations accelerate hypoallergenic formulation demand in urban hospital systems. FDA oversees GRAS notifications and facility inspections with emphasis on Cronobacter prevention protocols. Production gravity centers on Wisconsin and California dairy processing corridors with precision fermentation pilot investments.
Netherlands
EU organic regulation alignment opens export pathways for specialty retailers across German and French markets. EFSA sets compositional requirements through 2006/141/EC directive with anticipated perchlorate threshold revisions. FrieslandCampina anchors production in Friesland province with filtration retrofit investments for PFAS compliance.
Japan
Geriatric protein supplementation applications in aging prefectures divert manufacturing capacity toward senior-specific fortification. METI promotes functional food claims with stringent substantiation requirements. Production concentrates in Kanto region around Tokyo with precision fermentation partnerships for biosynthetic ingredient sourcing.
Standard Milk Formula Market Competitive Landscape
European producers anchor one tier through specialized hypoallergenic and organic portfolios; Chinese specialists hold volume leadership via domestic manufacturing scale and SAMR registration advantages. The market structures around three tiers: multinational nutrition conglomerates with direct-to-consumer infrastructure, domestic-scale manufacturers with captive dairy supply, and contract manufacturers serving private-label retailers. Consolidation pressures favor vertically integrated players with in-house R&D and testing infrastructure over import-reliant brands. Dominant competitive moves include strategic partnerships for precision fermentation ingredient sourcing and portfolio diversification into adult nutritional extensions.
Within the multinational tier, Nestlé and Danone occupy positions defined by recurring revenue capture through subscription platforms and specialized formulation expertise. Among China-based manufacturers, Yili Group and China Feihe exemplify domestic-scale competitive advantages through SAMR registration density and vertically integrated production assets. These named entities represent archetypal strategic positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| Reckitt Benckiser |
| Abbott |
| China Feihe |
| Yili Group |
| Ausnutria |
| FrieslandCampina |
| Perrigo Company |
| Others |
Value Network & Pricing Analysis
Captive dairy supply integration in Hebei and Inner Mongolia anchors both procurement stability and pricing power for Chinese manufacturers, while import-reliant brands absorb tariff and logistics premiums that compress margin structures against domestic-scale competitors.
Pricing Analysis
Capacity additions in China's provincial dairy clusters are reshaping price floors for standard milk formula, pressuring import-dependent brands to absorb logistics premiums or cede share. Three-tier pricing structure across organic, hypoallergenic, and standard certification levels captures divergent buyer willingness-to-pay, with urban millennial parents in tier-one cities showing lowest price sensitivity for specialized pediatric recommendations. Price erosion runs through economy-tier powdered segments as domestic manufacturers exploit backward integration into whey processing. Bulk institutional buyers in India's hospital channels exhibit highest price sensitivity, driving concentrated procurement negotiations.
Supply Chain Analysis
Freight cost differentials between ocean container and overland rail routes are restructuring procurement geography for European and Chinese manufacturers serving Asian demand. Raw material sourcing draws from New Zealand whey concentrate, EU lactose refiners, and domestic Chinese dairy cooperatives, creating multi-origin dependency patterns. Single-source vulnerability concentrates in precision fermentation feedstock suppliers based in Singapore and Netherlands pilot facilities. Distribution runs through platform-operated fulfillment centers that intermediate last-mile logistics and capture customer data assets from brand manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's SAMR-registered domestic production and India's FSSAI-import barriers creates margin expansion opportunities for manufacturers with dual-jurisdiction compliance infrastructure, exploiting regulatory cost differentials that exceed freight economics.
For Market Incumbents: Hedge against biosynthetic ingredient disruption by securing offtake agreements with precision fermentation operators in Singapore and Netherlands, while reinforcing SAMR registration density to defend against import-reliant challengers facing 12-18 month approval timelines. Capacity expansion in Hebei dairy corridors preserves cost position against New Zealand whey price volatility. For New Entrants and Emerging Players: Launch via subscription-based replenishment models on Tmall and JD Health platforms to bypass supermarket slotting fee barriers and capture recurring revenue predictability. White-space concentrates in adult nutritional extensions for Japan's aging prefectures and organic-certified export pathways aligned with EU regulation. For Investors and Strategic Acquirers: Roll-up economics work for domestic Chinese manufacturers with captive dairy supply because SAMR registration scarcity creates acquisition premiums for compliant production assets. Target vertically integrated mid-scale producers with in-house R&D infrastructure. Signal to watch: precision fermentation ingredient cost curves crossing conventional dairy fractionation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Biosynthetic lactoferrin sourcing from Singapore facilities reduces whey commodity dependence for premium tiers. |
| SAMR Registration Expansion | Additional GB standard approvals in China compress competitor entry timelines and consolidate shelf access. |
| Adult Nutritional Extension | Geriatric protein fortification for Japan's METI-regulated functional food claims diversifies revenue beyond infant segments. |
| Direct-to-Consumer Platform Buildout | Owned subscription infrastructure recaptures customer data from Tmall and JD Health platform intermediation. |
| EU Organic Certification Alignment | Perchlorate and PFAS compliance investments unlock export pathways to German and French specialty retailers. |
Research Methodology
Direct dialogue with infant formula brand managers, pediatric nutrition R&D directors, SAMR regulatory consultants, and Tmall platform category buyers grounded qualitative findings, validated against FDA GRAS notification databases, EU EFSA scientific opinions, China customs import records, and Nielsen retail audit data across the analysis window. Bottom-up volume estimates triangulated with top-down category spend analysis.
Bottom-up modeling segmented by product format, age group target, certification tier, and distribution channel across the projection horizon, with value outputs derived from pricing stratification across premium, standard, and economy tiers. CAGRs synthesized from historical trajectory analysis and regulatory event impact assessment, incorporating SAMR approval timeline distributions and precision fermentation scale-up curves as industry-specific inputs.
Several conditions sit outside the modeled scope, including sudden GB standard revisions, bilateral trade tariff escalations, and breakthrough breastfeeding promotion policy shifts in Southeast Asian markets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Functional Milk Replacers Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
Canned Baby Food Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market