
 Beverage Clouding Agent Market | 2026-2036
Beverage Clouding Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Clouding Agent Market Outlook
Capital-intensity divergence between in-house extraction capabilities and outsourced blending operations is reorganizing competitive tiers across the beverage clouding agent supply base. Kerry Group leverages integrated citrus and tropical fruit extract streams to anchor its natural clouding portfolio. Givaudan competes through flavor-clouding synergy platforms that bundle taste modulation with turbidity control. Cargill sustains agricultural origination advantages that secure consistent feedstock for gum-based clouding systems.
Beverage clouding agents are colloidal suspensions—typically comprising modified starches, gum arabic, or titanium dioxide alternatives—engineered to scatter light and impart visual opacity without destabilizing flavor or shelf stability. Their primary commercial purpose lies in replicating the sensory expectation of freshness and pulp content in clarified or diluted juice matrices. Natural clouding systems command expanding formulation share as beverage makers replace synthetic titanium dioxide under regulatory pressure, while emulsifiers retain structural importance in dairy-alternative beverages where fat-protein stabilization determines mouthfeel consistency. Powder forms dominate logistics economics for multinational food manufacturers, though liquid concentrates gain traction among craft beverage producers seeking batch flexibility.
FDA oversight of color additive petitions and EFSA evaluations of titanium dioxide safety are reshaping permissible ingredient lists and accelerating clean-label transitions. BIS standards in India and GB standards in China add compliance layers for exporters targeting Asia-Pacific manufacturing hubs. Stakeholders must monitor evolving positive-list frameworks for clouding agents and calibrate R&D pipelines toward label-friendly alternatives before regulatory deadlines crystallize procurement requirements.
Market Dynamics
Clean-label regulatory deadlines from EFSA and FDA are forcing beverage formulators to abandon synthetic opacity systems before 2025 compliance windows close, compressing reformulation cycles and reordering supplier hierarchies around natural extract capabilities.
Growth Catalysts
- EFSA titanium dioxide ban:The 2022 EFSA safety assessment and subsequent additive prohibition across EU member states is accelerating procurement of starch and citrus-based clouding alternatives in premium juice portfolios.
- Dairy-alternative beverage expansion:Oat, almond, and coconut milk manufacturers require stable fat-protein emulsification systems that cloud uniformly while maintaining extended shelf stability.
- Japan functional drink premiumization:Japanese beverage makers are integrating natural clouding agents into collagen-enriched and vitamin-fortified SKUs to signal freshness and pulp authenticity.
Market Restraints
- Gum arabic supply concentration:Sudan and Chad supply over 80% of commercial gum arabic, exposing formulators to geopolitical disruption and price volatility in hydrocolloid-dependent systems.
- Natural extract yield variability:Citrus and tropical fruit extract turbidity fluctuates by harvest season and cultivar, complicating standardization for multinational brand consistency requirements.
- FDA color additive petition timelines:New natural clouding submissions face 12-24 month review windows, delaying market entry for novel botanical opacity systems.
Strategic Opportunities
- India beverage manufacturing expansion:FSSAI clean-label guidelines and domestic juice processing growth create demand for cost-optimized natural clouding systems in Mumbai and Bangalore production clusters.
- Cell-cultured fat integration:Precision fermentation-derived lipid structures are converging with plant protein stabilization to enable next-generation opacity in hybrid dairy alternatives.
- Direct-to-craft distribution:Liquid concentrate clouding formats are bypassing traditional ingredient distributors to reach small-batch kombucha and functional soda producers through specialized e-procurement platforms.
Industry Challenges
- Emulsion stability expertise gap:Formulation chemists with cross-functional knowledge of colloid science and beverage pasteurization are scarce relative to R&D pipeline demands.
- Clean-label certification complexity:Multiple non-GMO, organic, and natural claim standards across USDA, EU organic, and private retailer specifications extend validation timelines by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Clouding Agent Market |
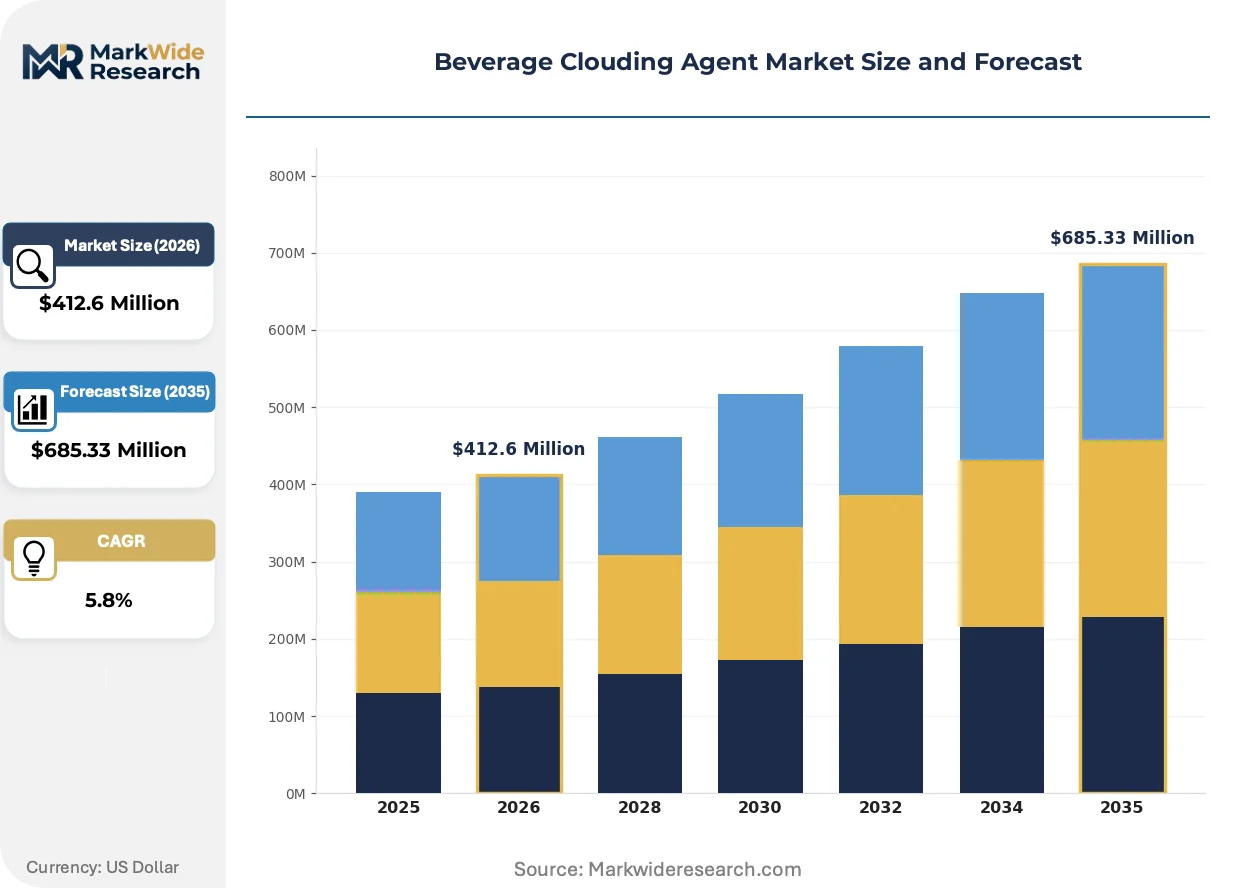
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Emulsifiers, Gums Application: Non-alcoholic Beverages, Dairy Products, Juices, Soft Drinks End User: Food Manufacturers, Beverage Makers, Distributors, Retailers Form: Powder, Liquid, Granular, Paste |
| Companies Covered | Kerry Group, Givaudan, Cargill, CP Kelco, Sensient Technologies Corporation, Eastman Chemical, Chr. Hansen Holding, Danisco, ADM Wild Flavours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Clouding Agent Market Strategic Shifts
Reformulation pressure is fragmenting the clouding agent supply base into specialized natural extract processors and synthetic emulsion houses, with technology convergence determining competitive survival.
Cellulose nanocrystal suspensions are decomposing the traditional modified starch dominance in high-acid juice applications. Premium organic juice manufacturers in Germany and California are adopting these plant-derived colloids at pilot scale. The technology is decomposing cost barriers between natural and synthetic opacity systems by eliminating heat-processing steps.
REACH authorization requirements for titanium dioxide nanoparticles are extending compliance documentation burdens to EU-based beverage exporters. Manufacturers must submit updated safety dossiers for legacy opacity formulations or face market withdrawal. Dairy-alternative portfolios targeting Nordic retail channels are most affected, accelerating substitution timelines by 18 months.
Beverage procurement teams are consolidating supplier relationships around integrated flavor-clouding platforms rather than discrete ingredient sourcing. Large multinational manufacturers are displacing spot-market gum arabic purchases with multi-year extract supply agreements. This concentration is most visible in United States contract manufacturing, where three-tier supplier qualification is narrowing the approved vendor base.
Beverage Clouding Agent Market Segmentation
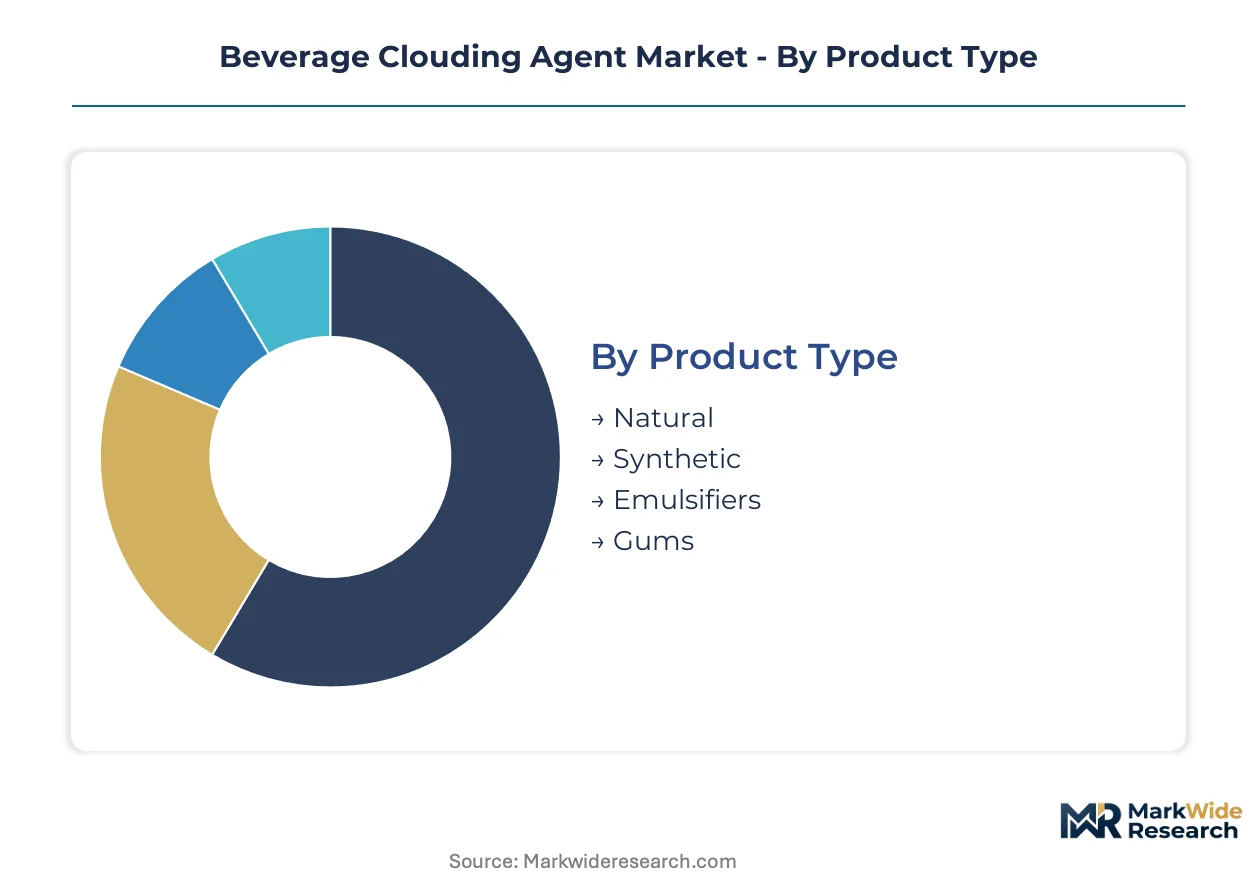
Beverage clouding agent procurement diverges sharply across formulation philosophies and supply chain configurations. Segmentation reveals where natural substitution pressure concentrates versus where synthetic systems retain structural advantages.
Product Type:
Natural clouding systems face the steepest substitution threat as EFSA and FDA deadlines force titanium dioxide abandonment across premium juice portfolios.
- Natural:Citrus pectin, tropical fruit extracts, and cellulose nanocrystal suspensions scatter light through colloidal particle distribution. German organic juice manufacturers and California premium beverage processors are consolidating procurement around these systems to meet clean-label certification requirements.
- Synthetic:Modified starches and engineered emulsifiers deliver standardized turbidity at lower unit cost. These retain formulation share in emerging-market soft drink production where regulatory deadlines lag and price sensitivity dominates procurement decisions.
- Emulsifiers:Fat-protein stabilization systems for oat and almond milk applications.
- Gums:Hydrocolloid suspensions dependent on Sudan and Chad supply chains.
Natural retains volume leadership; Emulsifiers hold the steepest expansion curve.
Application:
Cost tier stratification separates premium juice reformulation from mass-market soft drink opacity requirements.
- Non-alcoholic Beverages:Functional drink manufacturers in Japan integrate clouding agents into collagen-enriched and vitamin-fortified SKUs to signal freshness authenticity. METI guidance on clean-label claims is accelerating natural system adoption in Tokyo and Osaka production clusters.
- Dairy Products:Plant-based milk alternatives require stable emulsification for uniform opacity across extended shelf life. Oat milk processors in Sweden and almond milk manufacturers in California are standardizing on gum arabic and modified starch blends.
- Juices:Premium clarified juice matrices demanding pulp replication.
- Soft Drinks:Mass-market carbonated and still beverages prioritizing cost efficiency.
Juices command premium pricing tiers; Non-alcoholic Beverages are expanding most quickly.
End User:
Customer type determines whether procurement flows through multi-year supply agreements or spot-market purchasing.
- Food Manufacturers:Integrated beverage and snack conglomerates with captive R&D capabilities. These buyers qualify suppliers through three-tier vendor assessment protocols and consolidate around integrated flavor-clouding platforms.
- Beverage Makers:Dedicated drink producers ranging from multinational juice processors to craft kombucha startups. Small-batch producers in Brooklyn and Portland are bypassing traditional distributors through specialized e-procurement platforms for liquid concentrate formats.
- Distributors:Ingredient intermediaries managing inventory and logistics for regional processors.
- Retailers:Private-label beverage developers with direct formulation oversight.
Beverage Makers retain volume leadership; Food Manufacturers hold the steepest expansion curve.
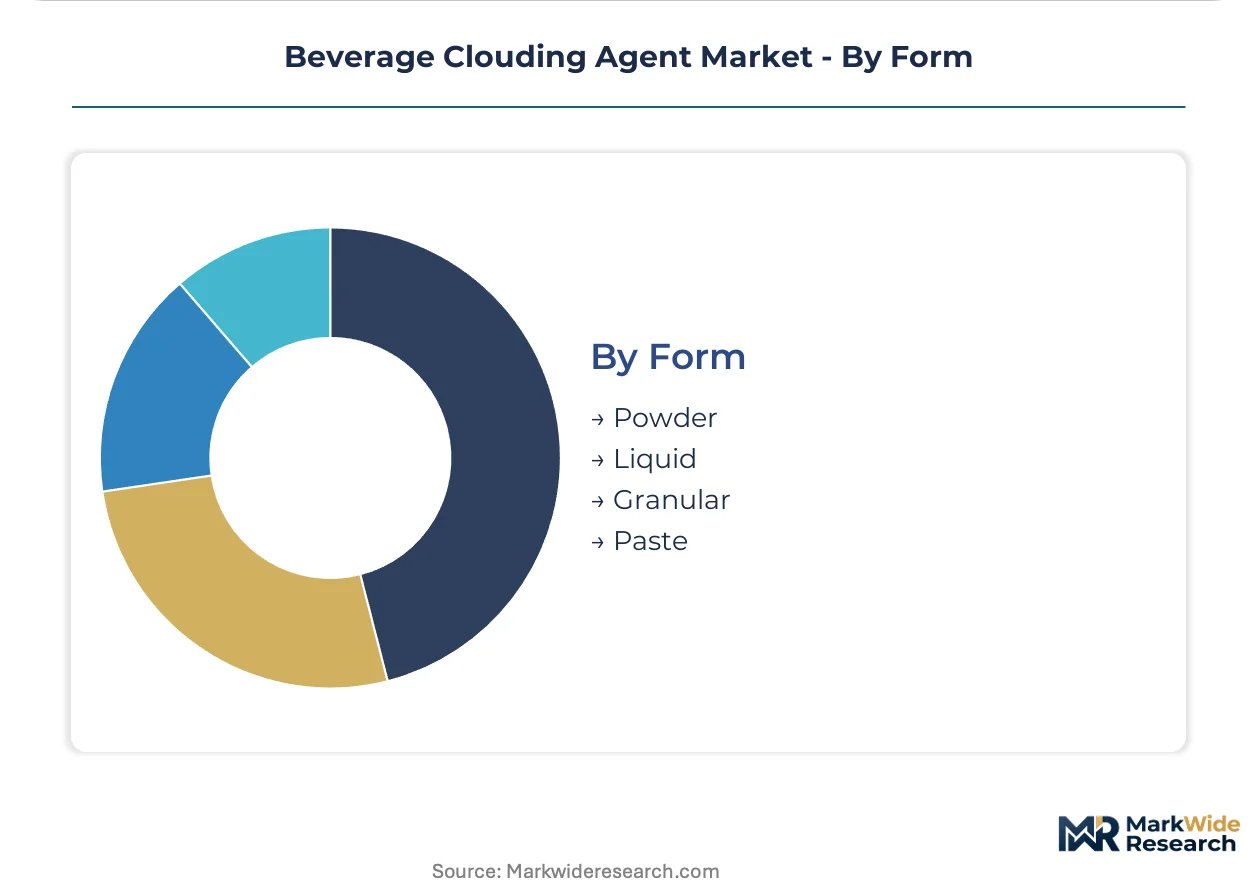
Form:
Supply chain economics favor powder logistics for multinational scale, while batch flexibility drives liquid adoption among craft producers.
- Powder:Spray-dried and agglomerated formats dominating multinational food manufacturer procurement. Powdered systems reduce transport costs and extend shelf stability for transoceanic supply chains serving Mumbai and São Paulo production hubs.
- Liquid:Concentrated suspensions enabling rapid batch adjustment. Craft beverage producers in Copenhagen and Melbourne are adopting liquid clouding systems to accommodate seasonal recipe variations without dry-mix infrastructure investment.
- Granular:Intermediate flowability for mid-scale processing operations.
- Paste:High-viscosity formats for specialized dairy-alternative applications.
Powder retains volume leadership; Liquid gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium juice formulators in Germany command pricing power that mass-market processors in India cannot replicate. This asymmetry fragments procurement strategies across the Beverage Clouding Agent Market.
United States
Functional beverage brands in Brooklyn and Portland drive liquid concentrate adoption through e-procurement platforms. FDA color additive petition timelines stretch 12-24 months, delaying novel botanical opacity systems. California organic juice processors anchor West Coast natural clouding demand.
Germany
REACH authorization requirements for titanium dioxide nanoparticles force legacy formulation withdrawals across dairy-alternative portfolios. EFSA's additive prohibition accelerates starch and citrus-based substitution. Bavarian premium beverage manufacturers pilot cellulose nanocrystal suspensions at commercial scale.
Japan
Collagen-enriched and vitamin-fortified SKUs integrate natural clouding agents to signal freshness authenticity. METI guidance on clean-label claims compresses reformulation cycles in Tokyo and Osaka production clusters. Functional drink premiumization outpaces regional volume growth.
India
FSSAI clean-label guidelines and domestic juice processing expansion create demand for cost-optimized natural systems. BIS standards add compliance layers for imported emulsion formulations. Mumbai and Bangalore production clusters concentrate procurement activity for South Asian export markets.
China
GB standards for food additives reshape permissible ingredient lists for beverage exporters targeting Asia-Pacific manufacturing hubs. Dual carbon goals pressure processors toward lower-energy clouding production methods. Yangtze River Delta beverage conglomerates consolidate supplier relationships around multi-year extract agreements.
Beverage Clouding Agent Market Competitive Environment
Concentration sits with integrated ingredient conglomerates that control upstream agricultural origination and downstream formulation science. The vendor base organizes around three strategic archetypes: citrus and tropical fruit extract processors, flavor-clouding synergy platforms, and gum-based hydrocolloid suppliers. M&A activity targets captive supply chain control, while portfolio diversification moves bundle turbidity systems with taste modulation technologies.
Within the integrated extraction tier, Kerry Group leverages captive citrus streams to anchor natural clouding portfolios. Givaudan occupies a position exemplifying flavor-clouding convergence. Cargill represents agricultural origination advantages securing consistent feedstock for hydrocolloid-dependent systems.
| Leading Market Players |
|---|
| Kerry Group |
| Givaudan |
| Cargill |
| CP Kelco |
| Sensient Technologies Corporation |
| Eastman Chemical |
| Chr. Hansen Holding |
| Danisco |
| ADM Wild Flavours |
| Others |
Value Chain & Pricing Dynamics
Starch and citrus-based clouding alternatives replacing titanium dioxide simultaneously redraw procurement geography toward Mediterranean and Southeast Asian extract processors and compress pricing premiums for natural opacity systems. This substitution dynamic forces beverage formulators to absorb harvest-season yield variability while negotiating multi-year supply agreements that lock in cost predictability.
Pricing Analysis
The customization-premium spread separates configured-to-order natural extract blends from standard modified starch formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—organic and non-GMO claims command 15-25% uplifts—while volume scale inversely correlates with unit economics. Cost compression in synthetic emulsion tiers stems from Sudanese gum arabic price volatility. Mass-market soft drink manufacturers exhibit highest price sensitivity; premium organic juice processors accept formulation premiums for label compliance.
Supply Chain Analysis
Sudan and Chad anchor commercial gum arabic production, while Brazil and India concentrate citrus pectin extraction capacity. Natural clouding systems draw from tropical fruit pulp streams, cellulose nanocrystal feedstocks, and modified starch corn derivatives. Single-source vulnerability concentrates in the Sahel gum belt where geopolitical disruption threatens hydrocolloid-dependent formulations. Distribution runs through integrated ingredient conglomerates with captive agricultural origination and regional blending facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against cellulose nanocrystal suspensions and precision-fermented lipid structures that threaten modified starch dominance in high-acid juice applications.
For Market Incumbents: Secure backward integration into citrus and tropical fruit extract streams to anchor natural clouding portfolios against EFSA and FDA compliance deadlines. Lock multi-year supply agreements with Sudanese and Chadian gum arabic cooperatives to mitigate geopolitical disruption risk. Prioritize certification investment in USDA Organic and EU Organic tiers to capture premium pricing spreads. For New Entrants and Emerging Players: Lead with liquid concentrate formats targeting craft kombucha and functional soda producers in Copenhagen and Melbourne through specialized e-procurement platforms. Target India's Mumbai and Bangalore production clusters where FSSAI clean-label guidelines create demand for cost-optimized natural systems. Deploy direct-to-craft distribution to bypass traditional ingredient intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flavor-clouding synergy platforms that bundle taste modulation with turbidity control. The 5-10 year viability window favors agricultural origination advantages securing consistent feedstock for hydrocolloid-dependent systems. Monitor EFSA additive prohibition enforcement as inflection indicator for natural substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Extraction | Kerry Group leverages captive Mediterranean streams to secure natural clouding feedstock against harvest volatility. |
| Flavor-Clouding Synergy Platform | Givaudan bundles taste modulation with turbidity control to displace discrete ingredient sourcing relationships. |
| Cellulose Nanocrystal Commercialization | Bavarian premium beverage manufacturers pilot plant-derived colloids to eliminate heat-processing cost barriers. |
| Direct-to-Craft Distribution Channel | Liquid concentrate formats bypass traditional distributors to reach Brooklyn and Portland small-batch producers. |
| Multi-Year Extract Supply Agreement | United States contract manufacturers consolidate three-tier supplier qualification around integrated ingredient platforms. |
Study Parameters
Desk research of EFSA safety assessments, FDA color additive petitions, FSSAI guidelines, and customs trade data preceded structured interviews with beverage formulation chemists, procurement directors at multinational juice processors, technical R&D leads at hydrocolloid suppliers, and quality assurance managers at organic certification bodies. Bottom-up volume modeling triangulated against top-down expenditure analysis across natural, synthetic, and emulsifier product categories.
Variance decomposition across product type, application, end user, and form dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic beverage consumption indicators. Industry-specific forecast inputs incorporated EFSA titanium dioxide prohibition timelines and METI clean-label guidance implementation patterns.
Forecasts assume regulatory continuity in EFSA additive frameworks and FDA petition review protocols; material policy shifts would require re-modeling substitution velocity assumptions. Cell-cultured fat integration timelines and gum arabic supply disruption scenarios represent specific revision triggers. Recalibration cycles align with material shifts in clean-label certification adoption and precision fermentation technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Ellagic Acid Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
South America Food Additives Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Carob Gum Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Australia Anti Caking Market