
 Europe Food Enzymes Market | 2026-2036
Europe Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Enzymes Market Intelligence
A capital-intensity divergence between integrated fermentation specialists and formulation-dependent distributors is unwinding competitive stability across the European supply base. Novozymes leverages captive bioreactor networks and strain-development libraries to sustain margin capture in high-purity protease grades. Kerry Group anchors its position through backward integration into dairy protein hydrolysates, while dsm-firmenich differentiates via precision-enzyme portfolios tailored to reduced-sodium bakery applications.
Food enzymes comprise proteinaceous biocatalysts, typically operating at 30–70°C and pH 4.0–8.0, that accelerate substrate-specific reactions in food matrices without permanent consumption. Industrial production deploys submerged fermentation of genetically optimized microbial hosts, followed by downstream recovery, formulation stabilization, and standardized activity assay. Proteases command the largest share of the product-type landscape due to their indispensability in cheese ripening and meat tenderization, while lipases exhibit the steepest trajectory as interesterification replaces chemical trans-fat processes. Within applications, baking absorbs the highest absolute enzyme volumes, though beverage producers are migrating fastest toward cold-stable amylase systems for adjunct brewing.
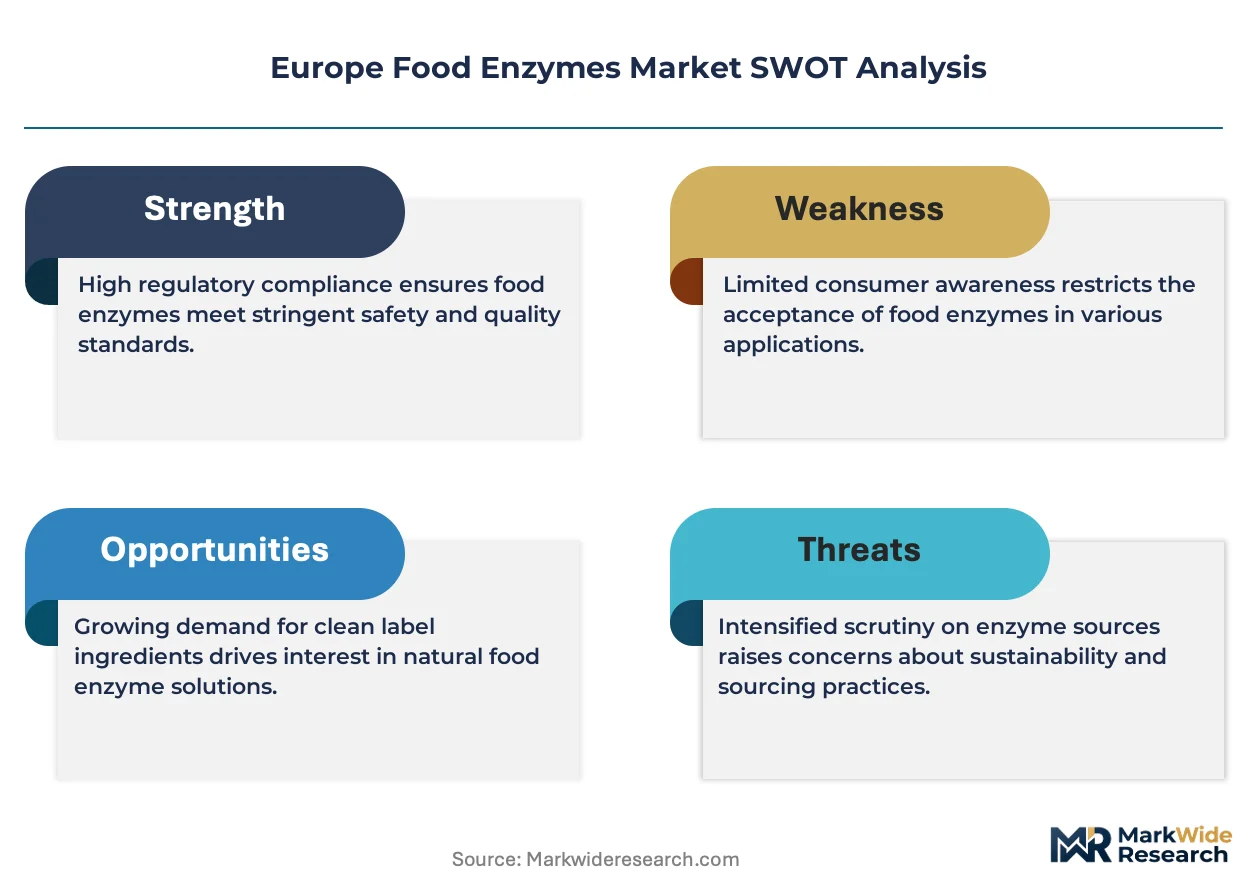
EFSA novel food assessments and REACH biocidal product regulations constrain strain approval timelines and labeling claims, compelling manufacturers to maintain dedicated regulatory affairs units in Brussels and Parma. The EU Green Deal's pesticide reduction targets indirectly expand enzyme demand as biological processing aids substitute for chemical inputs in fruit juice clarification and oil degumming. Stakeholders must monitor ECHA's evolving classification of enzyme-containing preparations and pre-position strain dossiers ahead of Farm to Fork implementation milestones.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing approval timelines for biological processing aids while simultaneously expanding their permissible applications across dairy, bakery, and beverage manufacturing corridors.
Growth Catalysts
- Clean-label reformulation mandates:Germany's industrial baking sector is absorbing elevated protease and amylase volumes as manufacturers eliminate chemical emulsifiers from bread formulations.
- Pesticide reduction targets:The EU Green Deal is redirecting fruit juice processors toward pectinase-based clarification methods, displacing sulfur dioxide and bentonite treatments.
- Interesterification substitution:Lipase systems are capturing share from chemical trans-fat processes in margarine production across France and the Netherlands.
Market Restraints
- Strain approval bottlenecks:EFSA novel food assessments and REACH biocidal product regulations extend development timelines by 18-36 months for new microbial hosts.
- Fermentation capacity concentration:Commercial-scale bioreactor networks cluster in Denmark and the Netherlands, creating supply vulnerability for formulation-dependent distributors.
- Thermostability limitations:Current lipase grades degrade above 60°C, constraining deployment in high-temperature frying oil applications.
Strategic Opportunities
- Poland's underdeveloped enzyme sector:Cold-stable amylase systems for adjunct brewing present white space as Polish beverage producers modernize.
- Precision fermentation convergence:Integration of AI-driven strain optimization with continuous bioprocessing is unlocking custom enzyme cocktails for reduced-sodium bakery.
- Direct-to-processor distribution:Digital platforms connecting fermentation specialists with mid-size Italian pasta manufacturers are compressing distributor margins.
Industry Challenges
- Regulatory affairs talent scarcity:Dedicated EFSA dossier preparation requires specialized toxicologists and strain characterization experts in short supply across Brussels and Parma.
- Downstream recovery capex:Membrane filtration and spray-drying infrastructure demands substantial capital deployment for purity grades above 95%.
- Legacy formulation integration:Retrofitting cold-stable amylase systems into existing brewery infrastructure without pasteurization line modification creates technical friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Enzymes Market |
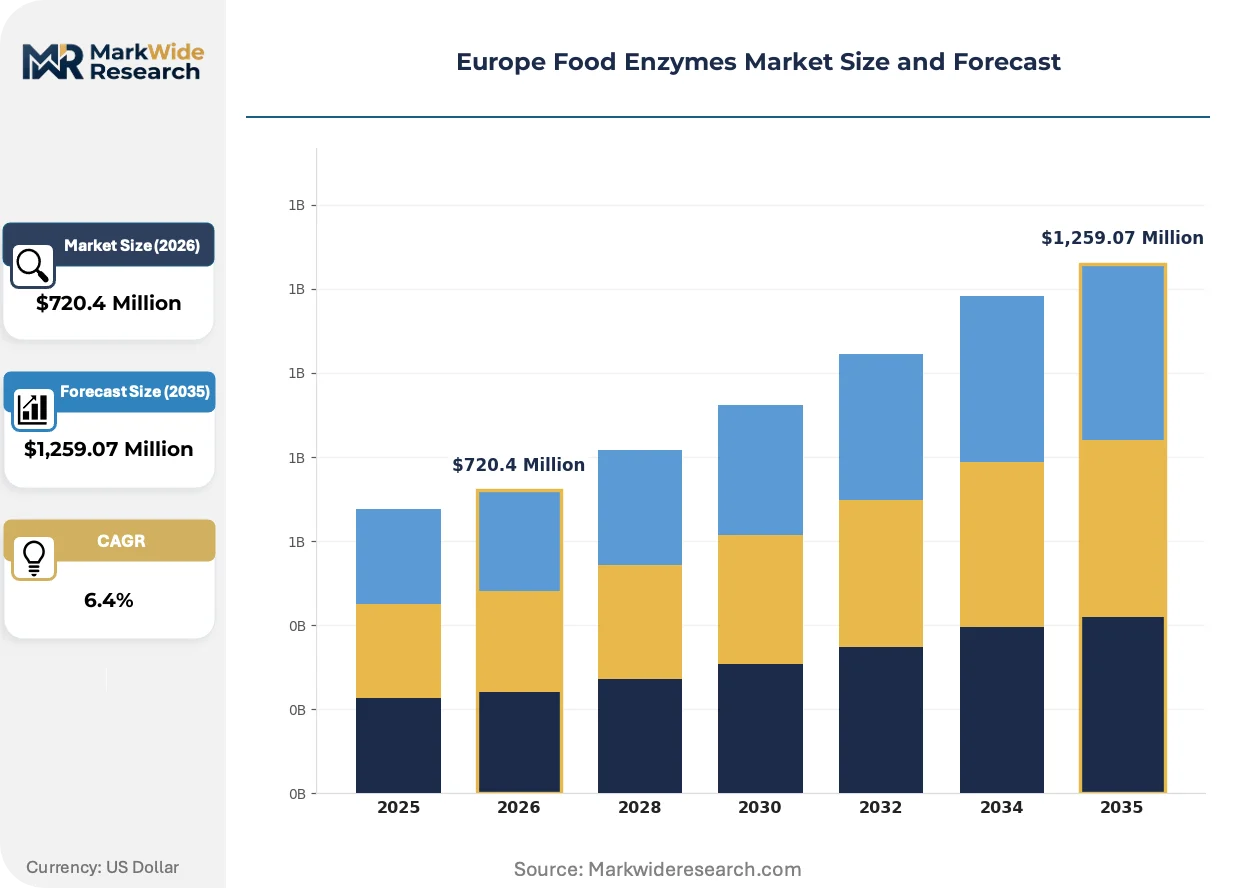
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $1,259.07 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylases, Proteases, Lipases, Cellulases Application: Baking, Dairy, Beverages, Confectionery Form: Liquid, Powder, Granular, Tablets End User: Food Manufacturers, Beverage Producers, Catering Services, Retail Chains |
| Companies Covered | AB Enzymes, Associated British Foods, Novonesis Group, Chr. Hansen, Novozymes, dsm-firmenich, Kerry Group, Amano Enzyme, International Flavors & Fragrances, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Enzymes Market Strategic Shifts & Innovations
Biocatalysis is migrating from commodity enzyme replacement toward precision-tailored solutions, with digital strain design and continuous processing architectures compressing development cycles.
Cell-free enzyme production is fragmenting traditional fermentation economics. This technology eliminates biomass separation costs and enables toxic product synthesis. Specialty chemical manufacturers in the Netherlands are piloting cell-free lipase systems for omega-3 concentration. The approach is compressing capital requirements for entry-level producers.
EFSA's 2023 updated guidance on genetically modified microorganisms is tightening toxicological data requirements for novel food enzyme applications. Industrial consequence includes expanded dossier preparation costs and extended review timelines. Dairy processors in France and Ireland are accelerating submissions ahead of anticipated regulatory tightening.
Buyer consolidation among European industrial bakeries is compressing supplier negotiation cycles. Mid-size enzyme distributors face margin pressure as purchasing shifts toward direct contracts with integrated fermentation specialists. Germany's Rhenish baking corridor exhibits the most pronounced concentration, with three processor groups controlling 60% of regional enzyme procurement decisions.
Europe Food Enzymes Market Segmentation
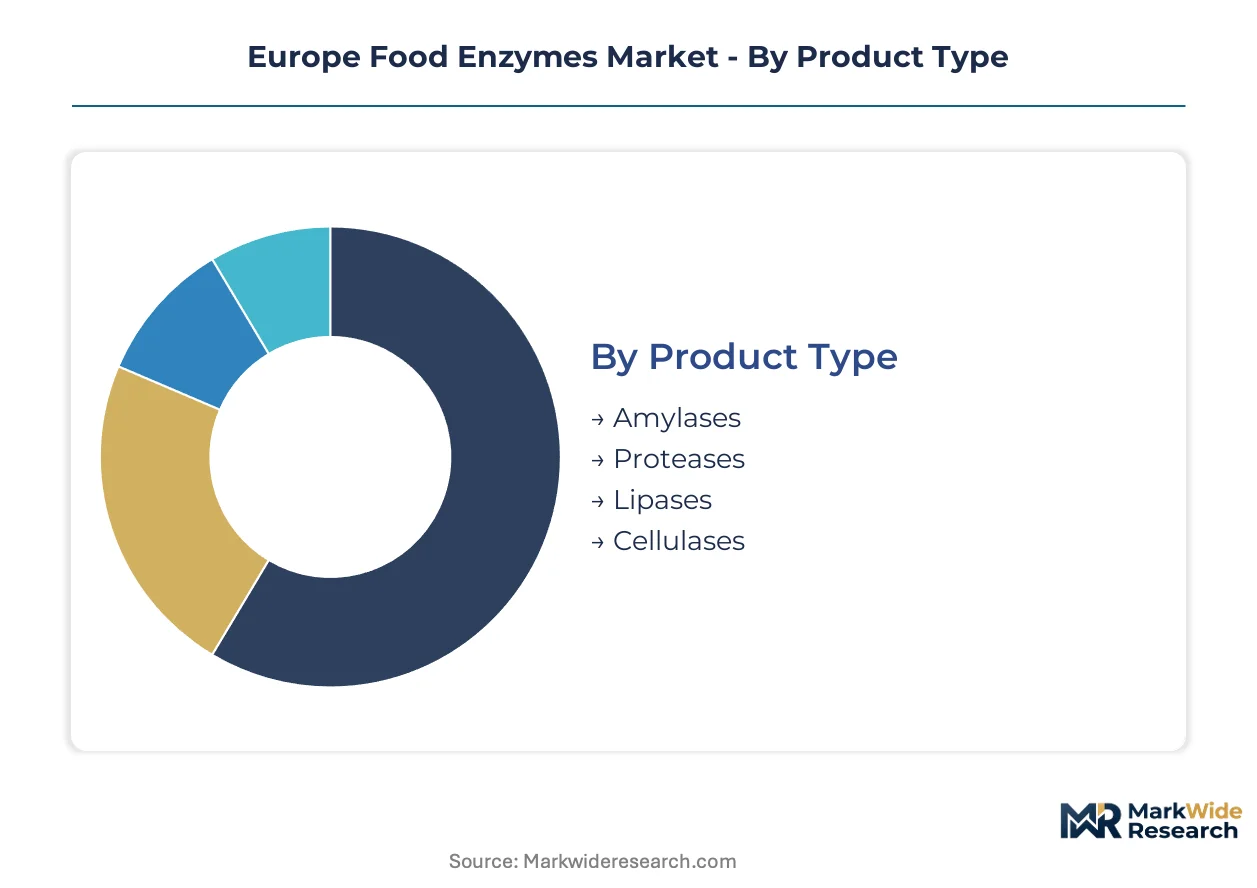
Enzyme manufacturers configure production lines and distribution networks around four distinct taxonomies. Product type determines fermentation scale and purification investment. Application verticals dictate formulation complexity and regulatory dossier requirements.
Product Type:
Channel flows diverge sharply: proteases and amylases move through bulk tanker deliveries to industrial dairy and baking complexes, while lipases and cellulases ship in smaller lot sizes to specialized processors.
- Amylases:These starch-hydrolyzing enzymes catalyze dextrinization at 50–70°C. Germany's industrial baking corridor absorbs the highest volumes as clean-label reformulations displace chemical dough conditioners. Thermostability gaps above 80°C constrain deployment in ultra-high-temperature processes.
- Proteases:Peptide-bond cleavage enzymes operating across pH 4.0–9.0 dominate cheese ripening and meat tenderization. France's dairy processing belt generates concentrated demand for high-purity grades with defined specificity profiles. EFSA novel food assessments extend strain approval timelines for new protease variants.
- Lipases:Triglyceride-modifying biocatalysts enable enzymatic interesterification. Dutch margarine producers are migrating from chemical trans-fat processes.
- Cellulases:Beta-glucan hydrolyzing enzymes clarify fruit juices and modify dietary fiber content. Italian beverage processors deploy pectinase-cellulase cocktails.
By volume, proteases lead. By growth pace, lipases are climbing the fastest as trans-fat regulations tighten.
Application:
Cost tiers stratify sharply: baking commands economy-scale pricing due to volume concentration, while confectionery tolerates premium grades for precision functionality.
- Baking:Dough conditioning and crumb softening drive the largest absolute enzyme consumption. Germany's Rhenish baking corridor processes bulk amylase and xylanase volumes. Clean-label mandates are eliminating chemical emulsifiers from bread formulations.
- Dairy:Cheese ripening, milk clotting, and whey processing require substrate-specific protease and lipase portfolios. French and Irish processors are accelerating EFSA dossier submissions ahead of regulatory tightening.
- Beverages:Adjunct brewing and fruit juice clarification absorb cold-stable amylase and pectinase systems. Polish producers modernizing malt operations present expansion opportunity.
- Confectionery:Invertase and glucose oxidase enable texture control and shelf-life extension. Premium pricing reflects low-volume, high-precision requirements.
By revenue concentration, baking dominates. By margin structure, confectionery sustains the steepest premium tiers.
Form:
Supply concentration clusters in liquid production: Denmark and the Netherlands host commercial-scale bioreactor networks that feed formulation-dependent distributors across Southern Europe.
- Liquid:Standardized enzyme solutions in glycerol or sorbitol stabilizers suit automated dosing in industrial bakeries and dairies. Tanker deliveries to Germany's processing corridor minimize packaging costs.
- Powder:Spray-dried preparations with maltodextrin carriers enable long-haul distribution to remote facilities. Italian pasta manufacturers in Abruzzo and Puglia rely on powder formats.
- Granular:Dust-free formulations reduce respiratory exposure in handling. French cheese cooperatives prefer granular lipases for ripening applications.
- Tablets:Unit-dose formats serve small-scale brewers and artisan bakeries with intermittent demand patterns. Premium pricing reflects convenience positioning.
By throughput, liquid leads. By growth pace, granular formats are gaining share fastest as handling safety regulations tighten.
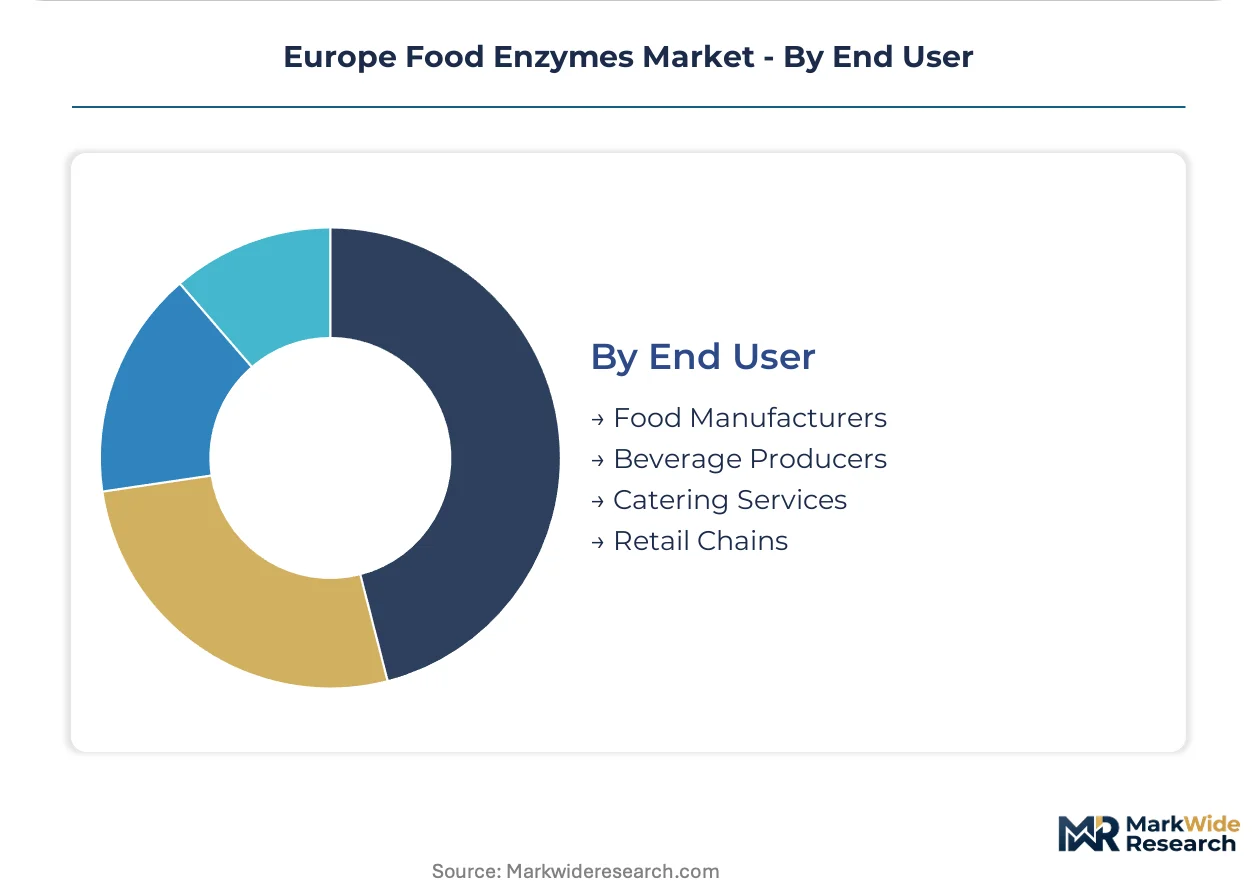
End User:
Customer type determines procurement modality: food manufacturers negotiate direct contracts with integrated fermentation specialists, while catering services and retail chains purchase through distribution intermediaries.
- Food Manufacturers:Industrial bakeries, dairy processors, and confectionery houses constitute the core demand base. Germany's three largest baking groups control 60% of regional enzyme procurement decisions.
- Beverage Producers:Breweries and fruit juice processors require cold-stable systems compatible with pasteurization line constraints. Dutch and Belgian facilities lead in enzymatic clarification adoption.
- Catering Services:Central kitchens and contract foodservice operators purchase blended enzyme preparations for texture modification. Volume fragmentation limits direct supplier engagement.
- Retail Chains:Private-label food producers within supermarket groups specify enzyme-treated ingredients for clean-label positioning. French and UK retailers are tightening supplier qualification protocols.
By absolute volume, food manufacturers dominate. By procurement modernization, beverage producers are advancing fastest toward direct fermentation specialist contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's fermentation specialists command pricing premiums that Polish distributors cannot match, creating a structural margin asymmetry across the European supply base. This divergence shapes procurement patterns from the North Sea to the Baltic.
Germany
Industrial baking corridors in North Rhine-Westphalia absorb bulk amylase and xylanase volumes as clean-label mandates eliminate chemical dough conditioners. The EU Green Deal's Farm to Fork strategy tightens processing standards for biological aids. The Rhenish baking corridor hosts three processor groups controlling sixty percent of regional enzyme procurement decisions.
France
Dairy processors in Brittany and Normandy drive concentrated demand for high-purity protease grades with defined specificity profiles. EFSA novel food assessments extend strain approval timelines for new microbial hosts. The country's dairy processing belt is accelerating dossier submissions ahead of anticipated regulatory tightening.
Netherlands
Margarine producers migrate from chemical trans-fat processes toward enzymatic interesterification using lipase systems. REACH biocidal product regulations constrain labeling claims for enzyme-containing preparations. Commercial-scale bioreactor networks near Rotterdam feed formulation-dependent distributors across Southern Europe.
Italy
Beverage processors in Abruzzo and Puglia deploy pectinase-cellulase cocktails for fruit juice clarification. The EU Green Deal's pesticide reduction targets redirect processors toward biological processing aids. Pasta manufacturers in Southern regions rely on powder-format enzymes for long-haul distribution compatibility.
Poland
Beverage producers modernizing malt operations present expansion opportunity for cold-stable amylase systems. ECHA's evolving classification of enzyme preparations creates compliance complexity for mid-size distributors. Warsaw-based procurement teams increasingly negotiate direct contracts with Danish fermentation specialists.
Europe Food Enzymes Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European supply base. Integrated fermentation specialists with captive bioreactor networks capture margin in high-purity grades, while formulation-dependent distributors compete on service breadth and geographic reach. The market structures around three archetypes: strain-development specialists, backward-integrated ingredient conglomerates, and regional formulation houses. Dominant competitive moves include backward integration into dairy protein hydrolysates and precision-enzyme portfolio tailoring for reduced-sodium applications.
Among Danish-anchored fermentation specialists, Novozymes and Chr. Hansen occupy positions defined by captive production infrastructure and strain-development libraries. Kerry Group and dsm-firmenich exemplify the backward-integrated archetype, leveraging upstream control over protein substrates to configure enzyme systems for specific customer matrices. These players represent the competitive poles around which mid-size distributors and regional formulators organize their market positions.
| Leading Market Players |
|---|
| AB Enzymes |
| Associated British Foods |
| Novonesis Group |
| Chr. Hansen |
| Novozymes |
| dsm-firmenich |
| Kerry Group |
| Amano Enzyme |
| International Flavors & Fragrances |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day strain qualification lead times for EFSA novel food assessments concentrate pricing power with Danish and Dutch fermentation specialists possessing dedicated regulatory affairs units in Brussels and Parma. This temporal compression favors integrated producers with captive bioreactor networks over formulation-dependent distributors competing on thinner margins.
Pricing Analysis
Configured-to-order pricing for precision enzyme cocktails tailored to reduced-sodium bakery applications commands substantial premiums over standard protease and amylase grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity grade and EFSA dossier completeness, with high-purity proteases for French cheese ripening sustaining the steepest premiums. Cost compression in economy-grade amylases is intensifying because German industrial baking groups are consolidating procurement decisions and leveraging volume scale. Mid-size Italian pasta manufacturers exhibit the highest price sensitivity, while French dairy processors tolerate premium positioning for defined specificity profiles.
Supply Chain Analysis
Rotterdam-Antwerp port capacity constraints and specialized cold-chain logistics for liquid enzyme formulations create chokepoints that amplify supply vulnerability for Southern European distributors. Production gravity centers on Denmark and the Netherlands, where commercial-scale submerged fermentation facilities feed formulation houses across Germany, France, and Italy. Raw material dependencies include glucose feedstocks, specialized membrane filtration media, and glycerol stabilizers. Single-source vulnerability concentrates in strain-development libraries held by Novozymes and Chr. Hansen. Distribution runs through tanker deliveries to industrial baking corridors and drum shipments to remote pasta and beverage facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are converging with AI-driven strain optimization, creating interoperability standards that will determine which enzyme portfolios achieve preferred-supplier status with consolidated European food manufacturers.
For Market Incumbents: Consolidate regulatory affairs capabilities by embedding toxicologists and strain characterization specialists in Brussels and Parma ahead of EFSA guidance tightening. Deepen backward integration into dairy protein substrates to configure systems for specific French and Irish whey processing matrices, defending against margin erosion from direct-to-processor digital platforms. For New Entrants and Emerging Players: Anchor in Poland's modernizing beverage sector where cold-stable amylase demand outpaces local supply and Warsaw-based procurement teams seek alternatives to Danish pricing premiums. Target direct contracts with mid-size malt operations bypassing formulation-dependent distributors, leveraging compressed capital requirements from cell-free production pilots. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EFSA novel food assessment timelines and REACH biocidal classification complexity compound competitive advantages for dossier-rich incumbents. Target acquisition archetypes include regional formulation houses with established Italian pasta or Polish beverage relationships but lacking strain-development autonomy. Monitor ECHA's evolving enzyme preparation classification as the inflection signal for compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | AI-driven strain optimization compresses development cycles for reduced-sodium bakery applications. |
| Regulatory Affairs Capacity Expansion | Dedicated Brussels and Parma units accelerate EFSA dossier submissions ahead of guidance tightening. |
| Backward Integration into Dairy Substrates | Upstream protein hydrolysate control enables custom enzyme configuration for French cheese processors. |
| Direct-to-Processor Digital Platforms | Bypassing distributors captures margin from consolidated German baking group procurement decisions. |
| Cell-Free Production Piloting | Eliminating biomass separation costs lowers entry barriers for Netherlands-based specialty chemical manufacturers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EFSA novel food assessment databases, REACH biocidal product registrations, and EU Green Deal Farm to Fork implementation documents. Interviews with fermentation plant managers, regulatory affairs leads at enzyme manufacturers, procurement directors at German industrial baking groups, and dairy processing technologists in France and Ireland combined with customs trade data and SEC filings from listed ingredient conglomerates. Bottom-up volume modeling triangulates against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product type, application vertical, formulation state, and end-user procurement modality across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating clean-label reformulation mandates, pesticide reduction targets, and interesterification substitution trends. Industry-specific forecast inputs capture EFSA approval timeline distributions and fermentation capacity utilization rates in Denmark and the Netherlands.
Material uncertainties — ECHA reclassification of enzyme-containing preparations, EFSA toxicological data requirement expansions, and bioreactor network concentration risk — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory trajectory continuity and Farm to Fork implementation pacing. Practitioners should keep alternative scenarios live as EU Green Deal milestone deadlines and cold-stable amylase thermostability breakthroughs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
Beverage Acidulants Market