
 Africa Microbial Food Culture Market | 2026-2036
Africa Microbial Food Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Microbial Food Culture Market Outlook
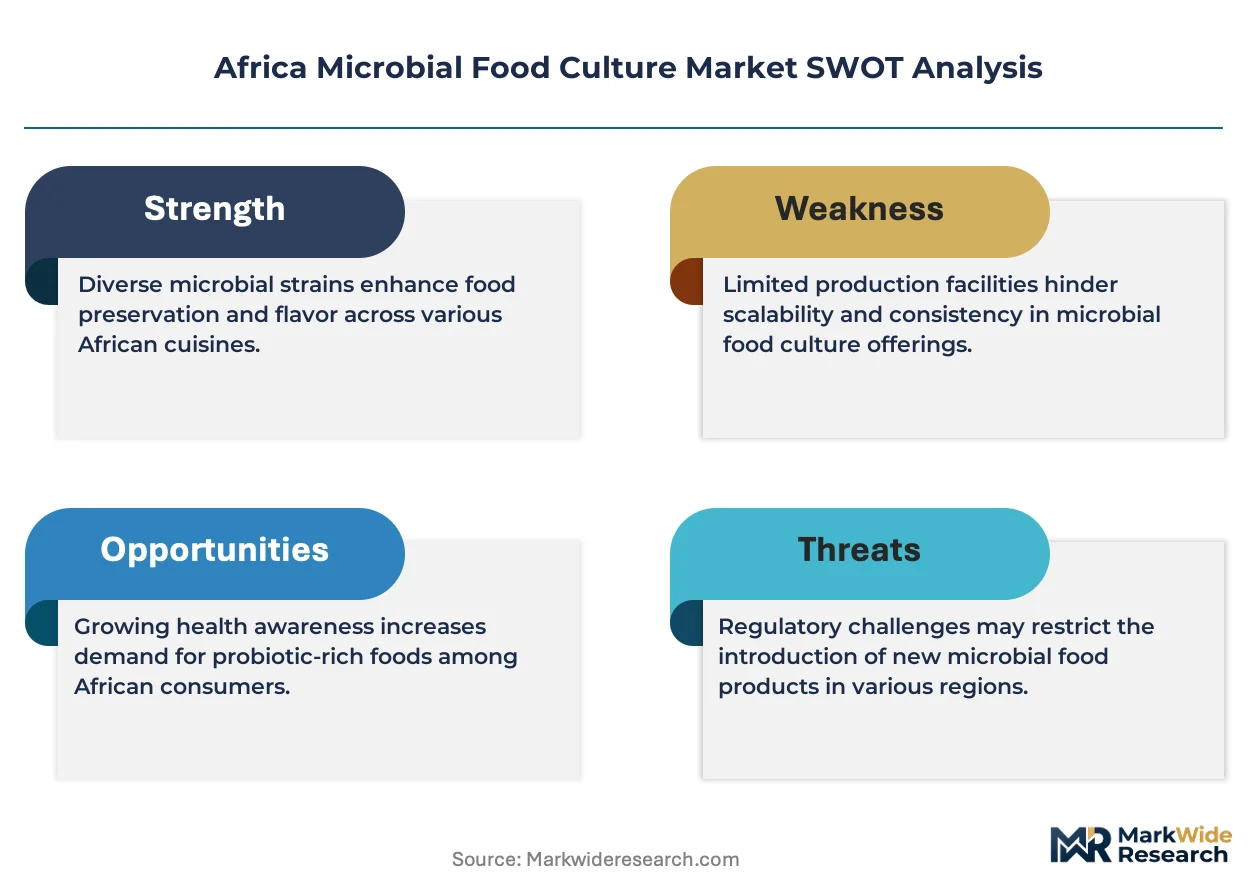
The gap between premium probiotic strains and commodity starter cultures is broadening across African food processing. Chr. Hansen Holding AS leverages its strain library to dominate high-value fermented dairy in North Africa. Lallemand Inc. anchors its position through yeast specialization for industrial bread production in Sub-Saharan hubs. DuPont competes on probiotic R&D intensity, targeting food production companies seeking clinically validated strains.
Africa microbial food culture comprises live microorganisms—primarily lactic acid bacteria, yeasts, and molds—cultivated under controlled fermentation conditions to inoculate food matrices, with cell counts typically ranging from 10^6 to 10^9 CFU per gram of finished product. These cultures acidify substrates, develop organoleptic profiles, and extend shelf life in commercial food manufacturing. Lactic acid bacteria and yeast together command the structural center of the market, while probiotic strains capture expanding margin pools as health claims gain regulatory traction. Fermented dairy remains the volume anchor, though fermented beverages show the steepest trajectory as urban consumers diversify beyond traditional fermented milk.
South Africa's Department of Health enforces CODEX-aligned standards for live culture viability and labeling, while Nigeria's National Agency for Food and Drug Administration and Control regulates import permits for industrial starter cultures. These frameworks elevate compliance costs for smaller suppliers but create structured pathways for certified producers to access formal retail channels. Stakeholders must monitor evolving strain-specific approval protocols and build regulatory dossiers before scaling across multiple African jurisdictions.
Market Dynamics
CODEX-aligned viability standards from South Africa's Department of Health are compressing import pathways for live cultures, forcing suppliers to rebuild certification dossiers while Nigerian yogurt manufacturers scale fermentation capacity to capture formal retail shelf space.
Growth Catalysts
- Fermented Dairy Expansion:East African processing cooperatives are scaling lactic acid bacteria inoculation systems to supply urban yogurt demand. Ethiopian and Kenyan dairy hubs anchor this trajectory.
- CODEX-Aligned Standards:South Africa's Department of Health protocols create structured import channels for certified live culture suppliers. Compliance investments unlock formal retail distribution.
- Cell Banking Infrastructure:Regional fermentation facilities are deploying controlled-temperature propagation systems. Nigerian cheese corridors and Ghanaian dairy clusters drive equipment deployment.
Market Restraints
- Starter Culture Import Concentration:Industrial-scale live cultures concentrate through European suppliers. African processors face currency volatility and extended lead times for strain replenishment.
- Cold Chain Fragmentation:Viability losses during last-mile distribution degrade culture performance. Temperature excursions in Nigerian and Kenyan logistics networks compress effective shelf life.
- Strain Registration Timelines:Nigeria's National Agency for Food and Drug Administration and Control mandates extended safety dossiers for novel probiotic introductions. Approval cycles stretch 18-24 months.
Strategic Opportunities
- Ethiopian Fermented Beverage White Space:Traditional tella and tej producers lack standardized inoculation systems. Industrial yeast suppliers can capture this artisan-to-formal transition.
- West African Cheese Manufacturing:Nigerian and Ghanaian dairy processors seek mesophilic starter cultures for continental cheese varieties. Localized strain adaptation offers margin capture.
- Regional Cell Banking Hubs:South African fermentation infrastructure can supply neighboring markets. CODEX certification creates export legitimacy into SADC member states.
Industry Challenges
- Phage Contamination Control:Dairy processors lack in-house microbiological screening capacity. Virulent bacteriophage outbreaks halt production lines and destroy culture inventories.
- Strain Characterization Capacity:Genomic identification of proprietary cultures requires equipment investments beyond mid-scale processor budgets. Service laboratory access concentrates in Johannesburg and Lagos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Microbial Food Culture Market |
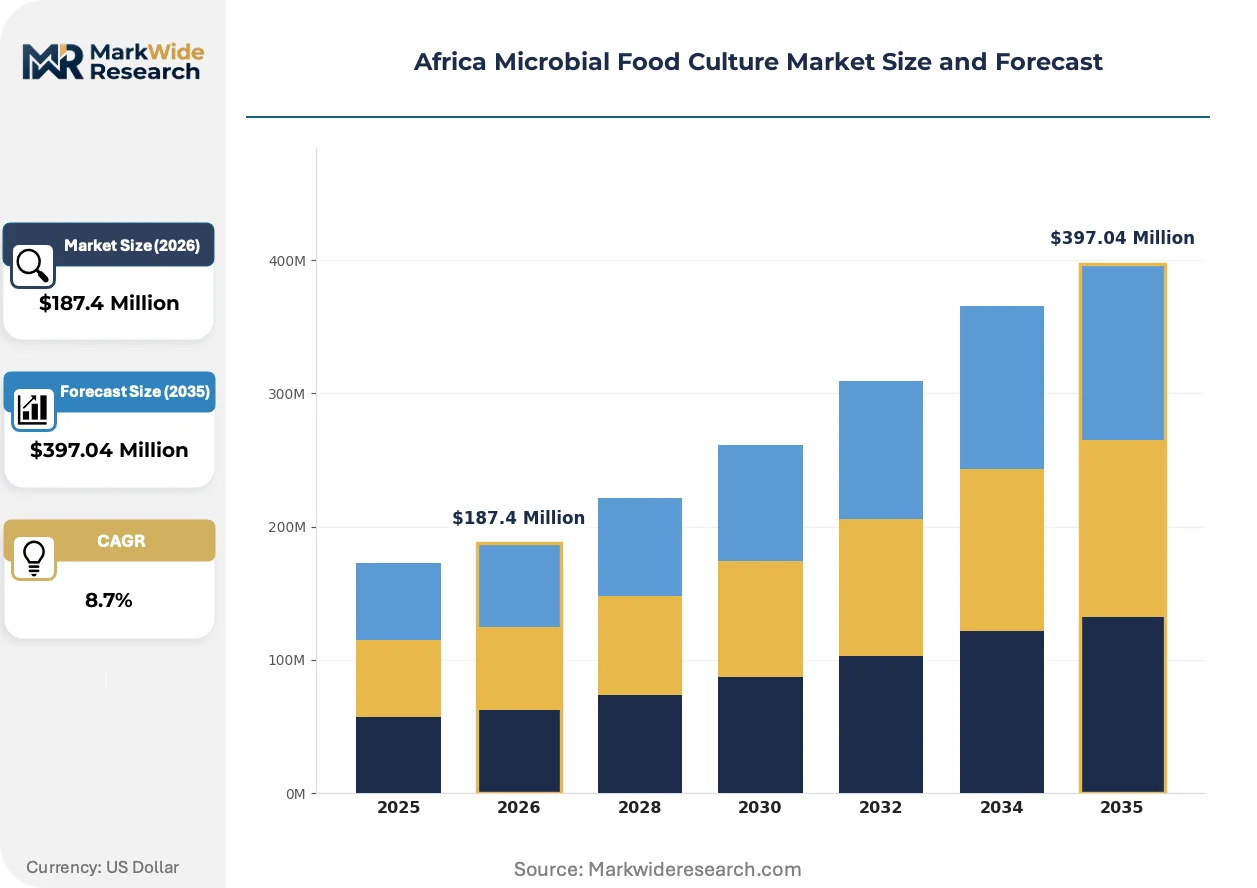
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermented Dairy, Fermented Vegetables, Fermented Beverages, Bread Microorganism Type: Lactic Acid Bacteria, Yeast, Molds, Probiotic Strains Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Farmer's Markets End User: Households, Restaurants, Food Production Companies, Caterers |
| Companies Covered | Chr. Hansen Holding AS, Lallemand Inc., Lake International Technologies, Protex International (Bioprox), LB Bulgaricum, Lyo-San Inc., Danone Group, KRBL Limited, DuPont, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Microbial Food Culture Market Strategic Shifts
Freeze-dried culture formats and precision fermentation controls are compressing the viability gap between artisan and industrial production, while regulatory strain registration requirements reshape competitive access.
Lyophilized direct-vat inoculation systems are rewriting distribution economics for live cultures. Nigerian yogurt manufacturers are adopting these formats to bypass on-site propagation infrastructure. The technology compresses working capital requirements and reduces phage exposure points across fermentation operations.
South Africa's Department of Health has aligned domestic standards with CODEX guidelines for live culture viability claims and labeling disclosures. Industrial starter culture imports now require documented cell count stability across declared shelf life. Nigerian processors are restructuring supplier qualification protocols to preempt registration delays.
Urban African consumers are rotating consumption toward functional fermented beverages beyond traditional dairy matrices. Kenyan and Nigerian beverage startups seek yeast and bacterial consortia for kombucha and water kefir production. This pivot strains existing supplier portfolios optimized for dairy-focused strain libraries.
Africa Microbial Food Culture Market Segmentation
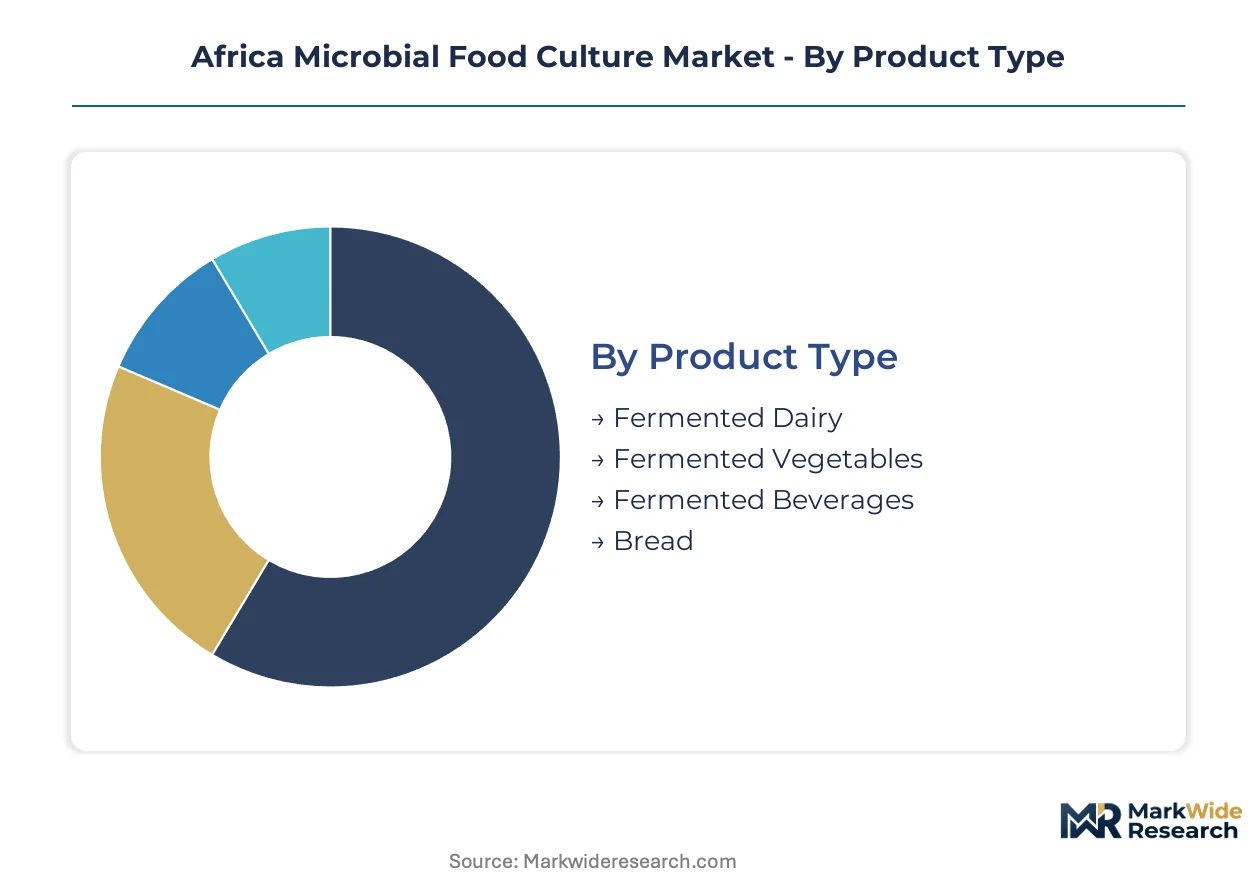
Microbial food culture demand in Africa fragments across production scales and application matrices. Each segment carries distinct technical specifications, cold chain requirements, and regulatory exposure that reshape supplier positioning.
Product Type:
Standalone fermentation applications dominate industrial procurement, while embedded culture systems penetrate artisan and household segments through pre-inoculated substrates.
- Fermented Dairy:Lactic acid bacteria and thermophilic starter consortia acidify milk matrices for yogurt and cheese production. Nigerian and Kenyan dairy processors anchor demand, scaling direct-vat inoculation to supply formal retail channels. CODEX-aligned viability standards from South Africa's Department of Health compress import pathways for uncertified suppliers.
- Fermented Beverages:Yeast and bacterial consortia drive kombucha, water kefir, and traditional tella production. Urban Kenyan and Nigerian beverage startups seek clinically validated strains to support functional health claims. This segment strains existing supplier portfolios optimized for dairy-focused libraries.
- Fermented Vegetables:Lactobacillus plantarum and Leuconostoc mesenteroides inoculants standardize sauerkraut and kimchi production for African processing hubs.
- Bread:Saccharomyces cerevisiae strains optimize industrial and artisan baking across Sub-Saharan urban centers.
Fermented dairy leads volumes today; fermented beverages are gaining share fastest.
Microorganism Type:
Cost tiers separate commodity starter cultures from premium probiotic strains, with margin structures diverging sharply across regulatory complexity and clinical validation requirements.
- Lactic Acid Bacteria:Streptococcus thermophilus and Lactobacillus delbrueckii subsp. bulgaricus constitute the technical backbone of African fermented dairy. East African processing cooperatives deploy these consortia in thermophilic yogurt systems.
- Yeast:Saccharomyces and non-Saccharomyces genera drive bread, beer, and emerging beverage applications. Industrial propagation facilities in Lagos and Johannesburg concentrate supply.
- Molds:Penicillium roqueforti and Penicillium camemberti enable blue and soft-ripened cheese varieties for nascent Nigerian and Ghanaian manufacturing corridors.
- Probiotic Strains:Lactobacillus rhamnosus GG and Bifidobacterium animalis subsp. lactis BB-12 command premium positioning through documented health outcomes. Nigeria's National Agency for Food and Drug Administration and Control mandates 18-24 month safety dossiers, compressing competitive entry.
Lactic acid bacteria and yeast together anchor volume; probiotic strains capture expanding margin pools.
Distribution Channel:
Channel selection reflects end-user technical sophistication and cold chain access, with formal retail requiring CODEX-compliant documentation that informal channels bypass.
- Supermarkets:Formal retail chains in South Africa and Nigeria stock lyophilized cultures with documented viability claims. Shelf-space allocation favors suppliers with strain registration completion.
- Online Retailers:E-commerce platforms aggregate fragmented demand from artisan producers and household fermenters. Temperature-controlled last-mile logistics remain underdeveloped outside Johannesburg and Lagos.
- Specialty Stores:Dedicated fermentation supply outlets serve commercial bakeries and dairy processors in Nairobi, Accra, and Cape Town.
- Farmer's Markets:Direct producer-to-consumer channels distribute artisan cultures with minimal regulatory oversight, concentrating in traditional fermentation strongholds.
Supermarkets dominate value capture; online retailers are expanding most quickly as urban logistics mature.
End User:
Customer type determines batch scale, technical support requirements, and sensitivity to unit economics, with industrial processors driving volume and households diversifying application matrices.
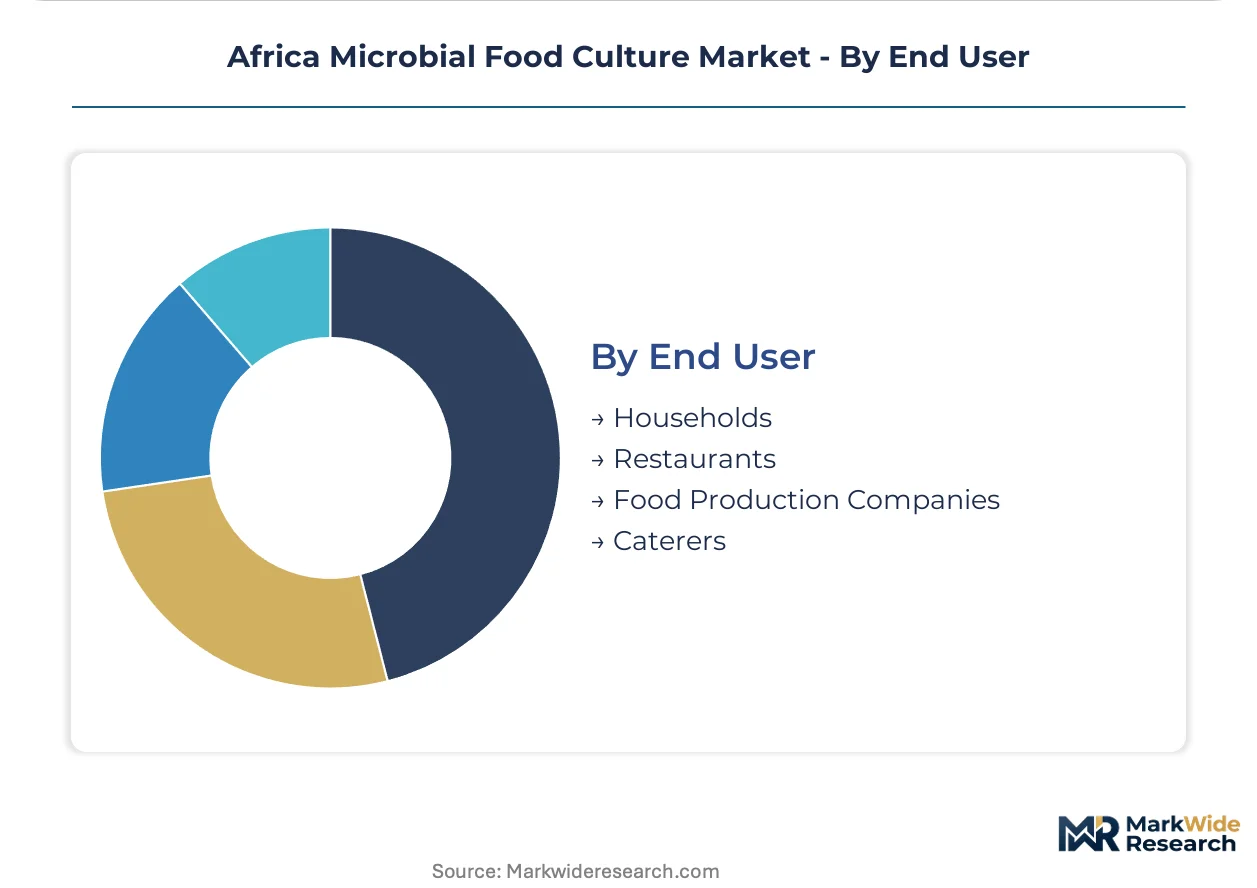
- Food Production Companies:Industrial dairy, bakery, and beverage manufacturers procure bulk cultures with technical service agreements. Nigerian cheese corridors and Ethiopian fermented beverage startups anchor this segment's growth trajectory.
- Households:Home fermenters purchase small-format cultures for yogurt, kombucha, and sourdough production. Urban middle-class expansion in Nairobi and Lagos drives demand.
- Restaurants:Foodservice operators seek consistent fermentation outcomes for menu differentiation in premium urban dining.
- Caterers:Event and institutional food providers deploy cultures for traditional fermented dishes at scale.
Food production companies command volume; households show the steepest expansion trajectory as DIY fermentation gains urban traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation technicians concentrate in South Africa's Gauteng province and Nigeria's Lagos industrial corridor, anchoring technical service capacity for live culture propagation across the continent.
South Africa
Johannesburg-based dairy processors deploy thermophilic starter consortia for industrial yogurt production. The Department of Health enforces CODEX-aligned viability standards that compress import pathways for uncertified suppliers. Cape Town fermentation facilities supply neighboring SADC markets with certified cell banking infrastructure.
Nigeria
Lagos cheese manufacturers scale mesophilic culture inoculation systems to capture formal retail shelf space. The National Agency for Food and Drug Administration and Control mandates 18-24 month safety dossiers for novel probiotic strain registration. Kano dairy corridors drive equipment deployment for controlled-temperature propagation systems.
Kenya
Nairobi processing cooperatives expand lactic acid bacteria inoculation capacity to supply urban yogurt demand. Kenya Bureau of Standards regulates live culture import documentation and labeling disclosures. The Rift Valley dairy belt anchors East African fermentation infrastructure expansion.
Ethiopia
Addis Ababa beverage startups seek standardized yeast inoculation systems for traditional tella and tej production. The Ethiopian Food and Drug Authority oversees strain safety assessments for industrial fermentation applications. Hawassa industrial park hosts emerging dairy processing clusters requiring technical culture support.
Ghana
Accra dairy processors import mesophilic starter cultures for continental cheese variety production. The Food and Drugs Authority enforces registration requirements for industrial live culture imports. Tema manufacturing zones concentrate equipment deployment for fermentation capacity scaling.
Africa Microbial Food Culture Market Competitive Environment
Top-tier vendors anchor strain library dominance, while regional distributors and specialty propagators occupy service-intensive niches. The market structures around three tiers: multinational culture houses with genomic capabilities, regional fermentation specialists with cold chain logistics, and artisan suppliers serving household fermenters. Strategic moves concentrate on regulatory dossier completion for strain registration and lyophilized format deployment to bypass on-site propagation infrastructure.
Among Denmark-based culture houses, Chr. Hansen Holding AS exemplifies premium strain library positioning, while Lallemand Inc. represents yeast specialization for industrial bread and beverage applications. DuPont occupies a position within the probiotic R&D-intensive archetype, targeting clinically validated strain demand from formal food manufacturers.
| Leading Market Players |
|---|
| Chr. Hansen Holding AS |
| Lallemand Inc. |
| Lake International Technologies |
| Protex International (Bioprox) |
| LB Bulgaricum |
| Lyo-San Inc. |
| Danone Group |
| KRBL Limited |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Nigerian yogurt manufacturers and East African dairy cooperatives concentrate procurement volume, anchoring a contract-based long-term offtake model where technical service bundling commands premium positioning over commodity starter culture spot purchases.
Pricing Analysis
Technical service bundling versus unbundled culture supply splits the market into divergent cost structures. Three-tier pricing structure across premium, standard, and economy levels separates probiotic strains with clinical dossiers from commodity lactic acid bacteria and generic yeast formats. Price differentiation rests on CODEX certification status and cold chain integrity guarantees. Cost compression in economy-tier starter cultures is intensifying because currency volatility erodes African processor purchasing power against European suppliers. Artisan bakeries and household fermenters exhibit highest price sensitivity; formal dairy manufacturers with technical service agreements show lowest.
Supply Chain Analysis
Regional distribution centers in Johannesburg and Lagos operate hub-and-spoke patterns for lyophilized culture formats, while ambient-temperature last-mile networks struggle with viability preservation. Supply concentrates in Denmark, France, and Canada for industrial starter cultures, with South African cell banking hubs emerging as secondary propagation points. Raw material dependencies span strain library access, freeze-drying equipment, and pharmaceutical-grade cryoprotectants. Single-source vulnerability runs through European culture houses for proprietary probiotic strains. Distribution runs through formal import channels with CODEX documentation requirements, though informal artisan supply bypasses regulatory checkpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where South African CODEX certification investments unlock premium pricing in Nigerian formal retail channels despite equivalent production costs.
For Market Incumbents: Deepen backward integration into regional cell banking infrastructure to reduce strain replenishment lead times and phage contamination exposure. Anchor capacity addition in Gauteng province to supply SADC markets with certified propagation services. Defend margin position by completing regulatory dossiers for novel probiotic strains before Nigerian NAFDAC registration timelines compress competitive entry windows.
For New Entrants and Emerging Players: Launch via direct-vat inoculation format specialization to bypass on-site propagation infrastructure requirements that constrain artisan dairy processors. Target Ethiopian tella and tej beverage startups as the most penetrable segment, where standardized yeast inoculation systems remain undeveloped. Pursue white-space capture in West African cheese manufacturing corridors through mesophilic starter culture adaptation for continental varieties.
For Investors and Strategic Acquirers: Regional fermentation specialists with cold chain logistics capabilities are the most active acquirer category in this space, consolidating service-intensive niches. Five-to-ten year viability hinges on regulatory dossier completion rates across multiple African jurisdictions. Monitor Nigerian NAFDAC strain registration approval velocity as the critical inflection signal for probiotic margin pool expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilized Format Deployment | Nigerian yogurt manufacturers bypass propagation infrastructure, compressing working capital requirements. |
| Regional Cell Banking Hub Establishment | South African CODEX-certified facilities supply SADC markets, reducing European import dependency. |
| Probiotic Strain Registration Investment | Completion of NAFDAC safety dossiers unlocks formal retail shelf space in Nigerian dairy corridors. |
| Traditional Beverage Inoculation System Launch | Ethiopian tella and tej producers transition from artisan to standardized fermentation controls. |
| Phage Contamination Screening Capacity Buildout | Dairy processors in Kenya and Nigeria reduce production line halt risk from virulent bacteriophage outbreaks. |
Study Parameters
Bottom-up dairy processor demand modeling reconciled against top-down live culture import tracking forms the analytical core of this study. Primary interviews with fermentation facility managers, dairy cooperative procurement leads, regulatory affairs specialists at national food safety agencies, and cold chain logistics operators combined with secondary validation. Secondary sources span CODEX Alimentarius standards documentation, South African Department of Health food safety protocols, Nigerian NAFDAC import permit records, Kenya Bureau of Standards labeling regulations, and customs trade data for starter culture shipments. Triangulation between processor-reported inoculation rates and supplier shipment volumes calibrated demand estimates.
Historical trendline analysis of fermented dairy production capacity and culture import volumes established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, microorganism category, distribution channel format, and end-user scale tier. CAGRs derived from regression analysis against dairy processing equipment deployment rates and urban consumer expenditure patterns. Industry-specific forecast inputs incorporate CODEX alignment implementation timelines and probiotic strain registration completion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended NAFDAC approval delays or severe currency devaluation episodes. Outputs reflect documented assumptions regarding cold chain infrastructure development and regulatory harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Invertase Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Global Oleate Esters Market
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Food Grade Glue Market
Food Additives and Ingredients
South America Food Stabilizers Market