
 Natural Ferulic Acid Market | 2026-2036
Natural Ferulic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
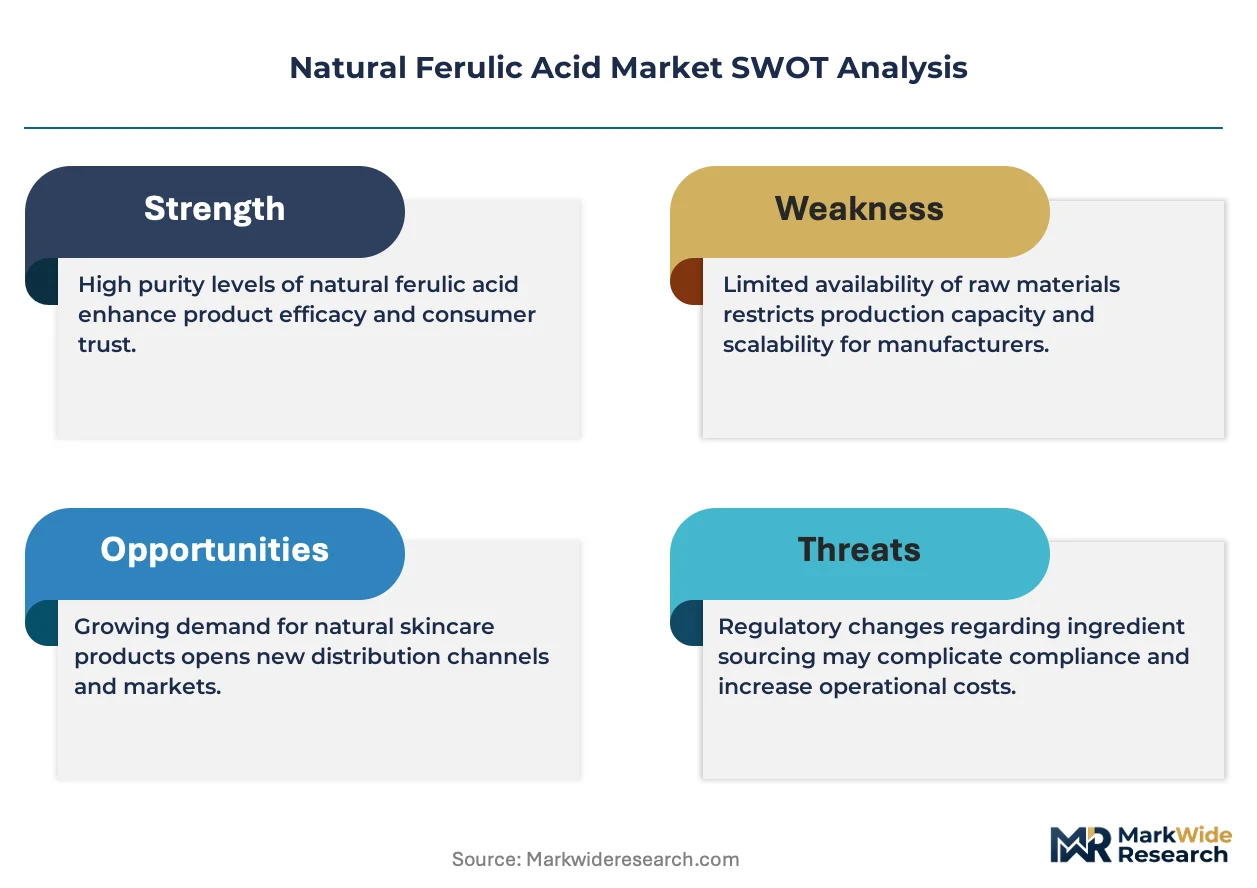
Natural Ferulic Acid Market Analysis
Chinese rice bran processors is pivoting toward higher-purity ferulic acid output to serve pharmaceutical and cosmeceutical specifications. Hunan Huacheng Biotech leverages vertical integration from rice bran sourcing to refined extraction, sustaining cost advantages in powder-grade supply. Oryza Oil & Fat Chemical dominates Japanese cosmetic ingredient channels through decades of technical collaboration with formulators. Xi'an Healthful Biotechnology specializes in liquid ferulic acid emulsions for North American skincare contract manufacturers.
Natural ferulic acid is a hydroxycinnamic acid derivative extracted primarily from rice bran, wheat bran, and corn hulls, typically standardized to 98% purity for cosmetic and pharmaceutical applications. Manufacturers deploy alkaline hydrolysis or enzymatic extraction to isolate this phenolic compound, which functions primarily as a potent antioxidant that stabilizes vitamins C and E while inhibiting melanin formation. Powder formulations occupy the largest volume share due to stability in bulk handling and compatibility with dry-blend supplement manufacturing, though liquid emulsions are gaining fastest in premium skincare for direct incorporation into water-based serums. Source-based segmentation reveals rice bran as the dominant feedstock, given its ferulic acid concentration and established supply chains across East Asia, while wheat-derived variants command margin premiums in European clean-label applications.
FDA oversight of cosmetic ingredient safety and China's SAMR registration requirements for new raw materials are elevating documentation burdens for cross-border suppliers. REACH registration in the European Union and ECHA substance evaluation protocols restrict certain solvent residues in extraction processes, favoring producers with green chemistry certifications. ISO 16128 natural origin criteria increasingly influence procurement decisions by multinational cosmetics houses. Stakeholders must monitor evolving purity standards across FDA, EMA, and NMPA jurisdictions to maintain market access and premium positioning.
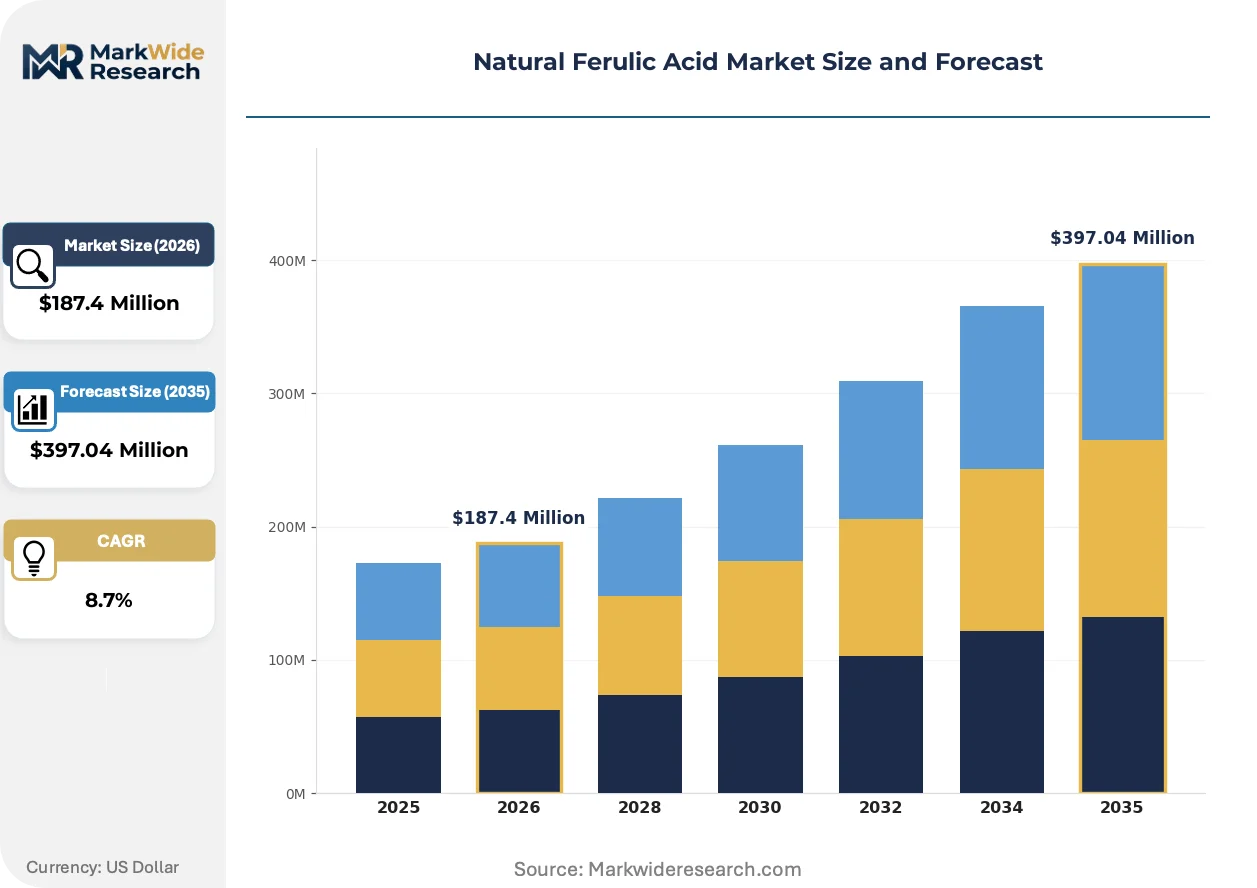
Market Dynamics
East Asian cosmetic formulators are consolidating ferulic acid procurement around vertically integrated rice bran processors, compressing spot-market liquidity and elevating purity specifications as the dominant market-shaping force.
Growth Catalysts
- Vitamin C stabilization protocols:South Korean and Japanese serum manufacturers are embedding ferulic acid into dual-antioxidant formulations, creating specification pull for 98% purity grades.
- REACH solvent residue limits:ECHA substance evaluation protocols are disqualifying extraction processes using methylene chloride, advantaging producers with enzymatic green chemistry certifications.
- Clean-label antioxidant positioning:North American skincare contract manufacturers are specifying natural-origin ferulic acid to meet ISO 16128 criteria for premium channel placement.
Market Restraints
- Rice bran supply concentration:Hunan province processors control 60% of feedstock refining capacity, creating geographic single-point vulnerability for powder-grade supply.
- Wheat bran input volatility:European milling byproduct pricing fluctuates with grain futures, compressing margin stability for wheat-derived ferulic acid specialists.
- Synthetic ferulic acid substitution:Pharmaceutical compounders in cost-sensitive markets are reverting to petroleum-derived alternatives when natural premiums exceed formulation budgets.
Strategic Opportunities
- Liquid emulsion penetration:North American contract manufacturers are adopting direct-incorporation formats to eliminate powder dissolution steps in water-based serum production.
- India cosmetic ingredient registration:CDSCO streamlined raw material pathways are opening formal supply channels previously served through informal traders.
- Dual carbon compliance positioning:China's MEE emissions tracking is creating preference for processors with verified carbon accounting in state-procurement channels.
Industry Challenges
- Cross-jurisdiction documentation burdens:Suppliers must maintain parallel FDA cosmetic ingredient safety files, REACH registration dossiers, and NMPA raw material certificates, stretching regulatory affairs capacity.
- Enzymatic extraction scale-up:Green chemistry certification requires capital-intensive bioreactor deployment that mid-tier processors cannot finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Ferulic Acid Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Emulsion End User: Cosmetics, Supplements, Food & Beverage, Pharmaceuticals Source: Rice Bran, Wheat, Corn, Sugar Beet Application: Anti-Aging, Antioxidant, Skin Repair, Dietary Enhancement |
| Companies Covered | Cayman Chemical, Hunan Huacheng Biotech, Haihang Group, Oryza Oil & Fat Chemical, Zhonglan Industry, Kingherbs Ltd., Xi'an Healthful Biotechnology, Shaanxi Guanjie Technology, Sisco Research Laboratories Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Ferulic Acid Market Emerging Trajectories
Bioprocess engineering advances and regulatory chemistry restrictions are converging to displace solvent-based extraction, while procurement consolidation among cosmetic houses is rewriting supplier qualification protocols.
Enzymatic hydrolysis using cellulase and feruloyl esterase cocktails is absorbing market share from alkaline hydrolysis routes, with Japanese cosmetic ingredient houses specifying enzyme-derived material for melanin-inhibition claims. South Korean formulators are accelerating adoption to meet MFDS cosmetic safety documentation requirements. This technology shift is compressing capital returns for legacy solvent-extraction facilities while rewarding processors with in-house enzyme production capability.
REACH Annex XVII restrictions on residual toluene and xylene are forcing extraction process redesigns across European-serving supply chains, with ECHA substance evaluation timelines extending registration maintenance costs. German cosmetic houses are requiring third-party solvent residue testing beyond regulatory minimums. Powder-grade suppliers without green chemistry certifications are losing qualified supplier status with multinational cosmetics procurement teams.
Long-term offtake contracting is displacing spot procurement in premium skincare channels, with North American contract manufacturers signing 24-36 month supply agreements specifying 98% purity and batch-level carbon footprint data. Direct processor relationships are eliminating regional distributor markups. This pattern is most visible in California and New York formulation clusters serving clean beauty retail channels.
Natural Ferulic Acid Market Segmentation
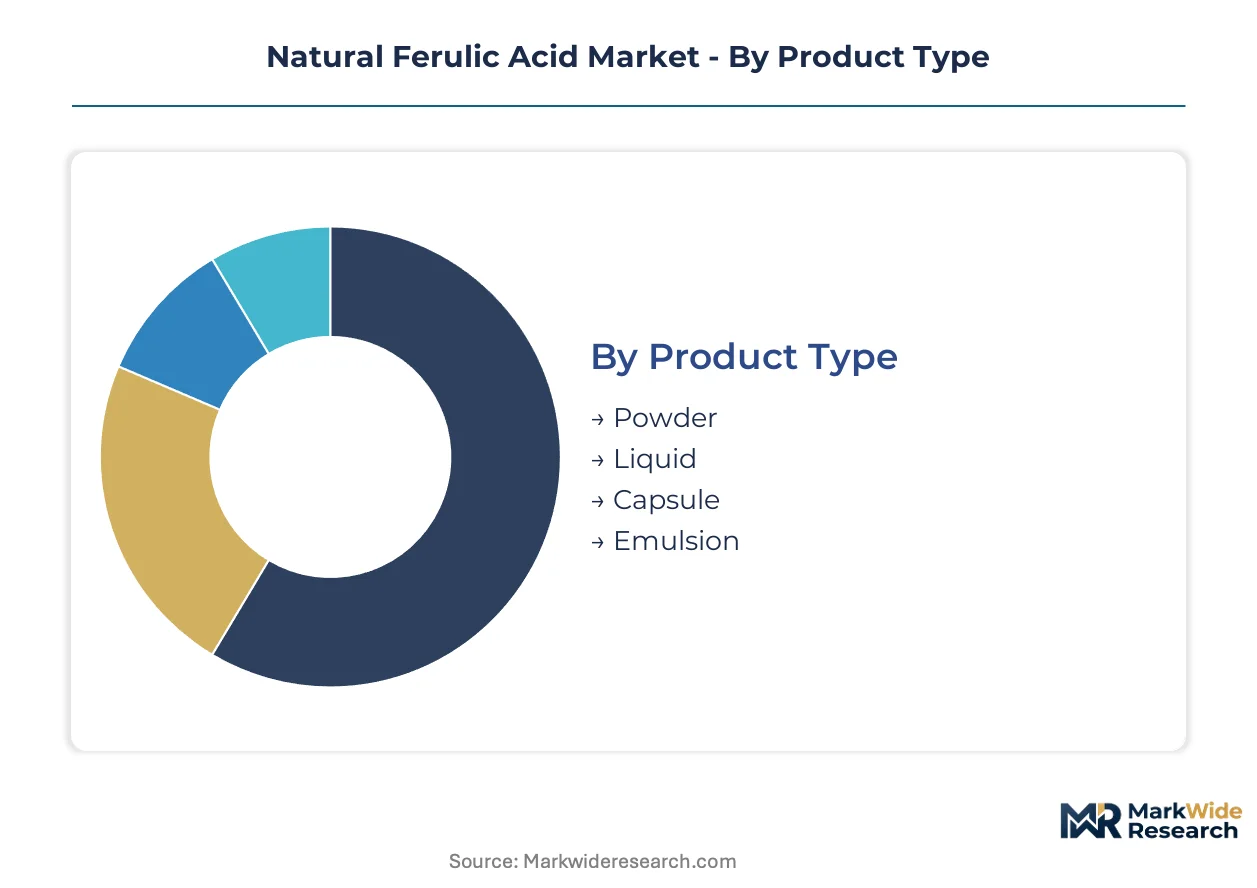
Natural ferulic acid procurement patterns diverge sharply across formulation requirements, feedstock provenance, and regulatory compliance tiers. Buyers segment supply by physical format stability, end-use purity thresholds, and extraction source traceability to align with channel-specific positioning.
Product Type:
Cosmetic compounders and supplement manufacturers select formats based on handling infrastructure and formulation integration protocols.
- Powder:Crystalline 98% purity grades dominate bulk antioxidant procurement for dry-blend supplement manufacturing and powder-in-oil cosmetic preparations. South Korean serum formulators specify micronized powder for vitamin C co-stabilization in anhydrous bases, though dissolution steps add processing overhead.
- Liquid:Pre-solubilized aqueous solutions eliminate hydration protocols in water-based serum production lines. North American contract manufacturers are adopting direct-incorporation liquid formats to compress batch cycle times in clean beauty manufacturing.
- Capsule:Encapsulated ferulic acid serves oral supplement brands requiring precise unit dosing and oxidation protection during shelf life.
- Emulsion:Lipid-dispersed formats target topical delivery systems where oil-phase compatibility and skin penetration enhancement drive specification.
Powder leads volumes today; liquid is gaining share fastest.
End User:
Downstream industries impose divergent purity benchmarks and documentation burdens that reshape supplier qualification.
- Cosmetics:MFDS-registered South Korean and Japanese formulators drive specification pull for 98% purity with batch-level solvent residue certificates. REACH-compliant enzymatic extraction is becoming a qualified supplier threshold for European cosmetics procurement teams.
- Supplements:FDA dietary ingredient notification requirements and cGMP documentation dominate North American procurement. Powder formats prevail for tablet and capsule manufacturing.
- Food & Beverage:Natural antioxidant applications in edible oils and fortified beverages require food-grade extraction solvent clearance and flavor-neutral profiles.
- Pharmaceuticals:API-grade ferulic acid for cardiovascular and neuroprotective drug candidates demands ICH Q3C residual solvent compliance and DMF-ready documentation packages.
Cosmetics commands premium positioning; pharmaceuticals shows steepest expansion trajectory.
Source:
Feedstock selection determines carbon footprint claims, supply security, and regional procurement clustering.
- Rice Bran:Dominant feedstock concentration in Hunan province processors anchors East Asian supply chains. Established alkaline and enzymatic extraction infrastructure supports cost-efficient 98% purity output for cosmetic and supplement channels.
- Wheat:European milling byproduct sourcing supports clean-label positioning in Germany and France, though grain futures volatility compresses margin predictability for wheat-derived specialists.
- Corn:North American corn hull processors serve regional supplement manufacturers with non-GMO and organic certification pathways.
- Sugar Beet:Emerging European feedstock for specialty applications where alternative phenolic profiles differentiate functional positioning.
Rice bran anchors volume concentration; wheat-derived variants capture clean-label premiums.
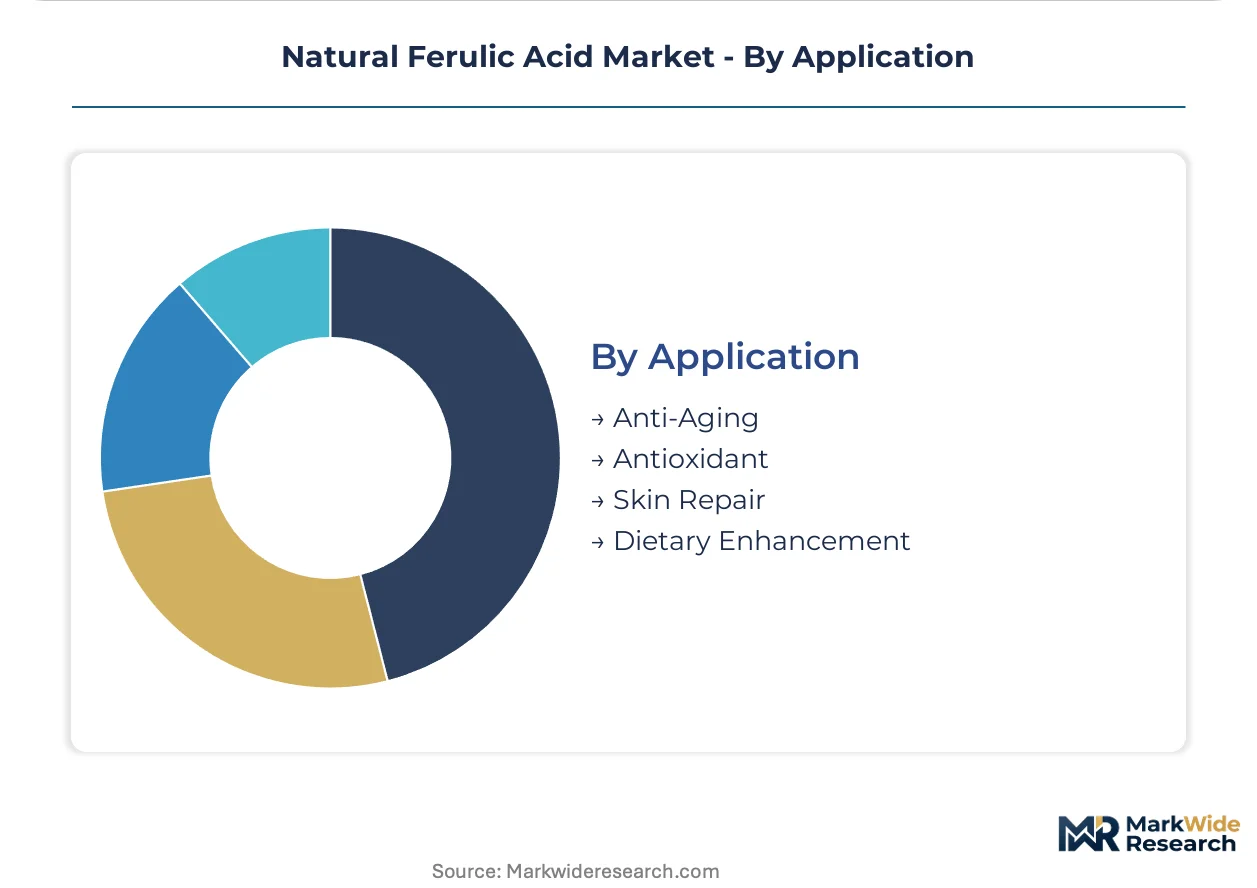
Application:
Functional positioning in finished goods dictates specification intensity and channel placement strategy.
- Anti-Aging:Dual-antioxidant serum formulations with vitamin C and E drive highest purity demand. South Korean and Japanese formulators embed ferulic acid for collagen protection claims and photodamage prevention positioning.
- Antioxidant:Broad-spectrum free radical scavenging applications span edible oils, supplements, and topical protectants. Stability in heat-processed foods distinguishes ferulic acid from ascorbate alternatives.
- Skin Repair:Barrier function and melanin inhibition claims in post-procedure skincare specify enzyme-derived material for bioactivity documentation.
- Dietary Enhancement:Metabolic health and cardiovascular support positioning in nutraceuticals requires oral bioavailability studies and GRAS or novel food regulatory clearance.
Anti-aging commands formulation premiums; dietary enhancement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting ferulic acid production toward jurisdictions with streamlined cosmetic ingredient registration, as processors seek to minimize compliance overhead while maintaining market access for premium purity grades.
China
Hunan province processors dominate rice bran feedstock refining, supplying powder-grade material to domestic and export channels. SAMR registration requirements for new cosmetic raw materials are elevating documentation standards for cross-border shipments. Changsha-based extraction clusters are upgrading enzymatic capacity to meet European green chemistry specifications.
South Korea
MFDS-registered formulators in Seoul Capital Area are embedding ferulic acid into vitamin C stabilization protocols for anti-aging serum manufacturing. The national pharmaceutical regulator mandates batch-level solvent residue certificates for cosmetic ingredient imports. Incheon and Suwon manufacturing corridors are consolidating procurement around vertically integrated rice bran suppliers.
Japan
Tokyo and Osaka cosmetic houses specify enzyme-derived ferulic acid for melanin-inhibition claims in premium skincare lines. METI industrial standards favor bioprocess extraction routes over legacy solvent methods. Chubu region technical collaboration networks between ingredient houses and formulators are tightening supplier qualification protocols.
United States
FDA cosmetic ingredient safety oversight and cGMP documentation requirements dominate procurement for North American supplement and skincare contract manufacturers. California and New York formulation clusters are adopting liquid emulsion formats to compress batch cycle times in clean beauty production. EPA emissions tracking is creating preference for processors with verified carbon accounting.
Germany
REACH Annex XVII restrictions on residual toluene and xylene are disqualifying non-compliant extraction processes from European supply chains. ECHA substance evaluation protocols extend registration maintenance costs for importers. Bavarian and North Rhine-Westphalian cosmetic houses require third-party solvent residue testing beyond regulatory minimums, advantaging enzymatic green chemistry certifications.
Natural Ferulic Acid Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue liquid emulsion formats and carbon-verified supply chains to differentiate positioning. The supplier base concentrates around rice bran processors with captive feedstock access and enzymatic extraction capability. Three archetypes dominate: vertically integrated agricultural processors, specialty biotech extractors, and regional trading houses with formulation technical support. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, as procurement teams eliminate distributor markups through direct processor relationships.
Among East Asian agricultural processors, Hunan Huacheng Biotech and Oryza Oil & Fat Chemical exemplify the vertically integrated archetype, anchoring supply security through captive rice bran sourcing. Xi'an Healthful Biotechnology occupies a position within the specialty extraction tier, representing the liquid emulsion capability that North American contract manufacturers are adopting for direct-incorporation workflows. These three entities illustrate how feedstock control and format diversification are rewriting supplier qualification protocols across cosmetic and pharmaceutical procurement channels.
| Leading Market Players |
|---|
| Cayman Chemical |
| Hunan Huacheng Biotech |
| Haihang Group |
| Oryza Oil & Fat Chemical |
| Zhonglan Industry |
| Kingherbs Ltd. |
| Xi'an Healthful Biotechnology |
| Shaanxi Guanjie Technology |
| Sisco Research Laboratories Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between enzymatic green chemistry and legacy solvent extraction manifests in parallel pricing premiums and supply chain reconfiguration toward East Asian rice bran processors with captive feedstock access. REACH-compliant enzymatic material commands substantial markups in European cosmetics procurement, while Hunan province processors leverage backward integration to undercut spot-market solvent-based alternatives.
Pricing Analysis
Distributor margin compression is accelerating as North American contract manufacturers eliminate regional trading houses through direct processor relationships. Three-tier pricing structure across premium enzymatic, standard alkaline-extracted, and economy solvent-derived grades reflects purity certification and carbon accounting documentation. Cost compression in standard powder grades is intensifying because synthetic ferulic acid substitution threats cap natural-origin premiums. Pharmaceutical compounders exhibit highest price sensitivity; premium skincare formulators show lowest.
Supply Chain Analysis
Rice bran feedstock supply rests on Hunan province processors controlling captive sourcing infrastructure across China, with secondary concentration in Japanese and South Korean cosmetic ingredient houses. Alkaline hydrolysis chemicals, enzymatic bioreactor capacity, and food-grade solvent clearance constitute critical input dependencies. Single-source vulnerability concentrates in Hunan's 60% share of powder-grade refining capacity. Distribution runs through direct long-term offtake contracts displacing spot procurement in premium channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in enzymatic extraction scale-up and liquid emulsion format penetration, where premium-tier positioning offsets bioreactor capital intensity through sustained pricing power.
For Market Incumbents: Extend enzymatic production capability to defend qualified supplier status against REACH Annex XVII solvent restrictions threatening legacy extraction assets. Deepen backward integration into rice bran sourcing to secure feedstock cost advantages against wheat-derived competitors exposed to grain futures volatility. Lock in 24-36 month offtake contracts with North American clean beauty manufacturers to eliminate distributor markups and anchor volume commitments. For New Entrants and Emerging Players: The premium-economy price-point gap in liquid emulsion formats offers white-space entry for specialty biotech extractors with direct-incorporation technical support capabilities. Target India's CDSCO-registered cosmetic ingredient channels where streamlined raw material pathways are displacing informal traders. Pursue carbon-verified supply chain positioning to capture China's state-procurement preference under MEE emissions tracking protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier processors lack bioreactor financing capacity to meet green chemistry certification thresholds. Long-term viability favors vertically integrated agricultural processors with captive feedstock and enzymatic capability over regional trading houses. Watch enzymatic extraction adoption rates in South Korean MFDS-registered formulators as inflection indicator for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Scale-Up | REACH Annex XVII compliance secures European cosmetics procurement access against solvent-based disqualification. |
| Long-term Supply Agreement | Direct processor relationships with North American contract manufacturers eliminate distributor margin layers. |
| Liquid Emulsion Format Launch | Direct-incorporation workflows compress batch cycle times in California and New York clean beauty manufacturing. |
| Carbon Accounting Certification | Verified emissions tracking aligns with China's MEE preferences in state-procurement channel placement. |
| Backward Integration into Rice Bran | Captive feedstock sourcing insulates margin stability against wheat bran futures volatility in European supply. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic formulators, rice bran processors, regulatory affairs specialists, and pharmaceutical API procurement managers with secondary validation through SAMR registration databases, REACH dossier filings, customs trade records, and MFDS cosmetic ingredient safety documentation. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates against extraction capacity disclosures and feedstock availability assessments.
Segment-weighting approaches modeled product type, end-use industry, source feedstock, and application function across the projection horizon. CAGRs were derived from trajectory fitting to historical purity-grade pricing trends and enzymatic adoption curves. Forecast inputs incorporated regulatory compliance timeline assumptions for green chemistry certification and clean beauty channel expansion patterns in North American contract manufacturing.
Caveats apply where REACH solvent restriction enforcement intensity, rice bran harvest volatility, or synthetic ferulic acid cost breakthroughs could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
Russia Food Preservatives Market
Food Additives and Ingredients
Global Organic Feed Additives Market