
 Global Human Rotavirus Vaccine Market | 2026-2036
Global Human Rotavirus Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Human Rotavirus Vaccine Market Foresight
Pricing for human rotavirus vaccines is decoupling between premium pentavalent formulations and monovalent alternatives optimized for public-sector tenders. Merck & Co., Inc. anchors the premium segment through its established RotaTeq franchise, while Bharat Biotech competes aggressively on cost with its ROTAVAC oral dose. Serum Institute of India Pvt. Ltd. leverages massive manufacturing scale to supply UNICEF procurement channels across Africa and Asia.
Human rotavirus vaccines are live attenuated or inactivated biological preparations containing G1-G4 and G9 serotype antigens, delivered orally to induce intestinal mucosal immunity against rotavirus gastroenteritis in infants. The pentavalent category dominates value pools due to complex formulation requirements and higher cold-chain infrastructure needs. Oral administration routes capture the bulk of volumes, though intranasal delivery research is intensifying as manufacturers seek thermostable alternatives that reduce distribution complexity in tropical climates.
FDA, WHO prequalification, and EMA standards collectively govern product licensure, with WHO prequalification serving as the gatekeeper for Gavi-eligible country procurement. National regulators in India and Indonesia increasingly reference WHO standards for accelerated approvals, compressing time-to-market for regional suppliers. Stakeholders must monitor evolving thermostability requirements and fractional-dosing protocols that could reshape competitive positioning in public-sector tenders.
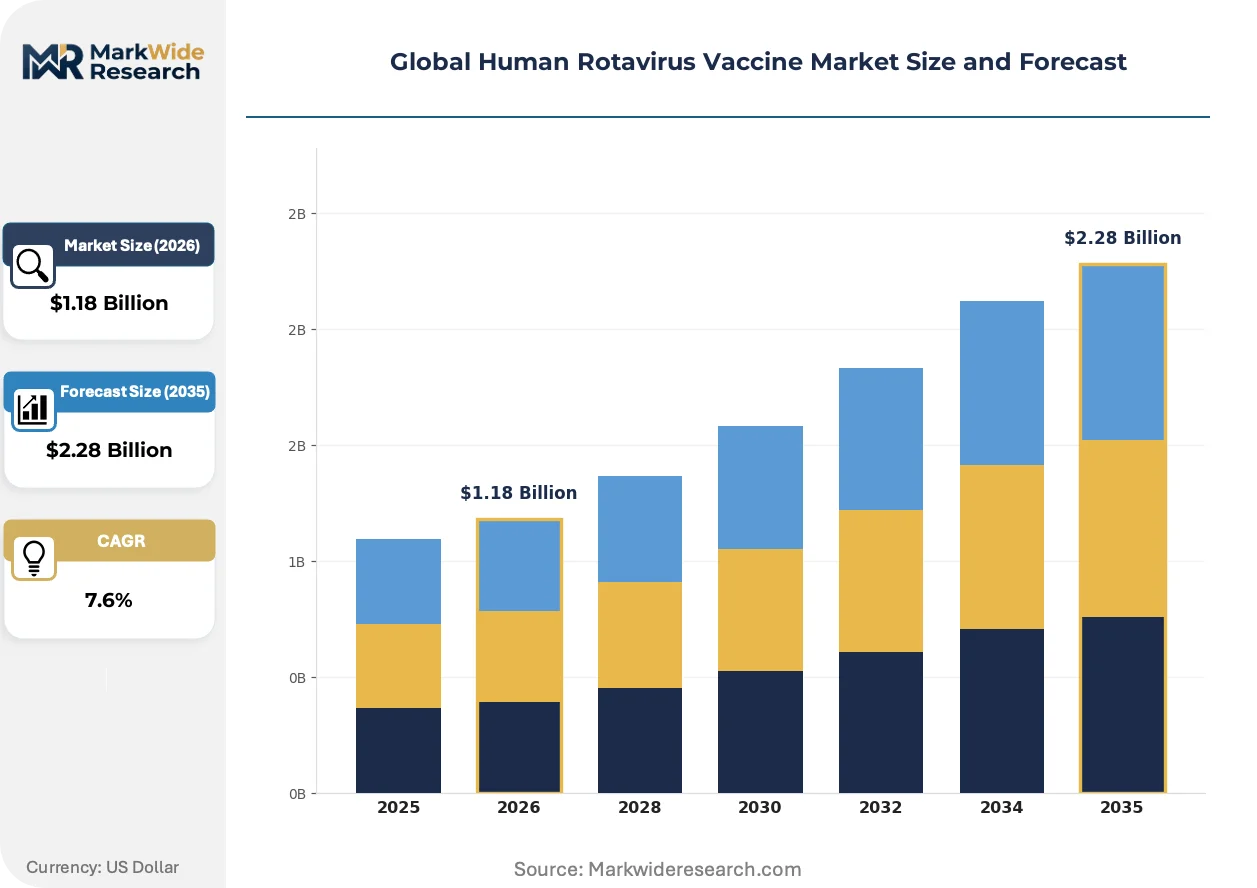
Market Dynamics
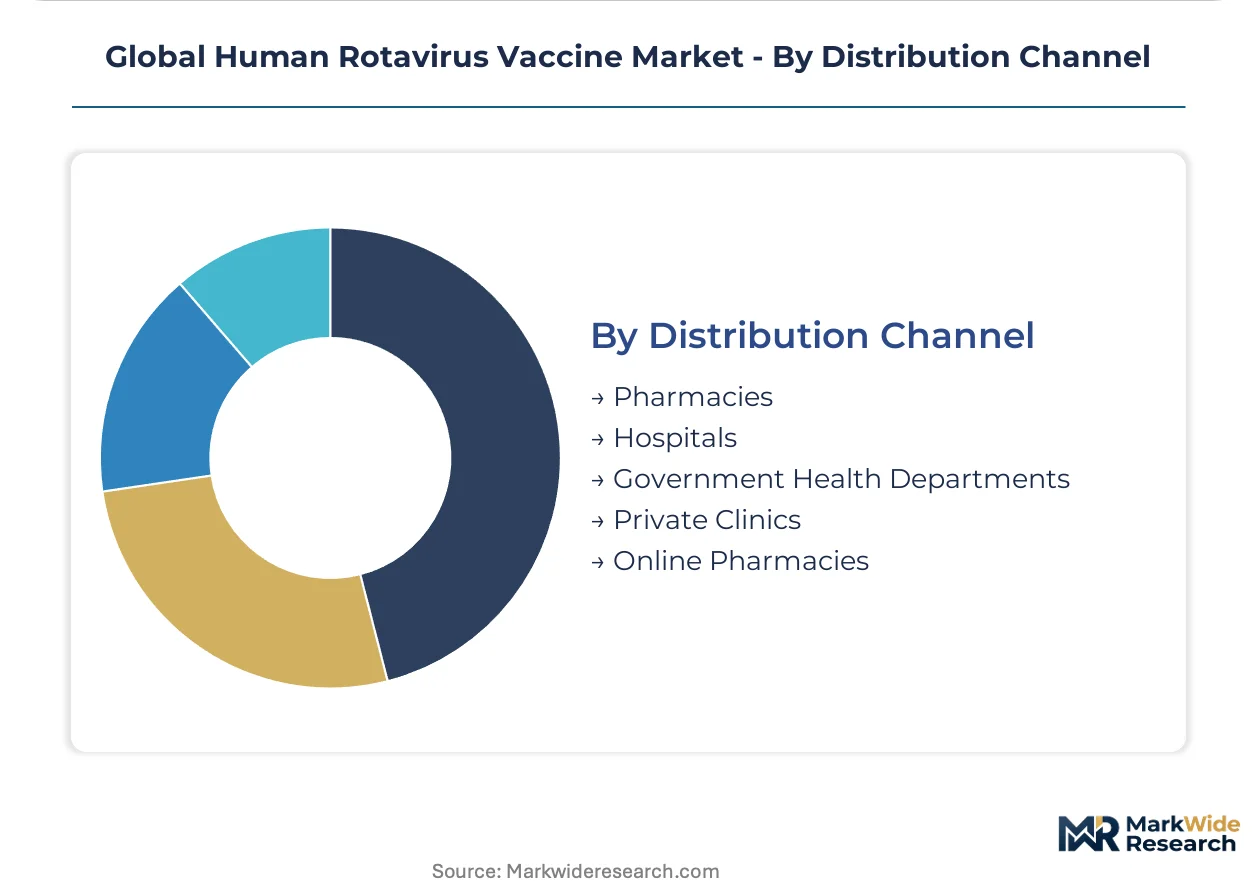
WHO prequalification pathways are compressing time-to-market for novel oral formulations while Gavi co-financing agreements restructure procurement economics across low-income country immunization programs.
Growth Catalysts
- Gavi co-financing agreements:These frameworks enable national immunization programs in sub-Saharan Africa and South Asia to expand coverage, creating sustained volume pull for oral rotavirus formulations.
- WHO prequalification acceleration:Streamlined pathways for thermostable alternatives reduce regulatory friction, compressing approval timelines for regional suppliers targeting UNICEF procurement channels.
- Cold-chain infrastructure investment:Development finance institutions are funding last-mile distribution networks in tropical climates, enabling broader reach for live attenuated oral doses.
Market Restraints
- Live attenuated stability limits:Temperature sensitivity constrains distribution to remote regions lacking reliable cold-chain infrastructure, particularly in equatorial zones.
- Supply concentration in Indian manufacturing:Dependence on Serum Institute of India Pvt. Ltd. and Bharat Biotech for UNICEF volumes creates geographic vulnerability to export policy shifts.
- Intranasal delivery immaturity:Alternative administration routes remain preclinical, leaving oral formulations as the sole viable option despite distribution complexity.
Strategic Opportunities
- Fractional-dosing protocols:WHO-sponsored trials in Bangladesh and Malawi are evaluating reduced-dose regimens that could expand supply availability without manufacturing expansion.
- Thermostable formulation development:Lyophilization and novel stabilizer technologies promise to eliminate cold-chain dependency, opening rural sub-Saharan African markets currently unreachable.
- Indonesia's national regulatory autonomy:The country's reference to WHO standards for accelerated approvals creates a template for other ASEAN members to fast-track regional supplier entry.
Industry Challenges
- Bioprocess engineering talent scarcity:Live attenuated vaccine production requires specialized fermentation expertise concentrated in legacy polio and measles manufacturing centers.
- EMA-FDA divergence on stability data:Differing requirements for real-time versus accelerated stability testing complicates dossier preparation for sponsors seeking dual jurisdiction approval.
- Serotype replacement surveillance:Post-introduction monitoring for G12 and emerging strains demands molecular epidemiology capacity that national immunization technical advisory groups often lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Human Rotavirus Vaccine Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Monovalent, Pentavalent, Live Attenuated, Inactivated, Recombinant Administration Route: Oral, Injectable, Mucosal, Intranasal, Sublingual End User: Children's Hospitals, Community Clinics, Pediatric Centers, Immunization Programs Distribution Channel: Pharmacies, Hospitals, Government Health Departments, Private Clinics, Online Pharmacies |
| Companies Covered | Bharat Biotech, Lanzhou Institute of Biological Products Co., Ltd., Merck & Co., Inc., Sinovac Biotech Ltd., Biological E. Limited, GlaxoSmithKline plc, Sanofi, PT Bio Farma, Serum Institute of India Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Human Rotavirus Vaccine Market Shifts & Advancements
Formulation science and delivery modality innovation are converging to address the fundamental tension between mucosal immunogenicity and thermostability in tropical distribution environments.
Lyophilized oral rotavirus formulations are absorbing the bulk of R&D investment from established and emerging manufacturers alike. UNICEF procurement specifications now prioritize candidates demonstrating stability at temperatures exceeding standard cold-chain parameters. This absorption of capital into thermostability research is compressing competitive timelines, with multiple candidates advancing simultaneously toward WHO prequalification submission.
EMA's revised guidelines on live viral vaccine stability testing now mandate real-time data for tropical zone label claims, eliminating accelerated stability extrapolation previously accepted for temperate market authorization. European sponsors must now conduct parallel stability studies in climatic zone IV conditions, adding eighteen to twenty-four months to development timelines. Indian and Indonesian regulators are adopting similar stringency, referencing EMA standards in draft guidance documents circulated for industry comment.
Bulk procurement through UNICEF Supply Division is consolidating national tender fragmentation that previously characterized rotavirus vaccine purchasing. Ministries of health in Gavi-eligible countries now channel demand through pooled mechanisms, displacing bilateral negotiations with manufacturers. This concentration is most visible in sub-Saharan Africa, where fifteen countries transitioned to unified procurement in the past three years, compressing price dispersion and standardizing presentation requirements across national programs.
Global Human Rotavirus Vaccine Market Segmentation
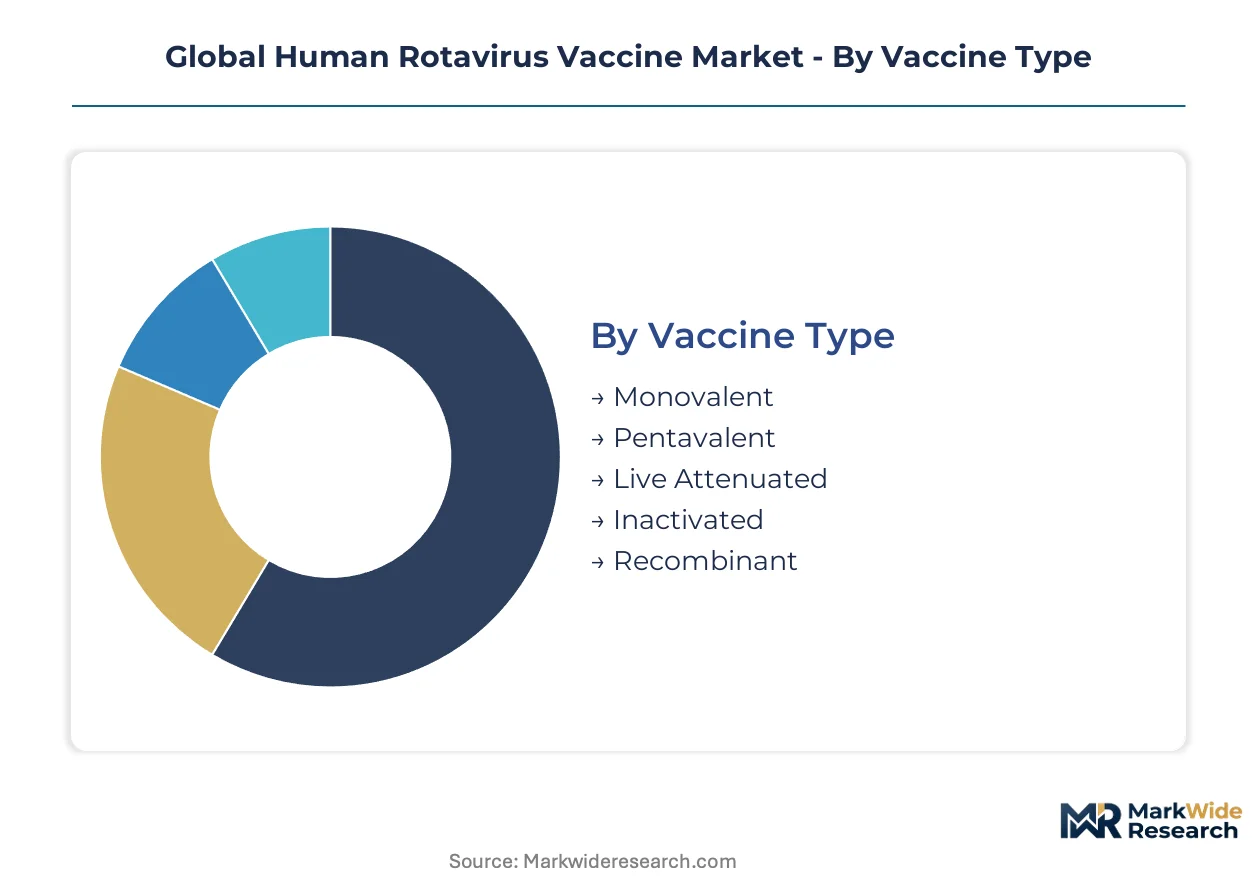
Rotavirus vaccine procurement splits sharply between premium formulations commanding higher margins and volume-optimized alternatives serving public-sector tenders. Understanding these segment boundaries reveals where manufacturers compete on cost versus complexity, and which distribution channels absorb each tier.
Vaccine Type:
Pentavalent formulations anchor premium value pools while monovalent alternatives capture procurement volume across Gavi-eligible countries.
- Monovalent:Single-serotype formulations reduce manufacturing complexity and cold-chain requirements. Demand concentrates in India's national immunization program and UNICEF procurement channels serving sub-Saharan Africa, driven by cost optimization mandates in public-sector tenders.
- Pentavalent:Multi-serotype preparations containing G1-G4 and G9 antigens require sophisticated formulation science. India's CDSCO and Indonesia's national regulator reference WHO prequalification standards for accelerated approvals, compressing time-to-market for complex candidates.
- Live Attenuated:Temperature-sensitive oral doses dominate current immunization programs despite distribution constraints in equatorial zones.
- Inactivated:Non-replicating alternatives offer theoretical stability advantages but remain commercially marginal due to inferior mucosal immunogenicity.
- Recombinant:Genetically engineered subunit vaccines absorb early-stage R&D investment from manufacturers seeking thermostable alternatives.
Today's leader: Pentavalent. Tomorrow's challenger: Recombinant.
Administration Route:
Oral delivery captures virtually all commercial volume while intranasal research intensifies around tropical distribution challenges.
- Oral:Live attenuated liquid or lyophilized formulations delivered to infants induce intestinal IgA responses. Bangladesh and Malawi host WHO-sponsored fractional-dosing trials evaluating reduced-volume regimens that could expand supply without manufacturing scale-up.
- Intranasal:Mucosal spray delivery promises to eliminate cold-chain dependency through thermostable powder formulations. Preclinical programs target rural sub-Saharan African markets currently unreachable by conventional oral doses.
- Injectable:Parenteral administration remains experimental for rotavirus, with no licensed products.
- Mucosal:Broad category encompassing non-oral mucosal surfaces including buccal and rectal routes.
- Sublingual:Under-tongue delivery absorbs exploratory research from pediatric formulation specialists seeking needle-free alternatives.
Oral administration holds current volume dominance. Intranasal candidates are gaining share fastest among pipeline investments.
End User:
National immunization programs absorb bulk procurement volumes while pediatric centers handle fragmented private-sector demand.
- Immunization Programs:Government-funded universal vaccination schemes channel demand through UNICEF Supply Division and Gavi co-financing frameworks. Nigeria, Ethiopia, and the Democratic Republic of Congo expanded coverage under these mechanisms.
- Children's Hospitals:Tertiary pediatric facilities manage severe rotavirus gastroenteritis cases and administer vaccines to high-risk infants. Urban hospital networks in India and Indonesia maintain cold-chain infrastructure for live attenuated formulations.
- Community Clinics:Primary healthcare access points in rural districts struggle with last-mile distribution.
- Pediatric Centers:Private specialist practices serve insured populations in middle-income markets.
Immunization programs drive volume economics. Children's hospitals anchor premium positioning.
Distribution Channel:
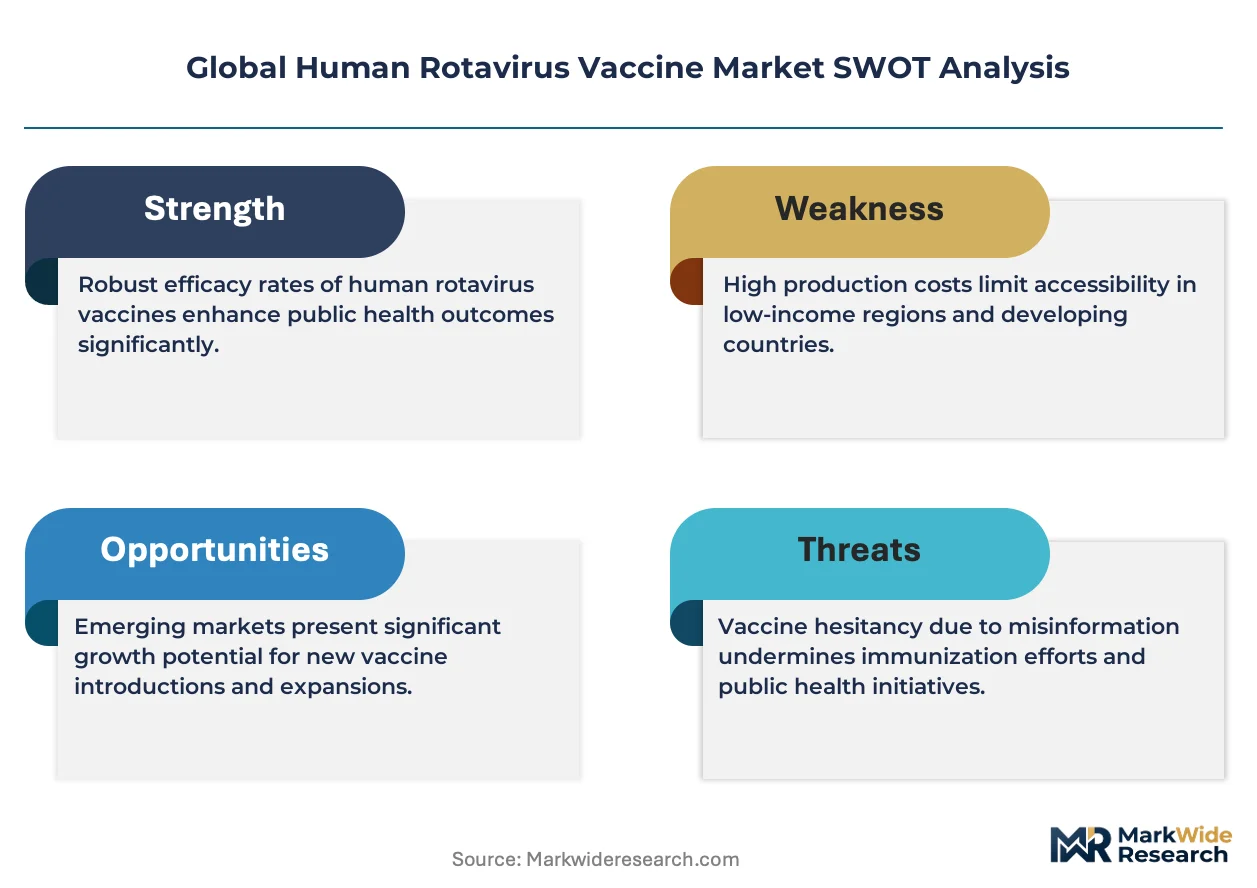
Government Health Departments consolidate procurement previously fragmented across bilateral negotiations.
- Government Health Departments:Ministries of health in Gavi-eligible countries now pool demand through unified procurement mechanisms. Fifteen sub-Saharan African countries transitioned to this model, compressing price dispersion.
- Hospitals:Institutional purchasers maintain dedicated cold-chain infrastructure for temperature-sensitive live attenuated doses.
- Pharmacies:Retail channels serve private-pay segments in urban India and Indonesia.
- Private Clinics:Independent practitioners capture out-of-pocket vaccination in middle-income cities.
- Online Pharmacies:Digital distribution remains nascent for temperature-controlled biological products.
Government Health Departments dominate procurement scale. Hospital channels sustain premium access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fermentation expertise concentrates in legacy vaccine manufacturing centers across India, the United States, and Europe, with emerging capacity building in Southeast Asian bioclusters.
India
UNICEF procurement channels absorb the majority of global rotavirus vaccine volumes, with Hyderabad and Pune hosting concentrated live attenuated vaccine manufacturing. CDSCO references WHO prequalification standards for accelerated approvals, compressing regulatory timelines for domestic suppliers. The Serum Institute of India Pvt. Ltd. and Bharat Biotech anchor production capacity in these clusters, supplying African immunization programs through Gavi frameworks.
United States
Pediatric hospital networks maintain sophisticated cold-chain infrastructure for temperature-sensitive oral formulations, with demand concentrated in tertiary care centers. FDA stability testing requirements mandate real-time data for tropical zone label claims, extending development timelines for thermostable candidates. The Research Triangle Park in North Carolina hosts contract manufacturing organizations supporting late-stage clinical trials for novel delivery modalities.
Indonesia
National immunization program expansion drives procurement volume growth, with Java-based distribution networks reaching remote archipelago regions. The national regulator references WHO standards for accelerated approvals, creating a template for ASEAN regulatory harmonization. Bandung and Jakarta host PT Bio Farma's manufacturing operations, supplying domestic and regional tender markets.
Bangladesh
WHO-sponsored fractional-dosing trials in Matlab and urban Dhaka evaluate reduced-volume regimens that could expand supply availability. The national immunization program channels demand through government health departments, with Gavi co-financing enabling coverage expansion. icddr,b research facilities anchor clinical trial infrastructure for thermostable formulation development.
South Africa
Sub-Saharan African distribution hubs concentrate in Johannesburg and Cape Town, supporting last-mile delivery to immunization programs across the continent. The national health department pools procurement with fifteen neighboring countries through unified mechanisms. Local biomanufacturing initiatives aim to reduce import dependency for routine pediatric vaccines.
Global Human Rotavirus Vaccine Market Competitive Landscape
Top-tier vendors anchor premium pentavalent formulations, while cost-optimized monovalent alternatives compete aggressively in public-sector tenders. The market structure bifurcates between multinational pharmaceutical conglomerates with established cold-chain franchises and regional biotech specialists leveraging manufacturing scale. Strategic archetypes include premium formulation innovators, volume-optimized suppliers, and emerging thermostability researchers. Capacity expansion and WHO prequalification pursuit dominate competitive moves as manufacturers position for UNICEF procurement consolidation.
Within the premium-tier multinational segment, Merck & Co., Inc. and GlaxoSmithKline plc occupy positions anchored by established regulatory dossiers and cold-chain distribution infrastructure. Indian manufacturing specialists exemplify the volume-driven archetype, with Bharat Biotech and Serum Institute of India Pvt. Ltd. representing cost-optimized production scale. These entities sit within distinct competitive vectors—multinationals defending margin through formulation complexity, regional suppliers capturing procurement volume through manufacturing efficiency.
| Leading Market Players |
|---|
| Bharat Biotech |
| Lanzhou Institute of Biological Products Co., Ltd. |
| Merck & Co., Inc. |
| Sinovac Biotech Ltd. |
| Biological E. Limited |
| GlaxoSmithKline plc |
| Sanofi |
| PT Bio Farma |
| Serum Institute of India Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Cold-chain infrastructure mandates from WHO prequalification standards gate qualified supply access and premium-tier pricing power for rotavirus vaccine manufacturers. UNICEF procurement specifications require demonstrated thermostability at elevated temperatures, creating a dual filter that excludes uncertified suppliers while enabling validated producers to command formulation complexity premiums.
Pricing Analysis
The bundled cold-chain service versus unbundled product-only split defines competitive positioning across tender categories. Pentavalent formulations with integrated distribution support capture premium positioning through Merck's RotaTeq franchise, while monovalent alternatives from Bharat Biotech compete on stripped-down pricing for volume-optimized public-sector awards. Price differentiation hinges on WHO prequalification tier and manufacturing scale, with Indian producers leveraging UNICEF channel access to compress margins in African tenders. Cost compression in monovalent segments intensifies as Gavi co-financing expands eligible country pools. Government immunization programs exhibit highest price sensitivity; private pediatric centers in urban India and Indonesia tolerate premium positioning for cold-chain reliability.
Supply Chain Analysis
Live viral seed stock supply rests on legacy polio and measles manufacturing centers concentrated in India, the United States, and Europe. Hyderabad and Pune clusters feed fermentation capacity for Serum Institute and Bharat Biotech, while North Carolina's Research Triangle Park anchors contract manufacturing for thermostable formulation trials. Specialized bioprocess engineering talent and GMP-grade cell culture media constitute critical input dependencies. Single-source vulnerability concentrates in Indian export policy exposure for UNICEF volumes. Distribution runs through government health department procurement pools that consolidated fifteen sub-Saharan African national tenders into unified mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through thermostable formulation premiums displacing cold-chain infrastructure costs, with fractional-dosing protocols enabling supply-side efficiency gains without manufacturing scale-up.
For Market Incumbents: Hedge thermostability leadership against intranasal delivery disruption by accelerating lyophilized oral candidates through WHO prequalification while funding preclinical powder formulation research. Merck and GlaxoSmithKline should defend pentavalent positioning through EMA-FDA stability data harmonization investments that extend regulatory moats. Serum Institute must secure backward integration into GMP-grade cell culture media to reduce input cost volatility. For New Entrants and Emerging Players: UNICEF Supply Division channel partnerships offer the most penetrable entry vector for regional biotech specialists lacking established cold-chain franchises. Indonesia's national regulatory autonomy provides a template for ASEAN market access without full EMA-FDA dossier investment. Target rural sub-Saharan African immunization programs currently unreachable by liquid oral formulations through thermostable powder development partnerships with icddr,b or equivalent tropical trial networks. For Investors and Strategic Acquirers: Roll-up economics work for thermostable formulation platforms because WHO prequalification scarcity and Gavi procurement consolidation concentrate value in validated manufacturing assets. Five-to-ten year viability favors sponsors with demonstrated climatic zone IV stability data and existing UNICEF supply agreements. Watch WHO-sponsored fractional-dosing trial readouts from Bangladesh and Malawi as inflection indicators for supply-demand rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Validates thermostable candidates for Gavi-eligible country procurement channels. |
| Lyophilization Technology Investment | Eliminates cold-chain dependency for rural sub-Saharan African market access. |
| Fractional-Dosing Clinical Trials | Expands effective supply availability without fermentation capacity expansion. |
| Regional Regulatory Harmonization | Accelerates ASEAN market entry through Indonesia's WHO-reference approval template. |
| UNICEF Supply Division Partnership | Secures volume commitments through pooled procurement consolidation mechanisms. |
Research Methodology
Bottom-up immunization program modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with vaccine development executives, regulatory affairs leads at CDSCO and Indonesia's national regulator, UNICEF procurement officers, and hospital formulary directors combined with secondary validation from WHO prequalification listings, EMA stability guideline documents, ClinicalTrials.gov fractional-dosing protocols, and Gavi co-financing disclosure databases. Top-down triangulation against Serum Institute and Bharat Biotech production capacity estimates anchored volume assumptions.
Input-output matrices mapped vaccine type, administration route, and end-user segments across the projection horizon. Modeled dimensions included pentavalent versus monovalent formulation tiers, oral versus intranasal delivery maturity, and immunization program versus private pediatric center demand splits. CAGRs derived from elasticity-adjusted price-volume trajectories incorporating cold-chain infrastructure investment flows and thermostable formulation R&D absorption rates. Forecast inputs incorporated Gavi-eligible country coverage expansion schedules and WHO prequalification pipeline progression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to intranasal delivery breakthroughs, serotype replacement epidemiology, and Indian export policy shifts. Assumptions reflect documented procurement consolidation trends and regulatory pathway acceleration. A small set of triggers—fractional-dosing trial readouts, thermostable candidate WHO submissions, and ASEAN regulatory harmonization progress—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Caspofungin Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Global Low Molecular Weight Heparin Market