
 US Dark Chocolate Market | 2026-2036
US Dark Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
US Dark Chocolate Market Insights
The US dark chocolate category is restructuring around a stark split between artisanal bean-to-bar products and mass-market formulations with lower cocoa percentages. The Hershey Company dominates shelf-stable distribution through grocery networks while competing on price against private-label alternatives. Lindt & Sprüngli AG anchors the premium gifting segment with European-imported couverture, and Guittard Chocolate Company specializes in craft baking supply channels where professional chefs demand specific cacao percentages.
Dark chocolate contains a minimum of 50% cocoa solids by weight, with extra-dark variants exceeding 70% and carrying elevated flavanol concentrations that manufacturers highlight for functional positioning. Semisweet products occupy the largest volume tier in retail supermarkets, while organic dark chocolate commands disproportionate margin pools through specialty stores and direct-to-consumer channels. Gourmet food lovers increasingly purchase single-origin bars through online retail, where packaging type innovation in small-format pouches supports trial and subscription models.
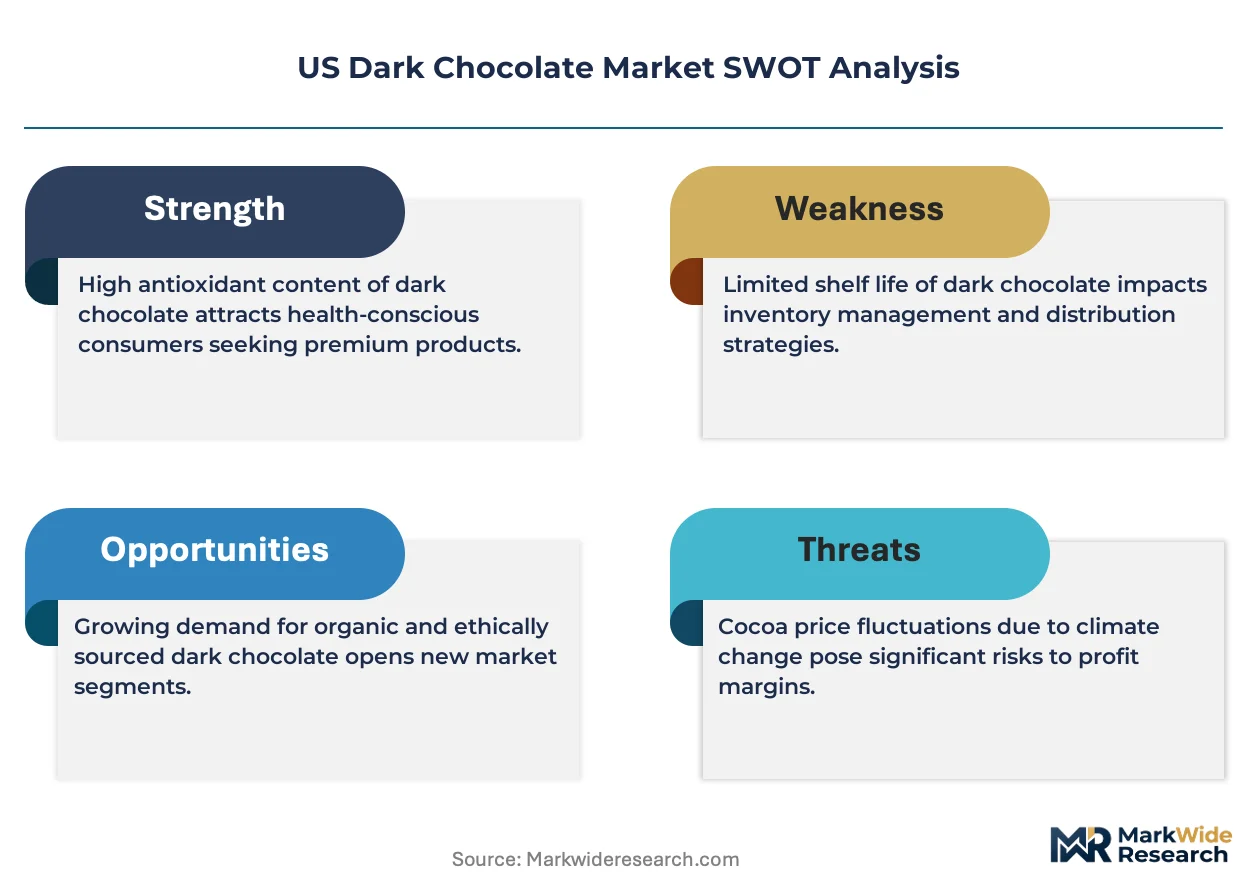
FDA standards of identity govern minimum cocoa butter requirements and prohibit vegetable fat substitutions in products labeled dark chocolate, while USDA organic certification shapes premium positioning and pricing architecture. State-level regulations in California under Proposition 65 add warning-label requirements for heavy metal content, creating compliance costs that favor scaled manufacturers with laboratory testing infrastructure. Stakeholders must monitor evolving FDA guidance on added-sugar disclosure and anticipate whether health-conscious shopper segments will shift purchases based on front-of-package labeling changes.
Market Dynamics
Bean-to-bar craft producers are forcing reformulation transparency across the US dark chocolate category, as single-origin sourcing claims and flavanol content verification displace legacy mass-market positioning.
Growth Catalysts
- California Proposition 65 enforcement:Heavy metal testing mandates push professional buyers toward certified suppliers with laboratory infrastructure, accelerating quality-tier consolidation.
- Specialty confectionery boutiques:Curated retail environments in New York City and San Francisco drive trial of small-batch extra-dark variants through educated staff recommendations.
- Direct-to-consumer subscription models:Online platforms enable origin-story marketing and recurring revenue capture among gourmet food enthusiasts seeking limited harvest releases.
Market Restraints
- Cocoa butter price volatility:FDA standards of identity prohibit vegetable fat substitution, locking manufacturers to commodity cocoa butter swings without formulation flexibility.
- West African supply concentration:Ivory Coast and Ghana origin dependence creates disruption exposure from political instability and climate yield variability.
- Flavor threshold limitations:Consumer rejection rates rise above 85% cocoa solids, capping premium positioning for ultra-high flavanol formulations.
Strategic Opportunities
- USDA organic certification expansion:Premium margin pools in specialty stores reward certified producers with pricing power unavailable in conventional grocery.
- Baking supply channel specialization:Professional chefs demand specific cacao percentages, creating technical specification lock-in for craft suppliers with precise grinding control.
- Front-of-package labeling evolution:Anticipated FDA added-sugar disclosure guidance positions early adopters to capture health-conscious shopper migration.
Industry Challenges
- Heavy metal compliance timeline:California laboratory testing requirements strain mid-tier producers lacking scaled quality assurance infrastructure.
- Bean sourcing transparency verification:Single-origin claims require supply chain documentation that conflicts with fragmented West African cooperative structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Dark Chocolate Market |
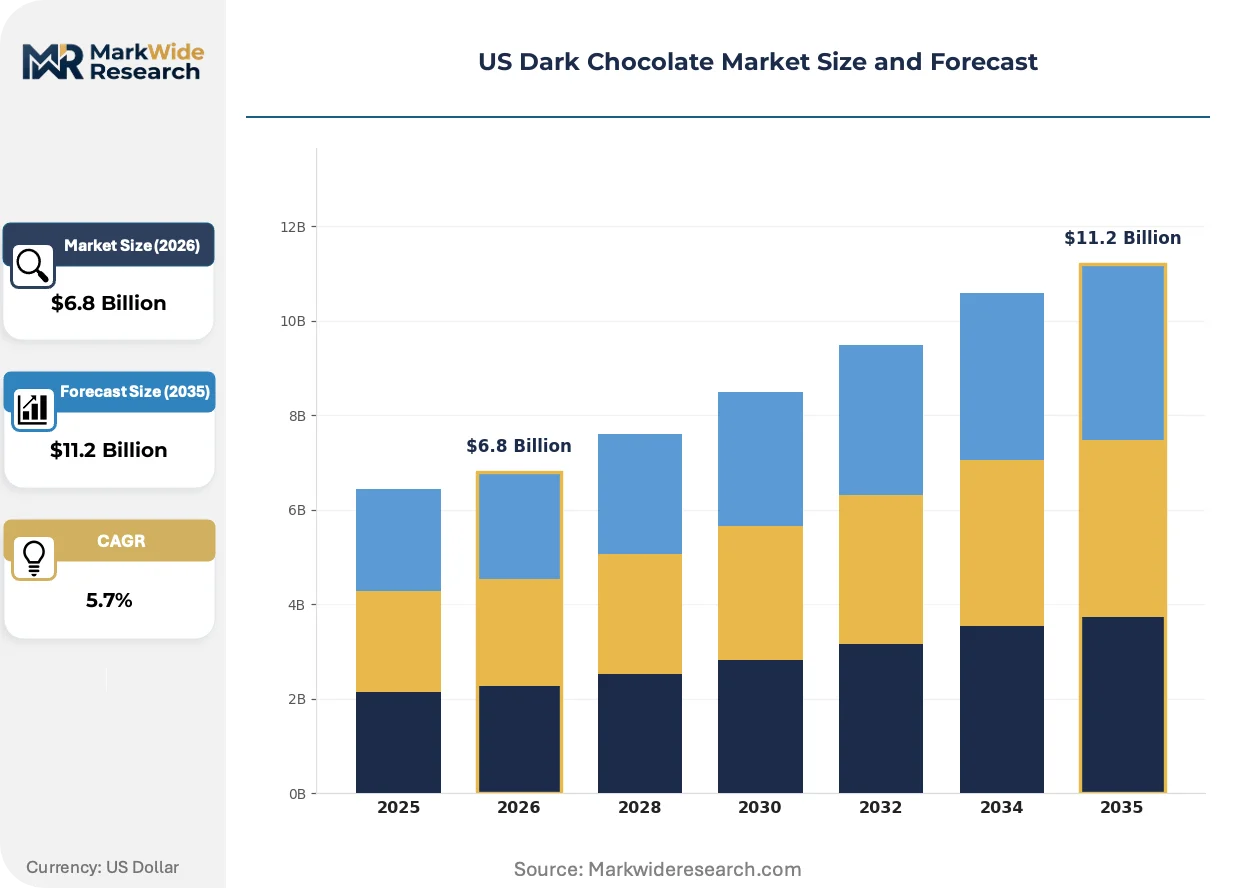
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bittersweet, Semisweet, Extra Dark, Organic Customer Type: Retail Consumers, Gourmet Food Lovers, Health-Conscious Shoppers, Chefs Sales Channel: Supermarkets, Specialty Stores, Online Retail, Convenience Stores Packaging Type: Bars, Bites, Pouches, Assorted Boxes |
| Companies Covered | The Hershey Company, Mars Incorporated, Mondelēz International, Ferrero International SA, Chocoladefabriken Lindt & Sprüngli AG, Barry Callebaut AG, Cargill, Incorporated, Ghirardelli Chocolate Company, Guittard Chocolate Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Dark Chocolate Market Trends and Innovations
Precision fermentation and alternative protein convergence are disrupting traditional cocoa butter economics, while regulatory disclosure mandates and channel fragmentation reshape how US consumers discover and purchase dark chocolate.
Precision fermentation-derived cocoa butter is rewriting fat chemistry standards for premium formulations. Artisanal producers in Brooklyn and Oakland are piloting microbial lipid alternatives that replicate crystallization behavior without agricultural commodity exposure. This technology is compressing the price gap between certified organic and conventional dark chocolate by decoupling production from West African harvest cycles.
FDA standards of identity updates are tightening vegetable fat prohibition enforcement while expanding added-sugar disclosure requirements. Manufacturers must reformulate legacy recipes or risk mislabeling penalties that trigger retailer delisting. The premium gifting segment faces the steepest compliance costs as European-imported couverture requires dual-jurisdiction certification alignment.
Specialty store discovery is yielding to algorithmic curation on subscription platforms where origin stories and harvest dates drive purchase decisions. Gourmet food enthusiasts now expect direct relationships with Ecuadorian or Peruvian estate producers, bypassing traditional importer-distributor markups. This channel rotation concentrates in California's premium retail corridor where digital-native brands capture trial through influencer-verified sourcing documentation.
US Dark Chocolate Market Segmentation
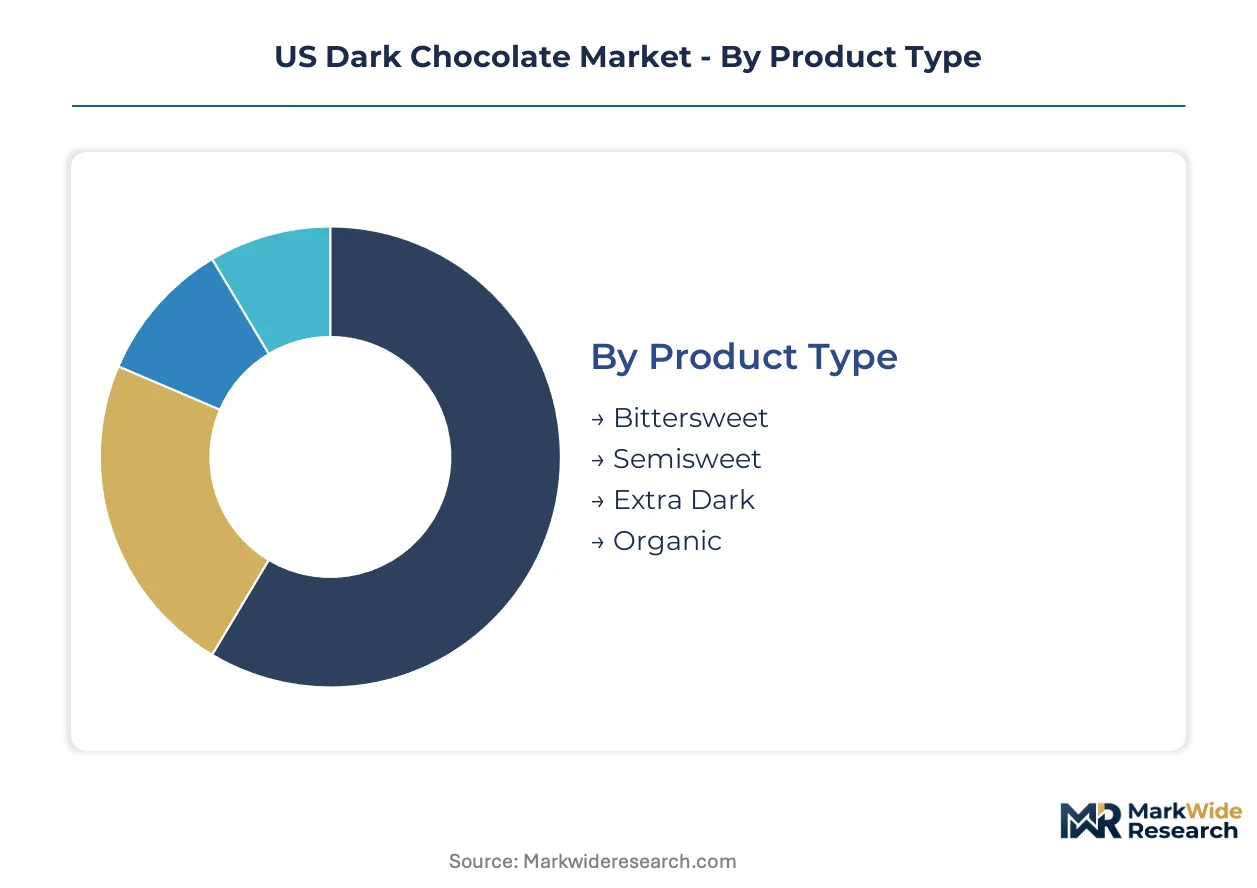
Segmentation in the US dark chocolate market reveals how FDA standards of identity and California Proposition 65 compliance costs concentrate production capabilities among scaled manufacturers. Supply chain fragmentation across West African origins and domestic bean-to-bar craft operations creates divergent margin structures that reshape competitive positioning.
Product Type:
Supply concentration in cocoa butter processing favors manufacturers with integrated grinding and pressing capabilities, locking out smaller producers from extra-dark and organic tiers that demand precise fat chemistry control.
- Semisweet:Contains 50-69% cocoa solids with balanced sugar ratios that dominate supermarket shelf space. Demand concentrates in California's premium retail corridor where mass-market brands compete on price against private-label alternatives, constrained by FDA minimum cocoa butter requirements that prohibit vegetable fat substitution.
- Extra Dark:Exceeds 70% cocoa solids with elevated flavanol concentrations that manufacturers highlight for functional positioning. Gourmet food lovers in New York City specialty boutiques drive trial through educated staff recommendations, though consumer rejection rates rise above 85% cocoa solids.
- Bittersweet:Technical specifications overlap with semisweet at 50-70% cocoa solids but with lower sugar content, creating formulation flexibility for baking applications.
- Organic:USDA certification shapes premium positioning through specialty stores and direct-to-consumer channels, commanding disproportionate margin pools unavailable in conventional grocery.
Today's leader: Semisweet. Tomorrow's challenger: Organic.
Customer Type:
Cost tier stratification separates mass-market retail consumers from premium segments willing to absorb origin-story pricing and subscription premiums.
- Retail Consumers:Price-sensitive mass-market purchasers who dominate supermarket volume tiers and respond to front-of-package labeling changes.
- Gourmet Food Lovers:Single-origin bar purchasers seeking limited harvest releases through online platforms with direct Ecuadorian or Peruvian estate relationships, bypassing traditional importer-distributor markups.
- Health-Conscious Shoppers:Flavanol content verification drives purchase decisions among consumers monitoring added-sugar disclosure guidance from FDA.
- Chefs:Professional kitchen demand for specific cacao percentages creates technical specification lock-in for craft suppliers with precise grinding control in baking supply channels.
Volume concentrates with Retail Consumers. Margin concentrates with Gourmet Food Lovers.
Sales Channel:
Application-driven channel fragmentation is accelerating as algorithmic curation on subscription platforms displaces specialty store discovery.
- Supermarkets:Shelf-stable distribution networks where The Hershey Company competes on price against private-label alternatives in semisweet and standard dark tiers.
- Specialty Stores:Curated retail environments in San Francisco and New York City where Lindt & Sprüngli AG anchors premium gifting with European-imported couverture.
- Online Retail:Direct-to-consumer subscription models enabling origin-story marketing and recurring revenue capture among digital-native brands in California's premium retail corridor.
- Convenience Stores:Impulse purchase locations for single-serve formats with limited SKU depth and minimal origin transparency.
Supermarkets hold volume dominance. Online Retail gains share fastest.
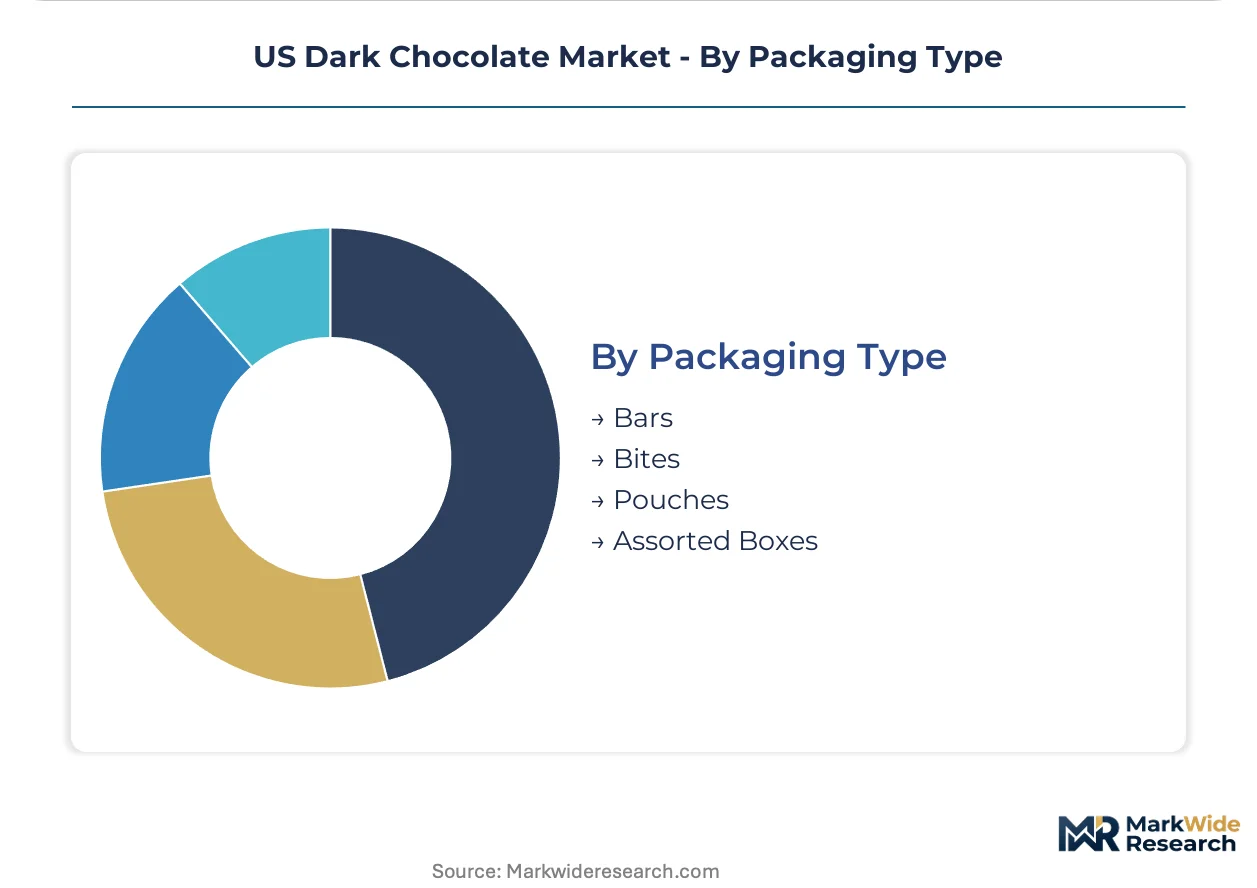
Packaging Type:
Maturity gradients separate established bar formats from emerging small-format innovations designed for trial and subscription logistics.
- Bars:Standard 1.5-3.5 ounce formats dominating retail shelf sets with established FDA labeling surface area for cocoa content and added sugar disclosure.
- Pouches:Small-format resealable packaging supporting trial sizes and subscription box logistics, favored by Brooklyn and Oakland artisanal producers piloting microbial lipid alternatives.
- Bites:Single-serve portion control formats targeting health-conscious shopper segments with precise calorie and flavanol count transparency.
- Assorted Boxes:Premium gifting configurations facing steepest compliance costs as European-imported couverture requires dual-jurisdiction certification alignment with FDA and origin-country standards.
Bars define today's standard. Pouches enable tomorrow's growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisanal chocolatiers and cocoa butter refiners concentrate in coastal metropolitan corridors, while mid-continent distribution hubs manage temperature-controlled logistics for shelf-stable formulations.
California
Premium retail corridors in San Francisco and Los Angeles anchor single-origin bar distribution through specialty boutiques and direct-to-consumer platforms. Proposition 65 mandates heavy metal testing for lead and cadmium content, favoring manufacturers with laboratory infrastructure. Oakland-based craft producers pilot precision fermentation-derived cocoa butter alternatives that bypass West African commodity exposure.
New York
Specialty confectionery boutiques in Manhattan and Brooklyn drive trial of extra-dark variants through educated staff recommendations and origin-story marketing. FDA labeling requirements for cocoa content and added sugars shape front-of-package design decisions for premium gifting formats. Brooklyn artisanal clusters experiment with microbial lipid alternatives to traditional cocoa butter formulations.
Pennsylvania
Integrated grinding and pressing capabilities support mass-market semisweet production for national grocery distribution networks. FDA standards of identity enforcement maintains minimum cocoa butter requirements that prohibit vegetable fat substitution in shelf-stable products. Hershey anchors chocolate manufacturing infrastructure with captive supply chain control over cocoa processing.
Illinois
Midwest distribution hubs manage temperature-controlled warehousing for baking supply channels serving professional chefs demanding specific cacao percentages. USDA organic certification infrastructure supports premium positioning for specialty store and foodservice segments. Chicago-area logistics clusters coordinate national fulfillment for subscription-based direct-to-consumer brands.
US Dark Chocolate Market Competitive Landscape
Top-tier vendors anchor mass-market grocery distribution, while craft bean-to-bar producers occupy premium specialty channels. The competitive structure stratifies across three capability tiers: integrated multinationals with cocoa processing infrastructure, regional couverture specialists with European import relationships, and artisanal producers with single-origin sourcing documentation. Strategic archetypes include scale-driven formulation standardizers, origin-story marketers leveraging direct-to-consumer platforms, and technical specification specialists serving professional baking channels. Competitive moves concentrate on supply chain transparency verification and precision fermentation technology licensing to decouple from commodity cocoa butter volatility.
Within the integrated multinational tier, The Hershey Company and Mars Incorporated exemplify scale-driven distribution architectures spanning conventional grocery and convenience store networks. Chocoladefabriken Lindt & Sprüngli AG occupies a premium-tier position through European-imported couverture and gifting-segment specialization. Guittard Chocolate Company represents the technical specification archetype, anchoring craft baking supply channels where professional chefs demand precise cacao percentage control.
| Leading Market Players |
|---|
| The Hershey Company |
| Mars Incorporated |
| Mondelēz International |
| Ferrero International SA |
| Chocoladefabriken Lindt & Sprüngli AG |
| Barry Callebaut AG |
| Cargill, Incorporated |
| Ghirardelli Chocolate Company |
| Guittard Chocolate Company |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation-derived cocoa butter alternatives are compressing cost economics between certified organic and conventional tiers while redistributing supply concentration toward domestic biotechnology clusters in Oakland and Brooklyn. This production-method transition simultaneously decouples pricing from West African commodity cycles and shifts margin capture toward manufacturers with laboratory infrastructure for heavy metal compliance.
Pricing Analysis
Subscription-bundled direct-to-consumer models separate origin-story premiums from unbundled supermarket transactional pricing. Three-tier pricing structure across premium single-origin, standard semisweet, and economy private-label levels stratifies by cocoa percentage and certification grade. Pricing pressure stems from cocoa butter commodity volatility that FDA standards of identity amplify by prohibiting vegetable fat substitution. Retail consumers in mass-market grocery show highest price sensitivity, while gourmet food lovers absorb subscription premiums for limited harvest releases.
Supply Chain Analysis
Dual-sourcing requirements from California Proposition 65 enforcement push professional buyers toward certified suppliers with redundant laboratory testing capabilities. Raw material flows draw from Ivory Coast and Ghana for bulk cocoa butter, Ecuador and Peru for single-origin cacao, and domestic precision fermentation pilots for microbial lipid alternatives. Single-source vulnerability concentrates in West African harvest cycles exposed to political instability and climate yield variability. Distribution runs through temperature-controlled warehousing in Illinois and Pennsylvania for national grocery networks, with direct-to-consumer fulfillment bypassing traditional importer-distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where bean-to-bar transparency and flavanol verification displace legacy mass-market positioning. Gourmet food lovers are migrating toward direct estate relationships and subscription discovery, elevating supply chain documentation and origin storytelling above price competition.
For Market Incumbents: Anchor shelf-stable distribution through backward integration into cocoa processing infrastructure that satisfies FDA standards of identity and California heavy metal testing mandates. Defend against precision fermentation disruptors by locking long-term offtake agreements with Ecuadorian and Peruvian estate producers, securing exclusive harvest releases that craft competitors cannot replicate. Prioritize laboratory quality assurance investment to maintain Proposition 65 compliance without margin erosion.
For New Entrants and Emerging Players: California Proposition 65 enforcement opens a window for certified organic specialists to capture premium margin pools unavailable to conventional grocery competitors. Target direct-to-consumer subscription channels where algorithmic curation and influencer-verified sourcing documentation bypass incumbent shelf-space advantages. Pursue USDA organic certification as the primary go-to-market angle, leveraging specialty store placement before scaling into conventional retail.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional couverture specialists lacking direct-to-consumer infrastructure but possessing established European import relationships and technical specification expertise for professional baking channels. Long-term viability favors targets with dual capability in precision fermentation pilot programs and single-origin supply chain documentation. Watch FDA added-sugar disclosure guidance as the inflection signal for health-conscious shopper migration that would accelerate premium tier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Domestic microbial lipid production decouples cost structures from Ivory Coast and Ghana commodity exposure. |
| USDA Organic Certification Expansion | Specialty store pricing power rewards certified producers with margin premiums unavailable in conventional grocery. |
| Direct-to-Consumer Platform Launch | Subscription models enable origin-story marketing and recurring revenue capture among gourmet food enthusiasts. |
| Heavy Metal Testing Infrastructure | California Proposition 65 compliance creates barrier to entry favoring scaled manufacturers with laboratory capabilities. |
| Single-Origin Supply Agreement | Ecuadorian and Peruvian estate relationships secure limited harvest releases that differentiate premium positioning. |
Research Methodology
Coverage spans California, New York, Pennsylvania, and Illinois, with primary inputs from each regional production and consumption cluster. Primary interviews combined bean-to-bar craft producers, specialty store buyers, professional chefs, and quality assurance directors at scaled manufacturers with secondary validation from FDA guidance documents, USDA organic certification databases, California Office of Environmental Health Hazard Assessment enforcement records, and Nielsen retail audit data. Bottom-up demand modeling from subscription platform metrics and top-down supply triangulation from cocoa butter processing capacity estimates converged on segment-level outputs.
Granularity-level modeling deployed product type, customer archetype, sales channel, and packaging format dimensions at the state level, with cocoa percentage tiers and certification status as cross-cutting variables. CAGRs derived from trend extrapolation of direct-to-consumer subscription growth rates, specialty store expansion patterns, and precision fermentation technology adoption curves across the projection horizon. Forecast inputs incorporated FDA standards of identity enforcement timelines, California Proposition 65 laboratory testing cost trajectories, and West African supply disruption probability assessments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained cocoa butter commodity volatility or accelerated precision fermentation cost parity. Deviation in FDA added-sugar disclosure implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Premium Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Gum Base Candy Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Chocolate Spread Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Italy Chocolate Market
Confectionery
United States Caramel Chocolate Market
Confectionery
China Chocolate Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
Macarons Market
Confectionery
Chocolate Flavors Market
Confectionery
Japan Chocolate Market
Confectionery
North America Confectionery Market
Confectionery
Bean-To-Bar Chocolate Market