
 Sugar-Free Gummy Market | 2026-2036
Sugar-Free Gummy Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Free Gummy Market Analytics
Multi-source ingredient procurement is restructuring supply economics for sugar-free gummy manufacturers as polyol sweetener costs fluctuate across regions. Mars leverages captive R&D facilities in Europe to sustain formulation consistency across its sugar-free portfolio. Haribo competes through brand strength in gelatin-based variants, while Symbio-lab specializes in pectin alternatives for vegan-positioned lines.
Sugar-free gummies are chewable confectionery products formulated with non-glycemic sweeteners such as maltitol, isomalt, or steviol glycosides, manufactured through starch molding or depositing processes at controlled temperatures to preserve active ingredients. Functional gummies command premium positioning as carriers for vitamins, minerals, and botanical extracts in adult wellness routines. Pectin gummies are gaining share among vegan consumers, while gelatin gummies retain cost advantages in children's segments where texture preferences favor traditional mouthfeel. Online retail channels are expanding fastest for subscription-based vitamin gummy deliveries, though supermarkets still occupy the largest volume share through impulse placement strategies.
FDA GRAS determinations and EFSA novel food catalog entries shape which sweetener systems gain commercial traction in their respective jurisdictions, with divergent approval timelines creating regional formulation fragmentation. India's FSSAI is tightening labeling requirements for sugar-claim confectionery, affecting export-oriented manufacturers targeting South Asian diaspora markets. Stakeholders must monitor evolving sweetener safety assessments and adapt formulation pipelines before regulatory exclusions disrupt existing product lines.
Market Dynamics
Clean-label functional confectionery demand is restructuring procurement priorities as fitness-oriented consumers reject synthetic additives and prioritize botanical-active formulations with transparent supply chains.
Growth Catalysts
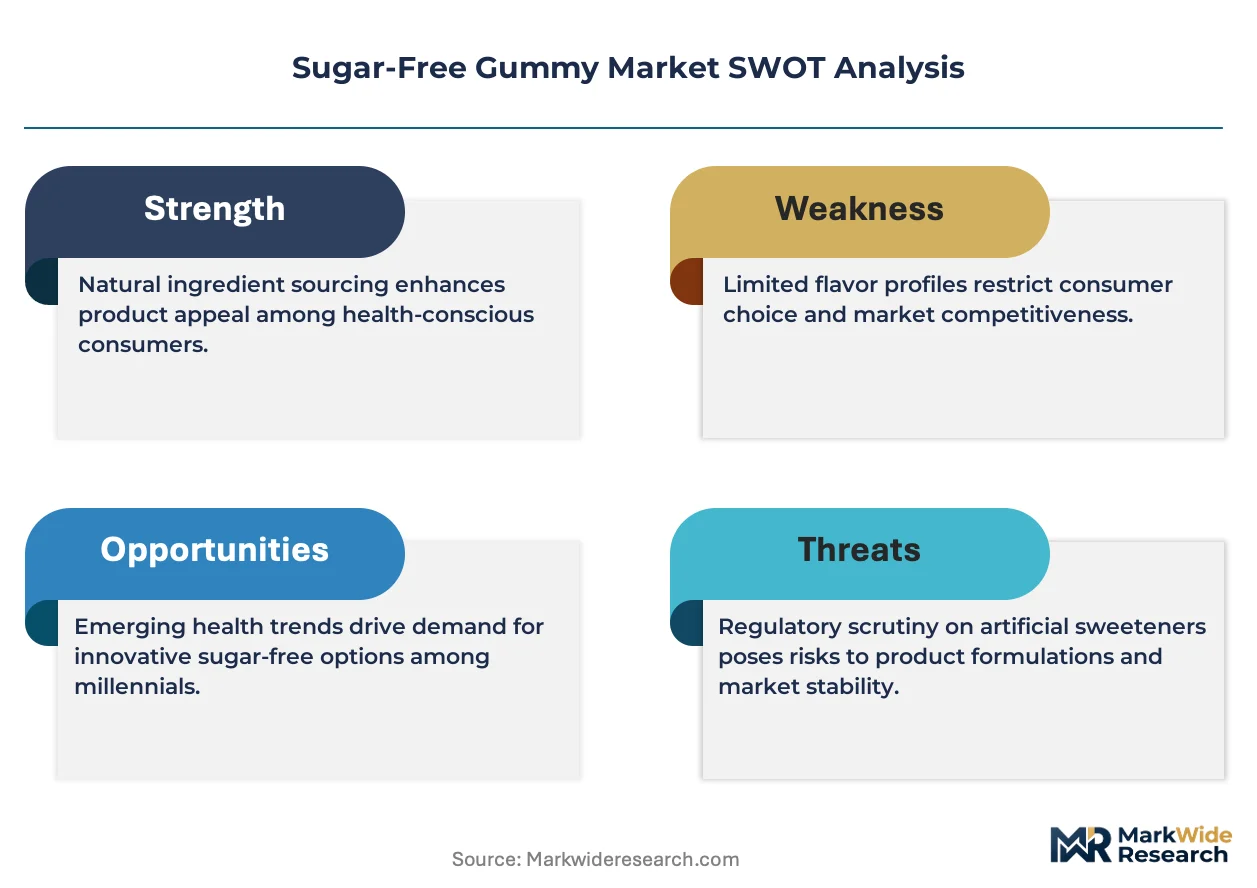
- EFSA Novel Food Pathways:Tightened approval frameworks for polyol sweeteners are accelerating investment in GRAS-compliant alternatives that preempt regulatory exclusion.
- Adult Wellness Routines:Vitamin and mineral fortification in chewable formats is displacing pill-based supplement adherence among time-constrained professionals.
- Germany's Private-Label Expansion:Health store chains are dedicating expanded shelf space to sugar-free vitamin gummies, creating concentrated demand pull for contract manufacturers.
Market Restraints
- Maltitol Price Volatility:Polyol sweetener costs fluctuate across regional procurement markets, compressing margin predictability for mid-scale producers.
- Gelatin Supply Concentration:Bovine and porcine-derived inputs face sourcing constraints from concentrated European rendering facilities.
- Texture Limitations in Pectin Systems:Vegan alternatives struggle to replicate the elastic mouthfeel that children's segments prefer, limiting category expansion.
Strategic Opportunities
- Subscription Vitamin Deliveries:Direct-to-consumer channels are capturing recurring revenue through personalized gummy regimens tailored to microbiome testing results.
- India's FSSAI Labeling Tightening:Export-oriented manufacturers can capture South Asian diaspora demand by preempting stricter sugar-claim disclosure requirements.
- Botanical-Active Convergence:Ashwagandha and adaptogen infusion is opening premium positioning beyond conventional vitamin matrices.
Industry Challenges
- Formulation Chemistry Expertise:Heat-sensitive active ingredient preservation requires specialized process engineering talent that remains scarce in contract manufacturing.
- Dual Jurisdiction Compliance:Parallel FDA GRAS and EFSA novel food dossier preparation extends time-to-market for multinational launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Free Gummy Market |
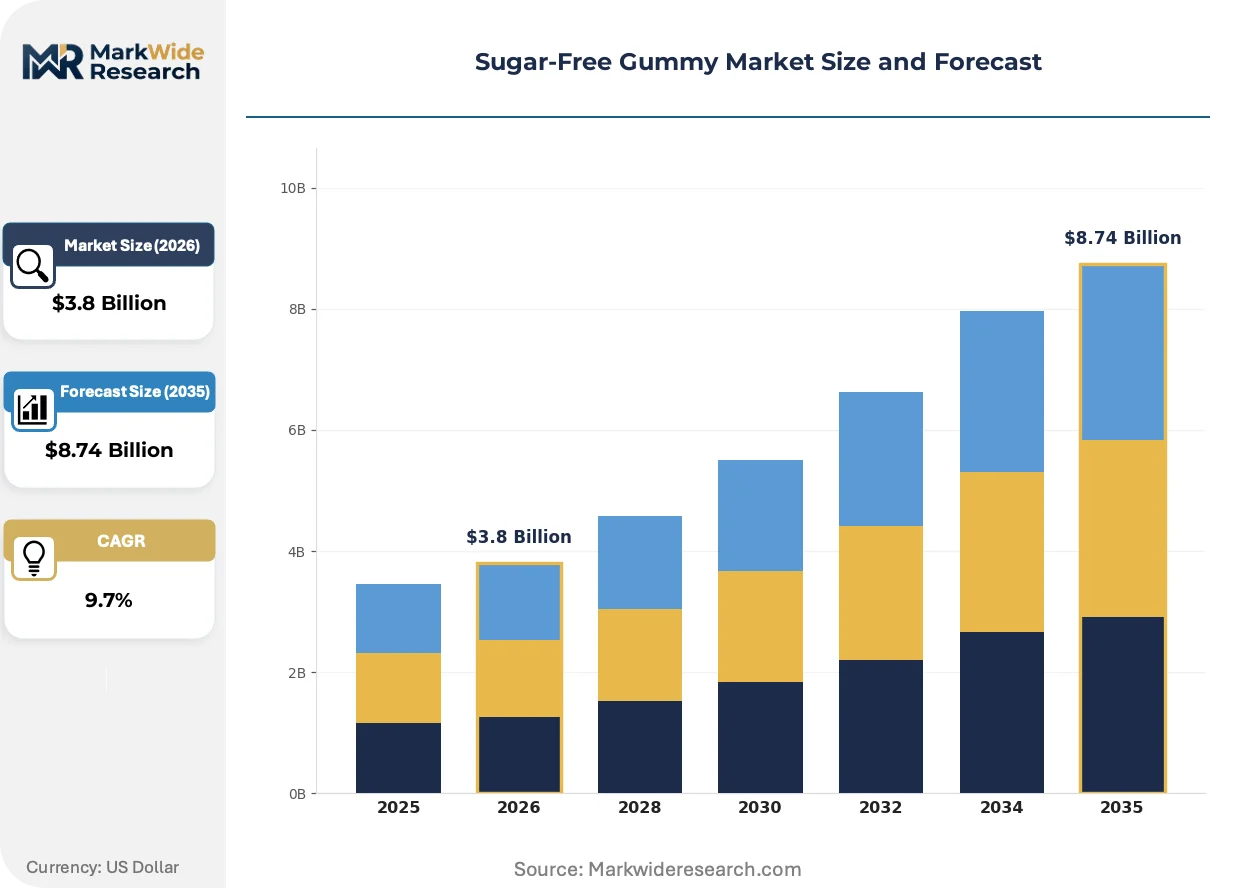
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegan Gummies, Gelatin Gummies, Pectin Gummies, Functional Gummies Flavor: Fruit Punch, Sour Citrus, Berry Medley, Tropical Breeze Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Children, Adults, Seniors, Fitness Enthusiasts |
| Companies Covered | TopGum Industries, Gumlink Confectionery Company, Mars, Parkacre Enterprises, Symbio-lab, Mondelēz, Haribo, Fermentis Life Sciences, Ferrero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Free Gummy Market Evolving Landscape
Starch molding automation and depositing precision are elevating active ingredient stability as manufacturers compete on functional efficacy rather than confectionery taste alone.
Precision depositing technology with temperature-controlled cooling tunnels is electrifying production economics for heat-labile probiotics and collagen peptides. Wellness brands targeting skin health and gut microbiome balance are adopting these systems at accelerated capital deployment cycles. The structural consequence is compression of batch-to-batch potency variation that previously plagued functional gummy credibility.
EFSA's tightening novel food catalog entries for steviol glycoside variants are forcing reformulation pipelines toward erythritol-allulose blends ahead of potential exclusion rulings. Manufacturers serving European retail channels are accelerating safety dossier submissions to secure grandfathered status. Adult vitamin gummies with botanical extracts face the steepest compliance timelines as novel food classifications proliferate.
Subscription-based replenishment models are displacing supermarket impulse purchases among millennial and Gen-Z supplement users. Direct-to-consumer brands leveraging microbiome test integration are capturing recurring revenue that traditional retail cannot replicate. Germany and Scandinavian urban markets exhibit the fastest channel rotation toward personalized gummy regimens with automated reorder algorithms.
Sugar-Free Gummy Market Segmentation
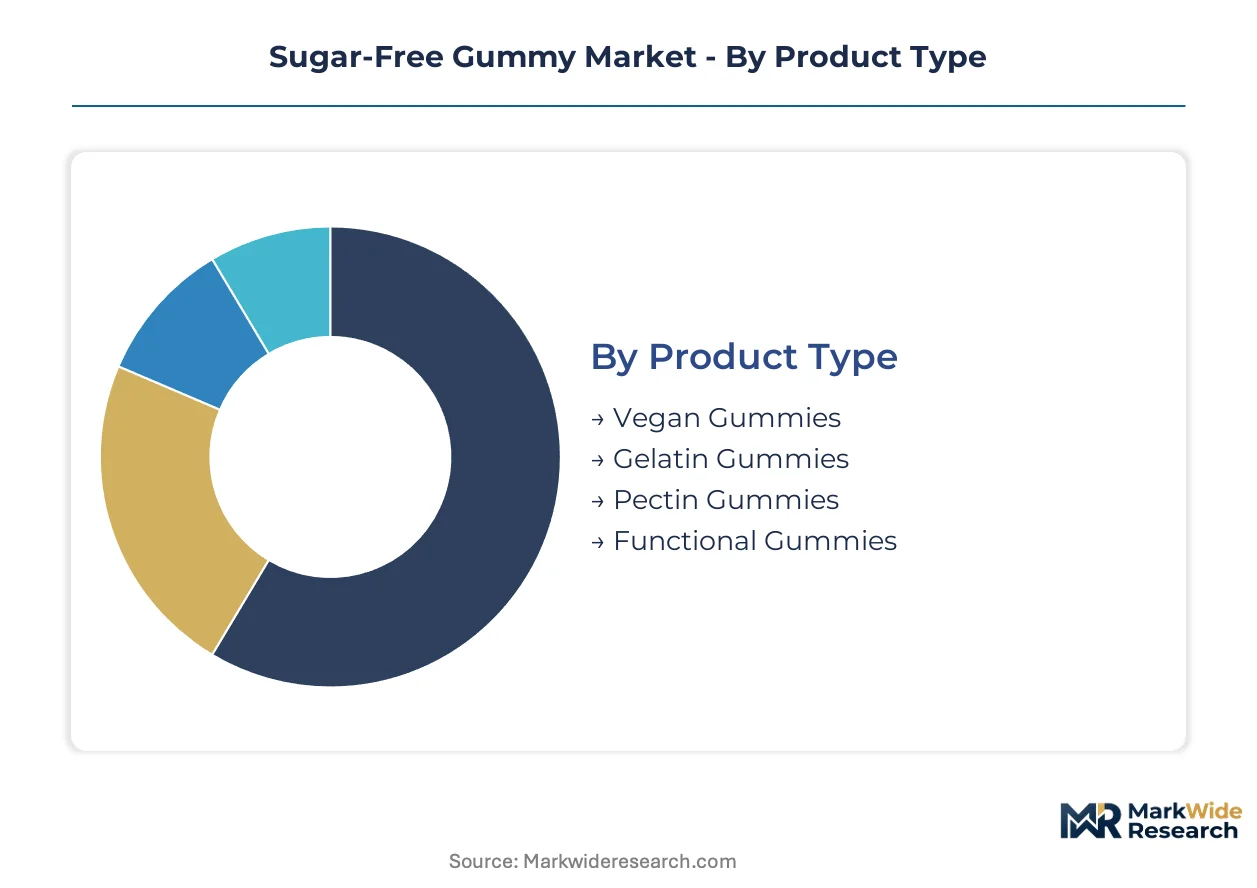
Sugar-free gummy manufacturers navigate formulation chemistry, regulatory compliance, and texture engineering simultaneously. Segmentation reveals where capital deployment concentrates and which technology platforms command premium positioning.
Product Type:
Gelling agent selection determines manufacturing capital intensity, vegan positioning eligibility, and active ingredient stability profiles.
- Gelatin Gummies:Bovine and porcine collagen hydrolysates create elastic, thermoreversible gel networks prized for traditional mouthfeel. Children's segments in Germany and the US sustain volume concentration despite sourcing constraints from European rendering facilities.
- Functional Gummies:Vitamin, mineral, and botanical matrices require precision depositing with temperature-controlled cooling tunnels to preserve heat-labile actives. Fitness enthusiasts seeking ashwagandha and adaptogen formulations are driving fastest adoption in subscription channels.
- Pectin Gummies:Citrus peel-derived amidated pectin forms thermally irreversible gels suited to vegan certification demands.
- Vegan Gummies:Carrageenan and agar alternatives serve strict plant-based positioning with texture trade-offs.
Mature deployment sits with Gelatin Gummies. Newer deployment is concentrated in Functional Gummies.
Flavor:
Flavor chemistry must mask polyol aftertastes while complying with EFSA novel food catalog entries for natural extract classifications.
- Berry Medley:Anthocyanin-rich fruit concentrates deliver antioxidant co-positioning with clean-label appeal. Adult wellness routines in Scandinavian health stores favor this profile for its functional ingredient synergy.
- Sour Citrus:Citric and malic acid blends enhance saliva stimulation to accelerate active ingredient buccal absorption. Fitness enthusiasts targeting pre-workout caffeine or electrolyte delivery prefer this sharpness profile.
- Fruit Punch:Multi-fruit flavor systems dominate children's segments where familiarity reduces trial barriers.
- Tropical Breeze:Mango-passionfruit extracts serve seasonal limited-edition strategies.
Volume leadership belongs to Fruit Punch. Steepest expansion trajectory is Sour Citrus.
Distribution Channel:
Channel selection determines margin structure, customer acquisition cost, and regulatory labeling exposure.
- Online Retail:Direct-to-consumer platforms enable subscription algorithms tied to microbiome testing results. Germany's urban millennials and Gen-Z supplement users are rotating fastest toward personalized replenishment models.
- Health Stores:Private-label chains in Germany dedicate expanded shelf space to sugar-free vitamin gummies, creating concentrated demand pull for contract manufacturers with EFSA compliance dossiers.
- Supermarkets:Impulse placement at checkout maintains largest volume share through visibility economics.
- Pharmacies:Clinical positioning requires OTC or supplement registration pathways.
Margin optimization concentrates in Online Retail. Volume scale remains with Supermarkets.
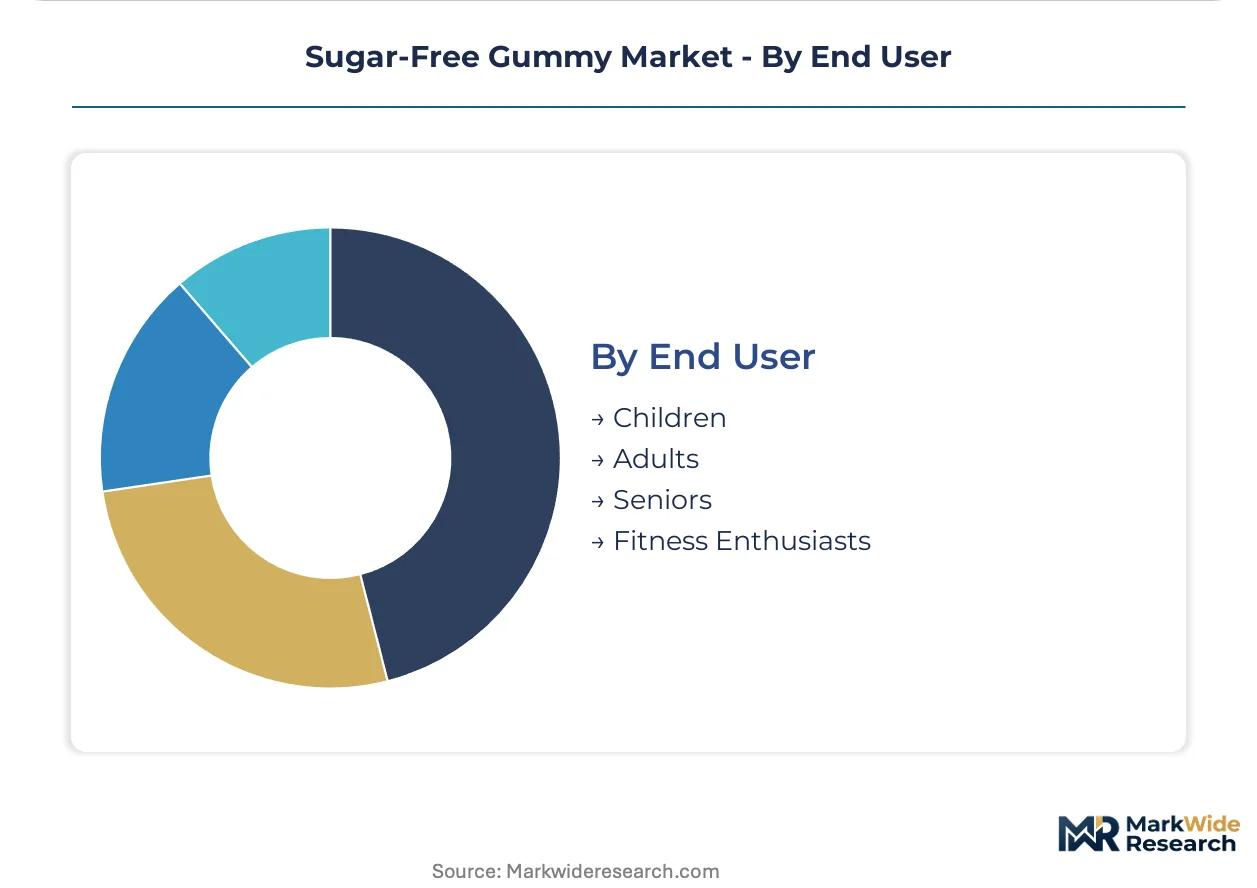
End User:
Demographic targeting shapes gelling system selection, active ingredient matrices, and packaging compliance requirements.
- Fitness Enthusiasts:Clean-label rejection of synthetic additives drives botanical-active formulations with transparent supply chains. Pre-workout caffeine, collagen peptides, and electrolyte matrices command premium positioning in subscription channels.
- Adults:Time-constrained professionals displace pill-based adherence with chewable vitamin and mineral fortification. India's FSSAI labeling tightening is preemptively reshaping export-oriented formulations for South Asian diaspora markets.
- Children:Texture preferences favor gelatin-based elasticity with controlled sugar-claim positioning.
- Seniors:Joint health and bone density actives require bioavailability-enhanced matrices.
Customer acquisition investment concentrates in Fitness Enthusiasts. Regulatory complexity sits with Adults.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyol sweetener production clusters in Germany and the Netherlands supply raw material foundations for European sugar-free gummy manufacturing, while pectin extraction facilities in Spain and Italy anchor southern supply chains.
Germany
Private-label health store chains are expanding sugar-free vitamin gummy shelf space across Berlin and Hamburg metropolitan corridors. EFSA novel food regulations are tightening ingredient approval pathways, forcing manufacturers to accelerate GRAS-compliant alternative submissions. Bavaria's contract manufacturing corridor near Munich concentrates precision depositing capacity for heat-labile active formulations.
United States
Fitness enthusiasts seeking clean-label supplements are driving functional gummy adoption through direct-to-consumer subscription channels. FDA GRAS determinations shape which sweetener systems gain commercial traction, with divergent approval timelines creating formulation fragmentation versus European counterparts. California's Los Angeles basin hosts wellness brand headquarters leveraging microbiome test integration for personalized gummy regimens.
India
Export-oriented manufacturers are targeting South Asian diaspora markets with reformulated sugar-claim positioning. FSSAI labeling requirements for confectionery are tightening, affecting product development timelines for international shipment preparation. Maharashtra's Mumbai-Pune industrial belt concentrates contract manufacturing capacity serving Middle Eastern and North American export destinations.
United Kingdom
Adult wellness routines are displacing pill-based supplement adherence among London's time-constrained professional demographic. EFSA novel food catalog entries apply through retained alignment mechanisms, preserving market access for steviol glycoside formulations. The Midlands manufacturing cluster around Birmingham maintains gelatin processing infrastructure for children's segment production.
China
Domestic demand for functional confectionery is expanding among urban middle-class consumers seeking vitamin fortification alternatives. NMPA dietary supplement regulations govern active ingredient claims, with GB standards applying to sweetener purity specifications. The Yangtze River Delta around Shanghai concentrates pectin and carrageenan gelling agent production for vegan-positioned export lines.
Sugar-Free Gummy Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and regulatory compliance capabilities. The vendor base stratifies between multinational confectionery conglomerates with captive R&D facilities and specialized contract manufacturers serving private-label health store chains. Three archetypes dominate: integrated confectionery giants with sugar-free portfolio extensions, dedicated functional gummy specialists with precision depositing expertise, and vegan-positioned pectin innovators serving botanical-active demand. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers securing EFSA compliance dossiers ahead of novel food catalog exclusions.
Within the integrated confectionery tier, Mars and Mondelēz occupy positions exemplifying multinational scale advantages in sweetener procurement and cross-border regulatory navigation. Among specialized functional manufacturers, Symbio-lab represents the pectin-alternative archetype for vegan certification demands, while TopGum Industries sits within the contract manufacturing segment serving private-label health store expansion. Haribo anchors traditional gelatin-based positioning in children's segments where texture preferences favor elastic mouthfeel, though this specialization faces sourcing constraints from European rendering facility concentration.
| Leading Market Players |
|---|
| TopGum Industries |
| Gumlink Confectionery Company |
| Mars |
| Parkacre Enterprises |
| Symbio-lab |
| Mondelēz |
| Haribo |
| Fermentis Life Sciences |
| Ferrero |
| Others |
Value Network & Pricing Analysis
Fitness enthusiasts' clean-label procurement preferences are forcing manufacturers toward botanical-active formulations with transparent supply chains, elevating ingredient certification costs and compressing margin structures for mid-scale producers unable to secure volume-scale polyol contracts.
Pricing Analysis
Subscription-based service bundling with microbiome testing and automated replenishment algorithms commands premium positioning versus unbundled supermarket impulse purchases. Three-tier pricing structure across premium functional gummies, standard vitamin fortification, and economy children's segments reflects certification grade differentiation and active ingredient complexity. Pricing pressure stems from maltitol cost volatility across regional procurement markets, with mid-scale contract manufacturers experiencing the steepest margin compression. Health store private-label buyers exhibit highest price sensitivity due to concentrated shelf-space negotiations, while direct-to-consumer wellness brands maintain pricing power through personalized regimen stickiness.
Supply Chain Analysis
EFSA novel food dossier preparation and FDA GRAS determination pathways function as certification gating mechanisms that filter supplier eligibility. Gelatin extraction draws from concentrated European rendering facilities in Germany and the Netherlands, while pectin supply centers on citrus peel processing in Spain and Italy. Raw material dependencies span polyol sweeteners, amidated pectin, and heat-labile active ingredients including probiotics and collagen peptides. Single-source vulnerability in bovine-derived gelatin creates structural exposure to regulatory restriction or supply disruption. Distribution runs through health store private-label chains, direct-to-consumer subscription platforms, and supermarket impulse placement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision depositing capacity scarcity for heat-labile active formulations is propping pricing power among qualified contract manufacturers, creating supply-constrained conditions that favor incumbents with certified production infrastructure.
For Market Incumbents: Cement formulation chemistry expertise advantages by acquiring specialized process engineering talent pools before competitor capacity expansion. Prioritize captive R&D facility investment in Germany's Bavarian manufacturing corridor to preempt EFSA novel food exclusion risks. Defend against pectin-alternative specialists by locking long-term gelatin supply contracts with European rendering facilities before sourcing constraints intensify. For New Entrants and Emerging Players: Direct-to-consumer subscription channels with microbiome test integration represent the most penetrable white-space opportunity, bypassing supermarket shelf-space barriers controlled by established brands. Target Germany's urban millennial and Gen-Z supplement users through personalized gummy regimens with automated reorder algorithms. Pursue white-label manufacturing partnerships with health store chains seeking EFSA-compliant private-label expansion. For Investors and Strategic Acquirers: The window for entry favors specialized functional gummy manufacturers with precision depositing expertise and existing EFSA compliance dossiers. Long-term viability hinges on botanical-active convergence capabilities beyond conventional vitamin matrices. Watch for steviol glycoside exclusion rulings from EFSA's novel food catalog as the inflection signal triggering accelerated consolidation among reformulation-lagged producers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Depositing Capacity Expansion | Captures heat-labile active formulation demand from wellness brands targeting gut microbiome and skin health positioning. |
| EFSA Novel Food Dossier Submission | Secures grandfathered status for erythritol-allulose blends ahead of potential steviol glycoside catalog exclusions. |
| Botanical-Active R&D Pipeline | Opens premium positioning beyond vitamin matrices through ashwagandha and adaptogen infusion capabilities. |
| Direct-to-Consumer Platform Launch | Captures recurring revenue from millennial and Gen-Z supplement users rotating away from supermarket impulse channels. |
| European Rendering Facility Partnership | Locks bovine gelatin supply against sourcing constraints from concentrated supplier geography. |
Research Methodology
Trade databases, EFSA novel food catalog entries, and customs records formed the secondary backbone, cross-referenced against primary interviews with contract manufacturing executives, health store category buyers, formulation chemistry directors, and regulatory affairs specialists. Bottom-up segmentation modeling triangulated against top-down macroeconomic trend analysis established volume and value estimates.
Historical trendline analysis across polyol sweetener procurement patterns, precision depositing technology deployment cycles, and channel rotation metrics informed projection assumptions. Segmentation dimensions modeled include gelling agent type, active ingredient matrix complexity, distribution channel structure, and end-user demographic targeting. CAGRs were derived from regression analysis of adoption curve penetration rates and regulatory approval timeline differentials.
The model holds under stable EFSA novel food classification frameworks and consistent polyol supply availability; deviation in regulatory exclusion rulings or gelatin sourcing disruptions would shift trajectory assumptions. A model refresh is warranted upon material change in EFSA steviol glycoside safety assessment outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Confectionery Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Confectionery Coating Market
Confectionery
Crunchy Chocolate Market
Confectionery
Sugar Free Lollipops Market
Confectionery
UK Chocolate Market
Confectionery
Fruit Jellies Market
Confectionery
Xylitol Lollipops Market
Confectionery
Middle East Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
Edible Glitter Market
Confectionery
Low Calorie Sweets Market
Confectionery
UK Compound Chocolate Market
Confectionery
Vegan Gummy Candy Market