
 Diet Candy Market | 2026-2036
Diet Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Diet Candy Market Analysis
China is rewriting production economics for diet confectionery through expanded stevia extraction and polyol manufacturing clusters in Guangxi and Shandong provinces. Nestlé leverages its Swiss R&D heritage to sustain premium positioning in sugar-free chocolate formulations across European pharmacies and North American club channels. Mars anchors its competitive set through scaled erythritol supply agreements and controlled distribution into Walmart and Target retail networks. Russell Stover specializes in seasonal sugar-free gift assortments that dominate the holiday confectionery aisle in U.S. mass retail.
Diet candy comprises confectionery products formulated with non-nutritive or reduced-calorie sweeteners—typically incorporating sugar alcohols such as maltitol and isomalt, high-intensity sweeteners including sucralose and steviol glycosides, or rare sugar allulose—to achieve caloric reduction of 25-50% versus conventional equivalents while maintaining comparable sensory profiles through modified crystallization and fat-bloom stabilization processes. Chocolate segments command disproportionate margin pools due to cocoa butter substitution complexity and premium positioning, while gummies experience accelerated formulation innovation as gelatin-free pectin bases with allulose gain traction among vegan and diabetic consumer segments. Hard candies occupy a mature volume position with stable diabetic channel penetration, whereas chewy candies face texture degradation challenges that limit sugar alcohol loading and constrain clean-label migration.
The FDA governs sweetener GRAS determinations and added-sugar disclosure requirements that directly dictate permissible formulations and front-of-package marketing claims for U.S.-distributed products. EFSA establishes Acceptable Daily Intake thresholds for intense sweeteners that shape European product portfolios and cross-border formulation standardization. Health Canada and the PMRA coordinate novel food approvals for emerging sweeteners including allulose, creating asynchronous market access timelines that fragment launch sequencing. Stakeholders must monitor evolving WHO guidance on non-sugar sweeteners and anticipate reformulation mandates as national dietary guidelines tighten added-sugar thresholds without explicit substitution pathways.
Market Dynamics
Sugar-reduction mandates from major U.S. food retailers are forcing accelerated reformulation timelines, compressing product development cycles from 18 months to under 12 months for clean-label confectionery launches.
Growth Catalysts
- FDA Added-Sugar Disclosure Rules:Front-of-package labeling requirements pressure conventional candy makers to develop reduced-calorie alternatives, expanding shelf space for diet formulations in American convenience retail.
- Steviol Glycoside Extraction Advances:Biotech fermentation methods in Chinese manufacturing clusters are lowering input costs for high-intensity sweeteners, enabling broader price accessibility across mass-market segments.
- Diabetic Channel Penetration:Pharmacy and medical nutrition retail networks in Germany and the United States are dedicating expanded fixture space to sugar-free confectionery as glucose management protocols integrate treat alternatives.
Market Restraints
- Erythritol Supply Concentration:Three Chinese producers control over 70% of global non-nutritive sweetener output, creating vulnerability to export restriction or input cost spikes in corn-derived feedstocks.
- Texture Degradation Thresholds:Sugar alcohol loading beyond 30% by weight in chewy candy formulations triggers crystallization and moisture migration, limiting clean-label migration in gummy and taffy segments.
- EFSA Daily Intake Ceilings:Acceptable Daily Intake thresholds for sucralose and aspartame constrain single-serve portion sizes in European formulations, complicating product standardization across Atlantic markets.
Strategic Opportunities
- Allulose Regulatory Tailwind:Health Canada and FDA novel food approvals for rare sugar allulose enable 70% calorie reduction with superior browning and freezing point depression versus polyol alternatives.
- Vegan Gelatin Substitution:Pectin-based gummy formulations with allulose sweetening unlock diabetic and plant-based consumer overlap previously excluded from animal-derived confectionery.
- Club Channel Expansion:Costco and Sam's Club warehouse formats in the United States are testing seasonal sugar-free gift assortments, validating bulk-pack diet candy economics beyond traditional pharmacy distribution.
Industry Challenges
- Fat-Bloom Stabilization Expertise:Cocoa butter substitution with shea and palm fractions in sugar-free chocolate requires specialized crystallization control talent scarce outside Swiss and Belgian processing centers.
- Cross-Border Formulation Synchronization:Asynchronous GRAS approvals between FDA and Health Canada force parallel product development tracks, inflating R&D overhead for North American market coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diet Candy Market |
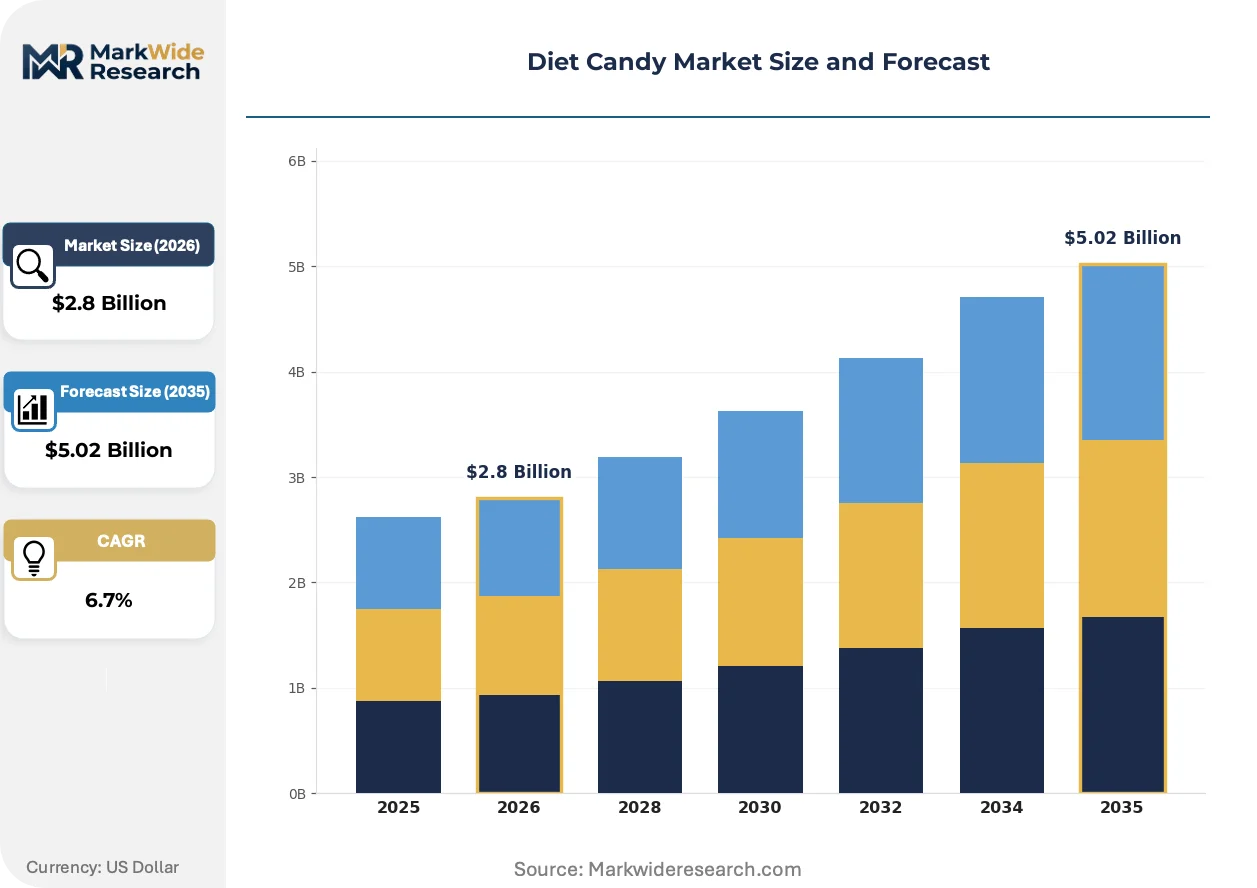
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewy Candies, Hard Candies, Gummies, Chocolate Ingredients: Low-Calorie Sweeteners, Natural Ingredients, Sugar-Free, Organic Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores Consumer Type: Health Conscious, Diabetics, Weight Watchers, Fitness Enthusiasts |
| Companies Covered | Carmit Candy, Canel, Nestlé, Toms Confectionary, The Hershey Company, Twizzlers TruJoy Sweets, Russell Stover, Tootsie Roll, Mars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diet Candy Market Emerging Trajectories
Clean-label migration is compressing artificial sweetener reliance while biotech-derived rare sugars and plant-based texturizers rewrite formulation economics. Three distinct vectors are reshaping competitive capability requirements.
Allulose is migrating from niche diabetic products to mainstream confectionery applications. Cargill and Ingredion are scaling fermentation-derived supply for North American chocolate and bakery segments. This migration from laboratory-scale production to industrial volume is collapsing the price premium versus erythritol, enabling mass-market penetration previously blocked by cost barriers.
EFSA's 2023 re-evaluation of sweetener safety profiles is tightening acceptable exposure thresholds for children and pregnant consumers. European manufacturers are reformulating with steviol glycoside blends to preempt portfolio restrictions. Hard candy and lozenge categories face the steepest compliance burden given their concentration of intense sweeteners per serving unit.
Millennial health-conscious buyers are consolidating purchase decisions through subscription direct-to-consumer channels. Thrive Market and iHerb are disintermediating traditional pharmacy and mass retail for recurring sugar-free confectionery orders. California and New York metropolitan areas exhibit the highest subscription conversion rates, correlating with diabetes prevalence and wellness expenditure intensity.
Diet Candy Market Segmentation
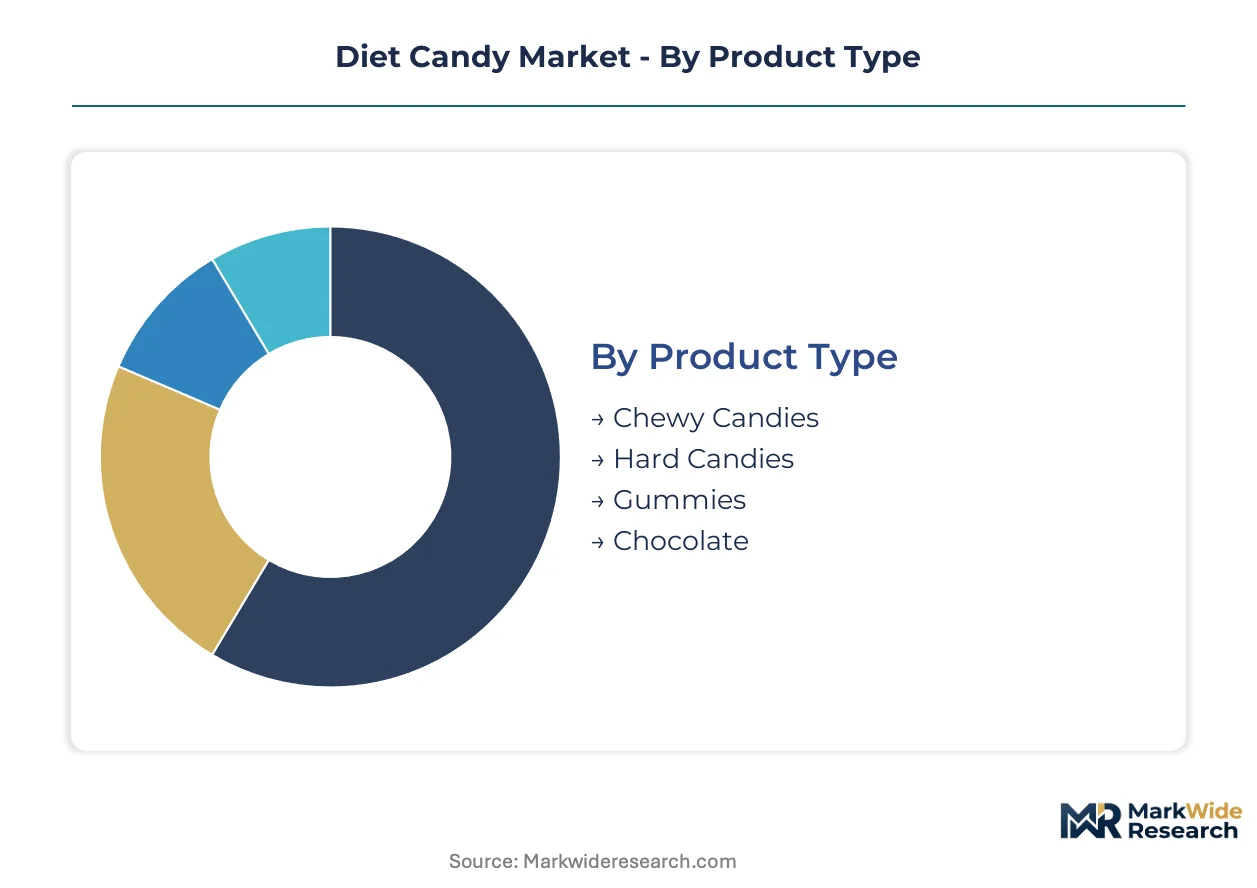
Diet candy segmentation reveals distinct formulation and channel strategies across product formats, with each category demanding specialized sweetener engineering and targeted retail placement. Understanding these divisions enables precise resource allocation toward high-margin segments and emerging consumption occasions.
Product Type:
The use-case spectrum spans impulse convenience purchases to premium gift occasions, with each format requiring distinct crystallization control and shelf-stability engineering.
- Chocolate:Cocoa butter substitution with shea and palm fractions demands specialized fat-bloom stabilization. Swiss and Belgian processing centers concentrate technical expertise, while U.S. club channels validate bulk-pack economics for seasonal assortments.
- Gummies:Pectin-based formulations with allulose sweetening unlock diabetic and plant-based consumer overlap previously excluded from animal-derived confectionery. California and New York metropolitan areas exhibit the highest subscription conversion rates through direct-to-consumer channels.
- Chewy Candies:Sugar alcohol loading beyond 30% by weight triggers crystallization and moisture migration, constraining clean-label migration in taffy and caramel segments.
- Hard Candies:Stable diabetic channel penetration with concentration-dependent intense sweetener compliance burdens under EFSA exposure thresholds.
The dominant share belongs to Chocolate, while Gummies is closing the gap fastest.
Ingredients:
Cost tier differentiation separates premium positioning from mass-market accessibility, with fermentation scale determining input economics.
- Sugar-Free:Erythritol supply agreements anchor Mars distribution into Walmart and Target networks, though three Chinese producers control over 70% of global non-nutritive sweetener output.
- Low-Calorie Sweeteners:Steviol glycoside extraction advances in Guangxi and Shandong provinces are lowering input costs for high-intensity sweeteners, enabling broader price accessibility.
- Natural Ingredients:Clean-label migration compresses artificial sweetener reliance while biotech-derived rare sugars rewrite formulation economics.
- Organic:Certification requirements limit supplier pools and extend procurement timelines for cocoa and fruit-derived inputs.
Sugar-Free commands volume leadership, though Low-Calorie Sweeteners is expanding most quickly through stevia fermentation scale-up.
Distribution Channel:
Customer type concentration varies sharply by channel, with pharmacy networks serving protocol-driven diabetic consumers versus discretionary wellness buyers in club formats.
- Supermarkets:Sugar-reduction commitments from major U.S. food retailers accelerate shelf-space reallocation toward low-calorie confectionery alternatives in convenience retail.
- Online Retail:Millennial health-conscious buyers consolidate purchase decisions through subscription channels, with Thrive Market and iHerb disintermediating traditional pharmacy and mass retail for recurring orders.
- Specialty Stores:Premium positioning leverages Swiss R&D heritage for sugar-free chocolate formulations across European pharmacy networks.
- Health Food Stores:Expanded fixture space dedication for sugar-free confectionery as glucose management protocols integrate treat alternatives in Germany and the United States.
Supermarkets retain the largest footprint, while Online Retail is gaining share fastest through subscription model adoption.
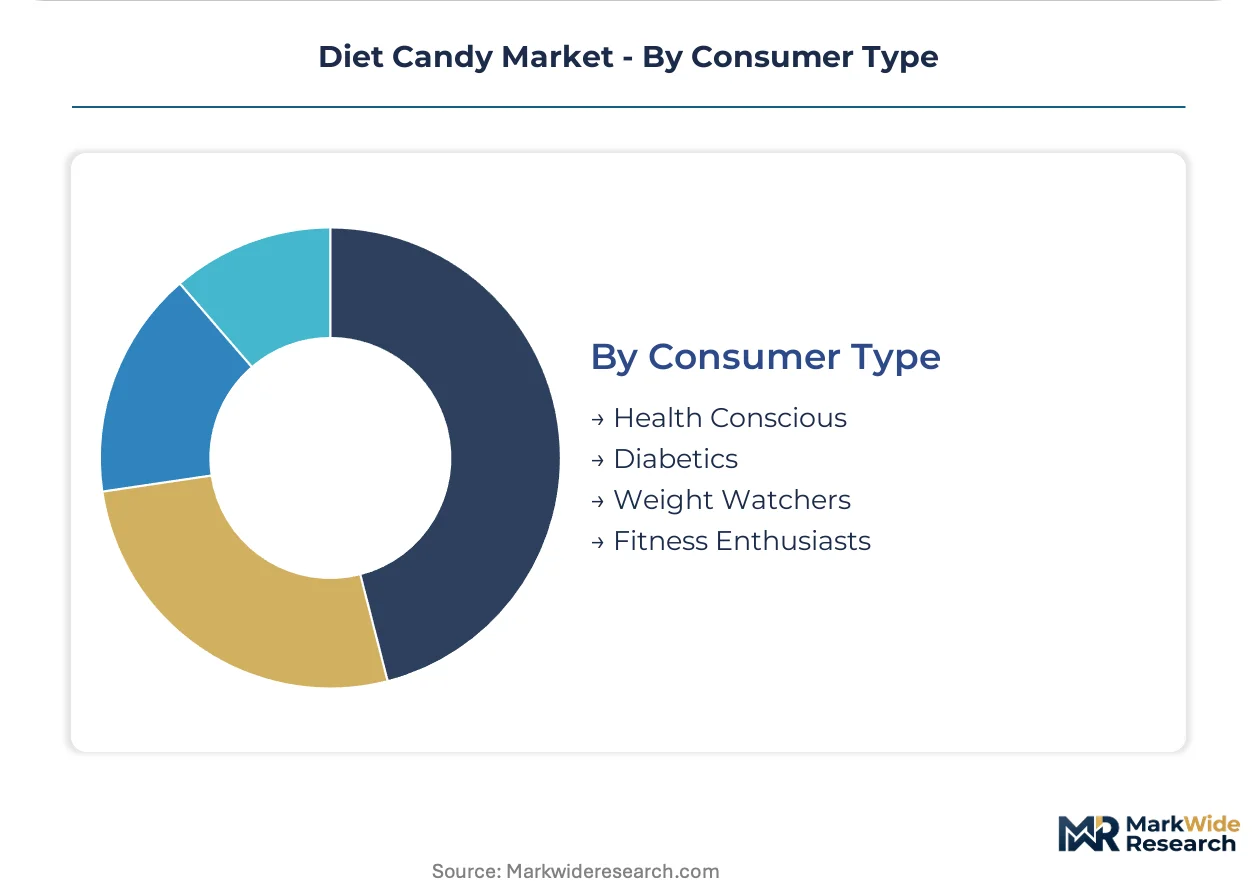
Consumer Type:
Application intensity correlates with dietary restriction severity, from discretionary wellness to medical nutrition integration.
- Diabetics:Pharmacy and medical nutrition retail networks dedicate expanded fixture space as glucose management protocols formalize treat alternatives into care pathways.
- Health Conscious:Health-conscious millennials drive adoption across North American convenience retail channels, consolidating purchase decisions through wellness expenditure.
- Weight Watchers:Caloric reduction of 25-50% versus conventional equivalents aligns with portion-controlled dietary frameworks.
- Fitness Enthusiasts:Protein-enhanced and electrolyte-infused formulations target post-workout recovery occasions with clean-label positioning.
Diabetics anchor medical channel penetration, though Health Conscious consumers are climbing the fastest through millennial wellness expenditure intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA added-sugar disclosure requirements anchor the United States as the regulatory benchmark for diet confectionery formulation. Health-conscious millennials and sugar-reduction commitments from major food retailers drive shelf-space reallocation toward low-calorie alternatives.
United States
Millennial wellness expenditure and diabetic channel penetration propel demand through pharmacy and convenience retail networks. FDA Nutrition Facts labeling rules for added sugars reshape permissible formulations and front-of-package marketing claims. Pennsylvania and Illinois processing centers concentrate chocolate fat-bloom stabilization expertise for sugar-free seasonal assortments.
Germany
Pharmacy network expansion for glucose management protocols integrates sugar-free confectionery into formal care pathways. EFSA Acceptable Daily Intake thresholds for intense sweeteners constrain single-serve portion sizes and complicate Atlantic product standardization. Bavarian and North Rhine-Westphalian manufacturing clusters specialize in steviol glycoside blending for hard candy compliance.
China
Biotech fermentation scale-up in stevia extraction and polyol manufacturing collapses input costs for high-intensity sweeteners. SAMR novel food approvals and dual carbon goals shape clean-label migration timelines for domestic producers. Guangxi and Shandong province clusters dominate global erythritol output, controlling over 70% of non-nutritive sweetener supply.
Switzerland
Premium positioning in European pharmacy and North American club channels leverages heritage R&D infrastructure for cocoa butter substitution. Swissmedic food safety standards and novel ingredient approvals enable rapid formulation iteration for rare sugar applications. Zurich and Geneva processing centers concentrate specialized crystallization control talent scarce outside Belgian competitors.
Canada
Asynchronous GRAS approvals with FDA force parallel product development tracks for North American market coverage. Health Canada and PMRA novel food approvals for allulose create regulatory tailwinds for 70% calorie reduction formulations. Ontario and Quebec distribution hubs test bulk-pack sugar-free gift economics through Costco and Sam's Club warehouse formats.
Diet Candy Market Vendor Landscape
Capability concentration sits with European heritage processors; scale advantage sits with North American mass-market distributors. The market structures around three tiers: premium Swiss and Belgian chocolate specialists, scaled CPG conglomerates with retail network anchoring, and seasonal gift assortment specialists with pharmacy channel dominance. Strategic moves concentrate on stevia fermentation supply agreements and allulose regulatory first-mover positioning.
Within the heritage-processing tier, Nestlé represents premium sugar-free chocolate formulation capability, while Mars exemplifies scaled erythritol supply integration with mass retail distribution control. Russell Stover occupies the seasonal gift assortment niche, anchoring holiday aisle penetration through sugar-free product lines. These three archetypes illustrate how technical specialization, supply security, and channel access define competitive position.
| Leading Market Players |
|---|
| Carmit Candy |
| Canel |
| Nestlé |
| Toms Confectionary |
| The Hershey Company |
| Twizzlers TruJoy Sweets |
| Russell Stover |
| Tootsie Roll |
| Mars |
| Others |
Supply Flow & Price Mechanics
Erythritol supply concentration in Chinese manufacturing clusters creates dual vulnerability to export restriction and corn feedstock volatility, compressing margin spreads between premium Swiss chocolate formulations and mass-market private-label alternatives while forcing buyers toward multi-source sweetener hedging strategies.
Pricing Analysis
North American club channels command 15-25% premiums over European pharmacy networks for identical sugar-free chocolate assortments, reflecting bulk-pack economics and seasonal gift positioning. Three-tier pricing structure across premium Swiss heritage brands, scaled CPG conglomerates, and private-label alternatives stratifies by cocoa butter substitution complexity and certification tier. Pricing pressure stems from stevia fermentation scale-up in Guangxi province collapsing input costs for high-intensity sweeteners. Health-conscious millennials in subscription channels exhibit lowest price sensitivity, while diabetic channel buyers in mass retail show highest elasticity to per-unit cost.
Supply Chain Analysis
Corn-derived feedstock processing in China, Belgium, and the United States anchors upstream erythritol and allulose production, with fermentation capacity expansion in Shandong province outpacing North American chemical synthesis. Raw material dependencies center on stevia leaf extraction, polyol hydrogenation catalysts, and cocoa butter equivalents from shea and palm fractions. Single-source vulnerability concentrates in three Chinese producers controlling bulk non-nutritive sweetener output. Distribution runs through Walmart and Target retail networks for mass-market penetration, with pharmacy and club channels serving protocol-driven diabetic and wellness consumer segments respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against functional snack bars and protein confectionery encroaching on treat occasions, as clean-label migration blurs category boundaries between indulgence and nutrition.
For Market Incumbents: Harden formulation moats through captive allulose supply agreements with Cargill or Ingredion, locking in rare sugar access before price parity with erythritol erodes premium positioning. Deepen Swiss and Belgian processing center relationships to secure fat-bloom stabilization talent scarce outside heritage chocolate clusters. Defend pharmacy channel fixtures against functional snack displacement by integrating glucose management protocol endorsements.
For New Entrants and Emerging Players: Build out pectin-based gummy capabilities targeting vegan-diabetic consumer overlap in California and New York metropolitan subscription channels, where wellness expenditure intensity supports premium pricing. White-space concentrates in seasonal sugar-free gift assortments for Costco and Sam's Club testing programs, validating bulk-pack economics beyond traditional pharmacy distribution. Go-to-market leverage rests on direct-to-consumer subscription models disintermediating incumbent retail networks.
For Investors and Strategic Acquirers: The market sits at a regulatory arbitrage phase that favors first-movers in allulose formulation approvals across asynchronous FDA and Health Canada timelines. Long-term viability hinges on fermentation scale economics collapsing input costs for rare sugars over the 5-10 year window. Acquisition targets with stevia extraction agreements or pectin texturizer capabilities offer defensive positioning. Watch EFSA sweetener re-evaluation thresholds as inflection signal for European portfolio restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Allulose Supply Agreement | Captive rare sugar access from Cargill or Ingredion secures 70% calorie reduction formulation lead. |
| Pectin-Based Gummy Launch | Vegan gelatin substitution unlocks diabetic-plant-based consumer overlap in subscription channels. |
| Club Channel Expansion | Costco and Sam's Club seasonal testing validates bulk-pack economics beyond pharmacy distribution. |
| Swiss Processing Partnership | Heritage fat-bloom stabilization expertise differentiates premium sugar-free chocolate positioning. |
| Direct-to-Consumer Subscription | Thrive Market and iHerb disintermediation captures recurring wellness expenditure from millennials. |
Methodological Framework
Operator-level perspectives from brand managers, category buyers at Walmart and Target, pharmacy procurement leads, and stevia extraction plant managers anchored the qualitative base. Primary interview findings combined with secondary validation from FDA GRAS filings, Health Canada novel food approvals, Nielsen retail audit data, and EFSA safety re-evaluation documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing around regulatory approval timelines, fermentation scale economics, and retail shelf-space reallocation shaped the analytical framework. Segmentation dimensions modeled include product format, sweetener technology tier, distribution channel archetype, and consumer dietary restriction severity. CAGRs derived from elasticity-adjusted volume projections incorporating stevia price collapse curves and allulose adoption S-curves. Forecast inputs center on EFSA exposure threshold compliance burdens and Chinese export policy volatility.
Sensitivities concentrate around asynchronous GRAS approvals fragmenting North American launch sequencing and erythritol supply disruption from Chinese environmental enforcement. Forecasts reflect assumptions on clean-label migration velocity and club channel adoption curves. Quarterly review of FDA allulose labeling guidance, EFSA sweetener re-evaluations, and Chinese dual carbon policy implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Durian Chocolate Market
Confectionery
Global Candy Market
Confectionery
Xylitol Lollipops Market
Confectionery
Chocolate Spread Market
Confectionery
US Confectionery Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Licorice Candy Market
Confectionery
Caramel Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
Confectionery Fats Market
Confectionery
United States Chocolate Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Middle East and Africa Premium Chocolate Market