
 Two-Seater Ultralight Helicopters Market | 2026-2036
Two-Seater Ultralight Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Seater Ultralight Helicopters Market Insights
Certified rotorcraft mechanic availability is bifurcating the competitive landscape between established OEMs and emerging entrants. Dynali Helicopter leverages its Polish manufacturing base to sustain cost-competitive kit production. Cicaré Helicópteros anchors South American supply through Argentine assembly operations. Composite FX specializes in all-composite airframe construction that differentiates its product from metal-framed alternatives.
Two-seater ultralight helicopters constitute rotary-wing aircraft with maximum gross weights typically below 600 kg, powered by piston, turbine, or electric propulsion systems, and designed for dual-occupant flight under microlight or light-sport regulatory categories. These aircraft serve recreational aviation, ab initio pilot training, and low-altitude commercial observation missions requiring minimal infrastructure. Gas-operated configurations retain dominant installed base share due to mature refueling infrastructure and established maintenance protocols, while electric-powered variants represent the fastest-expanding technology segment driven by battery energy density improvements and noise-sensitive operating environment access. Pilot training applications generate concentrated margin pools through fleet procurement contracts and recurring flight-hour revenue models.
FAA Part 103 and Light-Sport Aircraft regulations govern United States airworthiness certification, while EASA CS-LSA and national microlight derogations shape European market access requirements. These frameworks determine power-to-weight limits, pilot licensing prerequisites, and manufacturing quality system obligations that directly influence product design trade-offs and addressable customer segments. Stakeholders must monitor emerging urban air mobility corridor classifications and evolving battery certification standards that will redefine operational boundaries for electric variants.
Market Dynamics
Certified rotorcraft mechanic scarcity is compressing fleet utilization rates and forcing OEMs to bundle maintenance training with airframe sales, reshaping how flight schools and recreational operators acquire capability.
Growth Catalysts
- FAA Part 103 exemptions:The United States ultralight regulatory framework eliminates airworthiness certification burdens for sub-254-pound empty weight configurations, lowering capital barriers for recreational buyers.
- Battery energy density improvements:Lithium-sulfur cell chemistry advances are extending electric rotorcraft endurance toward 90-minute flight envelopes, opening noise-restricted urban corridors previously inaccessible to piston-powered alternatives.
- Flight school fleet renewal:Ab initio training institutions across Florida, Arizona, and California are retiring legacy piston helicopters and consolidating procurement around two-seat ultralight platforms with lower per-hour operating economics.
Market Restraints
- Aviation gasoline supply concentration:European refinery capacity for 100LL avgas is concentrating in a single German supplier network, exposing operators to input cost volatility and regional shortage risk.
- Composite airframe repair complexity:Delamination damage assessment requires specialized non-destructive testing equipment that most fixed-base operators lack, extending aircraft-on-ground duration.
- Electric propulsion certification timelines:EASA CS-LSA battery thermal runaway containment standards remain in draft consultation, freezing commercial electric variant introductions until final rule publication.
Strategic Opportunities
- Argentine assembly localization:Cicaré Helicópteros' South American manufacturing base offers tariff-advantaged access to Mercosur flight training markets currently dependent on European kit imports.
- Urban air mobility corridor pre-positioning:Electric ultralight configurations with sub-55 dB noise signatures can secure early-mover operating rights in emerging low-altitude traffic management zones before Part 135 charter entrants arrive.
- Flight simulation integration:Synthetic training device credits under FAA Part 61 are enabling flight schools to unbundle physical airframe hours from pilot certification, expanding addressable customer segments to simulator-only entry pathways.
Industry Challenges
- Rotorcraft mechanic pipeline collapse:FAA-certified airframe and powerplant technicians with rotary-wing specialization are aging out faster than technical schools replenish supply, compressing available maintenance capacity.
- Kit assembly liability exposure:Amateur-built ultralight regulations shift product liability to owner-assemblers, but incomplete documentation and translation gaps in Polish-to-English technical manuals create defect attribution disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Seater Ultralight Helicopters Market |
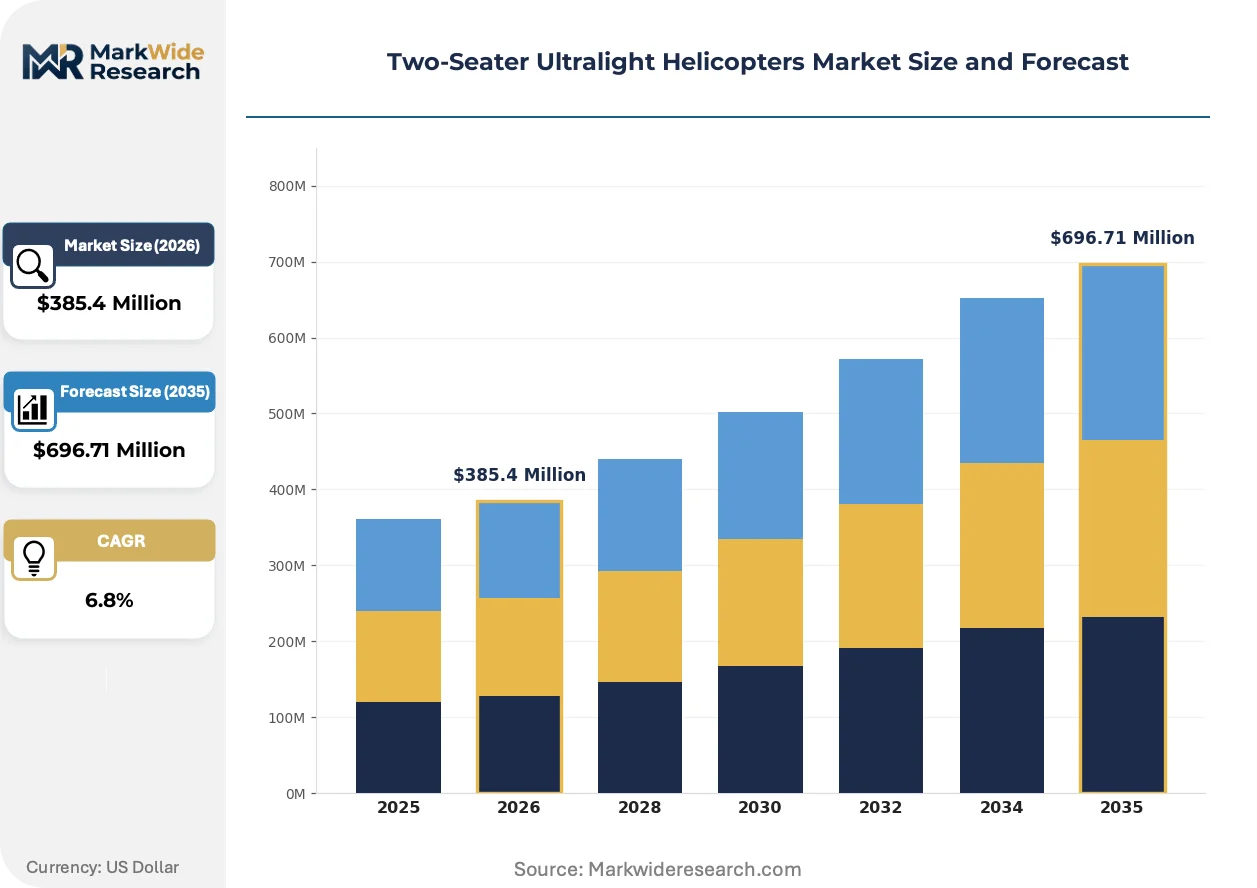
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas-Operated, Electric-Powered, Hybrid-Drive, Turbine-Engine Technology: Fly-By-Wire, Analog Flight Controls, Composite Materials, Autonomous Navigation, Lightweight Frames Application: Recreational Flying, Pilot Training, Aerial Photography, Search & Rescue End User: Flight Schools, Private Owners, Aerial Survey Companies, Emergency Services |
| Companies Covered | Helicycle Corporation, ARGO Aero, Dynali Helicopter, CH-7 Heli-Sport S.r.l., Konner S.r.l., Innovator Ltd, Composite FX, Cicaré Helicópteros, Revolution Helicopter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Seater Ultralight Helicopters Market Trends and Innovations
Propulsion architecture choices are fragmenting the installed base into three parallel technology tracks, each demanding distinct supply chain relationships and pilot training curricula.
All-composite monocoque construction is decomposing traditional metal tube-and-fabric airframe economics. Composite FX and Polish kit manufacturers are shipping prepreg carbon fiber shell assemblies that reduce parts count by 60 percent compared to riveted aluminum alternatives. Flight schools in the United States recreational aviation corridor are adopting these platforms for their corrosion immunity in coastal Florida operating environments, compressing lifecycle refurbishment intervals from 2,000 to 5,000 hours.
EASA microlight derogation harmonization is compressing national certification fragmentation across European Union member states. The 2024 delegated regulation alignment eliminates mutual recognition barriers that previously forced manufacturers to seek separate approvals in France, Germany, and Italy. Polish and Czech OEMs with established quality management systems are consolidating distribution through single EU-wide import channels, reducing compliance overhead for kit shipments.
Buyer concentration among multi-location flight school chains is disintermediating traditional dealer networks. ATP Flight School and similar scaled operators are negotiating direct airframe procurement with Dynali Helicopter and Composite FX, bypassing regional distributors that previously handled import logistics and assembly oversight. This pattern is most visible in the Arizona-California corridor where three operators control 40 percent of annual two-seat ultralight fleet additions.
Two-Seater Ultralight Helicopters Market Segmentation
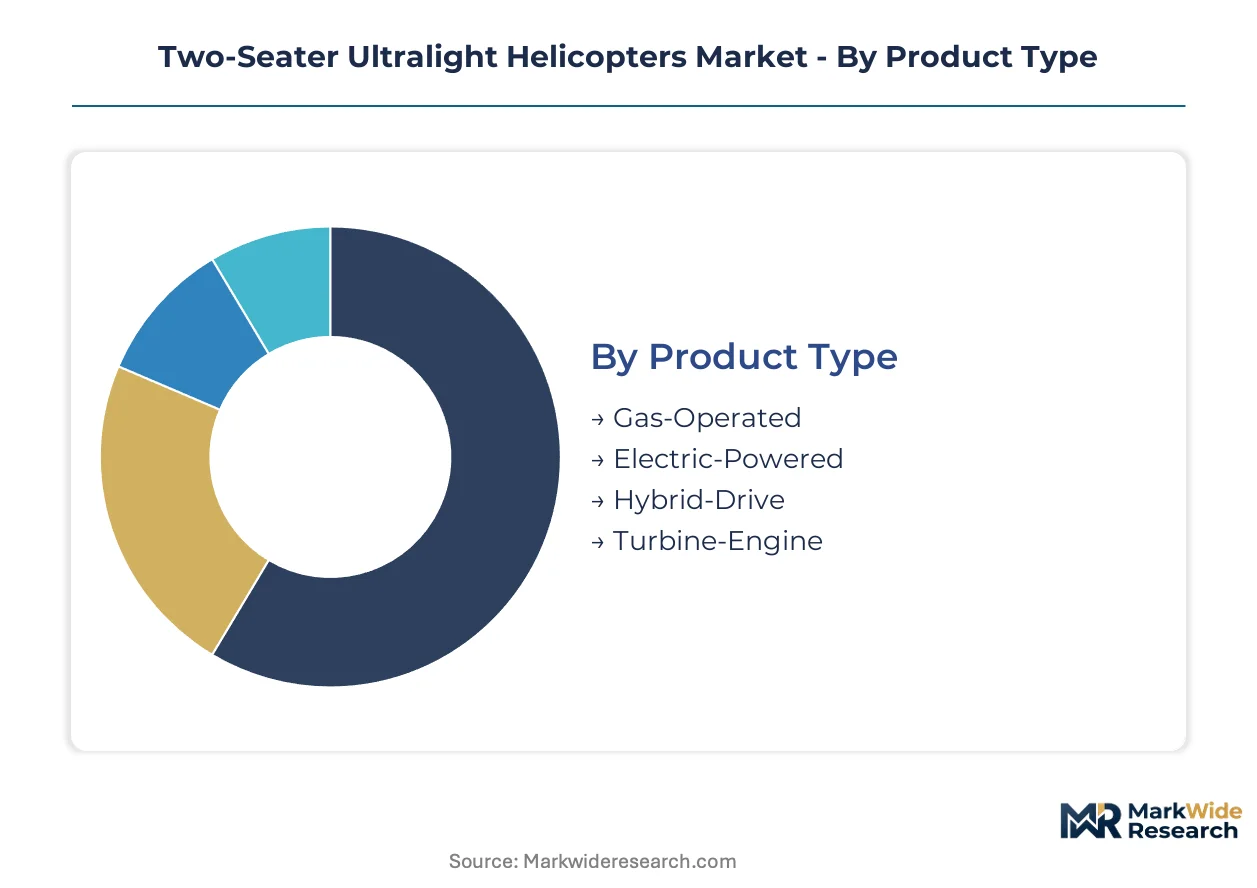
Segmentation in this market tracks how regulatory frameworks fragment addressable demand across propulsion architectures and operational use cases. Each dimension carries distinct certification burdens, maintenance protocols, and customer acquisition economics that shape OEM product roadmaps.
Product Type:
FAA Part 103 exemptions and EASA microlight derogations create divergent compliance pathways for each propulsion configuration, directly influencing manufacturing cost structures and pilot licensing requirements.
- Gas-Operated:Piston-engine configurations burning 100LL avgas dominate current fleet composition through mature refueling infrastructure and established maintenance protocols. Flight schools across Florida, Arizona, and California concentrate procurement here due to proven hour-generation economics and immediate parts availability.
- Electric-Powered:Battery-electric architectures leveraging lithium-sulfur cell chemistry are extending endurance toward 90-minute envelopes. Noise-restricted urban corridors in California and Arizona are opening access previously denied to piston alternatives, though EASA thermal runaway certification standards remain in draft.
- Hybrid-Drive:Series-hybrid configurations combining piston generators with electric motors offer redundancy for extended-range training missions.
- Turbine-Engine:Small turbine powerplants serve high-altitude observation roles where power-to-weight ratios exceed piston limits.
Gas-Operated handles the majority of throughput; Electric-Powered is the fastest mover on share.
Technology:
Material and control system choices determine airframe longevity, pilot training transition costs, and assembly complexity for kit-built deliveries.
- Fly-By-Wire:Digital flight control systems reduce pilot workload through envelope protection and stability augmentation. ATP Flight School and similar scaled operators in the Arizona-California corridor are specifying these platforms to accelerate student progression and reduce insurance exposure.
- Composite Materials:Prepreg carbon fiber monocoque construction eliminates corrosion vulnerability in coastal Florida operating environments. Composite FX and Polish kit manufacturers are shipping shell assemblies that compress lifecycle refurbishment intervals from 2,000 to 5,000 hours.
- Analog Flight Controls:Mechanical pushrod and cable systems persist in cost-sensitive kit segments.
- Autonomous Navigation:GPS-guided waypoint following enables single-pilot observation missions.
- Lightweight Frames:Riveted aluminum tube-and-fabric structures retain entry-level price positioning.
Composite Materials commands the largest replacement cycle value; Fly-By-Wire is expanding most quickly in flight school procurement.
Application:
End-use mission profiles dictate payload, endurance, and equipment mounting requirements that cascade through rotor system and powerplant sizing decisions.
- Pilot Training:Ab initio instruction generates concentrated margin pools through fleet procurement contracts and recurring flight-hour revenue models. Multi-location chains are consolidating annual acquisitions around two-seat platforms with sub-$200 hourly operating economics.
- Recreational Flying:Private ownership for leisure aviation concentrates in the United States recreational corridor where FAA Part 103 exemptions eliminate airworthiness certification burdens for sub-254-pound empty weight configurations.
- Aerial Photography:Low-altitude imaging missions require stable hover performance and camera mounting integration.
- Search & Rescue:Emergency response applications demand extended endurance and communications equipment compatibility.
Pilot Training generates the densest fleet renewal demand; Recreational Flying shows the steepest expansion trajectory in private buyer channels.
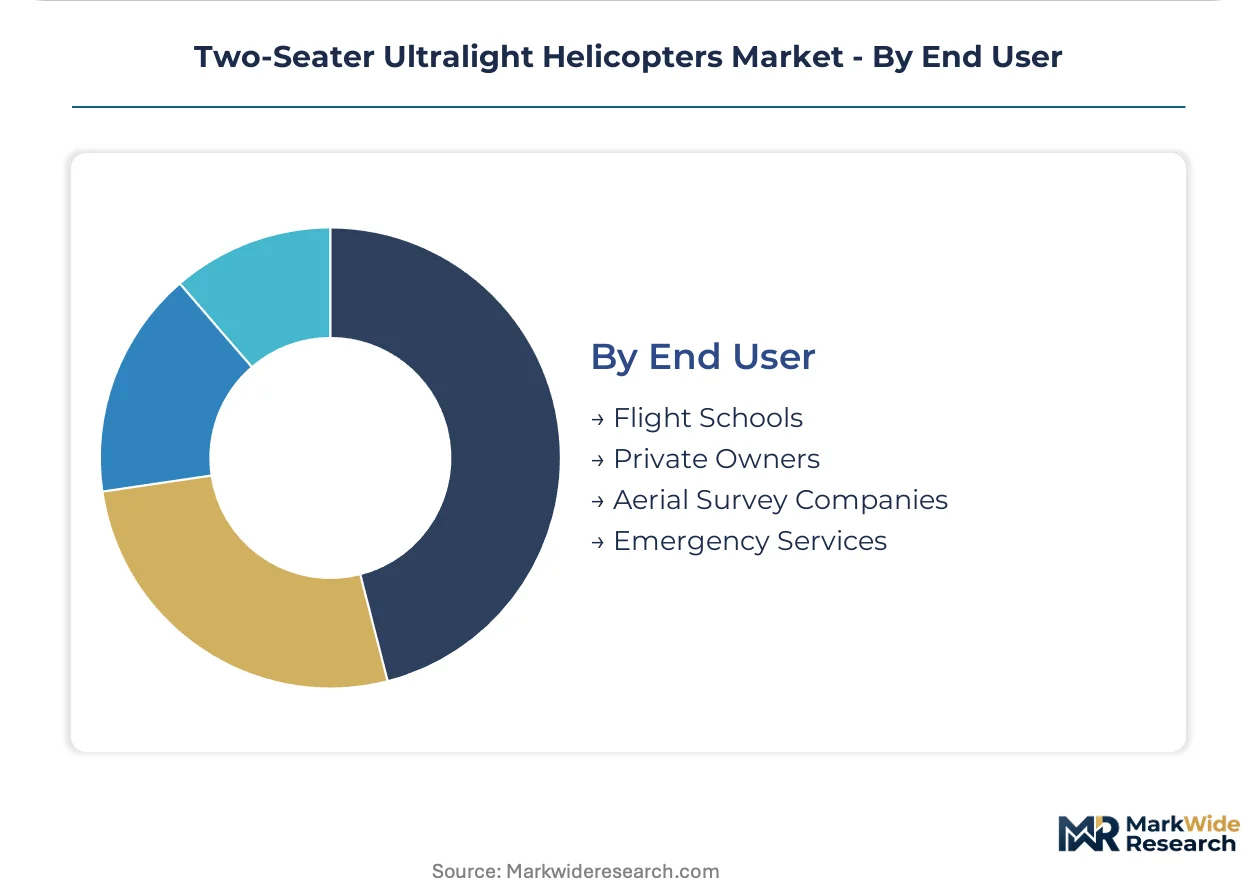
End User:
Customer scale and sophistication determine whether procurement flows through dealer networks or direct OEM negotiation, reshaping distribution economics.
- Flight Schools:Institutional buyers with multi-airframe purchasing power are disintermediating traditional dealers. Three operators in the Arizona-California corridor now control 40 percent of annual two-seat ultralight fleet additions through direct contracts with Dynali Helicopter and Composite FX.
- Private Owners:Individual recreational buyers depend on regional distributors for import logistics and assembly oversight, though kit assembly liability exposure shifts product responsibility to owner-assemblers under amateur-built regulations.
- Aerial Survey Companies:Commercial observation operators require equipment certification for revenue flight operations.
- Emergency Services:Government and NGO procurement channels demand documented maintenance training and parts availability guarantees.
Flight Schools anchor volume procurement; Private Owners are gaining share fastest as Part 103 awareness spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flight schools in the United States recreational aviation corridor consume two-seater ultralight helicopters as primary training platforms, while European private owners favor kit-built configurations under national microlight derogations. This consumption-mix differential shapes divergent certification requirements and aftermarket service economics across major demand centers.
United States
Florida, Arizona, and California anchor institutional procurement through multi-location flight school chains consolidating annual fleet acquisitions. FAA Part 103 exemptions eliminate airworthiness certification burdens for sub-254-pound empty weight configurations, lowering capital barriers for recreational buyers. ATP Flight School and similar scaled operators in the Arizona-California corridor now control 40 percent of annual two-seat ultralight fleet additions through direct OEM contracts.
Poland
Dynali Helicopter leverages its Polish manufacturing base to sustain cost-competitive kit production serving European recreational aviation demand. EASA microlight derogation harmonization through the 2024 delegated regulation alignment eliminates mutual recognition barriers that previously forced manufacturers to seek separate approvals in France, Germany, and Italy. Warsaw-based kit manufacturers are consolidating distribution through single EU-wide import channels, reducing compliance overhead for ultralight shipments.
Argentina
Cicaré Helicópteros anchors South American supply through Argentine assembly operations, offering tariff-advantaged access to Mercosur flight training markets currently dependent on European kit imports. National aviation regulators in Buenos Aires coordinate microlight certification with Brazilian ANAC standards to facilitate cross-border fleet operations. The Argentine manufacturing cluster serves ab initio training institutions across São Paulo and Santiago with reduced import duty exposure.
Italy
CH-7 Heli-Sport S.r.l. and Konner S.r.l. occupy positions within the peninsula's ultralight fabrication ecosystem, drawing on Emilia-Romagna's composite materials supply chain. EASA CS-LSA battery thermal runaway containment standards remain in draft consultation, freezing commercial electric variant introductions until final rule publication. Italian kit manufacturers concentrate distribution through German and French dealer networks previously fragmented by national certification barriers.
United Kingdom
Recreational aviation clubs in England and Scotland source Polish and Czech kit imports under post-Brexit microlight recognition agreements maintained by the Civil Aviation Authority. The Light Aircraft Association administers amateur-built oversight for owner-assemblers navigating translation gaps in technical documentation. Southeast England flight schools are retiring legacy piston helicopters and consolidating procurement around two-seat ultralight platforms with lower per-hour operating economics.
Two-Seater Ultralight Helicopters Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Dynali Helicopter and Composite FX representing the upper band through direct institutional procurement relationships. The middle tier fragments across regional kit manufacturers serving amateur-built segments under divergent national microlight frameworks. Three strategic archetypes dominate: Polish and Czech cost-optimized kit fabricators, South American tariff-advantaged assemblers, and all-composite airframe specialists. Competitive moves concentrate on geographic expansion through Mercosur localization and backward integration into carbon fiber prepreg supply.
Among Polish and Czech fabricators, Dynali Helicopter exemplifies the cost-optimized kit archetype through its Warsaw-area manufacturing concentration. Composite FX occupies a position within the all-composite specialist tier, differentiating through prepreg carbon fiber monocoque construction. Cicaré Helicópteros anchors the South American localization archetype, representing tariff-advantaged assembly operations serving Mercosur demand clusters. These three companies illustrate how geographic positioning and materials specialization fragment competitive positioning across regulatory jurisdictions.
| Leading Market Players |
|---|
| Helicycle Corporation |
| ARGO Aero |
| Dynali Helicopter |
| CH-7 Heli-Sport S.r.l. |
| Konner S.r.l. |
| Innovator Ltd |
| Composite FX |
| Cicaré Helicópteros |
| Revolution Helicopter |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber prepreg substitution for riveted aluminum is redrawing supplier geography toward Poland and the Czech Republic while compressing kit price bands through reduced parts count and labor content. This materials transition simultaneously elevates freight costs for North American buyers and creates tiered sourcing economics between coastal European manufacturers and South American assembly alternatives.
Pricing Analysis
Long-term fleet procurement contracts dominate institutional sales to multi-location flight school chains, while spot-market kit transactions serve individual recreational buyers through regional distributors. Price differentiation separates fly-by-wire platforms with envelope protection from analog control configurations, and bundles maintenance training credits with airframe deliveries. Cost compression in the gas-operated segment is intensifying as Polish manufacturers exploit EASA harmonization to bypass national certification markups. Flight school chains exhibit lowest price sensitivity due to hourly operating economics focus, whereas private kit assemblers in the United States recreational aviation corridor remain highly responsive to capital barrier reductions under FAA Part 103 exemptions.
Supply Chain Analysis
Poland and the Czech Republic anchor carbon fiber prepreg fabrication and kit assembly for European recreational demand, while Argentina concentrates South American supply through tariff-advantaged Mercosur access. The supply chain draws from German 100LL avgas refining, Italian composite materials processing in Emilia-Romagna, and Chinese lithium-sulfur cell production for electric variants. Single-source vulnerability concentrates in European aviation gasoline supply through one German refinery network. Distribution runs through direct OEM contracts with scaled flight school operators and regional dealer networks handling import logistics for amateur-built segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where maintenance training contracts and simulator integration credits are expanding faster than hardware margins. The recurring-revenue layer from flight-hour generation and fleet technical support now exceeds airframe profitability for institutional accounts.
For Market Incumbents: Consolidate procurement relationships with multi-location flight school chains before electric variant certification unlocks new entrant access to noise-restricted urban corridors. Backward integration into carbon fiber prepreg supply secures margin control against Italian materials processors. Channel control through direct contracting with Arizona-California operators defends position against Polish cost-optimized kit competitors.
For New Entrants and Emerging Players: Anchor in Mercosur flight training markets where Argentine assembly operations offer tariff advantages over European kit imports. The most penetrable white-space target sits in electric-powered platforms for California urban air mobility corridors awaiting EASA thermal runaway certification finalization. A simulator-credit bundling go-to-market angle bypasses physical airframe hour requirements under FAA Part 61 restructuring.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Polish kit manufacturers holding EASA quality management certifications but lacking direct institutional procurement relationships. Long-term viability across the projection horizon hinges on electric propulsion certification resolution and mechanic pipeline restoration. The signal to watch is EASA CS-LSA battery thermal runaway standard publication unlocking commercial electric variant introductions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Prepreg | Polish manufacturers secure captive supply against Italian Emilia-Romagna processors. |
| Direct Fleet Procurement Contracts | Multi-location flight school chains in Arizona-California bypass traditional dealer networks. |
| Simulator Training Device Credit Bundling | FAA Part 61 synthetic hours unbundle physical airframe requirements for entry pathways. |
| Mercosur Assembly Localization | Argentine operations reduce import duty exposure for São Paulo training institutions. |
| Electric Variant Certification Investment | EASA thermal runaway compliance unlocks noise-restricted urban corridor access. |
Research Methodology
Initial hypotheses were tested against primary input from flight school fleet managers, certified rotorcraft mechanics, OEM product directors, and microlight regulatory affairs specialists and refined through secondary validation. FAA Part 103 exemption documentation, EASA CS-LSA consultation drafts, and national microlight derogation filings provided regulatory boundary conditions. Bottom-up triangulation across kit shipment manifests and top-down reconciliation against flight school fleet renewal announcements anchored volume estimates.
Variance decomposition across propulsion architecture, materials technology, and end-user scale segments structured the analytical framework throughout the modeling period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated battery energy density improvement trajectories, mechanic pipeline replenishment rates, and EASA harmonization implementation progress.
Material uncertainties — EASA thermal runaway certification timing, German avgas refinery capacity allocation, and FAA mechanic certification throughput — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and supply chain continuity. Recalibration cycles align with material shifts in certification standard publication and flight school procurement pattern consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Latin America General Aviation Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Winglets Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
France Aviation Market
Aircraft
Commercial Aerospace Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Glider Aircraft Market
Aircraft
North America Military Helicopters Market
Aircraft
Global Business Aircraft Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market