
 Asia-Pacific AI Orchestration Market | 2026-2036
Asia-Pacific AI Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific AI Orchestration Market Analytics
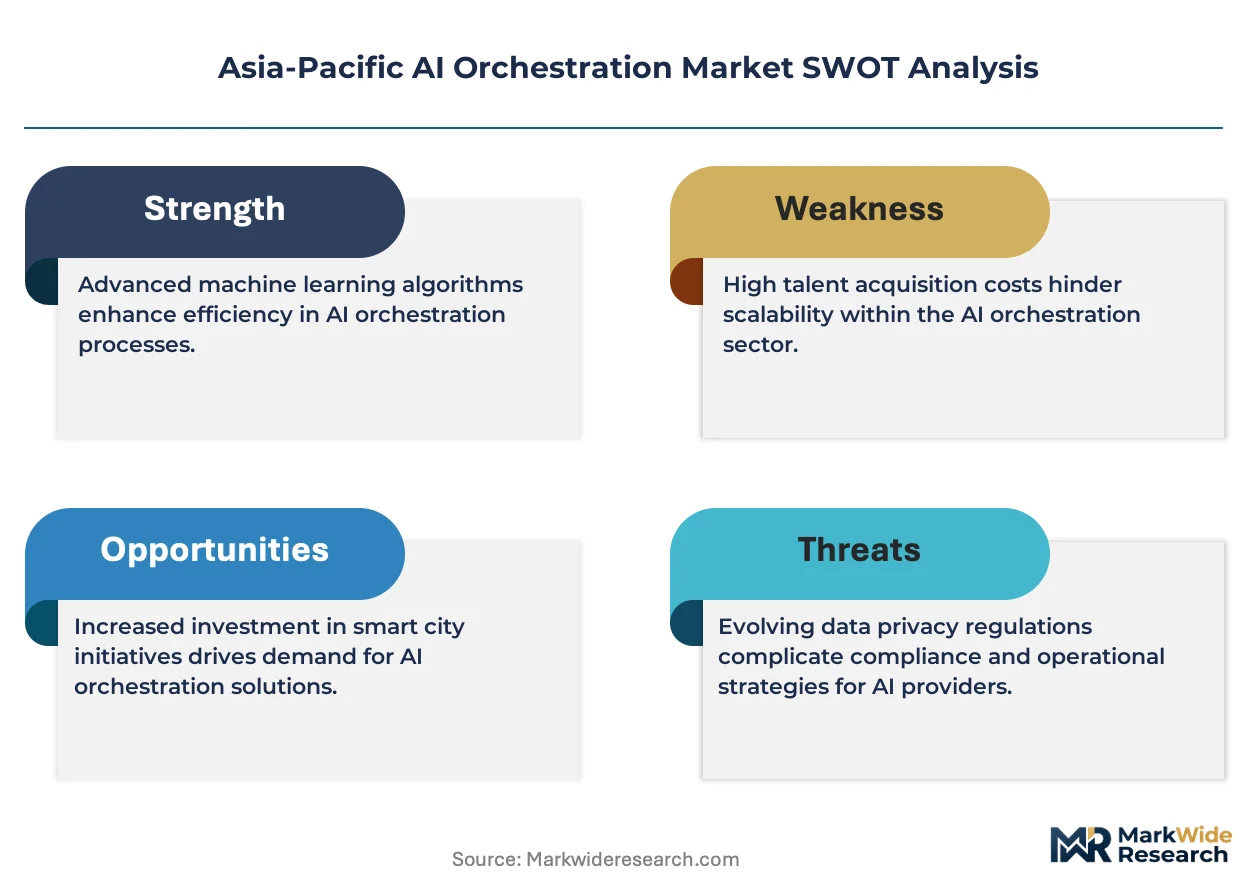
Cloud-native MLOps talent scarcity across Southeast Asia is bifurcating vendor performance, with firms possessing localized training pipelines pulling ahead of generalist competitors. Microsoft Corporation leverages its Azure Kubernetes Service footprint to anchor enterprise workloads across Australian financial services and Indian e-commerce platforms. Fujitsu Limited sustains dominance in Japan's on-premises integration segment through deep alignment with domestic manufacturing execution systems. Amazon Web Services, Inc. competes aggressively on serverless orchestration pricing, though its reliance on imported specialist labor constrains deployment velocity in regulated Indonesian sectors.
Asia-Pacific AI orchestration denotes the automated coordination of machine learning model training, inference, and monitoring across distributed compute clusters, typically governed by container orchestration layers such as Kubernetes with custom controllers for GPU scheduling and pipeline dependency resolution. Its primary commercial purpose is to collapse latency between data ingestion and actionable model output in sectors where real-time decisioning determines operational efficiency. Workflow automation solutions currently capture the deepest margin pools, as these implementations require bespoke integration with legacy ERP systems prevalent across Korean and Taiwanese manufacturing conglomerates. Cloud-based deployment models represent the fastest-expanding category, though hybrid configurations retain structural importance in Australian healthcare and Japanese automotive supply chains where data residency requirements fragment compute architectures.
Japan's METI issues technical guidelines for AI system interoperability that directly shape procurement specifications for domestic orchestration vendors. China's SAMR algorithmic recommendation provisions and India's Digital Personal Data Protection Act impose divergent audit trail and explainability mandates, compelling multinational platform providers to maintain jurisdiction-specific compliance modules. Australia's TGA and South Korea's MFDS are developing parallel frameworks for AI-enabled medical device orchestration that will constrain market access for uncertified workflow engines. Stakeholders must evaluate whether to architect region-agnostic compliance cores or accept the cost of maintaining fragmented regulatory instances across each national jurisdiction.
Market Dynamics
Fragmented data sovereignty requirements across the Asia-Pacific region are forcing orchestration vendors to engineer jurisdiction-specific compliance architectures rather than deploying unified regional platforms. This structural pressure compounds operational complexity for multinational enterprises managing cross-border AI workflows.
Growth Catalysts
- India's Digital Personal Data Protection Act:Financial services firms in Mumbai and Bangalore are accelerating orchestration investments to automate consent management and cross-border data transfer governance, creating immediate demand for compliant pipeline infrastructure.
- Smart factory sensor networks:Japan's precision manufacturing corridors under METI guidance require real-time coordination across heterogeneous industrial IoT devices, pulling GPU-accelerated orchestration layers into production environments.
- Algorithmic recommendation regulations:China's SAMR provisions mandate explainability audit trails for consumer-facing AI, compelling e-commerce platforms to deploy orchestration systems with embedded provenance tracking and model lineage documentation.
Market Restraints
- Cloud-native MLOps talent scarcity:Southeast Asia faces acute shortages of Kubernetes-certified engineers with GPU scheduling expertise, constraining deployment velocity for complex multi-cluster orchestration projects.
- Imported specialist labor dependence:Foreign platform providers in Indonesia's regulated banking sector must navigate restrictive visa frameworks for AI infrastructure specialists, extending implementation timelines.
- Legacy ERP integration friction:Korean and Taiwanese manufacturing conglomerates operate entrenched on-premises manufacturing execution systems that resist API-based orchestration connectivity without costly middleware development.
Strategic Opportunities
- Vietnam's emerging fintech corridor:Ho Chi Minh City's digital payment ecosystem lacks mature orchestration infrastructure, presenting first-mover advantages for vendors establishing localized training pipelines and support operations.
- Healthcare AI certification pathways:Australia's TGA and South Korea's MFDS are developing parallel frameworks for AI-enabled medical device orchestration, creating regulated market access for certified workflow engine providers.
- Edge-to-cloud convergence:Japanese automotive supply chains are piloting hybrid orchestration architectures that federate inference workloads between factory-floor edge nodes and centralized cloud clusters, opening deployment models beyond pure cloud or pure on-premises.
Industry Challenges
- Cross-border compliance module maintenance:Multinational platform providers must sustain fragmented regulatory instances across India's data localization mandates, China's algorithmic transparency requirements, and Japan's METI interoperability guidelines.
- GPU resource contention management:Real-time orchestration across distributed compute clusters demands sophisticated scheduling algorithms that most enterprise IT organizations lack capability to architect and operate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific AI Orchestration Market |
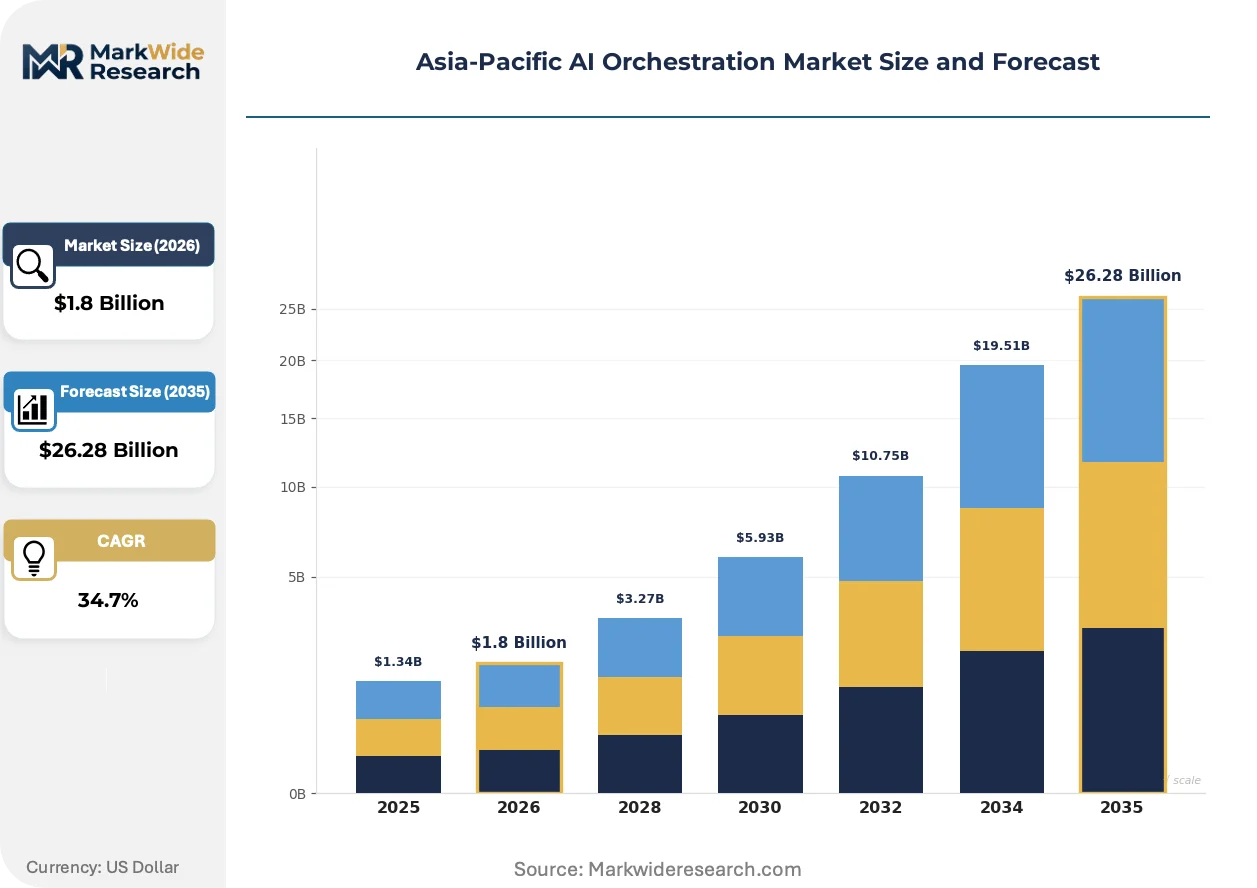
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Infrastructure Management, Workflow Automation, Application Integration, Data Processing Deployment Model: On-premises, Cloud-based, Hybrid, Multi-cloud End User: Retail, Healthcare, Manufacturing, Telecommunications Service Type: Consulting, Implementation, Support, Managed Services |
| Companies Covered | Oracle Corporation, Hewlett Packard Enterprise Company, Fujitsu Limited, Microsoft Corporation, Wipro Limited, SAP SE, Cisco Systems Inc, Amazon Web Services, Inc., International Business Machines Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific AI Orchestration Market Evolving Landscape
Container-native orchestration architectures are displacing monolithic MLOps platforms across Asia-Pacific financial services and manufacturing deployments. This architectural shift is compressing vendor consolidation timelines and elevating specialized controller development capabilities.
Serverless orchestration primitives are decomposing traditional Kubernetes-based pipeline management into function-as-a-service components. Australian financial institutions and Indian e-commerce platforms are adopting these lighter-weight abstractions for inference-heavy workloads. The structural consequence is collapsing operational overhead for seasonal demand spikes and experimental model deployments.
China's SAMR algorithmic recommendation provisions and India's Digital Personal Data Protection Act are diverging on audit trail and explainability mandates. Industrial consequence includes mandatory jurisdiction-specific compliance modules rather than portable regional configurations. Healthcare and financial services segments in both markets are responding by bifurcating their orchestration architectures.
Buyers in Japan's automotive supply chains are compressing vendor evaluation cycles and demanding proof-of-concept deployments with measurable latency reduction commitments. Traditional RFP-to-contract timelines are halving as procurement teams prioritize demonstrated GPU scheduling efficiency over feature breadth. This behavioral shift is most visible among tier-one suppliers in Toyota City and Nagoya manufacturing clusters.
Asia-Pacific AI Orchestration Market Segmentation
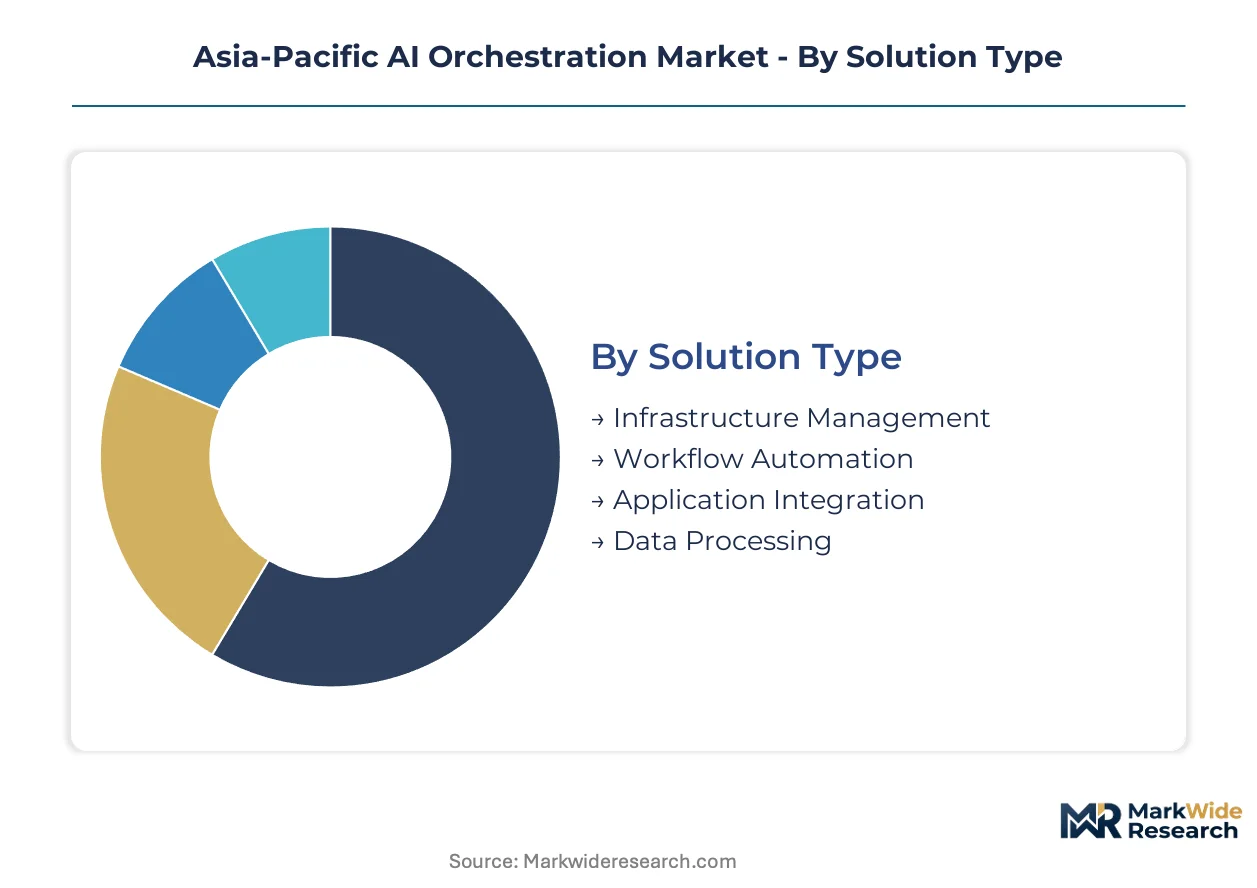
AI orchestration architectures fragment across deployment topologies and solution layers, with procurement patterns diverging sharply between Japan's precision manufacturing clusters and India's emerging fintech corridors. Vendors must calibrate segment-specific roadmaps to capture value across heterogeneous compliance and latency requirements.
Solution Type:
Domestic demand concentrates in workflow automation across Japanese automotive supply chains, while infrastructure management serves export-oriented semiconductor fabrication in Taiwan and Korea.
- Workflow Automation:Bespoke pipeline orchestration for legacy ERP integration captures premium margins in Korean and Taiwanese manufacturing conglomerates. METI-guided smart factory initiatives in Toyota City and Nagoya clusters pull GPU-accelerated scheduling layers into production environments with stringent latency requirements.
- Infrastructure Management:Container-native compute coordination governs distributed training clusters across Australian financial services and Indian e-commerce platforms. Regulatory fragmentation between India's data localization mandates and China's SAMR algorithmic provisions forces jurisdiction-specific controller architectures.
- Application Integration:API mediation layers connect heterogeneous sensor networks in Vietnamese fintech corridors.
- Data Processing:Stream processing engines handle real-time inference pipelines for Indonesian digital payment platforms.
Workflow automation commands the established base. The steepest expansion runs through infrastructure management.
Deployment Model:
Cost tier bifurcation separates premium hybrid configurations from commodity cloud-native deployments, with regulated sectors absorbing 40-60% implementation premiums for data residency compliance.
- Cloud-based:Serverless orchestration primitives decompose Kubernetes pipelines into function-as-a-service components for Australian financial institutions. AWS and Microsoft Azure compete aggressively on inference-heavy workload pricing, though imported specialist labor constraints throttle velocity in Indonesian banking sectors.
- Hybrid:Federated edge-to-cloud architectures partition workloads between factory-floor inference nodes and centralized training clusters. Japanese automotive supply chains pilot these configurations to satisfy METI interoperability guidelines while containing WAN latency.
- On-premises:Fujitsu sustains dominance through alignment with domestic manufacturing execution systems in Nagoya manufacturing corridors.
- Multi-cloud:Vendor-agnostic abstraction layers mitigate concentration risk for Singaporean wealth management platforms.
Hybrid deployments anchor high-value manufacturing contracts. Cloud-based configurations are expanding most quickly across financial services and e-commerce.
End User:
Application maturity varies by sector, with manufacturing exhibiting sophisticated pipeline orchestration while healthcare remains constrained by certification timelines.
- Manufacturing:Real-time coordination across heterogeneous industrial IoT devices dominates procurement specifications in Japan's precision manufacturing corridors. GPU scheduling efficiency determines vendor selection more than feature breadth among tier-one Toyota City suppliers.
- Healthcare:TGA and MFDS certification pathways for AI-enabled medical device orchestration create regulated market access barriers. Australian and South Korean healthcare systems fragment compute architectures between edge diagnostics and centralized model governance.
- Retail:Chinese e-commerce platforms deploy provenance tracking to satisfy SAMR explainability mandates for algorithmic recommendation systems.
- Telecommunications:Indonesian and Vietnamese carriers build orchestration layers for network optimization and fraud detection pipelines.
Manufacturing commands the established base. Healthcare presents the steepest expansion trajectory pending regulatory clarity.
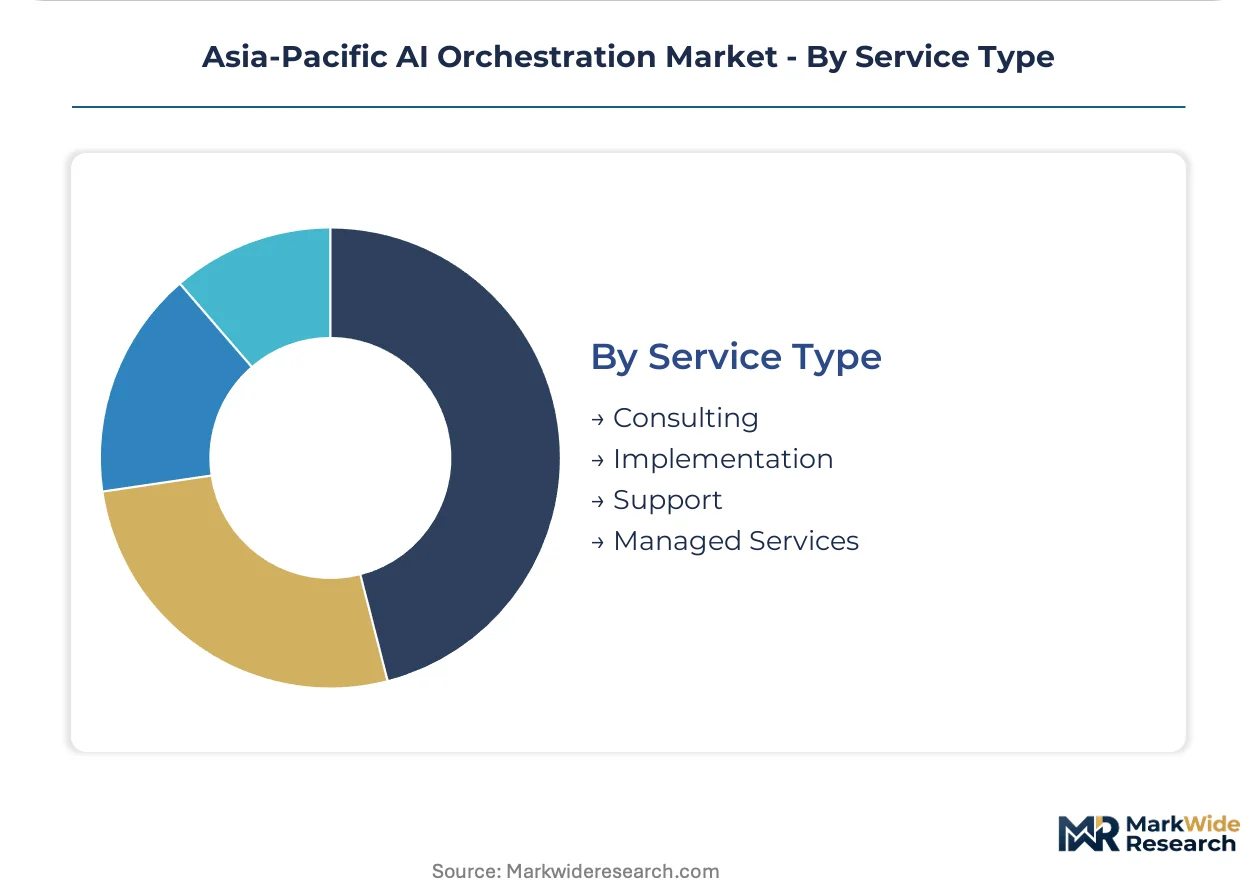
Service Type:
Customer type stratification separates enterprise self-managed implementations from mid-market managed service consumption, with talent scarcity driving outsourcing preferences in Southeast Asia.
- Implementation:Kubernetes-certified engineers with GPU scheduling expertise command premium day rates across Southeast Asia, where acute talent shortages extend deployment timelines for multi-cluster orchestration projects. Vendors with localized training pipelines pull ahead of generalist competitors.
- Managed Services:Ongoing pipeline operations and compliance module maintenance address multinational enterprises managing fragmented regulatory instances across India, China, and Japan. Cross-border workflow governance requires jurisdiction-specific audit trail configurations.
- Consulting:Architecture design services navigate legacy ERP integration friction in Korean manufacturing conglomerates.
- Support:Tiered response agreements cover production orchestration layers for Australian financial services uptime requirements.
Implementation services command the established base. Managed services are climbing the fastest as compliance complexity outstrips internal capability development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's technical guidelines for AI system interoperability anchor procurement specifications across Japan's precision manufacturing corridors. The Asia-Pacific region fragments into jurisdiction-specific compliance architectures driven by divergent data sovereignty mandates and industrial policy priorities.
Japan
Smart factory sensor networks in Toyota City and Nagoya clusters demand real-time GPU-accelerated orchestration across heterogeneous industrial IoT devices. METI guidance shapes vendor selection criteria, prioritizing demonstrated latency reduction over feature breadth. Fujitsu sustains dominance through deep alignment with domestic manufacturing execution systems.
China
E-commerce platforms deploy provenance tracking and model lineage documentation to satisfy SAMR algorithmic recommendation provisions. The country's algorithmic transparency requirements mandate explainability audit trails for consumer-facing AI systems. Shanghai and Shenzhen technology corridors concentrate orchestration investments for cross-border workflow governance.
India
Mumbai and Bangalore financial services firms accelerate orchestration investments to automate consent management under the Digital Personal Data Protection Act. The central bank's cross-border data transfer governance creates immediate demand for compliant pipeline infrastructure. Localized training pipelines pull domestic vendors ahead of generalist competitors.
Australia
TGA certification pathways for AI-enabled medical device orchestration fragment compute architectures between edge diagnostics and centralized model governance. Sydney financial institutions adopt serverless orchestration primitives for inference-heavy workloads. Data residency requirements sustain hybrid deployment premiums in healthcare and banking sectors.
South Korea
MFDS parallel frameworks for medical device orchestration create regulated market access barriers for uncertified workflow engines. Seoul semiconductor fabrication clusters demand container-native compute coordination for distributed training pipelines. Legacy ERP integration friction in manufacturing conglomerates requires costly middleware development.
Asia-Pacific AI Orchestration Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Asia-Pacific AI orchestration. Cloud hyperscalers anchor enterprise workloads through Kubernetes service footprints, while domestic systems integrators sustain on-premises dominance in manufacturing corridors. Three archetypes define competitive positioning: infrastructure-native platforms with regional compliance modules, legacy systems integrators with manufacturing execution system alignment, and emerging specialists with localized training pipelines. M&A activity concentrates on Kubernetes controller capabilities and jurisdiction-specific compliance engineering.
Within the infrastructure-native tier, Microsoft Corporation and Amazon Web Services, Inc. exemplify scale-driven platform strategies, with the former leveraging Azure Kubernetes Service across Australian financial services and Indian e-commerce. Fujitsu Limited occupies a distinct position through manufacturing execution system integration in Japan's Nagoya corridor. Among enterprise systems integrators, Wipro Limited represents the managed services archetype addressing fragmented regulatory instances across India, China, and Japan. Oracle Corporation and SAP SE anchor workflow automation demand in Korean and Taiwanese manufacturing conglomerates confronting legacy ERP connectivity friction.
| Leading Market Players |
|---|
| Oracle Corporation |
| Hewlett Packard Enterprise Company |
| Fujitsu Limited |
| Microsoft Corporation |
| Wipro Limited |
| SAP SE |
| Cisco Systems Inc |
| Amazon Web Services, Inc. |
| International Business Machines Corporation |
| Others |
Value Network & Pricing Analysis
India's Digital Personal Data Protection Act gates both vendor qualification and price differentiation in Asia-Pacific AI orchestration, forcing compliance-certified providers to command substantial premiums over uncertified alternatives while disqualifying cost-focused entrants from regulated financial services procurement.
Pricing Analysis
Japan-to-Indonesia price spreads exceed threefold for equivalent orchestration deployments, with METI-certified configurations in Toyota City manufacturing clusters anchoring premium tiers while serverless primitives in Jakarta fintech corridors compete on per-inference unit economics. Subscription SaaS tiers dominate cloud-native segments, though project-based implementation fees prevail where legacy ERP integration demands bespoke middleware. Certification level—specifically TGA alignment for Australian healthcare and MFDS compliance for South Korean medical devices—drives the steepest price differentiation alongside GPU scheduling performance guarantees. Cost compression in Indonesian cloud deployments intensifies as AWS and Microsoft Azure escalate serverless pricing warfare. Korean manufacturing conglomerates exhibit least price sensitivity, prioritizing latency reduction commitments over per-unit economics.
Supply Chain Analysis
GPU accelerator lead times from Taiwan Semiconductor Manufacturing and Samsung Foundry now stretch eighteen to twenty-four weeks, constraining deployment velocity for real-time orchestration projects across Southeast Asia. Hardware supply concentrates in Taiwan, South Korea, and USA for advanced compute silicon, while specialized Kubernetes controller development pools in India and Singapore. NVIDIA A100 and H100 tensor core dependencies, alongside custom FPGA inference accelerators, tether orchestration platform performance to foundry allocation priorities. Single-source vulnerability around CUDA-optimized firmware creates systemic risk for multi-cluster deployments. Distribution runs through hyperscaler marketplaces and domestic systems integrators, with Fujitsu channel dominance persisting in Nagoya manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acute scarcity of Kubernetes-certified engineers with GPU scheduling expertise fragments competitive outcomes, rewarding vendors who anchor localized training pipelines while punishing reliance on imported specialist labor.
For Market Incumbents: Consolidate controller development capabilities through targeted acquisition of Kubernetes-native specialists, particularly those with jurisdiction-specific compliance engineering expertise. Defend Azure Kubernetes Service and equivalent platform positions by embedding METI interoperability modules and SAMR audit trail primitives directly into managed service tiers, neutralizing emerging domestic competitors in Japan and China. For New Entrants and Emerging Players: TGA fast-track certification for AI-enabled medical device orchestration opens regulated market access ahead of incumbent platform adaptation. Target Vietnam's Ho Chi Minh City fintech corridor, where orchestration infrastructure maturity lags demand acceleration and localized support operations confer first-mover positioning. Lead with managed service consumption models addressing Southeast Asian talent scarcity. For Investors and Strategic Acquirers: India's Digital Personal Data Protection Act enforcement reshapes the acquisition landscape toward compliance-engineering capabilities over raw platform scale. Five-to-ten year viability favors vendors with fragmented regulatory instance maintenance rather than region-agnostic architectures. Kubernetes controller development teams with demonstrated GPU scheduling optimization represent priority acquisition archetypes. Watch MFDS and TGA certification timeline convergence as inflection signal for healthcare orchestration market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Localization | Jurisdiction-specific audit trail engineering satisfies India's data localization mandates and China's SAMR provisions simultaneously. |
| GPU Scheduling Optimization | Demonstrated latency reduction commitments determine vendor selection in Toyota City manufacturing procurement cycles. |
| Managed Service Expansion | Ongoing pipeline operations outsourcing addresses Southeast Asian MLOps talent scarcity and extends recurring revenue capture. |
| Edge-to-Cloud Federation | Hybrid architectures partition inference workloads between factory-floor nodes and centralized clusters per METI guidelines. |
| Training Pipeline Localization | Domestic Kubernetes certification programs in Bangalore and Ho Chi Minh City accelerate deployment velocity versus imported labor dependence. |
Research Methodology
A standing panel of MLOps platform engineers, financial services CTOs, manufacturing IT directors, and regulatory compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings of hyperscaler cloud providers, METI technical guideline publications, SAMR algorithmic recommendation enforcement notices, and TGA medical device software consultation papers. Bottom-up segment sizing triangulated against top-down market aggregation across deployment model, solution type, and end-user vertical dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled deployment topology, organization scale tier, vertical application, integration complexity level, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from year-over-year growth rate progression analysis incorporating GPU infrastructure capex trajectories, cloud service pricing elasticity, and compliance cost pass-through assumptions.
Underlying assumptions cover sustained hyperscaler competition intensity, stable foundry allocation for AI accelerators, and incremental regulatory harmonization progress, with deviation risk concentrated in sudden visa policy tightening for specialist labor and accelerated data localization enforcement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
US Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Enterprise LLM Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
AI Development Service Market
Artificial Intelligence (AI)
AI in Life Sciences Market