
 AI Development Service Market | 2026-2036
AI Development Service Market Size, Share, and Industry Trends Forecast 2026-2036
AI Development Service Market Insights
Pricing for AI development service engagements is decoupling sharply between premium-tier custom model builds and commodity API integration work. Microsoft leverages its Azure infrastructure and OpenAI partnership to dominate enterprise-grade deployments. Google sustains competitive pressure through deep research pipelines and proprietary TPU access for training-intensive clients.
AI development service encompasses the full lifecycle of designing, training, deploying, and optimizing artificial intelligence systems for commercial use, spanning data pipeline engineering, model architecture selection, hyperparameter tuning, and inference optimization to meet latency and accuracy thresholds. Custom development and integration services command the deepest margin pools as enterprises seek bespoke solutions rather than off-the-shelf implementations. Cloud-based deployment is accelerating fastest as organizations prioritize elastic compute access over capital-intensive on-premises infrastructure.
The EU AI Act, FDA guidance on AI-enabled medical devices, and China's algorithmic recommendation provisions are creating divergent compliance landscapes that shape where providers can deploy and how they architect model governance. ISO standards for AI risk management are becoming baseline procurement requirements across regulated industries. Stakeholders must monitor how jurisdictional fragmentation in liability frameworks affects cross-border service delivery and data residency obligations.
Market Dynamics
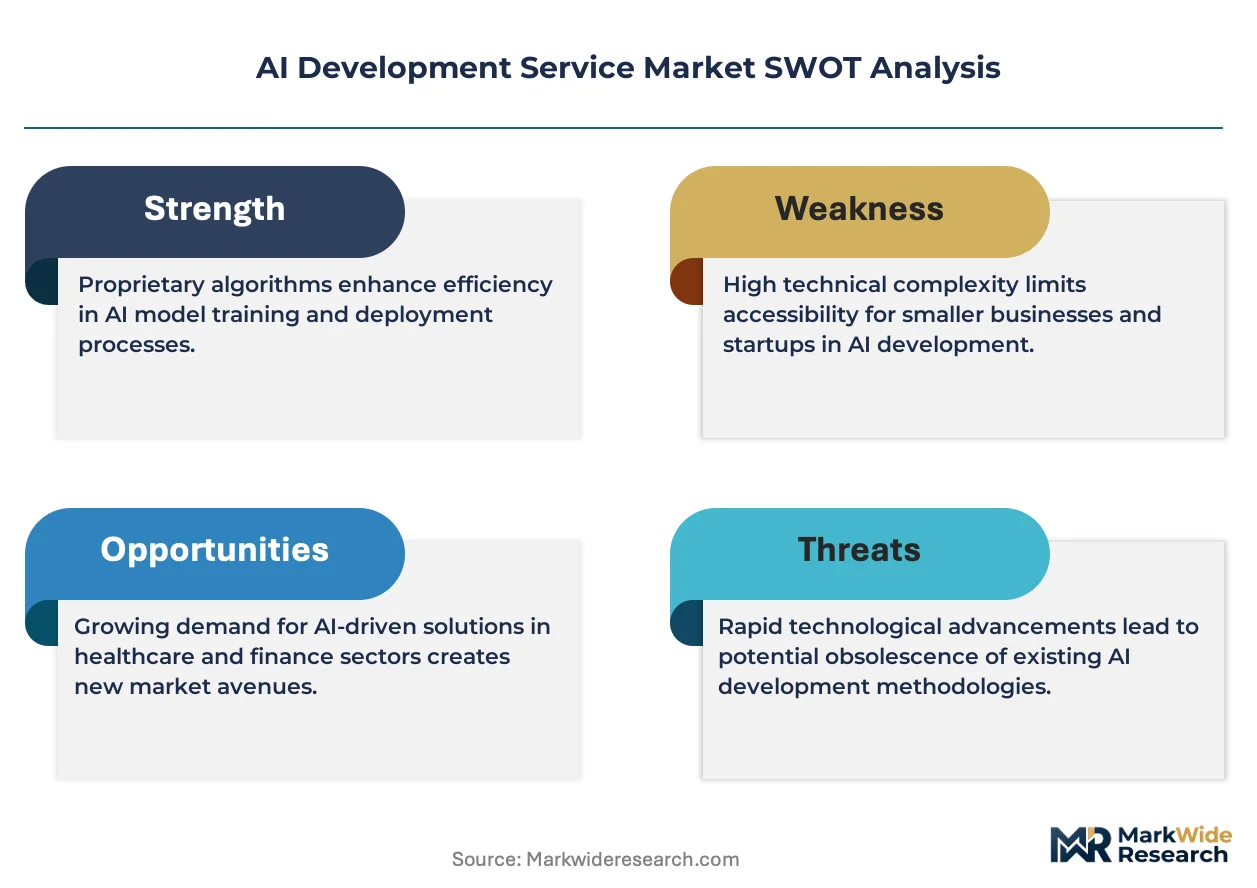
The AI development service market is bifurcating sharply between hyperscaler-backed model-as-a-service platforms and boutique firms specializing in vertical-specific fine-tuning, with regulatory fragmentation across the EU AI Act, FDA guidance, and China's algorithmic provisions forcing divergent compliance architectures.
Growth Catalysts
- EU AI Act Mandates:Risk-classification requirements for high-stakes AI systems are compelling European enterprises to seek external governance expertise, creating sustained demand for compliance-integrated development services.
- Healthcare Diagnostic Expansion:FDA 510(k) pathway refinements for AI-enabled medical devices are accelerating provider adoption of radiology and pathology automation tools.
- Retrieval-Augmented Generation:Enterprise knowledge management systems are absorbing RAG architectures to ground large language models in proprietary data without full retraining cycles.
Market Restraints
- GPU Supply Concentration:Foundry capacity constraints in Taiwan and South Korea are extending lead times for training infrastructure, compressing project margins for compute-intensive engagements.
- Data Residency Requirements:China's data localization provisions and EU GDPR cross-border transfer mechanisms are fragmenting cloud deployment options and multiplying compliance costs.
- Foundation Model Commoditization:Open-weight releases from Meta's Llama family and Mistral are eroding pricing power for basic inference API services.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for AI hardware and data center infrastructure are attracting service providers to establish captive development centers in Bangalore and Hyderabad.
- Edge AI Convergence:Synthesis of TinyML optimization with 5G private networks is opening industrial predictive maintenance applications previously blocked by latency constraints.
- Sovereign Cloud Mandates:French ANSSI and German BSI certification requirements for sensitive-sector AI deployments are creating protected market segments for EU-headquartered developers.
Industry Challenges
- MLops Talent Scarcity:Pipeline engineering and model observability specialists command premium compensation, constraining scale-out capacity for mid-tier service firms.
- Legacy System Integration:Mainframe and proprietary ERP environments in financial services require custom middleware development, extending project timelines and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Development Service Market |
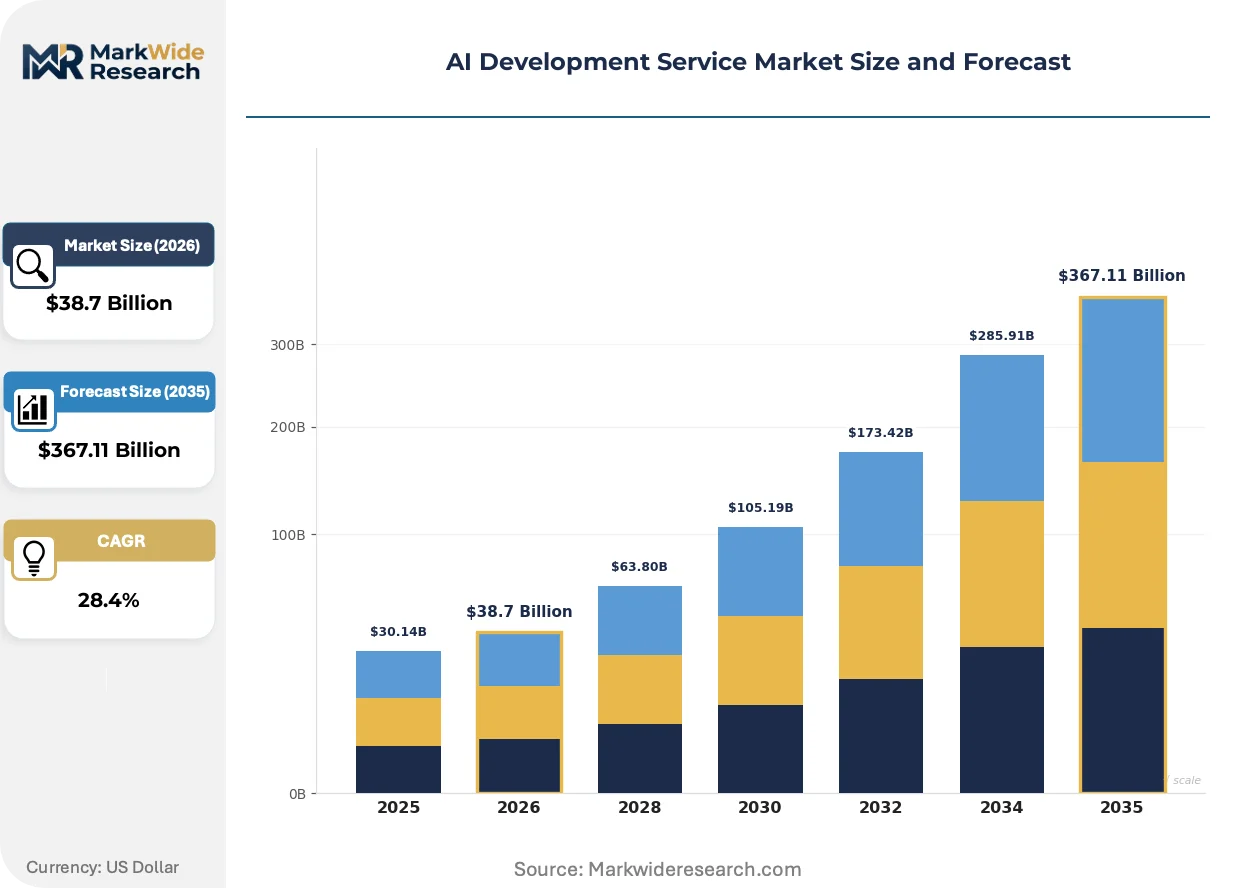
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $367.11 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Custom Development, Integration, Maintenance Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Healthcare, Finance, Retail, Manufacturing Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics |
| Companies Covered | Microsoft, Google, AWS, IBM, Accenture, Deloitte, Cognizant, Palantir, LeewayHertz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Development Service Market Trends and Innovations
Foundation model architectures are commoditizing rapidly while differentiation migrates toward compound AI systems that orchestrate multiple specialized models, with regulatory pressure and buyer sophistication accelerating this structural shift.
Multimodal foundation models are absorbing document understanding, computer vision, and speech recognition into unified inference endpoints. Healthcare systems and legal services firms are adopting these consolidated stacks to reduce vendor fragmentation. This convergence is compressing addressable market space for point-solution specialists.
EMA's forthcoming guidance on AI in drug discovery and the FDA's predetermined change control plans for adaptive algorithms are mandating documented validation protocols. Pharmaceutical sponsors must now embed quality-by-design principles from model conception. European CROs are responding by building dedicated AI validation divisions.
Enterprise buyers are unbundling model development from ongoing operations, separating training contracts from inference hosting and MLOps retainers. This disaggregation favors pure-play optimization shops over full-stack providers. Financial services procurement teams in New York and London are pioneering this bifurcated sourcing approach.
AI Development Service Market Segmentation
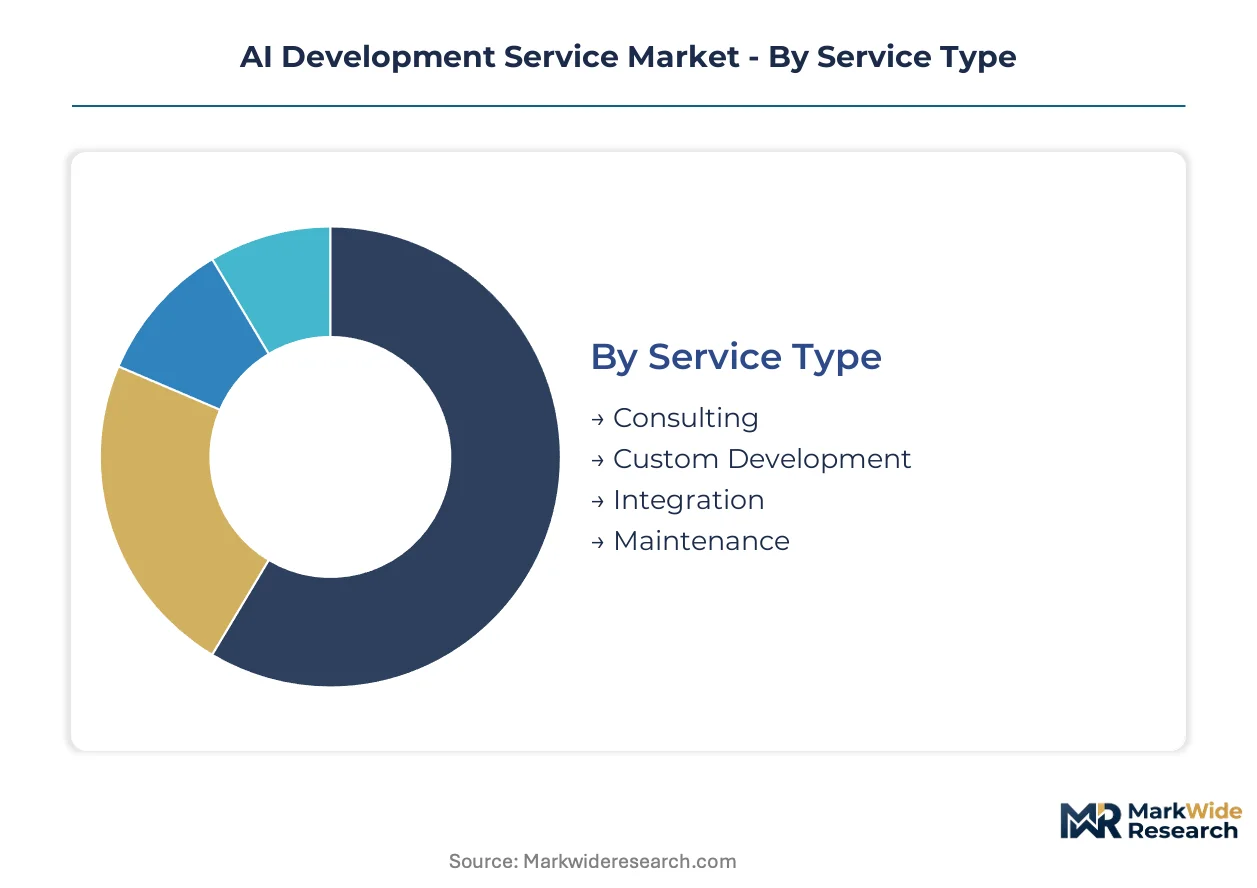
Service delivery models in AI development diverge sharply based on client technical maturity and regulatory exposure. Buyers with stringent data governance requirements favor bespoke architectures, while cost-sensitive segments gravitate toward standardized deployment templates.
Service Type:
Customization depth separates premium engagements from volume-driven implementation work across this category.
- Consulting:Strategic advisory spans AI readiness assessment, use case prioritization, and governance framework design. Financial services firms in New York and London dominate procurement as fiduciary obligations demand documented algorithmic risk protocols.
- Custom Development:End-to-end model engineering from data pipeline construction through production deployment commands the deepest margin pools. Healthcare providers commission bespoke diagnostic algorithms requiring FDA 510(k) validation pathways, extending project timelines but securing multi-year exclusivity arrangements.
- Integration:API orchestration and legacy system connectivity absorbs the highest transaction volume. Manufacturing ERP environments require substantial middleware development to embed predictive maintenance modules.
- Maintenance:Post-deployment MLOps retainers cover model drift monitoring, retraining scheduling, and inference optimization. Regulated industries mandate continuous validation documentation under EU AI Act high-risk system requirements.
Most installed capacity flows through Integration services. Expansion is steepest in Custom Development.
Deployment Model:
Capital intensity and latency requirements segment buyer preferences across infrastructure architectures.
- On-Premises:Dedicated hardware installations serve classified government workloads and proprietary financial trading systems. Sovereign cloud mandates in France and Germany preserve demand despite higher total cost of ownership.
- Cloud-Based:Elastic compute access via hyperscaler platforms dominates new project starts. Healthcare systems leverage cloud training clusters for radiology model development while maintaining HIPAA-compliant data partitioning.
- Hybrid:Split architectures train models in cloud environments then deploy inference engines locally. Retail chains adopt this pattern to personalize recommendations without transmitting raw transaction data externally.
- Edge Computing:TinyML optimization enables millisecond-latency inference on constrained devices. Industrial predictive maintenance applications in automotive manufacturing plants exploit 5G private networks for real-time vibration analysis.
Cloud-Based deployments carry the majority of new project starts. Edge Computing climbs the fastest as latency-sensitive use cases proliferate.
End User:
Regulatory stringency and data asset richness determine vertical spending concentration.
- Healthcare:FDA and EMA validation requirements for AI-enabled diagnostics create substantial compliance overhead. Radiology automation and pathology screening tools absorb the largest development budgets as reimbursement pathways stabilize.
- Finance:Algorithmic trading, credit underwriting, and fraud detection systems face SEC and ECB scrutiny for model explainability. Model risk management frameworks mandate independent validation teams.
- Retail:Demand forecasting and dynamic pricing engines prioritize speed-to-deployment over architectural sophistication. Supply chain optimization projects integrate computer vision for inventory management.
- Manufacturing:Quality inspection and predictive maintenance applications exploit proprietary sensor data streams. Automotive and semiconductor fabs commission the most complex edge deployment architectures.
Healthcare commands the highest average contract value. Manufacturing gains share fastest as Industry 4.0 investments accelerate.
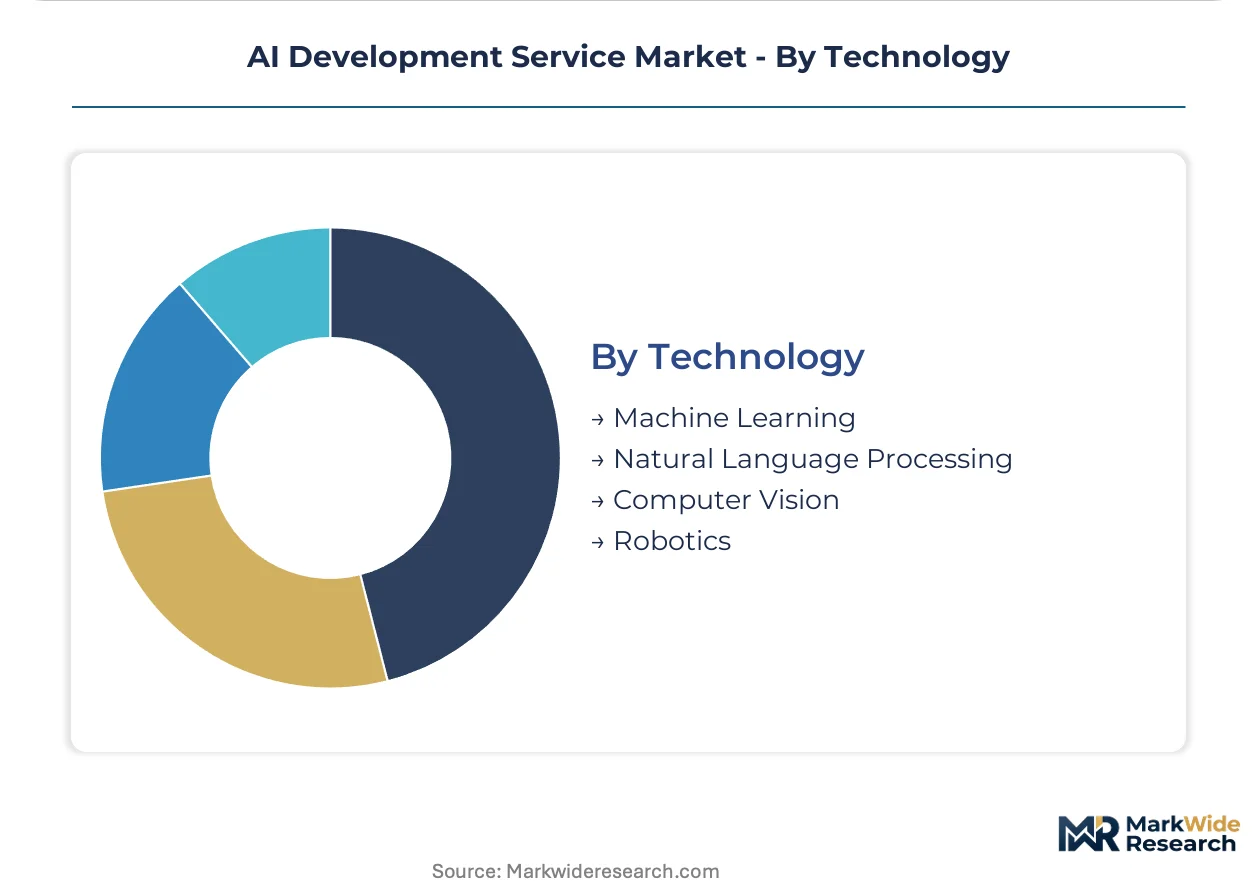
Technology:
Foundation model commoditization is reshaping where specialized engineering investment concentrates.
- Machine Learning:Classical supervised and unsupervised techniques persist in structured data applications where interpretability requirements preclude deep neural architectures. Tabular data pipelines for credit scoring and demand forecasting remain substantial revenue contributors.
- Natural Language Processing:Large language model fine-tuning and retrieval-augmented generation systems dominate enterprise knowledge management budgets. Legal services firms and pharmaceutical regulatory affairs teams deploy contract analysis and literature mining tools.
- Computer Vision:Defect detection, medical imaging analysis, and autonomous navigation systems require substantial labeled dataset curation. Manufacturing quality control and agricultural yield estimation drive commercial deployment volume.
- Robotics:Perception-stack development for manipulation and locomotion integrates multimodal sensor fusion. Warehouse automation and surgical assistance platforms absorb the most intensive development resources.
Natural Language Processing carries the steepest growth trajectory. Machine Learning retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep learning specialists cluster in San Francisco, London, and Bangalore, anchoring the geographic distribution of AI development talent. These concentrations shape where enterprises source premium model engineering versus commodity integration work.
United States
Enterprise buyers in California and New York commission the largest custom model development contracts. The FDA's 510(k) pathway refinements for AI-enabled medical devices accelerate healthcare provider adoption. Microsoft leverages its Azure infrastructure and OpenAI partnership to dominate enterprise-grade deployments from its Redmond headquarters.
United Kingdom
Financial services firms in London prioritize algorithmic risk protocols and model explainability frameworks. The Financial Conduct Authority scrutinizes credit underwriting and fraud detection systems for transparency. Boutique consultancies specializing in vertical-specific fine-tuning cluster around the City of London.
Germany
Industrial manufacturers commission predictive maintenance applications requiring edge deployment architectures. The BSI certification requirements for sensitive-sector AI deployments create protected market segments for EU-headquartered developers. Automotive and semiconductor fabs in Bavaria drive demand for TinyML optimization.
India
The PLI scheme for AI hardware and data center infrastructure attracts service providers to establish captive development centers. CDSCO guidance shapes pharmaceutical AI validation protocols for domestic drug discovery programs. Bangalore and Hyderabad host the fastest-expanding engineering talent pools for retrieval-augmented generation systems.
China
Domestic cloud platforms serve algorithmic recommendation systems under MIIT oversight. Data localization provisions fragment deployment options and multiply compliance costs for foreign providers. Beijing-Tianjin-Hebei anchors government and surveillance AI procurement.
AI Development Service Market Competitive Landscape
Top-tier vendors anchor hyperscaler-backed model-as-a-service platforms, while boutique specialists concentrate in vertical-specific fine-tuning. The market bifurcates between full-stack cloud providers and pure-play optimization shops. Strategic archetypes include infrastructure-integrated platforms, compliance-integrated consultancies, and edge-deployment specialists. M&A activity concentrates on acquiring MLOps talent, while strategic partnerships target sovereign cloud certification.
Among hyperscaler-backed platforms, Microsoft and Google exemplify the infrastructure-integrated archetype, leveraging proprietary compute access and research pipelines. IBM occupies a position bridging legacy enterprise relationships with modern AI service delivery. These three anchors demonstrate how scale advantages in training infrastructure shape competitive positioning without guaranteeing margin capture in commoditized inference segments.
| Leading Market Players |
|---|
| Microsoft |
| AWS |
| IBM |
| Accenture |
| Deloitte |
| Cognizant |
| Palantir |
| LeewayHertz |
| Others |
Pricing and Supply Chain Analysis
Retrieval-augmented generation architectures are compressing training costs for enterprise knowledge systems while concentrating GPU procurement power among hyperscaler-backed platforms with direct foundry relationships. This technology shift simultaneously erodes margins for commodity API providers and inflates premiums for bespoke model engineering with proprietary data pipelines.
Pricing Analysis
Bundled full-stack engagements command premium retainers while unbundled inference hosting faces commoditization from open-weight foundation models. Three-tier pricing structure across premium custom development, standard integration services, and economy API consumption reflects certification grade and vertical specialization. Cost compression in basic inference tiers is intensifying because Meta's Llama and Mistral releases eliminate pricing power for undifferentiated model access. Healthcare providers with FDA validation requirements show least price sensitivity; retail demand forecasting buyers exhibit highest elasticity.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea extend lead times for NVIDIA H100 clusters, forcing service providers to book foundry capacity quarters ahead. Engineering talent pools in India and Vietnam feed implementation and MLOps layers, while proprietary TPU access centers on Google and Microsoft infrastructure. Supply chain risk hinges on single-source vulnerability for advanced GPU substrates. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory fragmentation across the EU AI Act, FDA guidance, and China's algorithmic provisions perpetuates demand for compliance-integrated development expertise.
For Market Incumbents: Lock in exclusive data partnerships with healthcare systems and financial institutions to defend against boutique fine-tuning specialists. Invest in sovereign cloud certification for French ANSSI and German BSI requirements to capture protected public-sector segments. GPU supply concentration threatens margin stability; secure long-term training cluster reservations through hyperscaler alliances. For New Entrants and Emerging Players: Begin with edge AI optimization for industrial predictive maintenance, where latency requirements and 5G private network integration create defensible specialization. Manufacturing quality inspection in automotive and semiconductor fabs offers the most penetrable entry point. Pursue OEM partnerships with sensor hardware vendors to embed TinyML models at the device layer. For Investors and Strategic Acquirers: Roll-up economics work for MLOps talent aggregators because ML pipeline engineering and model observability specialists command scarcity premiums that scale across client portfolios. Five-to-ten-year viability favors platforms with embedded regulatory validation workflows. Monitor FDA predetermined change control plan adoption rates as inflection signal for adaptive algorithm demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Integration | High-risk system classification mandates external governance expertise from European enterprises. |
| Retrieval-Augmented Generation Deployment | Enterprise knowledge management budgets shift toward proprietary data grounding without full retraining cycles. |
| Edge AI Convergence | TinyML optimization with 5G private networks unlocks industrial predictive maintenance previously blocked by latency. |
| Sovereign Cloud Certification | French ANSSI and German BSI requirements create protected market segments for EU-headquartered developers. |
| MLOps Talent Acquisition | Pipeline engineering and model observability specialists constrain scale-out capacity for mid-tier service firms. |
Research Methodology
Multiple input streams — primary interviews with AI development executives, MLOps engineering leads, and enterprise IT procurement officers; secondary validation against hyperscaler capex disclosures, FDA 510(k) filing databases, and EU regulatory guidance documents; plus customs records for AI hardware imports — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions informed the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate calibration incorporated training infrastructure cost curves, regulatory implementation timelines, and foundation model commoditization velocity as AI-specific forecast inputs.
Several conditions sit outside the modeled scope, including black-swan GPU supply disruptions, abrupt regulatory reversals in major jurisdictions, and breakthrough architectures that eliminate retraining requirements entirely. Forecasts reflect documented assumptions about compliance cost trajectories and talent pool expansion rates. Material deviation in FDA adaptive algorithm guidance adoption or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
Permission-Aware AI Repository Gateway Market
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Global Conversational Systems Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Global Insight Engines Market