
 Edge AI Market | 2026-2036
Edge AI Market Size, Share, and Industry Trends Forecast 2026-2036
Edge AI Market Analysis
ISO/IEC 23053 for AI system trustworthiness is bifurcating the vendor landscape into certified and non-certified tiers. NVIDIA Corporation leverages its CUDA software stack to dominate data center-to-edge deployment pipelines. Qualcomm Technologies, Inc. anchors mobile-native AI acceleration through its Snapdragon platform across automotive and IoT verticals. Intel Corporation competes on x86-based edge server consolidation for industrial control workloads.
Edge AI refers to artificial intelligence computation performed on decentralized devices—smartphones, sensors, vehicles, industrial gateways—rather than centralized cloud servers, typically operating within sub-10 watt thermal envelopes and millisecond latency constraints for real-time inference. Its primary commercial purpose is enabling autonomous decision-making where network connectivity is intermittent, bandwidth is costly, or privacy precludes data transmission. Machine Learning hardware currently commands the largest silicon allocation across edge deployments, while Computer Vision applications in manufacturing quality inspection represent the fastest-expanding margin pool. Natural Language Processing at the edge remains nascent, constrained by memory bandwidth limitations on battery-powered endpoints.
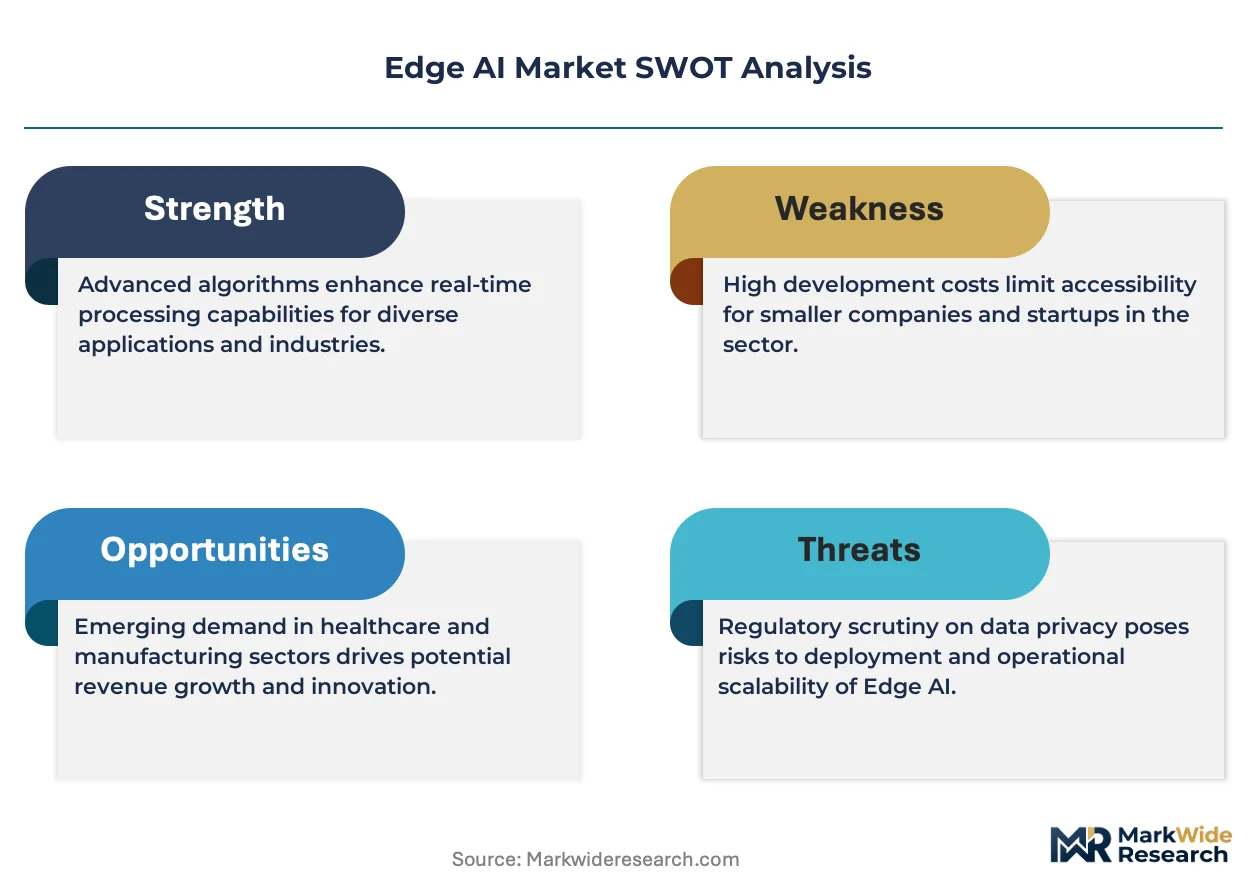
The EU AI Act imposes conformity assessment obligations on high-risk edge systems deployed in healthcare and transport, directly conditioning market access for non-EU chip vendors. The FCC in the United States governs spectrum allocation for edge-connected devices, shaping deployment economics for private 5G networks in industrial settings. China's SAMR enforces algorithmic recommendation regulations that affect edge-based personalization engines. Stakeholders must monitor divergence between Brussels' risk-classification approach and Washington's sector-specific agency model, as compliance architecture choices made today will determine geographic addressability for next-generation edge platforms.
Market Dynamics
The Edge AI market is being fundamentally restructured by thermal envelope constraints below 10 watts colliding with millisecond latency requirements for real-time inference, forcing silicon architects to abandon cloud-centric design assumptions.
Growth Catalysts
- EU AI Act conformity assessment:Mandatory certification for high-risk embedded systems in healthcare and transport is creating a two-tier vendor landscape where certified suppliers capture premium positioning.
- Automotive on-vehicle inference:German manufacturers are accelerating chip deployment for autonomous decision-making where network connectivity is intermittent or bandwidth costs are prohibitive.
- Shenzhen hardware ecosystem clustering:Fabless semiconductor design houses concentrate edge device production, enabling rapid prototyping cycles and captive foundry relationships.
Market Restraints
- Memory bandwidth limitations:Natural Language Processing at the edge remains constrained by battery-powered endpoint architectures, compressing addressable application scope.
- Silicon supply concentration:Advanced node fabrication depends on a concentrated foundry base, exposing edge chip vendors to geopolitical friction and allocation risk.
- Regulatory divergence costs:Brussels' risk-classification approach diverges from Washington's sector-specific agency model, forcing compliance architecture investments that limit geographic addressability.
Strategic Opportunities
- Industrial private 5G networks:FCC spectrum allocation rulings are reshaping deployment economics for factory-floor edge computing in the United States.
- Computer Vision quality inspection:Manufacturing defect detection represents the fastest-expanding margin pool as vision transformers shrink to sub-watt inference footprints.
- ISO/IEC 23053 trustworthiness certification:Early certification creates defensible positioning as procurement specifications harden around verified AI system reliability.
Industry Challenges
- Embedded systems firmware talent scarcity:The intersection of machine learning optimization and real-time operating systems expertise remains thinly staffed across hardware vendors.
- Legacy industrial control integration:Brownfield deployment requires protocol translation layers that inflate system cost and latency budgets.
- Conformity assessment timeline compression:EU AI Act notification body capacity constraints are extending market entry timelines for novel high-risk applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge AI Market |
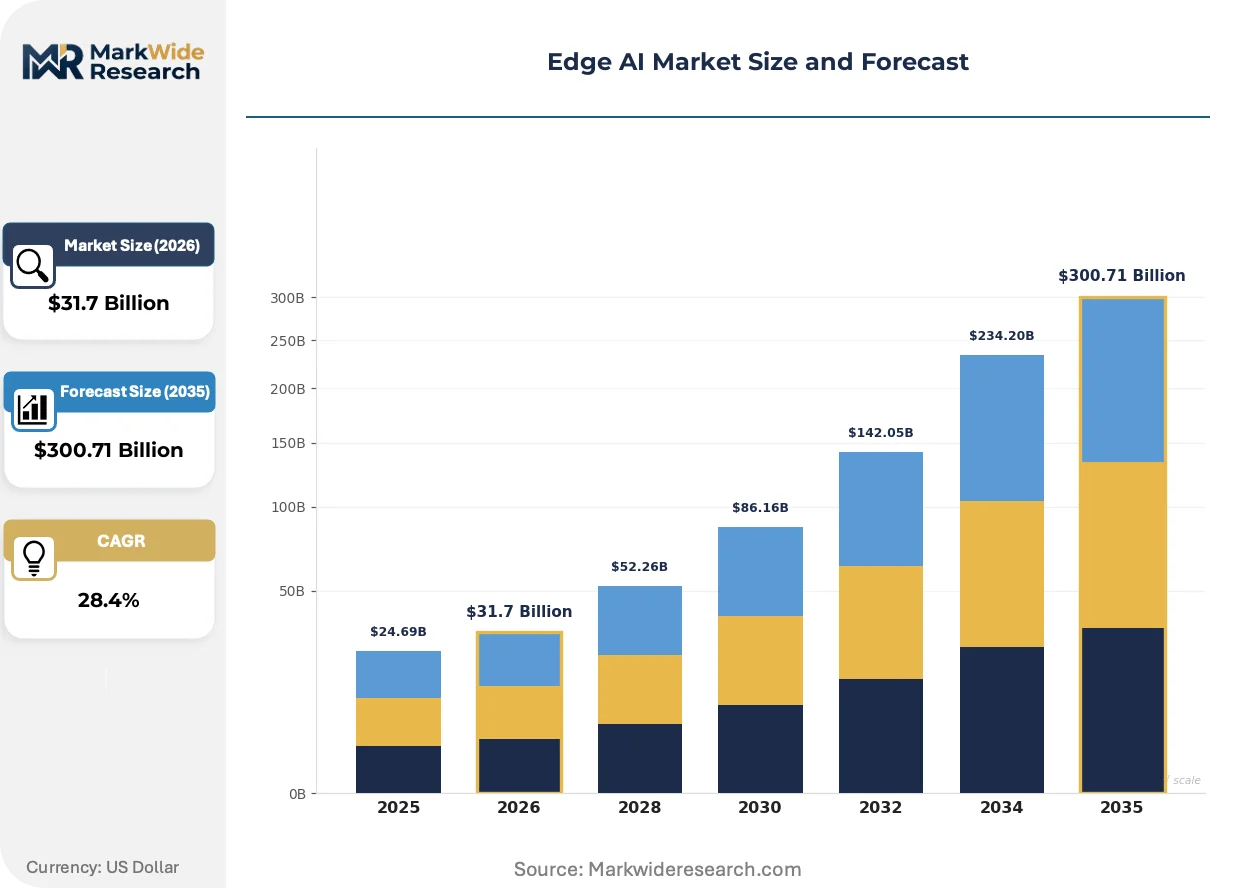
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $300.71 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Edge Integration, Hybrid, Cloud-Based End User: Manufacturing, Healthcare, Retail, Transportation Technology: Machine Learning, Computer Vision, Natural Language Processing, Image Recognition Application: Predictive Maintenance, Smart Home Solutions, Video Analytics, Autonomous Vehicles |
| Companies Covered | Qualcomm Technologies, Inc., NVIDIA Corporation, Intel Corporation, Apple Inc., Samsung Electronics, Huawei Technologies Co., Ltd., MediaTek Inc., Google LLC, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge AI Market Emerging Trajectories
Silicon architecture is actively fragmenting between cloud-trained model compression and native edge training capabilities, with thermal design power becoming the primary competitive battleground.
Neuromorphic computing architectures are bifurcating the inference chip landscape. These event-driven designs mimic biological neural processing to achieve sub-milliwatt operation for always-on sensing. Automotive tier-1 suppliers are adopting them for cabin monitoring and predictive maintenance. The technology is bifurcating vendor tiers into those with spiking neural network compiler stacks and those locked into conventional frame-based pipelines.
REACH substance restrictions and RoHS recast directives are tightening material compliance for edge devices deployed in European industrial settings. Component suppliers must now document full supply chain substance declarations for persistent organic pollutants. Medical edge AI devices face the steepest compliance ramps as MDR technical documentation requirements merge with AI Act algorithmic transparency obligations.
Buyers are consolidating vendor relationships around full-stack edge platforms rather than discrete silicon procurement. Industrial automation purchasers now specify combined hardware-software-service contracts that bundle model training, edge deployment, and continuous validation. This pattern is most pronounced in German automotive supply chains, where OEMs are reducing qualified supplier lists from twelve to three full-stack partners.
Edge AI Market Segmentation
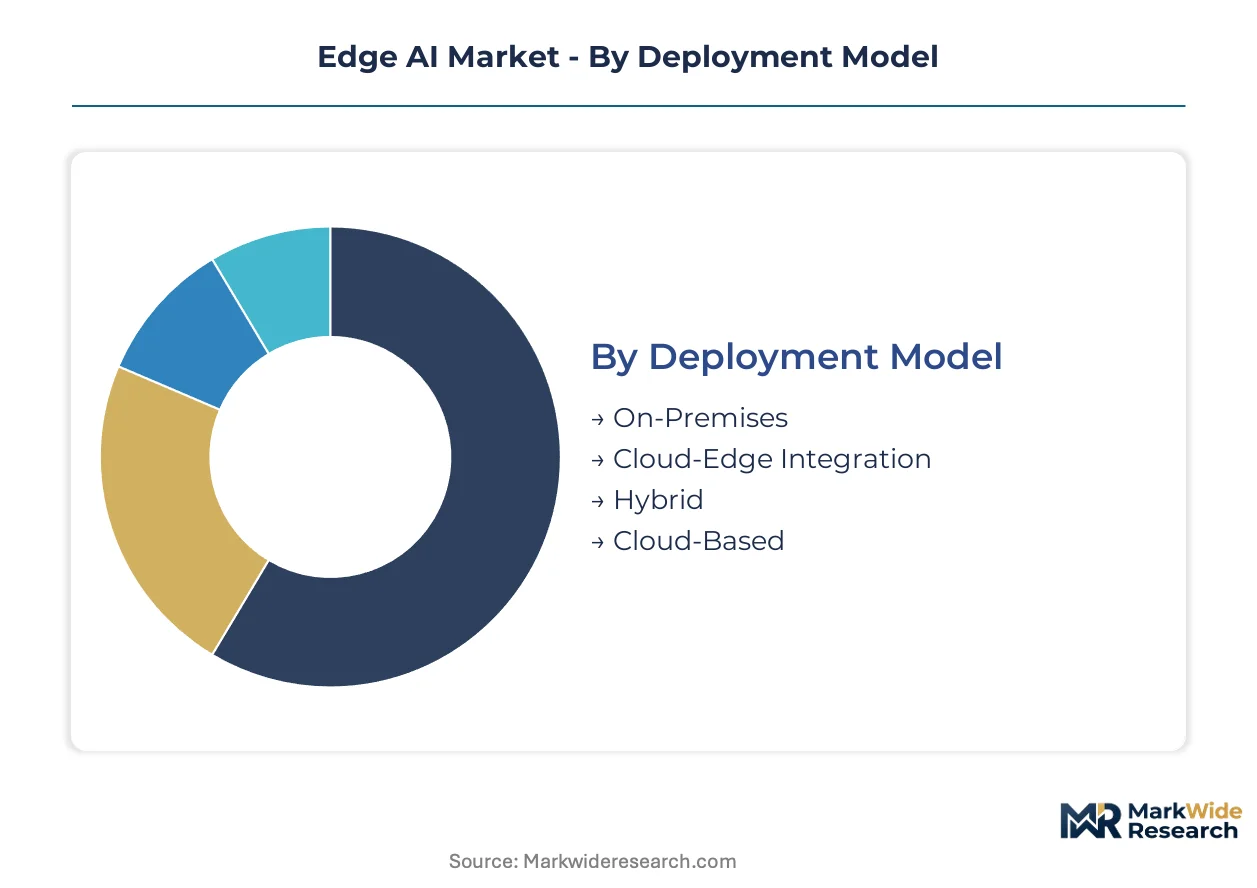
Edge AI segmentation reveals how thermal constraints and latency requirements reshape procurement patterns across deployment architectures. Buyers increasingly specify combined hardware-software bundles rather than discrete component sourcing.
Deployment Model:
Channel flow diverges sharply between capital-intensive on-premises installations and subscription-driven cloud-edge hybrids, with systems integrators capturing margin in the former and hyperscalers dominating the latter.
- On-Premises:Dedicated edge servers and industrial gateways deployed within facility firewalls, running inference workloads on customer-owned silicon. German automotive manufacturers favor this model for autonomous testing facilities where data sovereignty precludes cloud transmission. KBA certification requirements for high-risk systems reinforce preference for controlled infrastructure.
- Hybrid:Split inference pipelines where preprocessing occurs locally and model refinement feeds to centralized training clusters. Shenzhen hardware vendors bundle edge devices with managed connectivity services, capturing recurring revenue streams. This architecture dominates smart factory deployments where intermittent connectivity demands local fallback capability.
- Cloud-Edge Integration:Tightly coupled architectures with continuous synchronization between endpoint and cloud orchestration layers.
- Cloud-Based:Centralized inference with edge devices serving primarily as data collection terminals.
On-Premises dominates installed base. Hybrid is where expansion concentrates.
End User:
Cost tier stratification separates high-complexity regulated deployments from price-sensitive commercial implementations.
- Manufacturing:Computer vision quality inspection and predictive maintenance drive silicon allocation toward sub-10 watt inference accelerators. EU AI Act conformity assessment obligations for high-risk embedded systems elevate certified vendor premiums. REACH substance documentation requirements add procurement overhead for European industrial deployments.
- Healthcare:Diagnostic imaging and patient monitoring applications face MDR technical documentation merged with algorithmic transparency mandates. Medical edge AI devices confront the steepest compliance ramps as notified body capacity constraints extend market entry timelines. Battery-powered endpoints remain limited by memory bandwidth for NLP workloads.
- Retail:Inventory tracking and customer analytics applications prioritize low-cost vision sensors over precision inference.
- Transportation:On-vehicle inference chips for autonomous decision-making where network connectivity is intermittent.
Manufacturing captures the largest silicon volume. Healthcare is climbing the fastest as regulatory frameworks mature.
Technology:
Application maturity determines whether segments command premium pricing or compete on unit cost.
- Machine Learning:Neural network inference engines compressed for microcontroller-class devices, currently commanding the largest silicon allocation across edge deployments. Qualcomm's Snapdragon platform anchors mobile-native acceleration through automotive and IoT verticals. Firmware talent scarcity at the intersection of ML optimization and real-time operating systems constrains vendor scaling.
- Computer Vision:Vision transformers shrunk to sub-watt inference footprints for manufacturing defect detection. This segment represents the steepest expansion trajectory as neuromorphic event-driven architectures bifurcate vendor tiers between spiking neural network compilers and conventional frame-based pipelines. FCC spectrum rulings for private 5G networks reshape factory-floor deployment economics.
- Natural Language Processing:Constrained by memory bandwidth limitations on battery-powered endpoints.
- Image Recognition:Specialized convolutional accelerators for biometric and security applications.
Machine Learning dominates current procurement. Computer Vision is gaining share fastest as transformer architectures shrink.
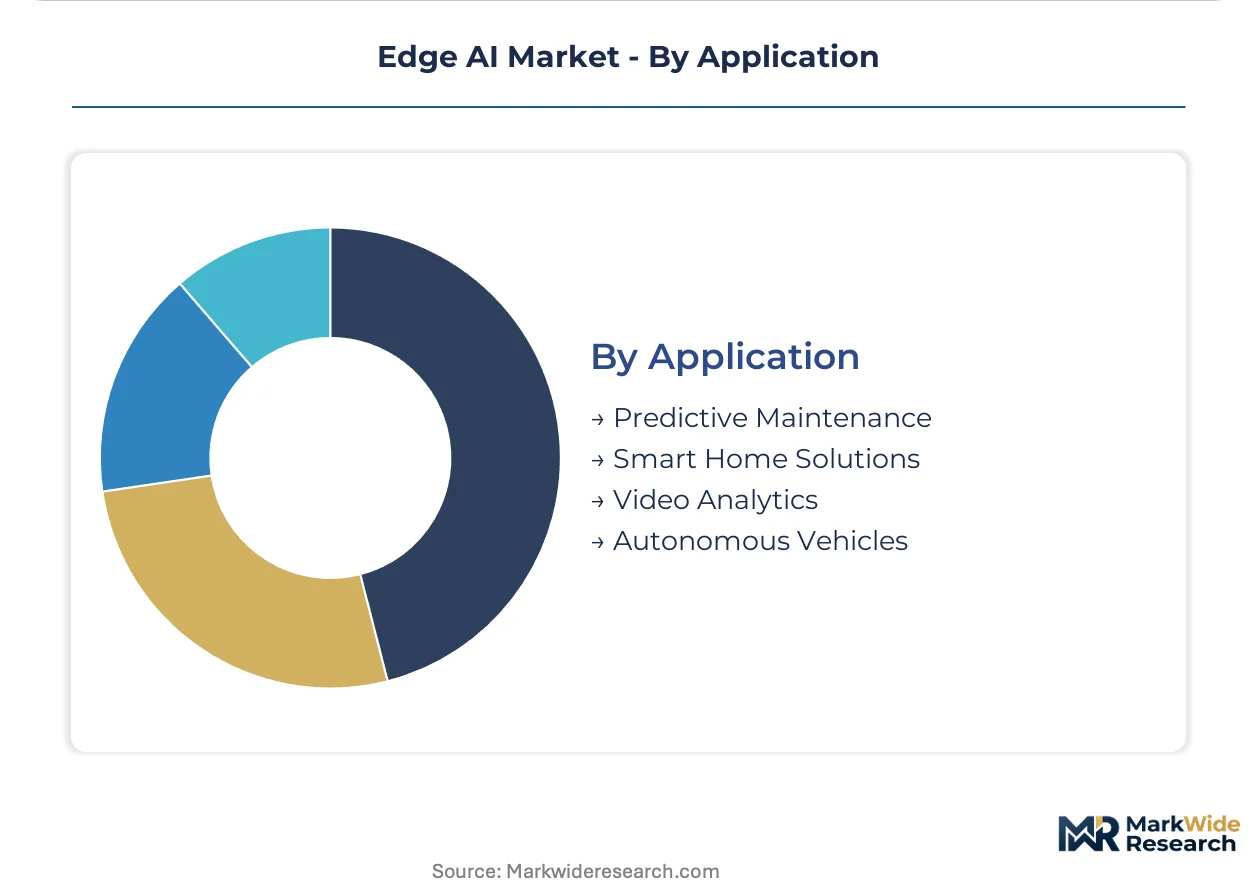
Application:
Customer type fragmentation separates industrial buyers specifying full-stack contracts from consumer markets purchasing discrete hardware.
- Predictive Maintenance:Vibration and thermal sensor fusion for industrial equipment failure forecasting, requiring always-on sub-milliwatt operation. Neuromorphic computing architectures from automotive tier-1 suppliers enable cabin monitoring and predictive maintenance with event-driven efficiency. Brownfield deployment demands protocol translation layers that inflate system cost.
- Autonomous Vehicles:On-vehicle inference for path planning and obstacle detection where millisecond latency constraints preclude cloud dependency. German OEMs are consolidating qualified supplier lists from twelve to three full-stack partners, bundling model training, edge deployment, and continuous validation. ISO/IEC 23053 trustworthiness certification creates defensible positioning as procurement specifications harden.
- Smart Home Solutions:Voice assistants and environmental control with aggressive cost targets.
- Video Analytics:Surveillance and traffic monitoring with varying privacy constraints across jurisdictions.
Predictive Maintenance anchors industrial demand. Autonomous Vehicles is where vendor consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation buyers cluster in Germany, healthcare procurement concentrates in the United States, and hardware manufacturing gravity sits in China's southern coastal provinces.
United States
Healthcare diagnostic imaging and autonomous vehicle testing drive edge AI silicon procurement. FDA device classification rules intersect with HIPAA data handling constraints for medical edge deployments. Austin and Detroit anchor competing clusters, with Austin housing hyperscaler edge orchestration labs and Detroit concentrating automotive tier-1 integration facilities.
Germany
Automotive on-vehicle inference and industrial quality inspection absorb the majority of regional edge compute investment. KBA certification requirements for high-risk embedded systems extend procurement cycles for non-EU chip vendors. Bavaria's Munich-Stuttgart corridor hosts OEM consolidation of qualified supplier lists from twelve to three full-stack partners.
China
Shenzhen's hardware ecosystem concentrates fabless semiconductor design houses with captive foundry relationships for rapid prototyping. SAMR algorithmic recommendation regulations affect edge-based personalization engines in consumer devices. The Pearl River Delta cluster ships the majority of vision transformers for manufacturing defect detection globally.
Japan
Predictive maintenance for industrial robotics and precision manufacturing equipment dominates domestic edge AI demand. METI subsidies for Industry 4.0 adoption accelerate factory-floor deployment of sub-10 watt inference accelerators. Nagoya's Chubu region anchors automotive tier-1 supplier adoption of neuromorphic computing for cabin monitoring.
South Korea
Smart factory deployments and consumer electronics integration represent the primary demand vectors. MFDS medical device regulations create compliance overlays for healthcare edge AI applications separate from general electronics standards. Seoul Capital Area concentration of memory semiconductor fabricators shapes local edge chip supply chain configurations.
Edge AI Market Vendor Landscape
Player mix skews toward semiconductor incumbents with existing mobile or data center franchises extending into thermal-constrained environments. Three tiers have crystallized: CUDA-ecosystem dominants leveraging software stack lock-in, mobile-native platforms with automotive cross-over capability, and neuromorphic specialists pursuing sub-milliwatt event-driven architectures. Competitive moves concentrate on full-stack bundling and ISO/IEC 23053 certification pre-positioning.
Within the mobile-to-automotive cross-over tier, Qualcomm Technologies, Inc. and MediaTek Inc. exemplify platform consolidation strategies. NVIDIA Corporation anchors the data center-to-edge pipeline segment. These three entities represent divergent thermal-design-power optimization philosophies, with each occupying a distinct position in the inference acceleration hierarchy without direct segment overlap.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| NVIDIA Corporation |
| Intel Corporation |
| Apple Inc. |
| Samsung Electronics |
| Huawei Technologies Co., Ltd. |
| MediaTek Inc. |
| Google LLC |
| Microsoft Corporation |
| Others |
Supply Flow & Price Mechanics
ISO/IEC 23053 trustworthiness certification gates both supplier qualification and price differentiation simultaneously, bifurcating procurement into certified premium tiers and uncertified commodity alternatives while automotive OEMs in Germany consolidate vendor lists around full-stack partners.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate high-volume automotive procurement, while subscription-based edge platform bundles capture recurring revenue in smart factory deployments. Three-tier pricing structure across certified-premium, qualified-standard, and unverified-economy levels reflects EU AI Act conformity assessment status. Cost compression in microcontroller-class inference accelerators is intensifying because Shenzhen fabless vendors are flooding consumer IoT segments. Retail and smart home buyers exhibit acute price sensitivity, whereas German automotive OEMs prioritize certification over unit cost.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Shenzhen corridor and container availability at Yantian Port shape landed cost structures for European and North American buyers. Advanced node fabrication concentrates in Taiwan, South Korea, and the United States, while legacy node edge silicon sources from China's Pearl River Delta. Raw material dependencies span silicon wafers, advanced packaging substrates, and rare earth elements for magnetic components. Single-source vulnerability at leading-edge foundries exposes vendors to geopolitical friction and allocation constraints. Distribution runs through tier-1 electronics distributors and direct OEM partnerships for automotive-qualified chips.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge AI sits in early-cycle expansion as autonomous vehicle inference requirements and industrial quality inspection demands accelerate silicon deployment ahead of mature cloud saturation.
For Market Incumbents: Consolidate full-stack capabilities through backward integration into compiler software and model optimization tools to defend against neuromorphic computing specialists. Capture ISO/IEC 23053 certification early to lock in German automotive procurement specifications before notified body capacity constraints extend rival timelines. For New Entrants and Emerging Players: Lead with sub-milliwatt neuromorphic architectures for always-on predictive maintenance in Japanese industrial robotics, where METI subsidies reduce customer acquisition friction. Target brownfield protocol translation as a service layer to bypass direct silicon competition with CUDA-ecosystem dominants. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive tier-1 suppliers spinning off edge AI software divisions to focus on core electromechanical systems. Long-term viability hinges on defensible compiler ecosystems rather than discrete chip design. Watch for EU AI Act notified body capacity expansion as the inflection signal for high-risk application market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 23053 Certification Investment | Creates procurement gatekeeping advantage as German OEMs harden supplier qualification requirements. |
| Neuromorphic Computing Platform Launch | Captures sub-milliwatt sensing segments where Qualcomm and NVIDIA architectures face thermal constraints. |
| Full-Stack Partnership with Shenzhen Fabless Vendor | Secures captive foundry access and rapid prototyping cycles for automotive inference chips. |
| Private 5G Network Deployment Bundle | Leverages FCC spectrum rulings to capture factory-floor edge computing economics in United States manufacturing. |
| EU AI Act Conformity Assessment Pre-Positioning | Extends market entry timelines for uncertified rivals while capturing premium positioning in healthcare transport. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with semiconductor architects, automotive platform engineers, industrial automation procurement leads, and notified body certification specialists; and secondary validation through SEC filings from NVIDIA and Qualcomm, hyperscaler edge capex disclosures, EU AI Act implementation guidance, and customs trade data for edge device component flows. Bottom-up silicon unit forecasts triangulated against top-down automotive and industrial automation spending projections.
Across the projection horizon, the analytical framework modeled deployment architecture, end-user vertical, technology type, and application use case as core segmentation dimensions. CAGRs derived from polynomial trend fitting of historical silicon allocation patterns, adjusted for EU regulatory timeline impacts and automotive platform transition cycles. Thermal design power constraints and memory bandwidth limitations anchored supply-side capacity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification investment, stable foundry allocation policies, and coherent EU AI Act enforcement would require recalibration. Forecasts reflect documented assumptions regarding certification body capacity expansion and neuromorphic compiler ecosystem maturity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
Permission-Aware AI Repository Gateway Market
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market