
 Brain Computer Interface Market | 2026-2036
Brain Computer Interface Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Computer Interface Market Intelligence
Silicon carbide microelectrode arrays are recalibrating cost-performance tradeoffs in invasive BCI hardware. Neuralink leverages vertical integration from chip fabrication to surgical robotics, sustaining control over its proprietary neural thread manufacturing. Blackrock Neurotech anchors its position through decades of Utah array clinical data, while Synchron differentiates via endovascular electrode delivery that avoids open craniotomy.
A brain computer interface constitutes a direct communication pathway between the central nervous system and external computational devices, typically employing electrode arrays with impedance below 100 kΩ at 1 kHz to capture neural signals with millisecond temporal resolution. Its primary commercial purpose centers on restoring motor function, communication capability, or sensory perception in individuals with neurological injury or disease. Non-invasive electroencephalography systems dominate current volume due to lower regulatory barriers and consumer accessibility, while invasive platforms capture the deepest margin pools through chronic implantation contracts and surgical service revenue. Medical treatment applications lead clinical value generation, whereas neurogaming represents the fastest-expanding consumer-facing segment as headset costs decline and software ecosystems mature.
The FDA breakthrough device program and EU MDR Class III implantable active device framework collectively determine market access timelines and clinical evidence requirements for neural interface developers. ISO 14155 clinical investigation standards and IEC 60601-1 electrical safety benchmarks shape hardware design protocols across all commercialization pathways. Stakeholders must monitor evolving reimbursement decisions from CMS and national health technology assessment bodies, as these will determine whether hospital procurement budgets expand beyond research grants into sustainable recurring revenue for BCI platforms.
Market Dynamics
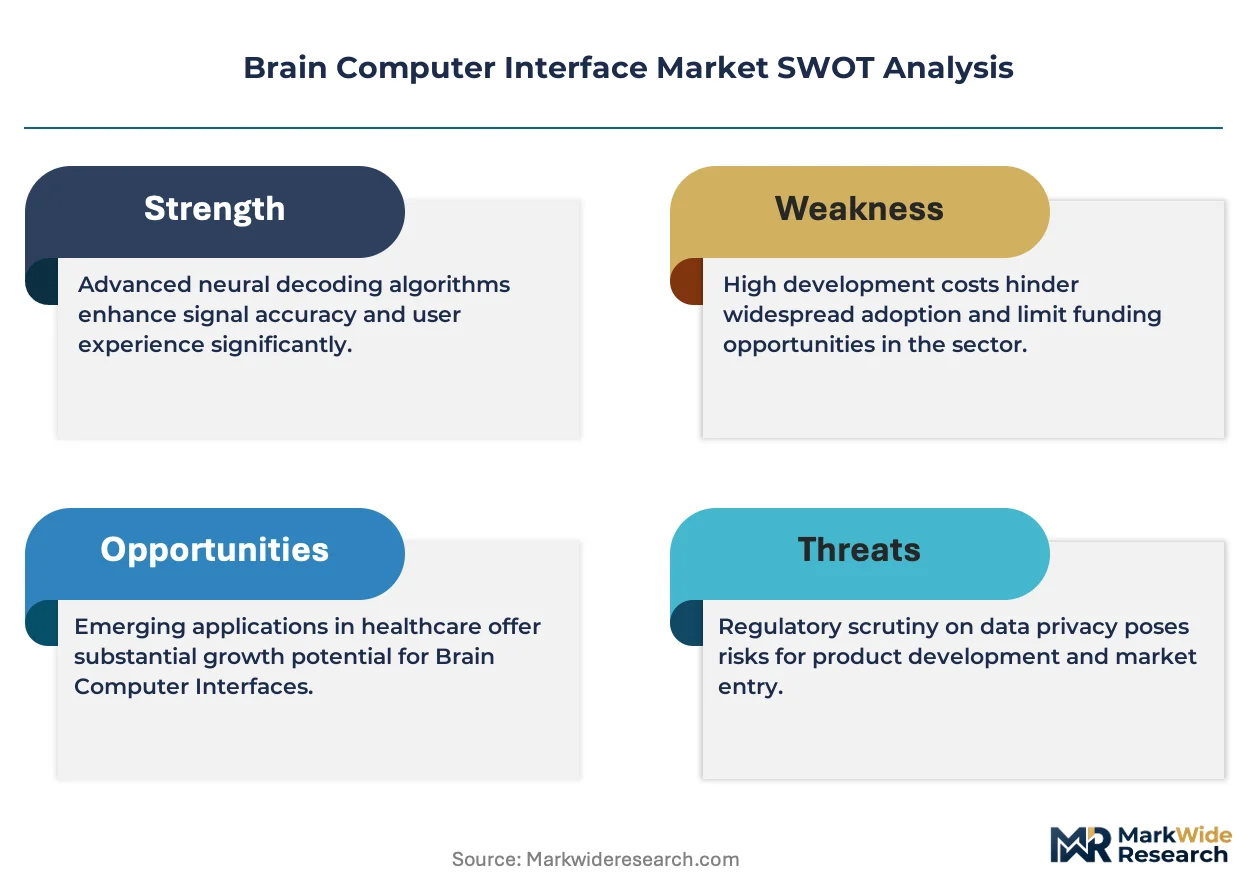
Silicon carbide microelectrode arrays are compressing cost-performance tradeoffs in invasive BCI hardware, forcing developers to recalibrate manufacturing strategies around chronic biocompatibility and signal fidelity benchmarks.
Growth Catalysts
- FDA breakthrough device pathway:The FDA's accelerated review framework for implantable neural interfaces is compressing clinical access timelines and reducing regulatory friction for first-in-human trials.
- Neurorehabilitation demand:Healthcare systems are integrating BCI platforms for stroke recovery and spinal cord injury motor restoration, creating pull-through from academic medical centers to community hospitals.
- Endovascular delivery methods:Catheter-based electrode placement through the jugular vein is eliminating open craniotomy requirements and expanding addressable patient populations.
Market Restraints
- Chronic biocompatibility limitations:Glial scarring around penetrating microelectrodes degrades signal quality over 12-24 month implantation windows, constraining long-term therapeutic efficacy.
- Neurosurgical infrastructure concentration:Qualified implantation centers cluster in major metropolitan hubs, limiting patient access outside tier-one hospital networks.
- Reimbursement uncertainty:CMS has not established distinct procedural codes for BCI implantation or programming, forcing providers to absorb costs under research grants.
Strategic Opportunities
- Consumer neurogaming:Electroencephalography headsets priced below five hundred dollars are penetrating fitness and wellness channels, creating volume opportunities outside regulated medical pathways.
- EU MDR Class III harmonization:The European Medical Device Regulation's implantable active device framework offers a parallel approval route that mutual recognition agreements may extend to other jurisdictions.
- Closed-loop neuromodulation convergence:Integration of BCI sensing with deep brain stimulation or spinal cord stimulation systems is enabling adaptive therapeutic adjustment based on real-time neural state detection.
Industry Challenges
- Neuroelectrophysiology talent scarcity:The specialized workforce spanning neural signal processing, biocompatible materials engineering, and regulatory affairs remains concentrated at a handful of academic institutions.
- ISO 14155 compliance burden:Clinical investigation standards for implantable active devices require extensive adverse event documentation and extended follow-up protocols that stretch startup cash runways.
- Signal decoding standardization gaps:Absence of interoperable neural data formats and machine learning model benchmarks forces redundant algorithm development across competing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Computer Interface Market |
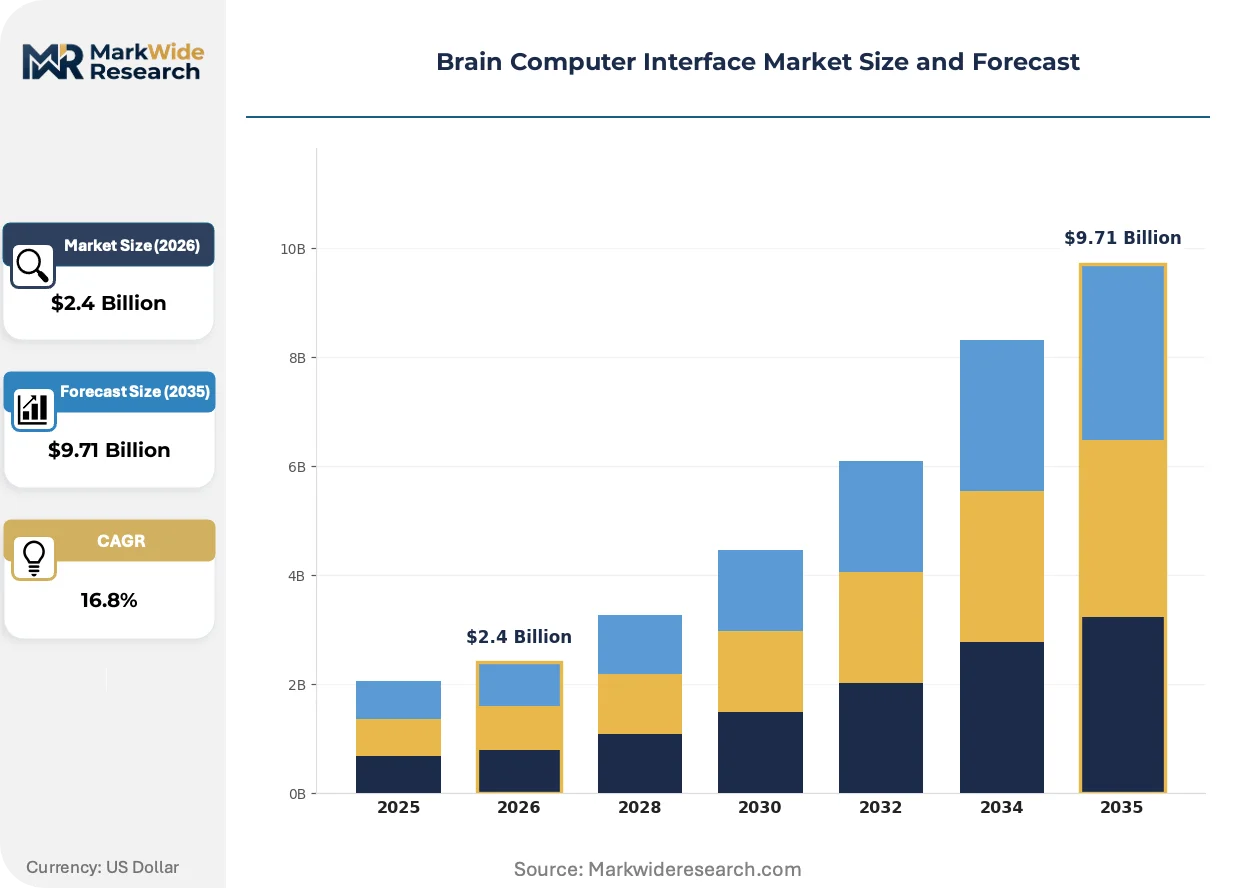
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $9.71 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Invasive, Non-Invasive, Partially Invasive, Electroencephalography End User: Healthcare, Gaming, Communication, Robotics Application: Medical Treatment, Rehabilitation, Neurogaming, Assistive Technology Component: Hardware, Software, Signal Processing Unit, Interface Device |
| Companies Covered | Neuralink, Blackrock Neurotech, Synchron, g.tec medical engineering, Advanced Brain Monitoring, Inc., Emotiv, Kernel, Paradromics, Brain Products GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Computer Interface Market Strategic Shifts & Innovations
Neural interface hardware is undergoing material and architectural transformation as developers pursue chronic implantation durability without sacrificing signal resolution. Three converging developments are compressing traditional tradeoffs between invasiveness and performance.
Silicon carbide microelectrode arrays are absorbing the thermal and mechanical stress that degrades traditional silicon probes in chronic neural implants. Academic medical centers in Germany and Japan are piloting these devices in motor cortex applications. The technology is absorbing investment from defense research programs seeking stable long-term brain-machine interfaces for prosthetic control.
The EU MDR Class III implantable active device framework is tightening clinical evidence requirements for neural interfaces seeking CE marking. Manufacturers must now submit post-market surveillance plans covering ten-year implantation windows. European neurotechnology startups are responding by front-loading clinical trials and establishing notified body relationships earlier in development cycles.
Hospital procurement committees are unbundling BCI hardware from surgical service contracts, forcing vendors to compete on electrode array pricing independent of robotic implantation systems. This pattern is most visible in United States academic medical centers where capital equipment budgets sit separate from disposable device purchasing. Neurotechnology suppliers are responding with electrode-only distribution agreements and third-party surgical training certifications.
Brain Computer Interface Market Segmentation
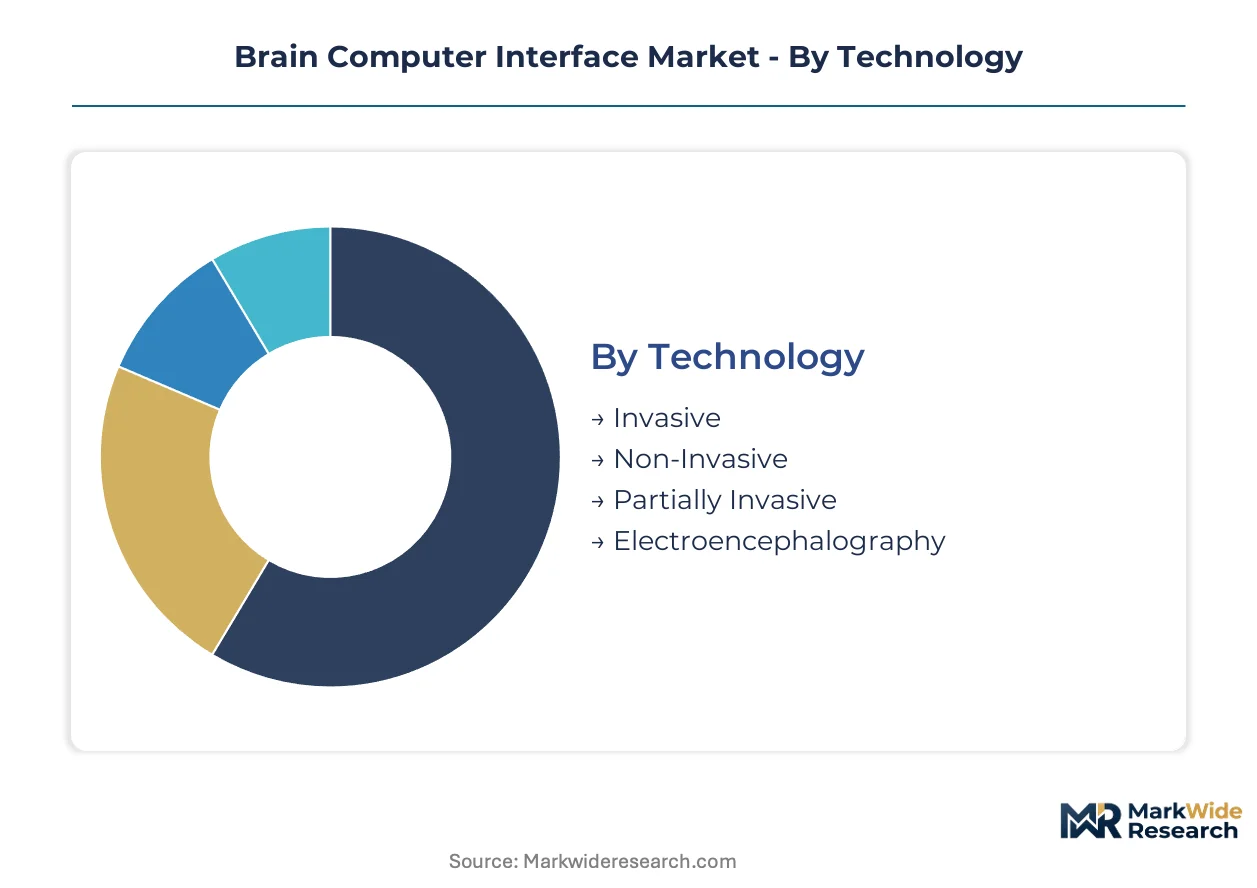
Segmentation in the BCI market reveals how technical specifications, regulatory pathways, and end-use economics create distinct commercial battlegrounds. Each dimension carries different margin profiles, customer concentration, and capital requirements that shape vendor strategy.
Technology:
The customization-standardization spectrum runs from fully bespoke surgical implants to mass-produced consumer headsets, with material choices and signal fidelity requirements determining manufacturing scale.
- Invasive:Penetrating microelectrode arrays with impedance below 100 kΩ capture single-neuron resolution through direct cortical implantation. Demand clusters at academic medical centers in the United States pursuing motor restoration for spinal cord injury patients, constrained by neurosurgical infrastructure bottlenecks and FDA breakthrough device review timelines.
- Non-Invasive:Electroencephalography headsets employing dry electrodes or conductive gel interfaces measure cortical electrical activity through the skull without surgical intervention. Volume concentrates in consumer wellness and neurogaming channels where sub-five-hundred-dollar price points drive accessibility, though signal attenuation limits clinical utility for precise motor decoding.
- Partially Invasive:Electrocorticography grids and endovascular stent-electrodes balance signal quality with reduced surgical trauma through placement beneath the skull or within cerebral vasculature. Synchron's catheter-delivered approach exemplifies this middle path.
- Electroencephalography:Scalp-recorded potential measurement systems dominate installed base through established clinical protocols for epilepsy monitoring and sleep diagnostics, with hardware commoditization pressuring margins.
Leading the category by volume: Non-Invasive. Expanding most quickly: Invasive platforms through chronic implantation contracts.
End User:
Customer type determines pricing power, with institutional procurement cycles in healthcare contrasting sharply with direct-to-consumer velocity in gaming.
- Healthcare:Hospital systems and rehabilitation centers purchase FDA-designated breakthrough devices through capital equipment budgets with extended service contracts. Neurorehabilitation departments at tier-one academic medical centers in Germany, Japan, and the United States anchor demand.
- Gaming:Individual consumers acquire electroencephalography headsets through retail and direct channels for focus training and immersive control interfaces. Hardware-software bundle economics favor ecosystem lock-in over margin extraction on devices alone.
- Communication:Assistive technology providers serving locked-in syndrome and advanced ALS patients represent concentrated high-value accounts with dedicated funding streams.
- Robotics:Prosthetic manufacturers and exoskeleton developers integrate BCI control modules into mobility restoration systems, with defense research programs supplementing medical demand.
Healthcare generates the deepest margins. Gaming climbs the fastest on unit volume expansion.
Application:
Clinical evidence requirements and reimbursement status create a maturity gradient from established therapeutic categories to speculative consumer use cases.
- Medical Treatment:Epilepsy monitoring, deep brain stimulation programming, and pre-surgical mapping employ electrocorticography and stereo-electroencephalography with established CPT codes and hospital reimbursement pathways.
- Rehabilitation:Stroke recovery and spinal cord injury motor restoration programs at Johns Hopkins Medicine, Stanford Health Care, and Charité Universitätsmedizin Berlin pilot closed-loop BCI-robotic therapy with research grant funding pending CMS coverage decisions.
- Neurogaming:Attention training and immersive entertainment applications leverage consumer electroencephalography hardware with minimal regulatory friction and rapid product iteration cycles.
- Assistive Technology:Communication interfaces for paralyzed patients represent the highest per-user value proposition, with Neuralink and Blackrock Neurotech competing for brain-to-text decoding performance benchmarks.
Medical Treatment holds the largest revenue base. Neurogaming traces the steepest volume trajectory.
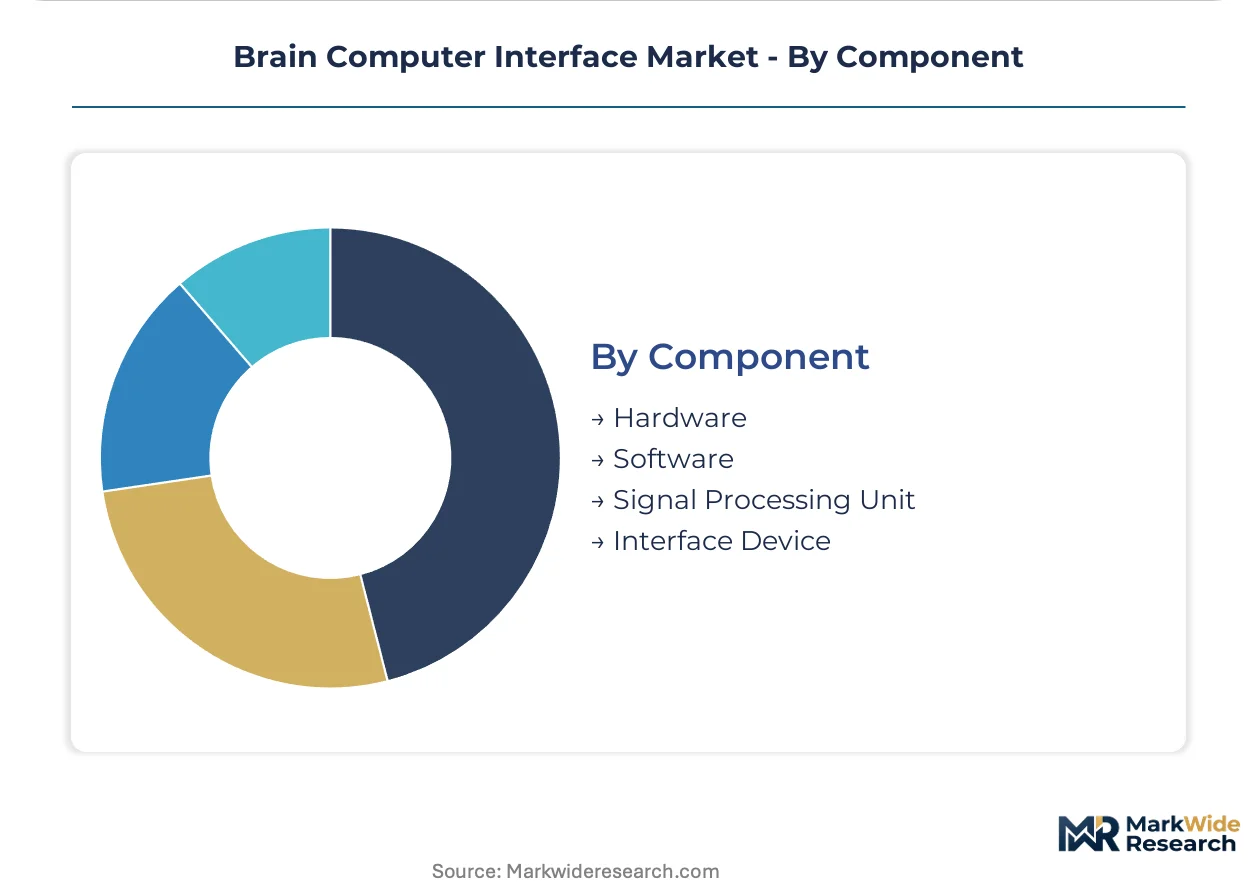
Component:
Supply chain concentration varies dramatically between commoditized electronics and specialized neural interface materials.
- Hardware:Electrode arrays, amplifiers, and biocompatible encapsulation materials constitute the highest-value captive manufacturing competency, with silicon carbide microelectrode production concentrated at specialized foundries.
- Software:Neural signal decoding algorithms and machine learning training pipelines represent the primary intellectual property differentiation layer, though absence of standardized data formats forces redundant development.
- Signal Processing Unit:Application-specific integrated circuits for real-time spike sorting and feature extraction operate under stringent IEC 60601-1 electrical safety and thermal dissipation constraints.
- Interface Device:Surgical robots, headset mounts, and telemetry modules complete system integration, with hospital procurement committees increasingly unbundling these from electrode array purchases.
Hardware commands the category's value concentration. Software gains share fastest as decoding performance becomes the primary competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial infrastructure and regulatory relationships concentrate demand in the United States, with Germany and Japan building parallel capabilities through academic medical center networks and national brain research initiatives.
United States
Neurorehabilitation departments at Johns Hopkins Medicine and Stanford Health Care drive institutional procurement of invasive BCI platforms for spinal cord injury motor restoration. The FDA breakthrough device designation pathway compresses review timelines for first-in-human neural interface trials. Neuralink and Synchron have established surgical robotics infrastructure and clinical investigator networks concentrated in California and New York metropolitan hubs.
Germany
Charité Universitätsmedizin Berlin and Heidelberg University Hospital anchor European demand for electrocorticography-based motor decoding research. The EU MDR Class III implantable active device framework mandates ten-year post-market surveillance plans for CE marking of neural interfaces. Bavaria-based academic consortia are piloting silicon carbide microelectrode arrays for chronic motor cortex applications with defense research program backing.
Japan
Osaka University and Tokyo Medical and Dental University lead Asia-Pacific clinical validation of brain-to-text communication interfaces for ALS patients. METI funding through the Brain/MINDS initiative supports translation of laboratory neural decoding algorithms into hospital-deployable systems. The Kansai region clusters electrode array foundries and neurosurgical robotics development with supply chain integration into precision manufacturing networks.
United Kingdom
Imperial College London and the University of Cambridge host concentrated neuroelectrophysiology talent pools for signal processing algorithm development. MHRA parallel scientific advice meetings allow synchronized FDA and UK regulatory strategy for implantable neural device developers. The Oxford-Cambridge-London golden triangle attracts venture financing for BCI startups targeting NHS procurement pathways.
China
Peking Union Medical College Hospital and Shanghai Jiao Tong University Affiliated Sixth People's Hospital conduct clinical investigations of non-invasive electroencephalography rehabilitation systems for stroke recovery. NMPA innovation review pathways for implantable active medical devices are compressing registration timelines for domestic neural interface manufacturers. The Yangtze River Delta concentrates consumer neurogaming hardware production with Shenzhen supply chain integration for sub-five-hundred-dollar headset manufacturing.
Brain Computer Interface Market Key Industry Players
Strategic partnerships dominate the current landscape as developers seek to combine specialized hardware manufacturing with clinical trial infrastructure and regulatory expertise. The vendor base organizes into three tiers: vertically integrated platform developers controlling surgical robotics and electrode fabrication; component specialists supplying standardized electrode arrays and signal processing units to multiple system integrators; and consumer-facing headset manufacturers competing on software ecosystem lock-in. Technology licensing and geographic expansion through academic medical center partnerships constitute the primary competitive moves, with capacity expansion in silicon carbide microelectrode foundries emerging as a secondary vector.
Within the vertically integrated platform tier, Neuralink exemplifies control over proprietary neural thread manufacturing and in-house surgical robotics production. Blackrock Neurotech occupies a position representing decades of Utah array clinical data accumulation and hospital procurement relationships. Synchron anchors the endovascular delivery specialization, demonstrating catheter-based electrode placement that bypasses open craniotomy requirements. These three companies collectively illustrate the strategic archetypes competing for chronic implantation contracts and surgical service revenue across United States and European hospital systems.
| Leading Market Players |
|---|
| Neuralink |
| Blackrock Neurotech |
| Synchron |
| g.tec medical engineering |
| Advanced Brain Monitoring, Inc. |
| Emotiv |
| Kernel |
| Paradromics |
| Brain Products GmbH |
| Others |
Cost & Logistics Intelligence
A sharp bifurcation between FDA-designated breakthrough devices and consumer-grade electroencephalography headsets manifests in divergent pricing architectures and supply chain configurations across the brain computer interface landscape. Premium invasive platforms command surgical service contracts and chronic implantation revenue streams through captive manufacturing of silicon carbide microelectrode arrays, while commodity neurogaming hardware sources standardized electronics from Shenzhen-based contract manufacturers.
Pricing Analysis
Volume-margin splits separate implantable neural interfaces from mass-market headsets. Three-tier pricing structure across premium, standard, and economy levels tracks regulatory certification intensity, with FDA breakthrough designation and EU MDR Class III CE marking commanding substantial premiums over wellness-grade alternatives. Cost compression in consumer electroencephalography intensifies as Shenzhen supply chain integration drives sub-five-hundred-dollar price points. Hospital procurement committees exhibit lowest price sensitivity for chronic implantation contracts, while individual gaming consumers demonstrate highest elasticity.
Supply Chain Analysis
Workforce availability constraints in specialized neuroelectrophysiology talent concentrate high-value electrode array fabrication in Germany, Japan, and the United States. Silicon carbide foundries in Bavaria and the Kansai region supply advanced microelectrode substrates, while surgical robotics assembly clusters in California and New York metropolitan hubs. Supply chain risk centers on single-source vulnerability for biocompatible encapsulation materials and application-specific integrated circuits. Distribution runs through academic medical center procurement committees for invasive platforms and direct-to-consumer channels for neurogaming hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA breakthrough device pathway requirements and EU MDR Class III implantable active device frameworks erect substantial barrier-to-entry moats favoring capitalized incumbents with established regulatory affairs infrastructure.
For Market Incumbents: Anchor market position through backward integration into silicon carbide microelectrode foundry capacity and exclusive surgical robotics deployment at tier-one academic medical centers. Threat of endovascular delivery methods from specialized entrants demands defensive patent positioning around catheter-based electrode placement. Priority lever rests on ten-year post-market surveillance data accumulation that new entrants cannot replicate. For New Entrants and Emerging Players: Enter via partially invasive endovascular delivery platforms that bypass open craniotomy infrastructure bottlenecks and expand addressable patient populations beyond concentrated neurosurgical hubs. White-space opportunity concentrates in stroke recovery applications at community hospitals lacking specialized implantation centers. Go-to-market angle emphasizes third-party surgical training certifications and electrode-only distribution agreements that unbundle from capital equipment procurement cycles. For Investors and Strategic Acquirers: Re-rating potential sits with component specialists controlling standardized electrode array supply to multiple system integrators, given hospital procurement committee unbundling trends accelerating electrode-only purchasing. Long-term viability favors platforms with demonstrated chronic biocompatibility data exceeding twelve-month implantation windows. Signal to watch is CMS establishment of distinct procedural codes for BCI implantation, which would convert research grant dependency into sustainable recurring revenue.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses first-in-human trial timelines for implantable neural interfaces. |
| EU MDR Class III CE Marking Pathway | Ten-year post-market surveillance requirements favor incumbents with longitudinal clinical data. |
| Hospital System Partnership | Academic medical center alliances secure surgical robotics deployment and investigator network access. |
| Silicon Carbide Foundry Investment | Captive microelectrode production insulates against supply chain concentration in specialized substrates. |
| Software Companion Development | Neural signal decoding algorithms constitute primary intellectual property differentiation layer. |
Research Approach
Document review covered FDA 510(k) and breakthrough device designation filings, EU MDR notified body guidance documents, and ISO 14155 clinical investigation standards, complemented by interviews with neurosurgeons, hospital biomedical engineers, GPO contracts managers, and neural interface regulatory affairs leads. Secondary sources included CMS reimbursement databases, hospital procurement records, and patent filings. Bottom-up demand modeling from individual procedure volumes triangulated against top-down market sizing from capital equipment expenditure flows.
Segmentation outputs across invasive, non-invasive, and partially invasive technology tiers; healthcare, gaming, communication, and robotics end users; and hardware, software, signal processing unit, and interface device components populated the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves modeling regulatory approval timelines and reimbursement decision lags. Industry-specific inputs incorporated FDA breakthrough device review velocity and EU MDR notified body capacity constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CMS reimbursement code establishment delays or chronic biocompatibility failures in silicon carbide microelectrode arrays. Material deviation in FDA breakthrough device pathway expansion or EU MDR notified body processing times warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Manufacturing Market
Artificial Intelligence (AI)
Brain-Computer Interface System Market
Artificial Intelligence (AI)
Voice User Interface Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Edge AI Software Market
Artificial Intelligence (AI)
AI Watermarking Market
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market