
 AI in Life Sciences Market | 2026-2036
AI in Life Sciences Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Life Sciences Market Outlook
The EU AI Act is hardening compliance requirements for high-risk AI applications in healthcare, forcing developers to embed transparency and human oversight into clinical algorithms from the design phase. Insilico Medicine leverages generative adversarial networks to compress target identification timelines, while Recursion Pharmaceuticals sustains massive cellular imaging datasets that power its phenotype-driven discovery engine. NVIDIA dominates the hardware layer with GPU architectures optimized for molecular dynamics simulations, giving it upstream control over computational throughput for the sector.
AI in life sciences denotes the application of machine learning, natural language processing, and predictive analytics to biological data generation, pattern recognition, and decision automation across research and care delivery, typically requiring petabyte-scale data infrastructure and specialized neural architectures trained on genomic, proteomic, or clinical corpora. Drug Discovery leads product type deployment as major pharmas outsource target validation to algorithmic platforms, while Machine Learning anchors technology adoption through its maturity in biomarker identification and patient stratification. Natural Language Processing shows accelerating traction in clinical trial protocol generation and regulatory document mining, though Robotics remains nascent outside laboratory automation settings.
The FDA, EMA, and WHO collectively shape market access through divergent post-market surveillance expectations and algorithmic bias audit requirements that fragment go-to-market strategies across jurisdictions. HIPAA constraints on training data access in the United States create friction for developers seeking to refine diagnostic models on real-world clinical records. Stakeholders must monitor how regulatory divergence between Washington and Brussels on explainability standards fragments platform development roadmaps and forces dual-track compliance investments.
Market Dynamics
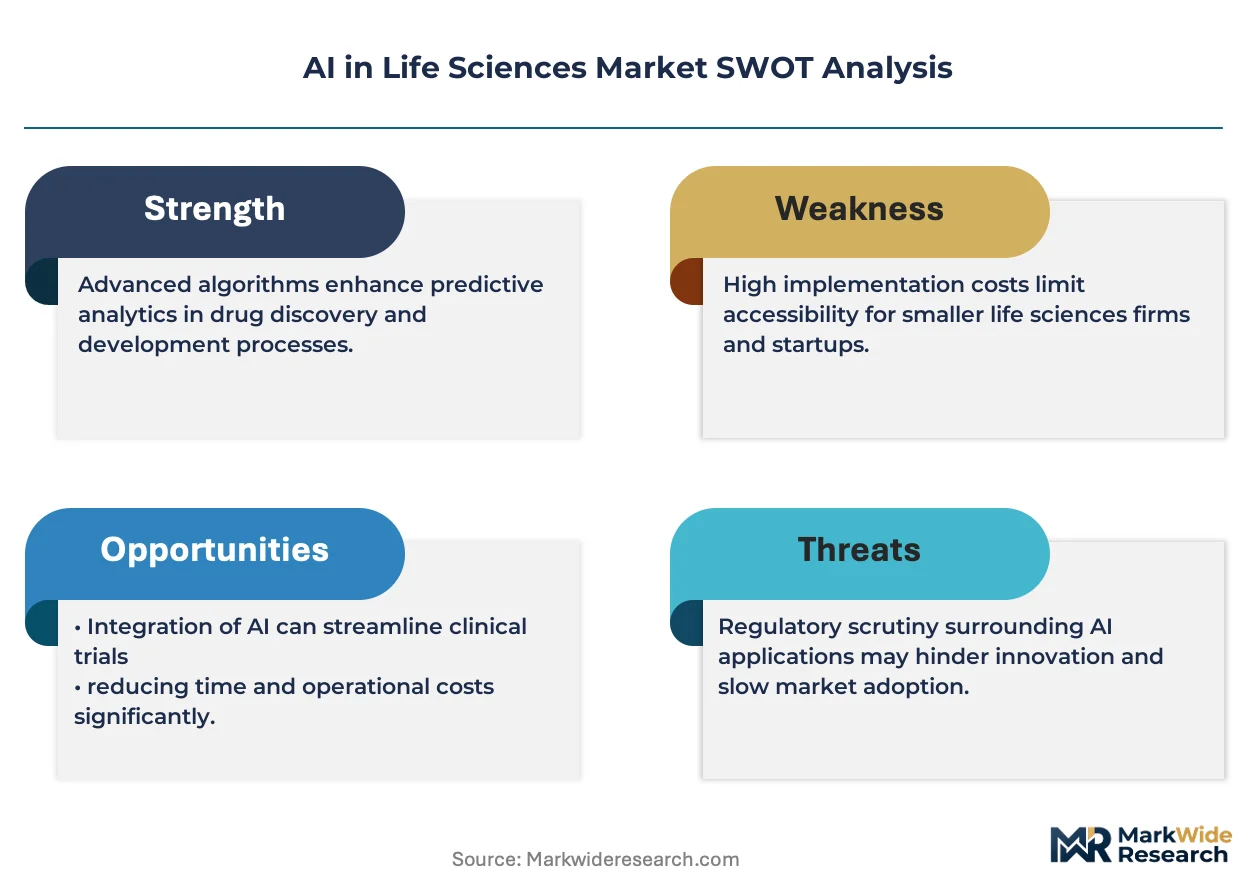
Pharmaceutical R&D pipelines are restructuring around generative architectures that compress target-to-lead timelines from years to months, forcing incumbents to outsource discovery layers or build captive AI capabilities.
Growth Catalysts
- FDA Algorithmic Bias Audits:Post-market surveillance requirements for AI-enabled medical devices are creating standardized validation protocols that reduce regulatory uncertainty for compliant developers.
- Generative Chemistry Platforms:De novo molecular design tools trained on proprietary structural databases are accelerating lead optimization cycles in oncology and rare disease programs.
- Boston-San Francisco Venture Concentration:Computational biology funding clusters in these metros are producing specialized talent pipelines that feed platform companies and Big Pharma partnerships.
Market Restraints
- GPU Supply Concentration:NVIDIA's dominance in molecular dynamics-optimized architectures creates single-source dependency for training infrastructure at petabyte scale.
- HIPAA Training Data Friction:Privacy constraints on real-world clinical record access limit model refinement for diagnostic applications in the United States.
- Explainability Standards Divergence:The EU AI Act's transparency mandates conflict with FDA interpretability expectations, forcing dual-track compliance investments.
Strategic Opportunities
- India's CDSCO Digital Pathways:The regulator's emerging framework for AI-enabled diagnostics offers first-mover positioning in a low-competition, high-volume market.
- Multimodal Foundation Models:Convergence of genomic, proteomic, and imaging data streams is enabling phenotype-to-target predictions previously requiring separate specialist teams.
- Cellular Imaging Data Marketplaces:Phenotype-driven discovery engines are creating demand for standardized, licensable biological datasets as an alternative to in-house generation.
Industry Challenges
- Computational Biology Talent Scarcity:Cross-training in both machine learning architectures and disease mechanism biology remains rare, inflating compensation for hybrid specialists.
- Legacy LIMS Integration:Laboratory information management systems designed for wet-lab workflows resist API connectivity with cloud-based AI pipelines, requiring custom middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Life Sciences Market |
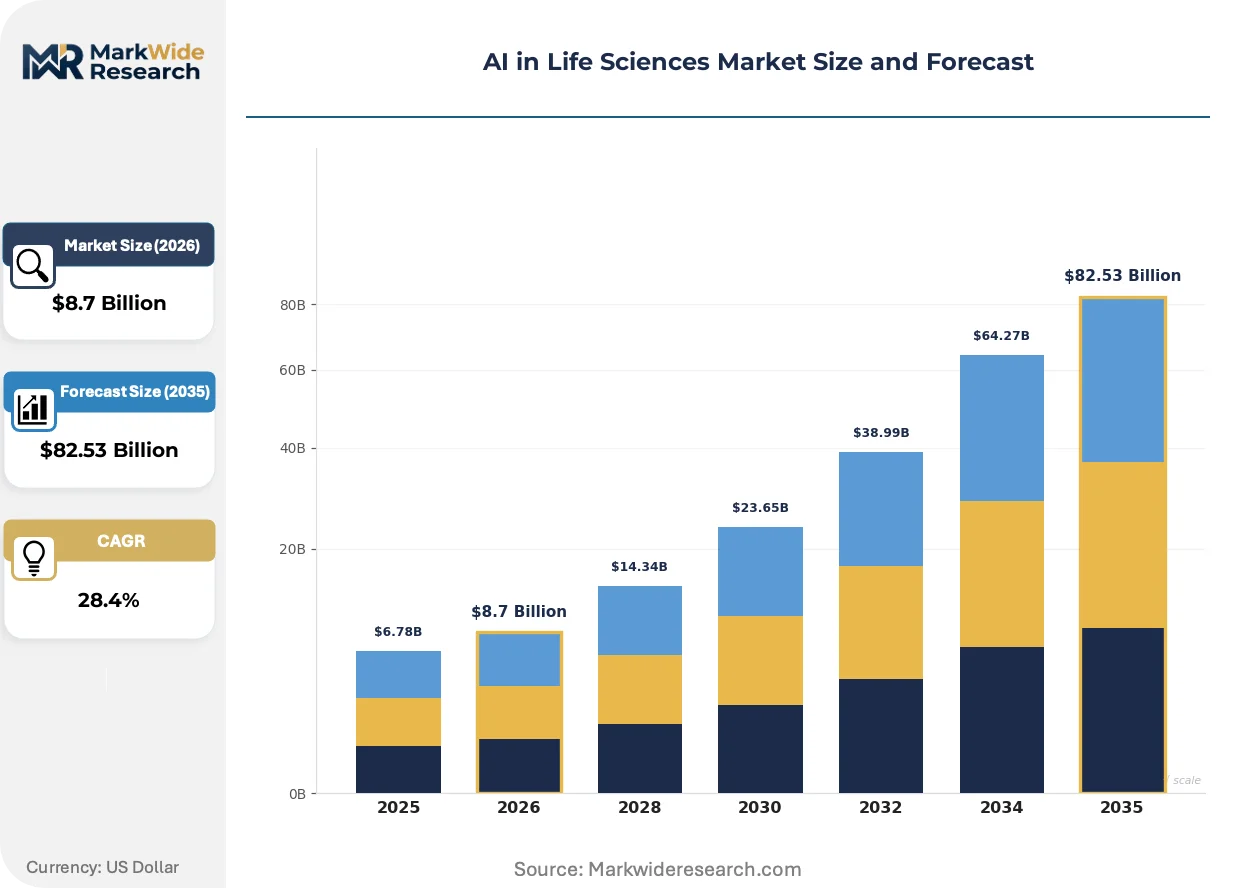
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Decision Support, Drug Discovery, Patient Monitoring, Workflow Optimization Technology: Natural Language Processing, Machine Learning, Predictive Analytics, Robotics End User: Pharmaceutical Companies, Academic Institutions, Healthcare Providers, Research Organizations Application: Clinical Trials, Personalized Medicine, Diagnostics, Drug Development |
| Companies Covered | IBM, Insilico Medicine, Tempus, Recursion Pharmaceuticals, BenevolentAI, Exscientia plc, Schrödinger, Inc., Atomwise Inc., NVIDIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Life Sciences Market Strategic Shifts
Foundation models trained on biological corpora are absorbing functions previously requiring separate specialist teams, compressing organizational boundaries between computational and experimental scientists.
Federated learning architectures are absorbing sensitive clinical data without centralizing protected health information, enabling multi-site model training across HIPAA-constrained hospital networks. Academic medical centers in the United States are adopting these frameworks faster than European counterparts due to stricter GDPR localization requirements. The structural consequence is a geographic split in collaborative AI development, with US institutions leading federated oncology trials.
The EU AI Act's high-risk healthcare application classification is forcing developers to embed human oversight mechanisms and algorithmic explainability from initial design phases. EMA parallel consultations on AI-enabled drug discovery tools are creating precedents for quality-by-design documentation that FDA guidance currently lacks. Small molecule discovery platforms face the steepest compliance burden, as their black-box generative models resist traditional mechanistic interrogation.
Biopharma procurement of AI discovery services is fragmenting from bundled platform licenses toward modular, milestone-based contracting that ties payments to validated target nominations. Mid-cap pharmas with constrained internal data science teams are driving this shift, using competitive benchmarking to pressure incumbent platform providers. The United Kingdom's Medicines and Healthcare products Regulatory Agency has accelerated adaptive trial designs that reward this flexibility, making British sites preferred partners for algorithmic protocol optimization.
AI in Life Sciences Market Segmentation
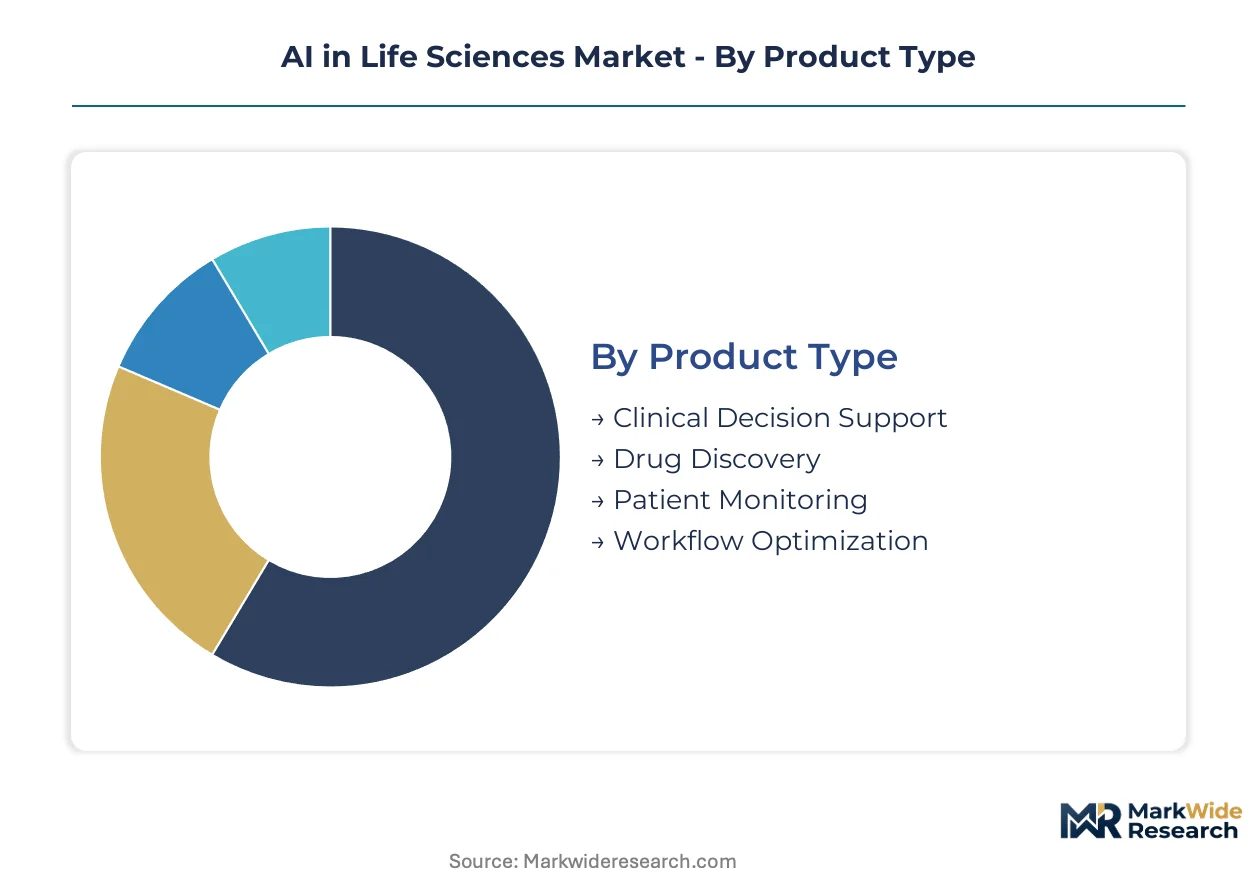
Platform architecture choices determine data infrastructure requirements and regulatory pathways for AI life sciences vendors. Segmentation reveals where computational investments concentrate and which customer types drive procurement decisions.
Product Type:
Upgrade cycles vary by therapeutic domain complexity, with oncology and rare disease programs demanding more frequent algorithmic refreshes than established therapeutic areas.
- Drug Discovery:Generative architectures compress target-to-lead timelines by training on proprietary structural databases. Demand concentrates among mid-cap pharmas in Boston and San Francisco outsourcing target validation to algorithmic platforms.
- Clinical Decision Support:Diagnostic algorithms embedded in electronic health records require continuous retraining on federated hospital networks. FDA post-market surveillance mandates create standardized validation protocols that reduce compliance uncertainty.
- Patient Monitoring:Wearable-derived biomarker streams enable real-time therapeutic adjustments.
- Workflow Optimization:Laboratory automation reduces manual protocol steps in high-throughput screening facilities.
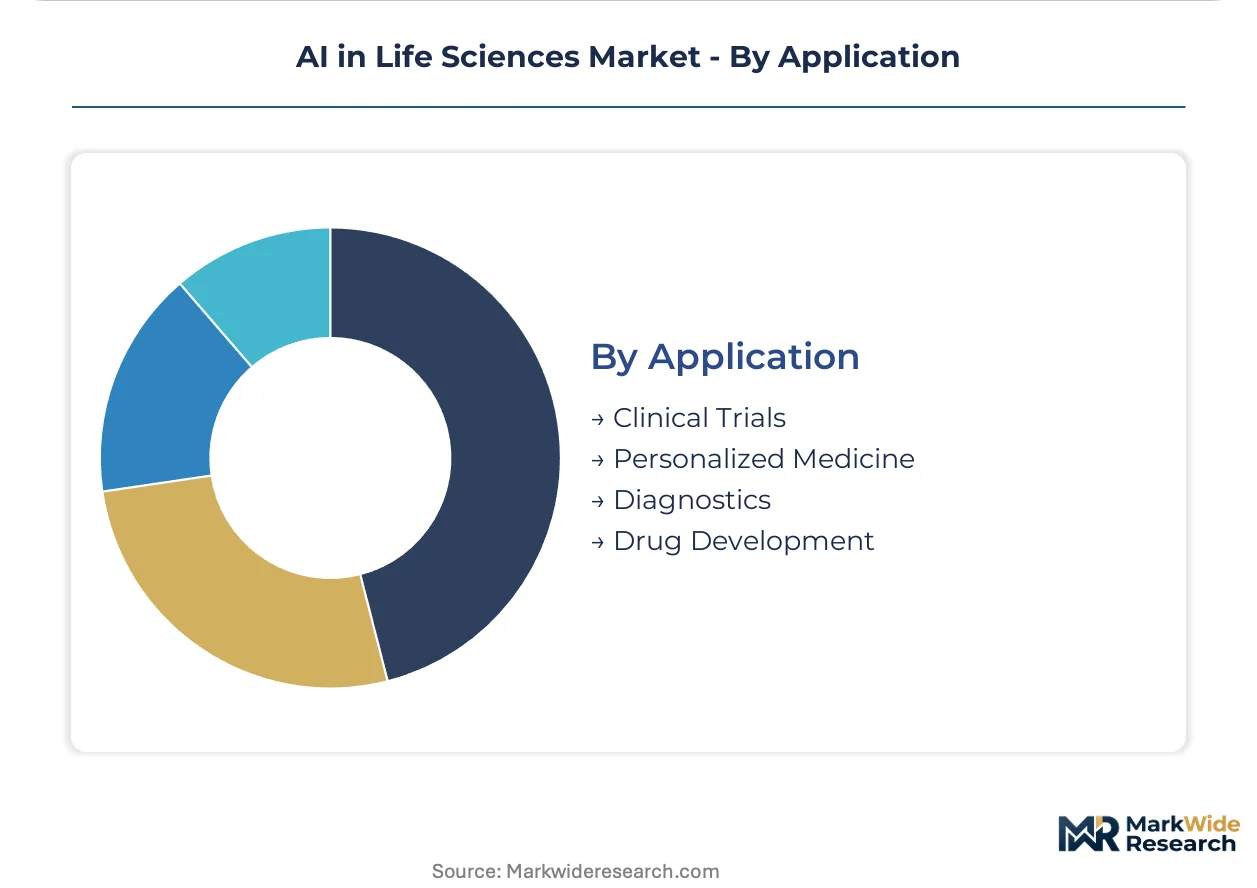
Drug Discovery sits at the top of the volume ranking, with Clinical Decision Support climbing the fastest.
Technology:
Cost tiers separate mature toolkits from emerging architectures, with established methods commanding premium pricing for validated regulatory submissions.
- Machine Learning:Supervised learning pipelines for biomarker identification and patient stratification represent the most mature deployment layer. Pharmaceutical procurement favors these proven frameworks for IND-enabling studies.
- Natural Language Processing:Clinical trial protocol generation and regulatory document mining accelerate as transformer architectures improve extraction accuracy from unstructured biomedical corpora.
- Predictive Analytics:Survival modeling and treatment response forecasting support adaptive trial designs.
- Robotics:Laboratory automation remains concentrated in liquid handling and imaging workflows.
Machine Learning captures the largest deployment base, while Natural Language Processing shows the steepest expansion trajectory.
End User:
Customer type dictates data access privileges and contracting structures, with commercial entities facing tighter privacy constraints than academic counterparts.
- Pharmaceutical Companies:Outsourced discovery partnerships and captive AI capabilities compete for R&D budget allocation. Mid-cap firms drive modular, milestone-based contracting that ties payments to validated target nominations.
- Healthcare Providers:Academic medical centers in the United States adopt federated learning faster than European counterparts due to GDPR localization requirements, leading collaborative oncology trials.
- Academic Institutions:NIH and NSF funding supports foundational biological corpus development.
- Research Organizations:CROs integrate algorithmic modules into traditional service offerings.
Pharmaceutical Companies dominate procurement volume, with Healthcare Providers gaining share fastest through hospital network consortiums.
Application:
Application maturity correlates with regulatory precedent density, with well-trodden pathways attracting conservative adopters and novel indications rewarding risk-tolerant entrants.
- Drug Development:Small molecule discovery platforms face the steepest EU AI Act compliance burden as black-box generative models resist traditional mechanistic interrogation. EMA parallel consultations create quality-by-design documentation precedents.
- Clinical Trials:Algorithmic protocol optimization receives accelerated pathways from the United Kingdom's Medicines and Healthcare products Regulatory Agency, making British sites preferred partners.
- Diagnostics:FDA algorithmic bias audits standardize validation for imaging-based classification tools.
- Personalized Medicine:Genomic stratification requires integration of multi-omic data streams.
Drug Development leads by commercial value, with Clinical Trials expanding most quickly through adaptive design adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artificial intelligence in life sciences originated from computational biology advances at MIT and Stanford during the 1990s, with early machine learning applications in protein folding prediction. This academic foundation seeded venture capital concentration in Boston and San Francisco that now drives platform commercialization.
United States
Venture funding clusters in Greater Boston and the San Francisco Bay Area feed specialized talent pipelines into platform companies and Big Pharma partnerships. FDA post-market surveillance mandates for AI-enabled medical devices create standardized validation protocols that reduce regulatory uncertainty. Academic medical centers adopt federated learning frameworks faster than European counterparts due to stricter GDPR localization requirements abroad.
United Kingdom
The Medicines and Healthcare products Regulatory Agency accelerates adaptive trial designs that reward algorithmic protocol optimization. British clinical sites attract algorithmic drug development partnerships seeking regulatory flexibility. London and Cambridge host concentrated discovery platform operations serving European pharmaceutical procurement.
Germany
EMA parallel consultations on AI-enabled drug discovery tools establish quality-by-design documentation precedents that shape EU compliance pathways. Heidelberg and Munich anchor industrial-academic consortia combining molecular dynamics simulation with pharmaceutical R&D. The country's national pharmaceutical regulator emphasizes mechanistic interrogation of generative models.
India
CDSCO's emerging framework for AI-enabled diagnostics offers first-mover positioning in a low-competition, high-volume market. Hyderabad and Bangalore clusters specialize in computational chemistry services and clinical data analytics outsourcing. The regulator's digital pathway development attracts platform companies seeking alternative approval routes to FDA or EMA processes.
Switzerland
Swissmedic maintains alignment with EMA standards while offering specialized consultation pathways for algorithmic drug discovery tools. Basel's pharmaceutical headquarters concentration drives demand for AI-enabled target validation services. The country's precision medicine initiatives create procurement opportunities for genomic stratification platforms.
AI in Life Sciences Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory validation depth, with algorithmic platforms commanding pricing power through FDA or EMA precedent density. The vendor base stratifies into three tiers: full-stack discovery platforms, modular algorithmic services, and infrastructure providers. Strategic archetypes include generative chemistry specialists, federated learning enablers, and hardware-software integrators. Competitive moves concentrate on milestone-based contracting structures and captive data generation partnerships.
Within the full-stack discovery tier, Insilico Medicine exemplifies generative adversarial network deployment for target identification, while Recursion Pharmaceuticals anchors phenotype-driven discovery through massive cellular imaging datasets. NVIDIA occupies a position upstream of platform competition through GPU architectures optimized for molecular dynamics simulations. BenevolentAI represents the European archetype combining natural language processing with disease mechanism mapping.
| Leading Market Players |
|---|
| IBM |
| Insilico Medicine |
| Tempus |
| Recursion Pharmaceuticals |
| BenevolentAI |
| Exscientia plc |
| Schrödinger, Inc. |
| Atomwise Inc. |
| NVIDIA |
| Others |
Value Chain & Pricing Dynamics
Computational biology talent scarcity in Boston and San Francisco clusters drives labor-cost differentials that widen pricing-tier spreads between premium algorithmic platforms and commodity analytics services.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates AI life sciences procurement, with differentiation hinging on FDA validation depth and proprietary dataset scale. Premium tiers command substantial markups for IND-enabling algorithmic outputs, while mid-cap pharmas squeeze standard-tier vendors through milestone-based contracting. Cost compression in economy-tier computational chemistry services is intensifying because Indian outsourcing clusters compete on labor arbitrage. Mid-cap pharmaceutical companies exhibit the highest price sensitivity, whereas Big Pharma captives accept premium pricing for regulatory precedent density.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and domestic-content mandates in semiconductor procurement are reshaping sourcing patterns for GPU-dependent training infrastructure. Supply concentrates in the United States for cloud compute, Taiwan for advanced GPU fabrication, and India for computational chemistry labor pools. Hardware dependencies center on NVIDIA GPU architectures, specialized cooling systems, and high-bandwidth memory modules. Single-source vulnerability from NVIDIA's molecular dynamics-optimized chip dominance creates concentration risk. Distribution runs through direct enterprise sales to pharmaceutical procurement teams, with cloud-based API access gaining share among mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI life sciences offers sustained margin expansion as generative platforms displace wet-lab FTE costs and premium-tier buyers absorb validation premiums for FDA-compliant outputs.
For Market Incumbents: Anticipate regulatory divergence between FDA interpretability expectations and EU AI Act transparency mandates by building dual-track compliance documentation from initial design phases. Deepen captive data generation partnerships to defend against emerging phenotype-driven discovery engines that commoditize target identification. Prioritize acquisition of federated learning specialists to secure hospital network access under HIPAA constraints. For New Entrants and Emerging Players: Mid-cap pharmas with constrained internal data science teams represent the most penetrable buyer archetype, as these organizations actively seek modular, milestone-based contracting that incumbents resist. CDSCO's emerging digital pathway for AI-enabled diagnostics offers first-mover positioning with lower competitive density than FDA or EMA routes. Lead with cellular imaging data marketplace propositions that eliminate capital-intensive in-house dataset generation. For Investors and Strategic Acquirers: Big Pharma AI strategy heads are the most active acquirers in this space, seeking generative chemistry capabilities that compress target-to-lead timelines. Long-term viability favors platforms with proprietary biological corpus depth and regulatory precedent density across multiple jurisdictions. Watch EMA quality-by-design documentation precedents as the inflection signal for EU compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Algorithmic Bias Audit Preparation | Standardized validation protocols reduce post-market surveillance uncertainty for compliant device developers. |
| Cellular Imaging Data Partnership | Massive phenotype datasets power discovery engines without capital-intensive in-house generation infrastructure. |
| Federated Learning Architecture Deployment | Multi-site model training absorbs HIPAA-constrained hospital data without centralizing protected health information. |
| Generative Chemistry Platform Launch | De novo molecular design tools trained on proprietary structural databases accelerate oncology lead optimization. |
| CDSCO Digital Pathway Engagement | First-mover positioning in India's emerging AI-enabled diagnostics framework bypasses FDA and EMA queue competition. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and computational biology platform engineers grounded this analysis. Secondary validation drew from FDA 510(k) filings, EMA scientific advice letters, ClinicalTrials.gov protocol registrations, and venture funding databases tracking Boston and San Francisco clusters. Bottom-up triangulation across platform revenue disclosures and top-down reconciliation against pharmaceutical R&D spending patterns ensured cross-verification.
Segment-level value and volume outputs across the projection horizon reflect modeled interactions between technology adoption curves, regulatory pathway durations, and therapeutic domain complexity. Segmentation dimensions included product type, underlying technology, end-user organization scale, and application maturity correlated with precedent density. CAGRs were derived from fitted growth curves anchored to disclosed platform bookings and pharmaceutical AI procurement survey data.
Underlying measurement precision varies by segment; drug discovery platforms with disclosed revenue carry tighter precision than early-stage clinical decision support tools. Forecasts embed assumptions regarding FDA guidance finalization timelines and EU AI Act implementation sequencing. Regulatory acceleration or delay in either jurisdiction could materially revise trajectory projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Edge AI Software Market
Artificial Intelligence (AI)
Text-To-Speech (TTS) Market
Artificial Intelligence (AI)
Image Recognition Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
AI As a Service (Aiaas) Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Decision Intelligence Market
Artificial Intelligence (AI)
AI in Project Management Market
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Manufacturing Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market