
 Digital Thermal Plates Market | 2026-2036
Digital Thermal Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Thermal Plates Market Insights
Multi-source procurement among commercial printers is broadening as converters reduce dependency on single plate vendors. FUJIFILM Holdings Corporation leverages its chemical coating expertise to sustain premium thermal plate supply across Asia-Pacific. Agfa-Gevaert NV anchors European demand through integrated prepress workflows. Heidelberger Druckmaschinen AG competes by bundling plate supply with press service contracts.
Digital thermal plates are aluminum-based lithographic printing surfaces coated with photopolymer or thermal-sensitive layers that image directly via laser exposure without chemical processing. These plates register at 2400 dpi or higher and tolerate run lengths exceeding 500,000 impressions in high-volume offset environments. Thermal plates dominate product type demand where chemistry-free variants capture margin pools from environmental compliance investments. Offset printing technology retains structural volume leadership while digital printing segments expand fastest among label manufacturers and short-run packaging providers.
REACH in Europe restricts solvent-based plate processing chemicals, compelling reformulation toward low-VOC thermal coatings. EPA air quality standards in the United States pressure commercial printers to abandon conventional wet-processing systems. ISO 12647 color management protocols shape plate calibration requirements for packaging providers serving multinational brand owners. Stakeholders must monitor regulatory divergence between jurisdictions when standardizing plate procurement across geographically distributed print operations.
Market Dynamics
Offset-to-digital plate conversion is accelerating as commercial printers face compressed turnaround demands from brand owners and packaging converters, forcing chemistry-dependent workflows toward thermal imaging systems that eliminate wet processing entirely.
Growth Catalysts
- REACH chemical restrictions:European ECHA mandates on solvent-based plate developers are compelling printers across Germany, France, and Italy to adopt chemistry-free thermal coatings that eliminate VOC emissions from prepress operations.
- Food-contact compliance:FDA food-contact material regulations in the United States are reshaping plate chemistry specifications as converters serving snack and beverage brands demand thermal plates with verified migration-safe coatings.
- Short-run packaging:Label manufacturers and folding carton converters are driving thermal plate volumes as brand owners fragment print jobs across multiple SKUs with faster revision cycles.
Market Restraints
- Aluminum substrate concentration:Primary aluminum smelting capacity for lithographic plate bases concentrates in China and Russia, exposing plate manufacturers to raw material supply disruptions and tariff volatility.
- Laser imaging capital intensity:Thermal CTP (computer-to-plate) systems require substantial upfront investment in 830nm and 1064nm diode laser arrays, limiting adoption among mid-tier commercial print shops with constrained capex budgets.
- Digital inkjet substitution:Single-pass inkjet presses from packaging equipment suppliers are capturing short-run work that previously migrated to thermal offset, compressing addressable plate volumes in the sub-10,000 impression segment.
Strategic Opportunities
- India packaging expansion:Domestic pharmaceutical and FMCG label converters in Mumbai and Ahmedabad represent underpenetrated demand as BIS standards alignment and FSSAI packaging rules drive quality upgrades.
- Processless thermal convergence:Integration of on-press imaging with chemistry-free thermal plates eliminates separate CTP equipment entirely, enabling direct-to-press workflows for newspaper and commercial printers seeking floor space reduction.
- Extended gamut packaging:Seven-color fixed palette printing using thermal plates with stochastic screening is displacing spot-color cylinder changes, creating margin expansion for flexible packaging converters serving cosmetic and premium food brands.
Industry Challenges
- Prepress technician scarcity:Skilled operators capable of calibrating thermal plate curves to ISO 12647-2 color standards are retiring faster than training programs in North America and Western Europe can replenish talent pipelines.
- Legacy CTP integration:Commercial printers with mixed-vendor press fleets face workflow fragmentation when attempting to standardize thermal plate specifications across Heidelberg, Komori, and KBA equipment with proprietary RIP configurations.
- REACH-SVHC documentation:European converters must maintain detailed substance-of-very-high-concern declarations for thermal plate coatings across complex multi-tier chemical supply chains, extending procurement cycles and audit burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Thermal Plates Market |
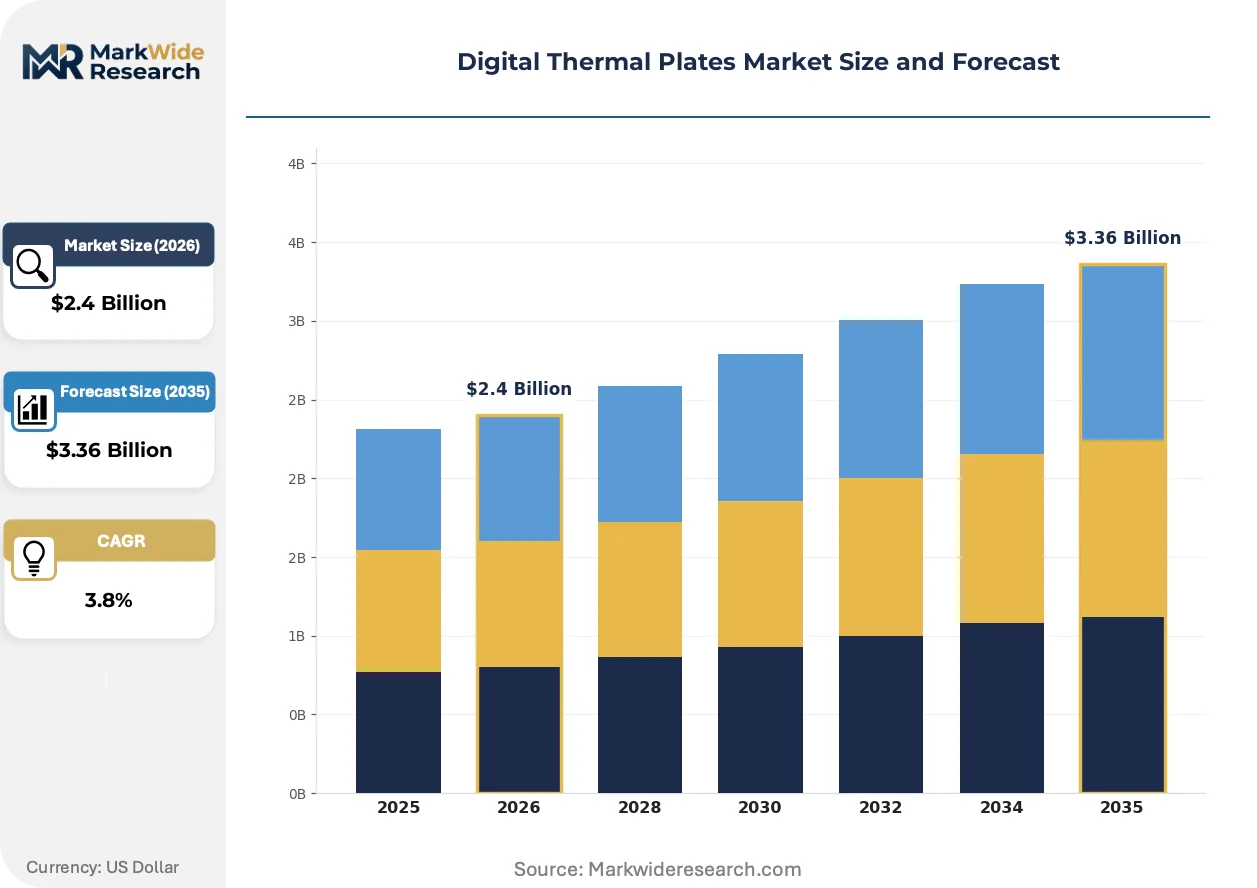
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Plates, High-Quality Plates, UV Plates, Thermal Plates End User: Commercial Printers, In-Plant Printers, Packaging Providers, Label Manufacturers Technology: Digital Printing, Offset Printing, Flexographic Printing, Gravure Printing Application: Packaging, Commercial Printing, Label Printing, Specialty Printing |
| Companies Covered | Agfa-Gevaert NV, Eastman Kodak Company, FUJIFILM Holdings Corporation, Heidelberger Druckmaschinen AG, Screen Holdings Co., Ltd., CRON-ECRM LLC, Mitsubishi Chemical Corporation, Toray Industries, Inc., Amsky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Thermal Plates Market Trends and Innovations
Thermal plate technology is converging with environmental compliance mandates and press automation systems, reshaping how converters specify, procure, and deploy lithographic surfaces across packaging and commercial print operations.
Grained anodized aluminum substrates with multi-layer thermal coatings are absorbing run-length compression in the 50,000-200,000 impression band that previously required conventional processed plates. Folding carton converters serving cosmetic and pharmaceutical brands are adopting these surfaces to eliminate developer chemistry handling while maintaining halftone fidelity below 20-micron dot gain. The technology is absorbing margin pressure from inkjet alternatives by reducing make-ready waste and enabling just-in-time plate production without darkroom infrastructure.
EPA National Emission Standards for Hazardous Air Pollutants (NESHAP) for printing and publishing operations are forcing commercial printers to abandon ammoniated fountain solutions and solvent-based plate developers by mandated compliance deadlines. Offset shops in California, Texas, and Ohio are retrofitting CTP lines with thermal imaging to eliminate classified hazardous waste streams and reduce air permitting burdens. The regulatory pressure is concentrating investment among mid-volume printers in states with stringent State Implementation Plan requirements.
Converter procurement of thermal plates is consolidating through managed print service contracts that bundle plate supply with equipment maintenance and color management software. Packaging providers serving multinational brand owners are displacing spot-buying arrangements with annual volume commitments that guarantee ISO-compliant plate calibration and dedicated technical support. This behavioral shift is most visible among corrugated and flexible packaging converters in the United States and Germany where brand owner audits mandate standardized prepress workflows across multiple production sites.
Digital Thermal Plates Market Segmentation
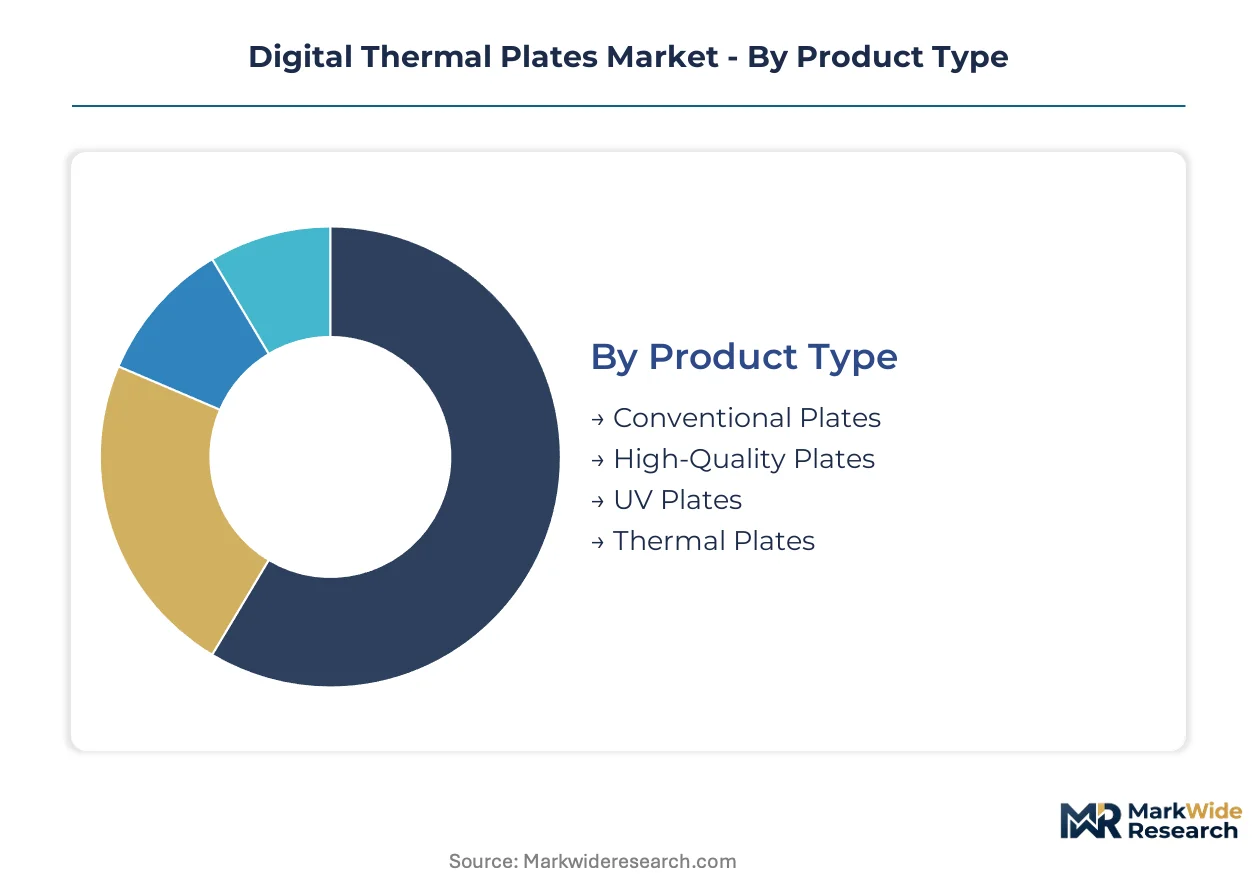
Digital thermal plates serve distinct workflow architectures across the printing value chain. Segment boundaries reflect divergent capital intensity, environmental compliance thresholds, and run-length economics that reshape procurement patterns among converters and commercial print operations.
Product Type:
Thermal plates integrate at varying depths within prepress ecosystems, from standalone chemistry-dependent systems to fully embedded processless workflows that eliminate separate CTP equipment entirely.
- Thermal Plates:Aluminum substrates coated with photopolymer layers image directly via 830nm or 1064nm laser exposure without wet chemical processing. Demand concentrates among folding carton converters in Germany and the United States where REACH and EPA NESHAP compliance eliminates solvent-based developer handling. Chemistry-free variants capture margin pools from environmental audit requirements.
- UV Plates:Specialized coatings tolerate high-intensity ultraviolet curing inks common in premium cosmetic and beverage packaging. Japanese and Italian converters serving luxury brand owners specify these surfaces for halftone fidelity below 20-micron dot gain in seven-color extended gamut workflows.
- High-Quality Plates:Multi-layer thermal coatings on grained anodized aluminum support stochastic screening for pharmaceutical insert and security printing applications.
- Conventional Plates:Wet-processed chemistry-dependent surfaces retain residual demand among legacy press fleets with amortized CTP infrastructure.
Volume placements concentrate in Thermal Plates; the faster expansion belongs to UV Plates.
End User:
Customer segments stratify by in-house technical capability and brand owner compliance exposure, from multinational packaging providers with dedicated prepress departments to commercial shops serving fragmented local demand.
- Packaging Providers:Corrugated and flexible packaging converters serving multinational FMCG and pharmaceutical brands drive thermal plate standardization across distributed production sites. These operators bundle plate procurement with ISO 12647 color management audits and managed print service contracts to satisfy brand owner quality mandates.
- Commercial Printers:Mid-volume offset shops in California, Texas, and Ohio retrofit CTP lines with thermal imaging to eliminate hazardous waste streams and reduce air permitting burdens under EPA NESHAP deadlines.
- Label Manufacturers:Folding carton and pressure-sensitive label converters absorb run-length compression from SKU fragmentation and faster revision cycles.
- In-Plant Printers:Corporate and institutional captive operations with constrained capex budgets retain mixed-vendor press fleets requiring proprietary RIP configurations.
Procurement scale peaks with Packaging Providers; In-Plant Printers face the steepest capability constraints.
Technology:
Print technology selection determines plate specification requirements, from high-volume offset run lengths exceeding 500,000 impressions to single-pass inkjet substitution eroding addressable plate volumes in short-run segments.
- Offset Printing:Thermal CTP systems dominate lithographic prepress with 2400 dpi registration and run-length tolerance above 500,000 impressions. Heidelberg, Komori, and KBA press fleets across Germany, Japan, and the United States anchor structural volume leadership despite digital fragmentation.
- Digital Printing:Electrophotographic and inkjet systems bypass plates entirely, compressing addressable thermal plate demand in the sub-10,000 impression segment where label manufacturers previously migrated to offset.
- Flexographic Printing:Photopolymer plate demand from corrugated converters competes with thermal offset for medium-run packaging work.
- Gravure Printing:Cylinder-based engraving retains niche dominance in ultra-long-run publication and decorative printing with minimal plate substitution opportunity.
Installed base concentration favors Offset Printing; Digital Printing segments expand most quickly among short-run packaging providers.
Application:
Application boundaries align with regulatory exposure and brand owner quality audit intensity, from food-contact compliance mandates in primary packaging to color-critical commercial work.
- Packaging:Folding carton and flexible packaging converters face FDA food-contact material regulations in the United States and evolving EU framework requirements for migration-safe thermal coatings. Seven-color fixed palette printing using stochastic screening displaces spot-color cylinder changes.
- Label Printing:Pharmaceutical and FMCG label manufacturers in Mumbai and Ahmedabad drive quality upgrades as BIS standards alignment and FSSAI packaging rules tighten.
- Commercial Printing:General marketing collateral and publication work faces margin pressure from digital media substitution.
- Specialty Printing:Security, currency, and decorative applications require proprietary plate formulations with restricted supply chains.
Compliance investment intensity peaks in Packaging; Label Printing climbs the fastest on pharmaceutical traceability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary aluminum smelting capacity for lithographic plate substrates concentrates in China and Russia, exposing manufacturers to raw material supply disruptions and tariff volatility that reshape procurement patterns across converting clusters worldwide.
United States
Commercial printers in California, Texas, and Ohio retrofit CTP lines with thermal imaging to eliminate hazardous waste streams under EPA National Emission Standards for Hazardous Air Pollutants deadlines. FDA food-contact material regulations reshape plate chemistry specifications as converters serving snack and beverage brands demand migration-safe thermal coatings. Folding carton converters in the Midwest absorb run-length compression through chemistry-free plate adoption.
Germany
REACH chemical restrictions from ECHA compel printers across Bavaria and North Rhine-Westphalia to abandon solvent-based plate developers for low-VOC thermal coatings. Heidelberg anchors European demand through integrated prepress workflows bundling plate supply with press service contracts. Stuttgart and Mannheim industrial clusters drive standardization across distributed packaging production sites.
Japan
Photopolymer coating expertise from chemical conglomerates sustains premium thermal plate supply across Asia-Pacific converting operations. METI industrial standards shape plate calibration requirements for pharmaceutical insert and security printing applications. Tokyo and Osaka metropolitan areas retain structural volume leadership in offset-to-digital transitions despite digital fragmentation.
India
Domestic pharmaceutical and FMCG label converters in Mumbai and Ahmedabad represent underpenetrated demand as BIS standards alignment and FSSAI packaging rules drive quality upgrades. CDSCO traceability requirements for pharmaceutical packaging accelerate thermal plate standardization among regulatory-compliant converters. Maharashtra and Gujarat industrial corridors absorb technology transfer from East Asian equipment suppliers.
China
Primary aluminum substrate production for lithographic plate bases supplies downstream coating operations across Pearl River Delta and Yangtze River Delta manufacturing clusters. MEE environmental enforcement pressures commercial printers toward chemistry-free thermal workflows that eliminate classified waste streams. Shenzhen and Shanghai converting hubs face margin compression from domestic inkjet press substitution in short-run packaging segments.
Digital Thermal Plates Market Competitive Landscape
Global majors compete with regional champions across chemical coating expertise and press-integrated workflow architectures. The vendor base stratifies between diversified chemical conglomerates with captive polymer research capabilities and specialized prepress equipment fabricators with proprietary imaging systems. Three archetypes dominate: integrated chemical-industrial conglomerates leveraging materials science R&D, precision equipment specialists bundling hardware with consumables, and regional coating specialists serving price-sensitive converting markets. Competitive intensity concentrates on backward integration into aluminum substrate supply and forward integration into color management software ecosystems.
Within the integrated chemical-industrial tier, FUJIFILM Holdings Corporation and Mitsubishi Chemical Corporation exemplify conglomerates with photopolymer coating expertise spanning multiple industrial applications. Agfa-Gevaert NV occupies a position among European-based specialists with integrated prepress workflow heritage. Heidelberger Druckmaschinen AG anchors the equipment-integrated archetype through bundled supply arrangements. These three represent distinct strategic postures: materials-led diversification, regional workflow integration, and hardware-consumables coupling.
| Leading Market Players |
|---|
| Agfa-Gevaert NV |
| Eastman Kodak Company |
| FUJIFILM Holdings Corporation |
| Heidelberger Druckmaschinen AG |
| Screen Holdings Co., Ltd. |
| CRON-ECRM LLC |
| Mitsubishi Chemical Corporation |
| Toray Industries, Inc. |
| Amsky |
| Others |
Pricing and Supply Chain Analysis
Packaging providers with multinational brand owner contracts dominate procurement volumes and impose contract-based long-term offtake structures that bundle plate supply with technical support. This buyer concentration forces thermal plate vendors to absorb cost volatility from aluminum substrate markets while competing on ISO 12647 calibration guarantees and managed service integration.
Pricing Analysis
Warranty and service bundling separates premium thermal plate tiers from unbundled commodity offerings in this market. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and volume scale, with chemistry-free variants commanding margins from REACH and EPA NESHAP compliance investments. Cost compression in the economy tier is intensifying because domestic inkjet press substitution erodes addressable volumes in short-run segments. Mid-tier commercial printers exhibit the highest price sensitivity, while multinational packaging providers prioritize calibration consistency over unit cost.
Supply Chain Analysis
Local-content rules in India and evolving domestic manufacturing incentives in China are reshaping sourcing patterns for aluminum substrate and photopolymer coating inputs. Primary aluminum smelting capacity concentrates in China and Russia, while photopolymer coating expertise centers on Japan and Germany. Raw material supply draws from bauxite mining operations, anodizing chemical processors, and thermal-sensitive polymer suppliers. Single-source vulnerability from concentrated aluminum substrate production exposes plate manufacturers to tariff volatility. Distribution runs through managed print service contracts that bundle consumables with equipment maintenance and color management software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as environmental compliance investments and laser imaging capital intensity force smaller coating specialists into acquisition targets. REACH-SVHC documentation burdens and prepress technician scarcity compound operational pressures that weaker players cannot absorb.
For Market Incumbents: Lock in backward integration into aluminum substrate supply to neutralize tariff exposure from China and Russia concentration. Deepen captive polymer research capabilities to sustain premium positioning as FUJIFILM and Mitsubishi Chemical defend coating expertise. Anchor multi-site packaging contracts with ISO 12647 calibration guarantees that offset-only specialists cannot replicate.
For New Entrants and Emerging Players: Domestic pharmaceutical label converters in Mumbai and Ahmedabad present the most penetrable demand cluster as BIS standards alignment and CDSCO traceability requirements accelerate quality upgrades. Target processless thermal convergence opportunities among newspaper printers seeking floor space reduction and CTP elimination. Enter through equipment-integrated partnerships with regional press distributors rather than standalone plate supply.
For Investors and Strategic Acquirers: The window for entry favors mid-cap coating specialists with captive aluminum sourcing and established brand owner audit relationships. Long-term viability hinges on chemistry-free thermal technology portfolios that align with tightening EPA and ECHA mandates. Watch for inflection when domestic inkjet press substitution rates in short-run packaging compress thermal plate addressable volumes beyond offset recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Substrate | Captive supply of grained anodized bases neutralizes China-Russia tariff exposure for plate manufacturers. |
| Chemistry-Free Thermal Coating R&D | Elimination of developer chemistry handling aligns with REACH and EPA NESHAP compliance deadlines. |
| Managed Print Service Expansion | Annual volume commitments with ISO 12647 guarantees displace spot-buying among multinational packaging providers. |
| Processless Thermal Convergence | On-press imaging integration eliminates separate CTP equipment for newspaper and commercial floor space reduction. |
| India Packaging Market Entry | BIS standards alignment and FSSAI rules create quality upgrade demand among Mumbai and Ahmedabad converters. |
Research Methodology
Trade association filings, customs export records, and SEC 10-K disclosures formed the secondary backbone for thermal plate production and trade flow analysis. Primary interviews with prepress operations directors, packaging procurement managers, plate coating R&D heads, and CTP equipment service engineers validated secondary findings across Germany, Japan, the United States, and India. Bottom-up and top-down triangulation reconciled unit shipment estimates with value aggregation across chemistry-free, low-chemistry, and conventional thermal plate categories.
Bottom-up modeling of installed CTP base by laser wavelength and press manufacturer anchored volume projections across the analysis window. Segmentation dimensions included product type, end user vertical, print technology, and application with regional regulatory cluster overlays. CAGRs derived from linear trend extrapolation of historical conversion rates from wet-processed to thermal imaging workflows. Forecast inputs incorporated REACH-SVHC substance restriction timelines and FDA food-contact material rule evolution.
Revisions become necessary when aluminum substrate tariff regimes shift, domestic inkjet press substitution accelerates beyond offset recovery thresholds, or ECHA expands SVHC candidate list to thermal coating chemistries. Forecasts reflect assumptions about regulatory enforcement continuity and brand owner audit standardization momentum. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Workbench Tanks Market
Others
Sound Reinforcement Market
Others
Agitator Bead Mill Market
Others
Global Virtual Keyboard Market
Others
Security Envelopes Market
Others
8K Technology Market
Others
Wearable Solar Devices Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Binoculars and Mounting Solutions Market
Others
Industrial PC Market
Others
Smart Home Service Market
Others
Bitcoin Mining Servers Market
Others
Digital Tattoos Market
Others
Cloud Advertising Market
Others
High Voltage Measuring Equipment Market
Others
Africa Smart Card Market