
 UK 3D Printing Construction Market | 2026-2036
UK 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
UK 3D Printing Construction Market Insights
Structural-grade concrete extrusion is rotating toward load-bearing wall applications in mid-rise housing. COBOD International leverages its gantry-based systems to anchor Nordic and UK project pipelines. Renishaw plc sustains metal powder bed specialization for architectural hardware and connection fixtures. Sika AG dominates advanced admixture supply chains that control printability windows and layer-bond strength.
UK 3D printing construction deploys layer-by-layer additive fabrication using cementitious, metallic, or polymeric feedstocks to produce structural and non-structural building elements with geometric complexity exceeding conventional formwork capabilities. Concrete extrusion leads application scale due to direct compatibility with existing building codes and trade workflows, while wire arc additive manufacturing occupies premium niche demand for bespoke steel nodes and facade brackets. Residential buildings and modular housing segments attract disproportionate capital allocation as construction firms and real estate developers seek program compression and labor substitution.
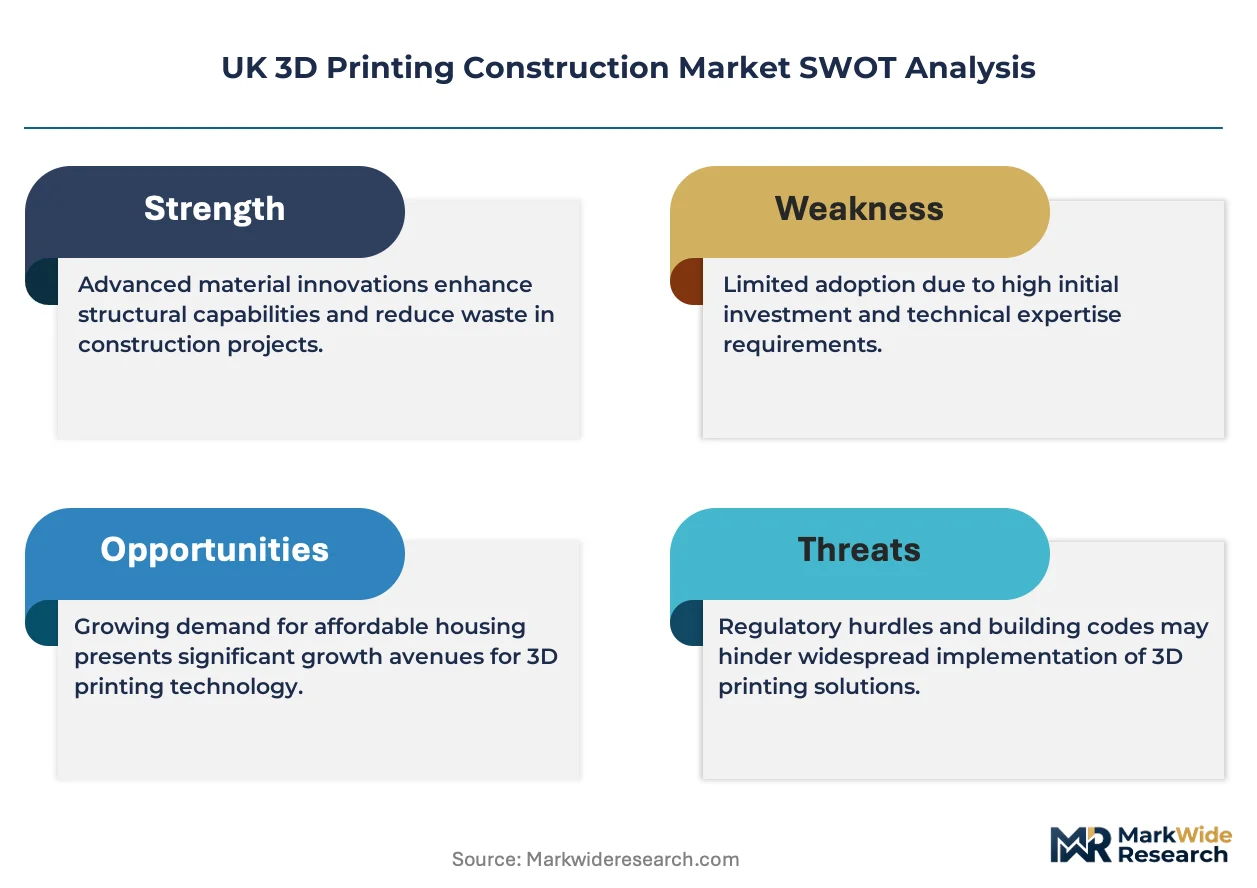
Building Regulations Part L, British Standards Institution certification protocols for printed concrete, and Health and Safety Executive construction safety mandates collectively shape material qualification paths and site deployment protocols. The Health and Safety Executive imposes stringent risk assessments for automated gantry operations on active construction sites, slowing rollout pace but elevating vendor compliance barriers. Stakeholders must monitor local planning authority appetite for printed building approvals as the decisive variable separating pilot projects from repeatable revenue streams.
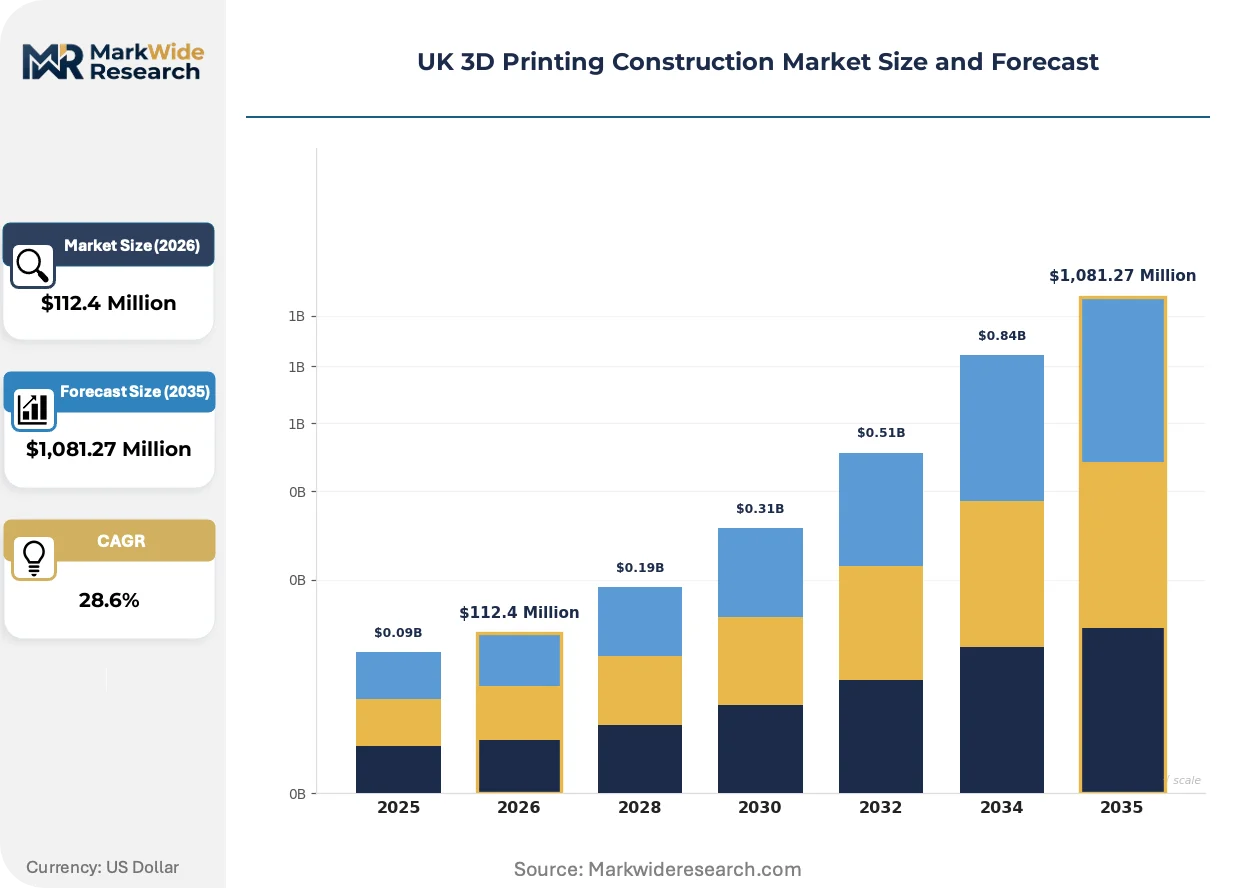
Market Dynamics
Building Regulations Part L thermal mandates are compressing construction timelines and forcing housing associations toward prefabricated structural elements that bypass traditional wet trades. This regulatory pressure is concentrating demand around gantry-based concrete extrusion systems capable of delivering thermally optimized wall assemblies at pace.
Growth Catalysts
- Part L Compliance Pressure:Tightened thermal performance mandates under UK Building Regulations Part L are accelerating specification of printed structural elements with integrated insulation cavities. Housing associations in Greater London are scaling procurement of load-bearing printed walls to meet fabric efficiency targets.
- Mid-Rise Housing Density Targets:Planning authorities in Birmingham and Manchester are piloting streamlined approvals for additive manufacturing in residential schemes. These local frameworks reduce pre-construction risk for developers pursuing five-to-eight storey printed housing.
- Gantry Automation:Automated concrete extrusion is displacing traditional masonry crews on constrained urban sites. The technology compresses structural enclosure programs from weeks to days where labor availability constrains conventional delivery.
Market Restraints
- Admixture Supply Concentration:Advanced rheology modifiers controlling printability windows and layer-bond strength concentrate among specialty chemical suppliers. Disruption to European supply chains for polycarboxylate ether superplasticizers would stall multiple UK project pipelines simultaneously.
- Health and Safety Executive Friction:HSE construction safety mandates impose stringent risk assessments for automated gantry operations on active sites. These protocols slow deployment velocity and elevate vendor compliance barriers beyond mid-tier contractor capabilities.
- Steel Connection Substitution:Wire arc additive manufacturing for bespoke structural nodes competes with conventional CNC-milled steel and imported castings. Cost parity remains elusive for standard connection geometries where conventional fabrication achieves scale economies.
Strategic Opportunities
- Scottish Housing Expansion:Scotland's social housing procurement frameworks remain underpenetrated by printed construction methods. The Scottish Government's affordable housing supply program presents a white space for gantry-based systems targeting remote and island communities with constrained conventional supply chains.
- Retrofit Integration:Printed facade panels with integrated thermal breaks offer a convergence pathway between additive manufacturing and deep energy retrofit mandates. Housing associations pursuing net-zero pathways represent a captive demand pool for external wall system replacement.
- Planning Pre-Approval Pathways:Local planning authorities in Greater London are developing standardized design codes for printed residential elements. Early alignment with these emerging frameworks secures preferred vendor status for repeat scheme delivery.
Industry Challenges
- BSI Certification Timelines:British Standards Institution protocols for printed concrete structural qualification remain under development. Extended testing programs for novel mix designs compress project feasibility windows and strain contractor cash flow.
- Site Integration Complexity:Printed structural elements must interface with conventional MEP rough-in and finishing trades. Coordination failures between gantry deployment schedules and follow-on contractor mobilization generate programme slippage on pilot projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK 3D Printing Construction Market |
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $1,081.27 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Concrete Extrusion, Powder Bed, Wire Arc Additive Manufacturing, Directed Energy Deposition, Binder Jetting Application: Residential Buildings, Commercial Complexes, Infrastructure Projects, Modular Housing, Public Facilities End User: Construction Firms, Real Estate Developers, Architectural Agencies, Government Bodies, Engineering Consultancies Material Type: Concrete, Metal Alloys, Thermoplastics, Geopolymers, Composite Materials |
| Companies Covered | Icon Technology Studio, Sika AG, Renishaw plc, XtreeE, MX3D, COBOD International, Contour Crafting Corporation, PERI Group, Apis Cor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK 3D Printing Construction Market Trends and Innovations
Concrete extrusion technology is rotating from demonstration projects toward repeatable delivery models as procurement frameworks mature. Three forces are compressing the gap between pilot validation and scaled deployment across UK residential construction.
Multi-axis robotic arms paired with real-time rheology monitoring are displacing fixed-gantry systems on complex geometric briefs. Architectural practices specifying double-curved facade elements are adopting these flexible deposition platforms. The shift is compressing the tradable scope between structural engineers and specialist subcontractors.
Building Regulations Part L 2021 conservation of fuel and power standards are mandating fabric-first efficiency upgrades that printed wall assemblies address directly. The regulation is forcing housing associations to abandon traditional cavity wall construction for thermally optimized alternatives. Developers in Greater London are responding by embedding printed suppliers into early design team appointments.
Client organizations are consolidating structural element procurement under design-build contracts that transfer performance risk to printed system vendors. Housing associations previously procuring shells separately from MEP and fit-out are bundling these scopes. This concentration is most visible in Birmingham where combined authorities aggregate social housing pipelines to attract integrated delivery partners.
UK 3D Printing Construction Market Segmentation
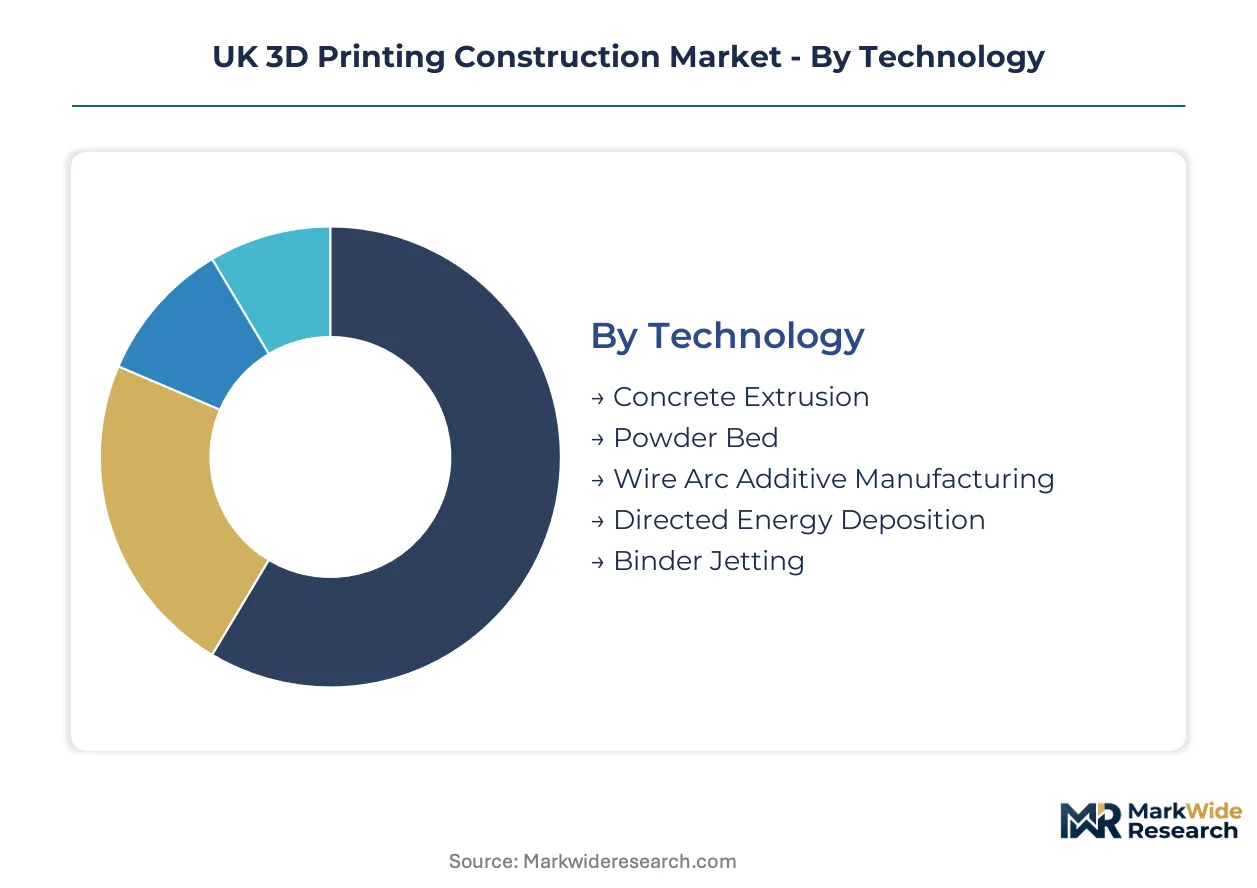
Segmentation in UK 3D printing construction reveals how technology maturity, regulatory pressure, and procurement consolidation concentrate value capture. Distinct capability requirements across deposition methods and end-user sophistication create tiered competitive arenas with divergent margin profiles.
Technology:
Substitution pressure from conventional construction methods varies sharply across deposition platforms, with gantry-based systems facing masonry competition while powder bed processes defend niche premium positioning.
- Concrete Extrusion:Layer-by-layer deposition of cementitious mixes through gantry or robotic arm systems. Housing associations in Greater London specify extruded load-bearing walls to meet Part L thermal mandates, displacing traditional cavity construction where program compression commands premium pricing.
- Powder Bed:Selective laser sintering and melting of metal or polymer powders for high-precision architectural hardware. Birmingham planning pilots for printed residential schemes are absorbing powder bed output for bespoke connection fixtures where geometric complexity exceeds CNC capabilities.
- Wire Arc Additive Manufacturing:Electric arc deposition of steel wire for structural nodes and facade brackets. Manchester mid-rise developments source WAAM components where conventional steel fabrication faces labor constraints.
- Directed Energy Deposition:Laser or electron beam-fed metal deposition for repair and reinforcement applications. Infrastructure contractors deploy DED for structural strengthening of heritage steelwork.
- Binder Jetting:Liquid binding agent deposition onto powder beds for sand molds and ceramic tooling. Specialist precast suppliers utilize binder jetting for complex formwork geometries.
Concrete Extrusion retains volume leadership; Powder Bed holds the steepest expansion curve in architectural hardware specification.
Application:
Cost tier stratification separates volume-driven residential deployment from premium commercial and infrastructure segments with divergent procurement cycles and performance risk allocation.
- Residential Buildings:Mid-rise housing schemes in Greater London, Birmingham, and Manchester represent the primary absorption channel for printed structural elements. Five-to-eight storey printed housing compresses traditional masonry programs from weeks to days where labor availability constrains conventional delivery.
- Commercial Complexes:Office and retail developments specify printed facade panels and structural nodes for geometric differentiation. Birmingham combined authorities aggregate social housing pipelines adjacent to commercial cores, creating mixed-use procurement bundles.
- Infrastructure Projects:Bridges, tunnels, and utility structures deploy printed elements for remote site access and accelerated enclosure. Scottish island communities present white-space demand where conventional supply chains face logistical barriers.
- Modular Housing:Factory-produced volumetric units incorporating printed structural components. Offsite manufacturing consolidates quality control and thermal performance verification before site delivery.
- Public Facilities:Schools, healthcare buildings, and civic structures with extended design lives and stringent durability requirements. Government procurement frameworks are piloting printed element pre-qualification for repeat scheme delivery.
Residential Buildings command the deepest procurement volume; Modular Housing is gaining share fastest through offsite manufacturing consolidation.
End User:
Customer type maturity determines specification authority, with design-build contractors capturing integrated risk while architectural agencies influence early-stage technology embedding.
- Construction Firms:Tier-one contractors deploying gantry systems on constrained urban sites. HSE risk assessment protocols for automated operations elevate compliance barriers beyond mid-tier contractor capabilities.
- Real Estate Developers:Private and institutional developers pursuing program compression and labor substitution. Greater London developers embed printed suppliers into early design team appointments to secure planning pre-approval pathways.
- Architectural Agencies:Practices specifying double-curved facade elements and complex geometries. Multi-axis robotic arm adoption traces directly to architectural briefs exceeding conventional formwork capabilities.
- Government Bodies:Housing associations and local authorities aggregating demand through framework agreements. Scotland's affordable housing supply program remains underpenetrated by printed construction methods.
- Engineering Consultancies:Structural and MEP engineers coordinating printed element interfaces with conventional trades. BSI certification timelines for printed concrete compress project feasibility windows and strain contractor cash flow.
Construction Firms retain execution control; Government Bodies are expanding procurement fastest through framework consolidation.
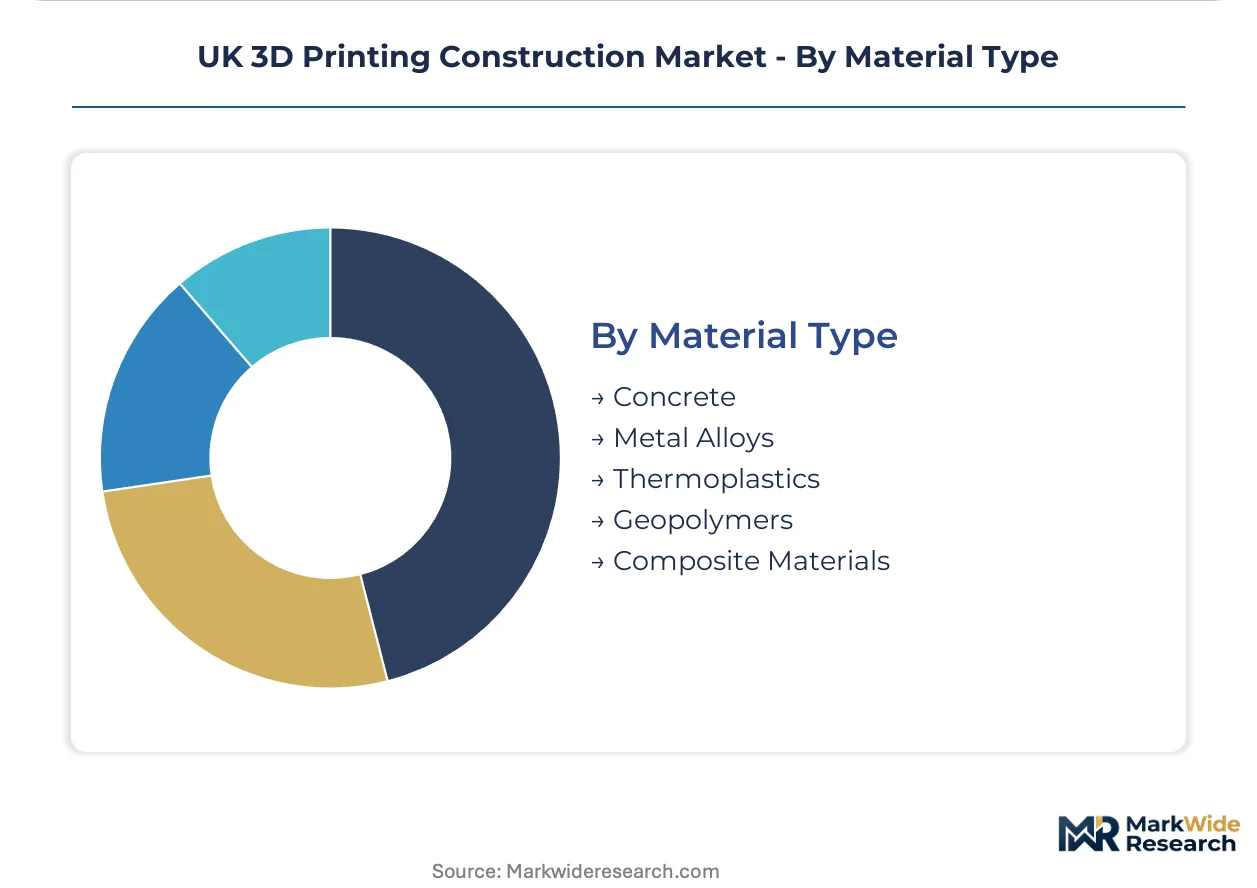
Material Type:
Supply concentration in advanced admixtures and metal powders shapes margin distribution across material categories, with geopolymers and composites contesting established concrete and metal positions.
- Concrete:Portland cement-based mixes with rheology modifiers controlling printability windows. Sika AG dominates specialty chemical supply chains that govern layer-bond strength and setting kinetics.
- Metal Alloys:Steel, aluminum, and titanium feedstocks for structural nodes and architectural hardware. Wire arc systems consume construction-grade steel wire where cost parity with conventional fabrication remains elusive for standard geometries.
- Thermoplastics:ABS, PLA, and PETG polymers for non-structural architectural elements and formwork. Limited structural application due to building code fire performance restrictions.
- Geopolymers:Alkali-activated binders with reduced carbon intensity versus Portland cement. Emerging specification in public sector procurement with net-zero pathway mandates.
- Composite Materials:Fiber-reinforced polymers and hybrid cementitious systems. Printed facade panels with integrated thermal breaks converge additive manufacturing with deep energy retrofit demand.
Concrete dominates structural volume; Geopolymers are climbing the fastest on carbon reduction procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK 3D printing construction market operates as a net importer of specialized gantry hardware and admixture chemicals, with domestic project pipelines absorbing equipment from Nordic and Continental European suppliers. Export potential concentrates in architectural design services and printed component specifications rather than capital equipment.
Greater London
Housing associations in Tower Hamlets and Southwark are scaling procurement of printed load-bearing walls to meet Part L thermal mandates. The Greater London Authority's streamlined planning pathways for additive manufacturing reduce pre-construction risk for developers. Canary Wharf contractors deploy gantry systems on constrained sites where labor availability constrains conventional masonry delivery.
West Midlands
Birmingham combined authorities aggregate social housing pipelines to attract integrated delivery partners bundling printed structural elements with MEP scopes. The West Midlands Combined Authority's pilot frameworks for printed residential approvals compress planning timelines. Coventry manufacturing clusters supply robotic arm components for multi-axis deposition platforms.
Greater Manchester
Mid-rise housing schemes in Salford and Trafford source wire arc additive manufacturing components where conventional steel fabrication faces skilled labor constraints. Manchester City Council's planning pre-approval pathways for five-to-eight storey printed housing reduce developer risk. Local contractors embed printed suppliers into early design team appointments.
Scotland
Remote island communities in the Highlands and Islands present white-space demand where conventional supply chains face logistical barriers. The Scottish Government's affordable housing supply program remains underpenetrated by printed construction methods. Aberdeen energy sector contractors repurpose offshore fabrication expertise toward printed structural node production.
UK 3D Printing Construction Market Competitive Landscape
Listed leaders compete with private specialists across equipment supply and chemical formulation, creating a tiered structure where public-market players anchor capital-intensive hardware segments while private firms dominate project execution. The vendor base separates into gantry system providers, specialty chemical suppliers, and integrated design-build operators. Three archetypes define competitive positioning: Nordic-origin equipment manufacturers, Swiss-German chemical formulators, and UK-based project delivery specialists. Dominant competitive moves include strategic partnerships between hardware vendors and housing associations, plus capacity expansion in admixture blending facilities serving multiple regional pipelines.
Among UK-listed fabricators, Renishaw plc occupies a position within the precision hardware tier, while Sika AG anchors the specialty chemical segment with European supply chain reach. COBOD International exemplifies the Nordic-origin gantry specialist archetype, representing equipment-led market entry strategies. These three entities sit within distinct competitive arenas—metallic component fabrication, rheology control chemistry, and large-format deposition systems—rather than direct confrontation.
| Leading Market Players |
|---|
| Icon Technology Studio |
| Sika AG |
| Renishaw plc |
| XtreeE |
| MX3D |
| COBOD International |
| Contour Crafting Corporation |
| PERI Group |
| Apis Cor |
| Others |
Pricing and Supply Chain Analysis
Gantry system utilization rates above 70% at Nordic manufacturing plants establish cost floors that UK project developers cannot undercut through domestic assembly. This capacity concentration in Denmark and Germany funnels hardware pricing power toward equipment vendors while compressing margins for British contractors bidding fixed-price design-build contracts.
Pricing Analysis
Housing associations anchor project-based pricing structures that bundle printed structural elements with thermal performance guarantees. Price differentiation separates Part L-certified wall assemblies from uncertified pilot installations, with certification tier commanding 15-20% premiums. Cost compression in standard cavity wall substitutes is intensifying because masonry crews are accepting reduced margins to retain market share. Tier-two regional contractors exhibit highest price sensitivity, while Greater London developers absorb premium pricing to secure planning pre-approval pathways.
Supply Chain Analysis
Extended lead times for polycarboxylate ether superplasticizers stretch 12-16 weeks from Swiss-German blending facilities to UK sites. Supply concentrates in Switzerland, Germany, and the Netherlands for advanced rheology modifiers, while steel wire feedstock for arc deposition draws from British and Spanish mills. Single-source vulnerability in specialty chemical formulation creates structural risk if European logistics chokepoints disrupt just-in-time admixture delivery. Distribution runs through tier-one construction distributors with direct vendor relationships, bypassing generalist builders merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of gantry operators certified under Health and Safety Executive automated construction protocols is constraining viable project execution capacity below demand growth trajectories. This credential gap separates repeat-scheme contractors from demonstration-project participants.
For Market Incumbents: Fortify admixture supply security through captive blending capacity or long-term offtake agreements with Sika AG and specialty chemical formulators. COBOD International's equipment leasing model threatens ownership-based revenue streams; incumbents should anchor recurring maintenance contracts and operator training programs to lock in housing association relationships. For New Entrants and Emerging Players: Differentiate on Scottish island community deployment where conventional supply chain logistics fail and gantry-based systems command sole-source positioning. The Scottish Government's affordable housing supply program remains the most penetrable geography for first-mover establishment. Target design-build partnerships with combined authorities aggregating social housing pipelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty chemical suppliers controlling printability window formulation, not equipment manufacturers exposed to cyclical capex postponement. Long-term viability favors firms with BSI certification pathway influence and housing association framework pre-qualification. The signal to watch is local planning authority adoption of standardized design codes for printed residential elements, which would trigger scalable deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Admixture Supply Agreement | Secures printability window control for housing association framework bids. |
| HSE Certification Investment | Unlocks automated gantry deployment on active construction sites. |
| Planning Pre-Approval Partnership | Aligns with Greater London Authority emerging design codes. |
| Scottish Housing Expansion | Captures white-space demand in island communities with logistics barriers. |
| Retrofit Facade Integration | Converges printed thermal breaks with net-zero pathway mandates. |
Research Methodology
A standing panel of gantry system operators, housing association procurement directors, Health and Safety Executive construction safety inspectors, and specialty chemical R&D leads provided ongoing calibration against project deployment realities. Primary interview findings triangulated with Building Regulations Part L compliance databases, British Standards Institution draft certification protocols, Greater London Authority planning approval records, and contractor financial disclosures. Bottom-up project pipeline aggregation cross-checked against top-down equipment import and admixture trade flow analysis.
Consistency checks validated volume and value outputs against external benchmarks including Nordic equipment manufacturer order backlogs and European specialty chemical shipment records. The analytical framework segmented across deposition technology, end-use application, customer type, and material chemistry throughout the projection horizon. CAGRs derived from fitted growth curves applied to validated base-year estimates, with inputs from thermal mandate compliance timelines and local planning authority pilot program expansion rates.
Material uncertainties — regulatory certification delays, supply chain disruption to European admixture sources, and planning authority appetite variability — sit outside the modeled envelope. Forecasts reflect assumptions about Building Regulations Part L enforcement continuity and gantry operator certification pipeline throughput. Revision becomes warranted when Health and Safety Executive protocol amendments or BSI standard finalization crosses thresholds that alter project feasibility windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Coloring Apps Market
Others
Mainframe Market
Others
Convertible Shipper Display Market
Others
Transportation Lighting Market
Others
Dried Fruit Extracts Market
Others
Binoculars and Mounting Solutions Market
Others
Enterprise Video Content Management Market
Others
Level Measuring Instrument Market
Others
US Legal Services Market
Others
Smart Home Water Softener Market
Others
Global Snow Sports Apparel Market
Others
ISO Cylinder Market
Others
Smart Home Gateways Market
Others
Banknote Printing Machine Market
Others
Automotive Smart Lighting Market
Others
Cloud Gaming Baas Market