
 Fresh Apples Market | 2026-2036
Fresh Apples Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Apples Market Analysis
Premium-grade and club-variety specifications is redrawing competitive boundaries across the fresh apples supply base. Stemilt Growers LLC leverages its integrated tree-to-retail control to sustain year-round Honeycrisp availability. Gebbers Farms anchors Pacific Northwest production volume through its expansive orchard footprint in Washington State. Auvil Fruit Co. Inc. differentiates via proprietary cultivation methods that enhance fruit firmness and color consistency.
Fresh apples constitute the raw, unprocessed fruit of Malus domestica species, harvested at physiological maturity with soluble solids content typically exceeding 10.5 degrees Brix and stored under controlled atmosphere conditions to suppress ethylene-induced ripening for commercial distribution to retail, foodservice, and processing channels. Conventional product type still occupies the largest volume share, though organic certification is capturing margin pools as retailers enforce stricter residue-limit protocols. Direct-to-consumer distribution channels are expanding fastest among digital-native growers, while wholesale channels dominate absolute tonnage movement through terminal markets.
USDA grading standards and FDA Food Safety Modernization Act requirements govern domestic market access, with EPA pesticide tolerance limits further constraining chemical management practices across orchards. EU REACH chemical regulations and EFSA maximum residue levels shape export eligibility for North American suppliers shipping to European retail chains. Stakeholders must monitor evolving phytosanitary barriers and climate-adapted variety development timelines to secure long-term procurement contracts.
Market Dynamics
Controlled atmosphere storage technology and USDA organic certification requirements are compressing margins for conventional growers while rewarding integrated operators who command year-round supply continuity.
Growth Catalysts
- Foodservice procurement expansion:Institutional buyers in K-12 and corporate dining are mandating premium-grade fruit specifications for prepared meal programs, pulling volume toward certified suppliers.
- EU REACH compliance:North American exporters investing in residue-limit documentation are capturing shelf space in European retail chains that enforce EFSA maximum residue levels.
- 1-MCP application:Post-harvest treatment with 1-methylcyclopropene is extending marketing windows for Honeycrisp and club varieties, enabling ocean freight to Asian markets.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings compress orchard operating margins, particularly for smaller growers lacking forward-contract hedging.
- Washington State supply concentration:Overreliance on Pacific Northwest production exposes buyers to climate-driven crop variability and labor availability shocks.
- Regulatory friction:EPA pesticide tolerance limit revisions force rapid chemistry transitions, straining integrated pest management program stability.
Strategic Opportunities
- China import demand:Rising domestic consumption of imported apple varieties in tier-one cities creates premium positioning for North American club varieties.
- Direct-to-consumer channels:Digital-native growers bypassing terminal markets capture margin through subscription box and farm-gate delivery models.
- Organic certification tailwind:USDA National Organic Program standards alignment opens access to retailer private-label programs with stricter residue protocols.
Industry Challenges
- H-2A visa program complexity:Orchard labor recruitment faces procedural delays and housing compliance costs, constraining harvest timing precision.
- Cold-chain capex intensity:Controlled atmosphere storage installation and CA container fleet expansion demand capital commitments that strain mid-scale operator balance sheets.
- Phytosanitary compliance timelines:Export protocol negotiations with multiple national plant protection organizations extend market access lead times unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Apples Market |
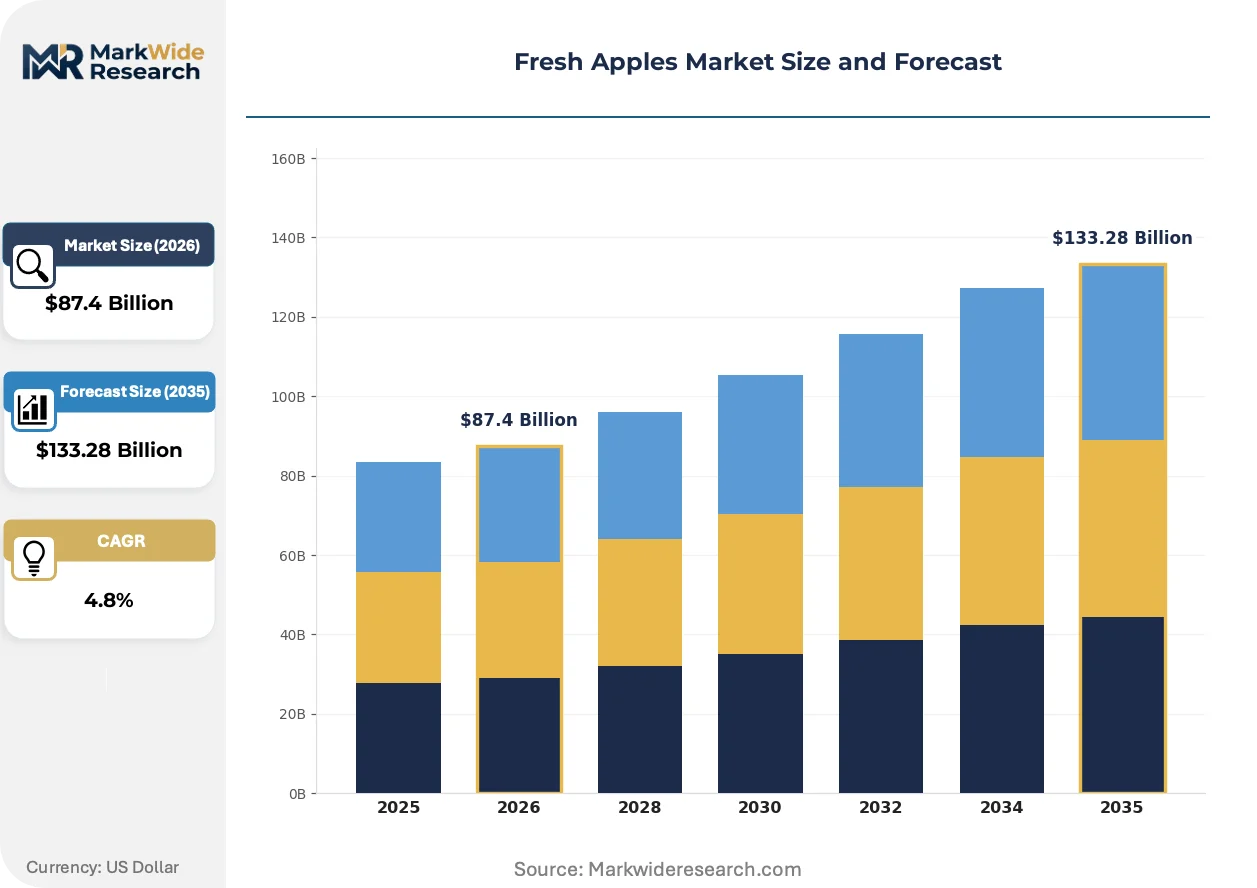
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Heirloom, Hybrid Distribution Channel: Retail, Wholesale, Direct-to-Consumer, E-commerce Variety: Granny Smith, Fuji, Gala, Honeycrisp Packaging Type: Bags, Boxes, Bulk, Clamshell |
| Companies Covered | Stemilt Growers LLC, Gebbers Farms, Auvil Fruit Co. Inc., Washington Fruit & Produce Co., Evans Fruit Co., Allan Bros. Inc., Salix Fruits, Symms Fruit Ranch Inc., FirstFruits Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Apples Market Emerging Trajectories
Biological crop protection chemistry and precision orchard management systems are displacing conventional input-intensive production models, while procurement digitization compresses traditional wholesale channel dominance.
Robotic harvesting platforms utilizing computer vision and gentle gripper technology are bifurcating labor availability constraints in Pacific Northwest orchards. Large-scale operators with capital access are piloting mechanical harvesters for processing-grade fruit, while fresh-market varieties remain hand-picked due to cosmetic damage sensitivity. This technology divide is concentrating volume among capitalized growers who can amortize equipment across thousand-plus acre footprints.
EU F-Gas Regulation phase-down mandates are accelerating cold-chain refrigeration retrofits across European import terminals and distribution centers. Operators face compliance deadlines for hydrofluorocarbon reduction, driving adoption of transcritical CO2 systems and ammonia-based alternatives. North American exporters shipping to Rotterdam and Hamburg must certify container fleet compatibility with receiving infrastructure standards.
Buyer concentration among top-ten US grocery retailers is compressing supplier negotiation leverage and mandating traceability documentation. Stemilt Growers and Gebbers Farms are deploying block-chain enabled lot tracking to satisfy Walmart and Kroger recall-precision requirements. This transparency investment is most visible in Washington State, where integrated packer-shippers control tree-to-retail data flows.
Fresh Apples Market Segmentation
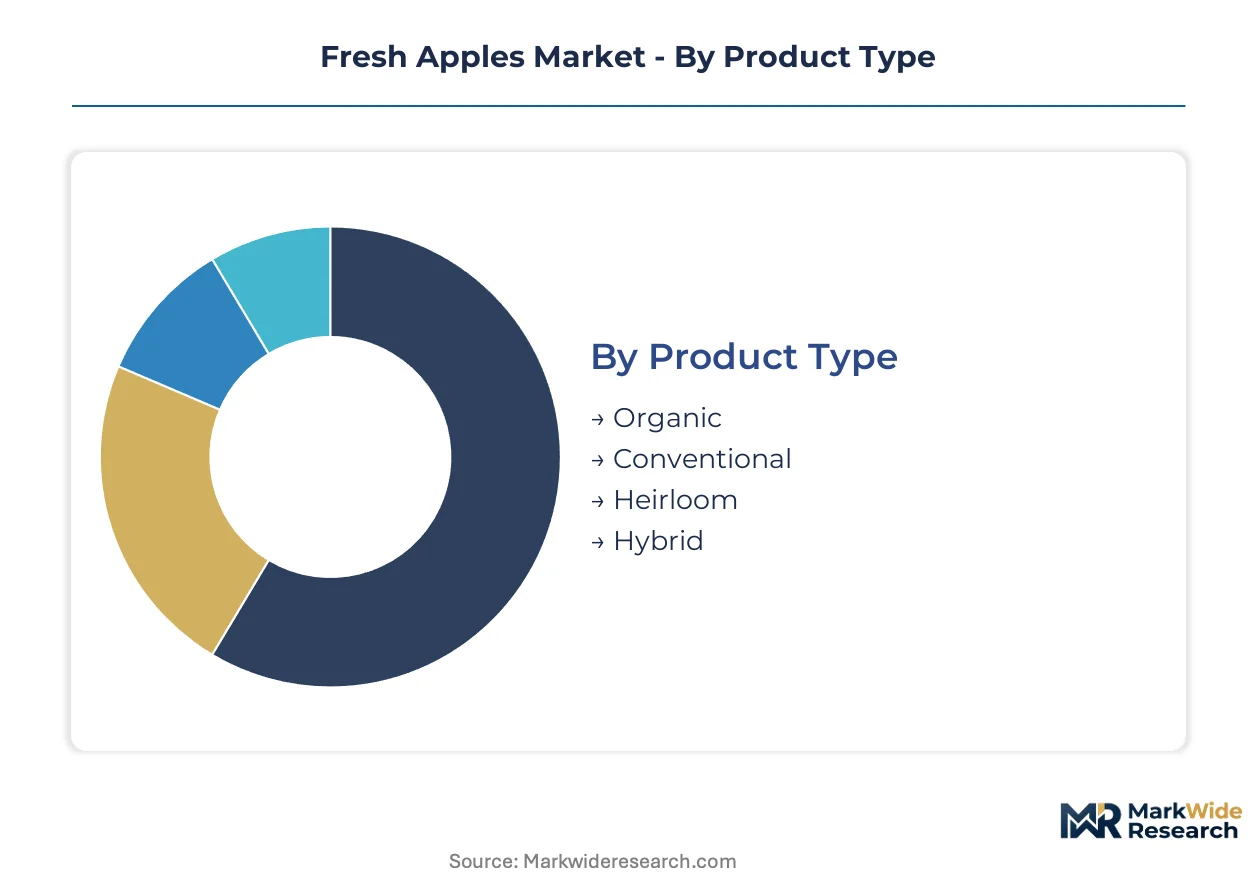
Fresh apples segmentation reveals divergent margin structures across certification tiers and channel strategies. Procurement specifications from institutional buyers and retail chains are fragmenting volume into distinct quality grades with incompatible supply chain requirements.
Product Type:
Domestic consumption concentrates in conventional grades, while export eligibility increasingly depends on organic certification alignment with EU and Asian import protocols.
- Organic:USDA National Organic Program certification mandates buffer zones and approved input lists that constrain orchard management flexibility. European retail chains in Germany and France enforce EFSA residue limits that favor organic procurement, pulling North American export volume toward certified suppliers.
- Conventional:EPA pesticide tolerance limits govern chemical management across Washington State and New York production zones. K-12 foodservice programs in the US still default to conventional grades for cost-controlled meal budgets, sustaining volume despite margin compression.
- Heirloom:Heritage varieties like Cox's Orange Pippin command farm-gate premiums through direct-to-consumer channels.
- Hybrid:Club varieties developed through controlled breeding programs restrict propagation licensing to contracted growers.
Conventional holds the largest share; momentum sits with organic certification.
Distribution Channel:
Cost tier separation runs deepest here, with capital-intensive cold-chain infrastructure determining which channels remain accessible to mid-scale operators.
- Retail:Terminal market aggregation supplies grocery chains with consistent volume and USDA grade-standard documentation. Walmart and Kroger mandate blockchain traceability that favors integrated packer-shippers with tree-to-retail data systems.
- Wholesale:Foodservice distributors like Sysco and US Foods pull volume toward Honeycrisp and club varieties for prepared meal programs. Institutional procurement specifications are tightening residue documentation requirements.
- Direct-to-Consumer:Subscription box models capture margin through farm-gate delivery bypassing terminal fees.
- E-commerce:Amazon Fresh and specialty platforms expand refrigerated last-mile capacity for premium grades.
Wholesale moves the most tonnage; e-commerce climbs the fastest.
Variety:
Application-specific demand patterns split volume between processing-grade tolerance and fresh-market cosmetic standards.
- Honeycrisp:1-MCP post-harvest treatment extends marketing windows for this firm-fleshed, high-sugar variety. China import demand for premium club varieties positions Honeycrisp for ocean freight expansion to Shanghai and Beijing tier-one markets.
- Gala:Year-round availability through Southern Hemisphere counter-seasonal supply sustains retail shelf presence. South African and Chilean exports compete directly with US Pacific Northwest production during domestic off-seasons.
- Granny Smith:Tart acidity profile serves processing channels for pie filling and sauce manufacturing.
- Fuji:Dense texture and extended storage compatibility favor controlled atmosphere inventory programs.
Gala maintains the broadest geographic footprint; Honeycrisp shows the steepest expansion trajectory.
Packaging Type:
Customer type differentiation separates retail-ready presentation from foodservice bulk efficiency.
- Bulk:Bin-based movement through terminal markets minimizes per-unit handling for processing-grade fruit. Juice and sauce manufacturers in Michigan and Washington State prefer bulk receiving for efficiency.
- Bags:Polyethylene retail bags dominate club store formats with multi-pound counts. Costco and Sam's Club specifications drive high-volume bagged program consolidation.
- Boxes:Corrugated wholesale cases satisfy foodservice distributor handling requirements.
- Clamshell:PET rigid containers protect cosmetic-grade varieties for premium retail placement.
Bulk captures the highest absolute volume; clamshell gains share fastest in premium retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean exporters ship counter-seasonal Gala and Granny Smith varieties to North American retailers during US domestic off-seasons, sustaining year-round retail shelf presence through Southern Hemisphere supply windows.
United States
Walmart and Kroger procurement teams enforce blockchain traceability mandates that favor integrated Washington State packer-shippers. The USDA National Organic Program certification requirements constrain orchard management flexibility for export-bound growers. Yakima Valley and Wenatchee Valley clusters concentrate controlled atmosphere storage infrastructure serving Pacific Northwest export terminals.
China
Tier-one city consumers in Shanghai and Beijing drive import demand for premium Honeycrisp and club varieties from North American suppliers. The General Administration of Customs China enforces phytosanitary protocols that extend market access lead times unpredictably. Shandong Province domestic production competes with imports on price while coastal import terminals expand refrigerated capacity.
Germany
Retail chains in Berlin and Munich enforce EFSA maximum residue levels that pull procurement toward certified organic suppliers. The EU F-Gas Regulation phase-down mandates cold-chain refrigeration retrofits across import terminals at Rotterdam and Hamburg. Hamburg distribution centers certify container fleet compatibility with transcritical CO2 systems for North American exporters.
France
Paris-based retail consortiums mandate stricter residue-limit protocols that favor organic certification alignment. EFSA chemical regulations shape import eligibility for suppliers shipping through Calais and Le Havre. Normandy and Brittany processing clusters source conventional grades for juice and sauce manufacturing channels.
India
Mumbai and Delhi institutional foodservice buyers expand procurement of premium-grade fruit for hotel and corporate dining programs. The FSSAI food safety standards govern import clearance timelines for Washington State suppliers. Maharashtra and Karnataka cold-chain infrastructure investments expand last-mile refrigerated capacity for retail distribution.
Fresh Apples Market Vendor Landscape
Listed leaders compete with private specialists across integrated tree-to-retail control versus orchard-scale specialization. The vendor base fragments across mid-scale operators lacking capital for controlled atmosphere storage installation and capitalized growers amortizing equipment across thousand-plus acre footprints. Three archetypes dominate: integrated packer-shippers with blockchain traceability systems, orchard-scale volume producers, and digital-native direct-to-consumer specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as operators secure year-round supply continuity.
Within the integrated packer-shipper tier, Stemilt Growers LLC and Gebbers Farms exemplify operators commanding tree-to-retail data flows. Auvil Fruit Co. Inc. occupies a position among specialty cultivators emphasizing proprietary cultivation methods. These three anchors represent distinct strategic postures across certification tiers and channel strategies in the fresh apples supply base.
| Leading Market Players |
|---|
| Stemilt Growers LLC |
| Gebbers Farms |
| Auvil Fruit Co. Inc. |
| Washington Fruit & Produce Co. |
| Evans Fruit Co. |
| Allan Bros. Inc. |
| Salix Fruits |
| Symms Fruit Ranch Inc. |
| FirstFruits Farms |
| Others |
Supply Flow & Price Mechanics
Controlled atmosphere inventory programs stretching 8-12 months from harvest to retail sale concentrate pricing power among Washington State packer-shippers with integrated storage infrastructure. This lead-time band compresses margins for operators lacking year-round supply continuity while rewarding capitalized growers who command premium positioning through Honeycrisp and club variety availability.
Pricing Analysis
Foodservice distributors anchor contract-based long-term offtake structures that stratify across organic certification, conventional grade, and club variety tiers. Price differentiation rests on USDA grade standards and residue documentation alignment with EFSA maximum residue levels for European export eligibility. Pricing pressure intensifies in conventional grades as input cost volatility in fertilizer and fuel squeezes orchard operating margins. K-12 institutional buyers exhibit highest price sensitivity, while European retail chains demonstrate lowest sensitivity for certified organic supply.
Supply Chain Analysis
Harvest-to-retail lead times exceeding 300 days for controlled atmosphere-stored varieties tether supply chain performance to capital-intensive storage infrastructure. Production concentrates in Washington State, Chile, and China, with counter-seasonal Southern Hemisphere supply sustaining year-round retail presence. The supply chain draws from fertilizer, fuel, and 1-MCP post-harvest treatment inputs. Single-source vulnerability runs through Washington State labor availability tied to H-2A visa program complexity. Distribution runs through terminal market aggregation serving retail chains and foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through USDA National Organic Program certification and FDA Food Safety Modernization Act compliance creates switching costs that protect incumbent positioning.
For Market Incumbents: Consolidate controlled atmosphere storage capacity in Yakima Valley and Wenatchee Valley clusters to defend against climate-driven crop variability threatening supply continuity. Deepen backward integration into proprietary club variety breeding programs to lock propagation licensing and capture premium margin pools inaccessible to conventional growers. For New Entrants and Emerging Players: Lead with direct-to-consumer subscription box models targeting tier-one Chinese cities where import demand for Honeycrisp and club varieties outpaces established supply. White-space opportunity sits in digital-native farm-gate delivery bypassing terminal market fees, with organic certification as the go-to-market angle for European retail chain access. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because buyer concentration among top-ten US grocery retailers is compressing supplier negotiation leverage and mandating traceability infrastructure investments that favor scaled operators. Acquisition targets should display integrated packer-shipper capabilities with blockchain-enabled lot tracking. The signal to watch is phytosanitary protocol negotiation timelines with China's General Administration of Customs as inflection indicator for premium export volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Atmosphere Storage Expansion | Year-round Honeycrisp availability commands premium positioning in China import channels. |
| USDA Organic Certification Investment | EFSA residue alignment opens European retail private-label procurement programs. |
| Blockchain Traceability Deployment | Walmart and Kroger mandates favor integrated packer-shippers with tree-to-retail data systems. |
| Direct-to-Consumer Channel Launch | Subscription box models capture margin through farm-gate delivery bypassing terminal fees. |
| Club Variety Licensing Agreement | Controlled breeding program access restricts propagation to contracted growers commanding premium tiers. |
Methodological Framework
Desk research of USDA crop production reports, customs export records, and FDA Food Safety Modernization Act guidance documents preceded structured interviews with orchard operations managers, foodservice procurement directors, retail category buyers, and cold-chain logistics specialists. Primary fieldwork combined with secondary validation from EPA pesticide tolerance databases and EFSA scientific opinions. Bottom-up variety-level volume estimates triangulated against top-down regional production assessments.
Variance decomposition across product type, distribution channel, variety, and certification tier dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth trajectory modeling incorporating input cost elasticity, climate yield variability, and import demand expansion patterns. Industry-specific forecast inputs included H-2A visa program processing timelines and EU F-Gas Regulation compliance deadlines affecting container fleet certification.
The analysis sits within stated boundaries; outcomes outside current phytosanitary protocol trajectories and climate adaptation timelines would require recalibration. Forecasts reflect documented assumptions regarding labor availability, residue limit enforcement consistency, and cold-chain infrastructure investment continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Agricultural Enzymes Market
Others
Global Computer Peripherals Market
Others
Floor Cleaning and Mopping Machine Market
Others
Asia-Pacific Intercom Devices Market
Others
Shisha Tobacco Market
Others
Global Tobacco Market
Others
Latin America Travel Retail Market
Others
US Luxury Travel Market
Others
Bitcoin Mining Servers Market
Others
Smartphone Gimbal Market
Others
Augmented Reality in Energy and Utilities Market
Others
Mobile Computing Devices Market
Others
China Packaging Primers Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Mini Personal Computer Market
Others
Mainframe Computers Market