
 Mining Flotation Chemicals Market | 2026-2036
Mining Flotation Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Flotation Chemicals Market Outlook
A shortage of experienced metallurgical chemists is unwinding project timelines across greenfield concentrator builds. BASF SE leverages its Ludwigshafen integrated production complex to sustain captive supply of xanthate precursors for European miners. Clariant competes through specialized fatty amine collectors tailored to reverse flotation in Brazil's iron ore belt.
Mining flotation chemicals are surface-active reagents engineered to render target minerals hydrophobic or hydrophilic, typically operating at pH ranges between 8 and 12 in aqueous slurry systems. Their primary industrial purpose is to enable selective separation of value minerals from gangue in froth flotation circuits processing run-of-mine ore. Collector formulations dominate product-type value pools, with xanthate derivatives anchoring base-metal copper circuits while fatty amines occupy iron ore reverse flotation. Nickel laterite projects are driving fastest growth among application segments, as limonite and saprolite ores demand tailored chelating collectors that conventional sulfide reagents cannot address.
EPA tailings management rules in the United States and REACH substance restrictions in Europe are tightening permissible chemistries in flotation effluents, pushing formulators toward biodegradable alternatives. Brazil's ANM dam safety protocols and Australia's state-based environmental licensing frameworks are similarly elevating reagent performance standards for new mine approvals. Stakeholders must monitor how China's GB standards for wastewater discharge reshape export formulation requirements for suppliers serving Chinese-owned overseas assets.
Market Dynamics
Ore grade decline across Chilean and Peruvian copper belts is forcing miners toward higher-reagent-intensity flotation circuits, compressing margins while expanding absolute chemical consumption per tonne of metal produced.
Growth Catalysts
- REACH substance restrictions:European formulators are accelerating biodegradable collector development to preempt regulatory displacement, creating first-mover advantage in sustainable reagent categories.
- Nickel laterite processing:Australia's limonite and saprolite projects require chelating collectors that command premium formulations unavailable from conventional sulfide suppliers.
- Brazil's iron ore reverse flotation:Fatty amine demand concentrates in the Carajás belt where Vale operations process high-silica ores through froth suppression circuits.
Market Restraints
- Isopropyl xanthate feedstock volatility:Carbon disulfide and caustic soda price swings transmit directly into collector manufacturing costs, squeezing formulator margins unpredictably.
- Chinese xanthate concentration:Over 70% of global xanthate precursor capacity clusters in Shandong and Jiangsu provinces, exposing non-Chinese miners to single-source supply risk.
- EPA tailings effluent limits:Stricter residual reagent discharge thresholds in US jurisdictions are forcing circuit redesigns that extend project approval timelines by 18-24 months.
Strategic Opportunities
- Indonesian nickel processing:Laterite-to-matte projects in Sulawesi and Halmahera lack established local reagent supply chains, creating greenfield formulation partnerships.
- EU Green Deal industrial emissions targets:Carbon-border adjustments on imported concentrates will favor European processors deploying low-carbon flotation chemistries in domestic circuits.
- Digital reagent dosing systems:Integration of machine-vision froth analysis with automated collector injection is opening retrofits for aging concentrators in South Africa and Zambia.
Industry Challenges
- Metallurgical chemist scarcity:Greenfield concentrator builds in Guinea and Mongolia face 12-18 month hiring delays for qualified flotation circuit designers.
- Legacy xanthate storage infrastructure:Existing warehouse configurations at remote mine sites often fail ANM and WorkSafe Australia safety protocols for reactive reagent handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Flotation Chemicals Market |
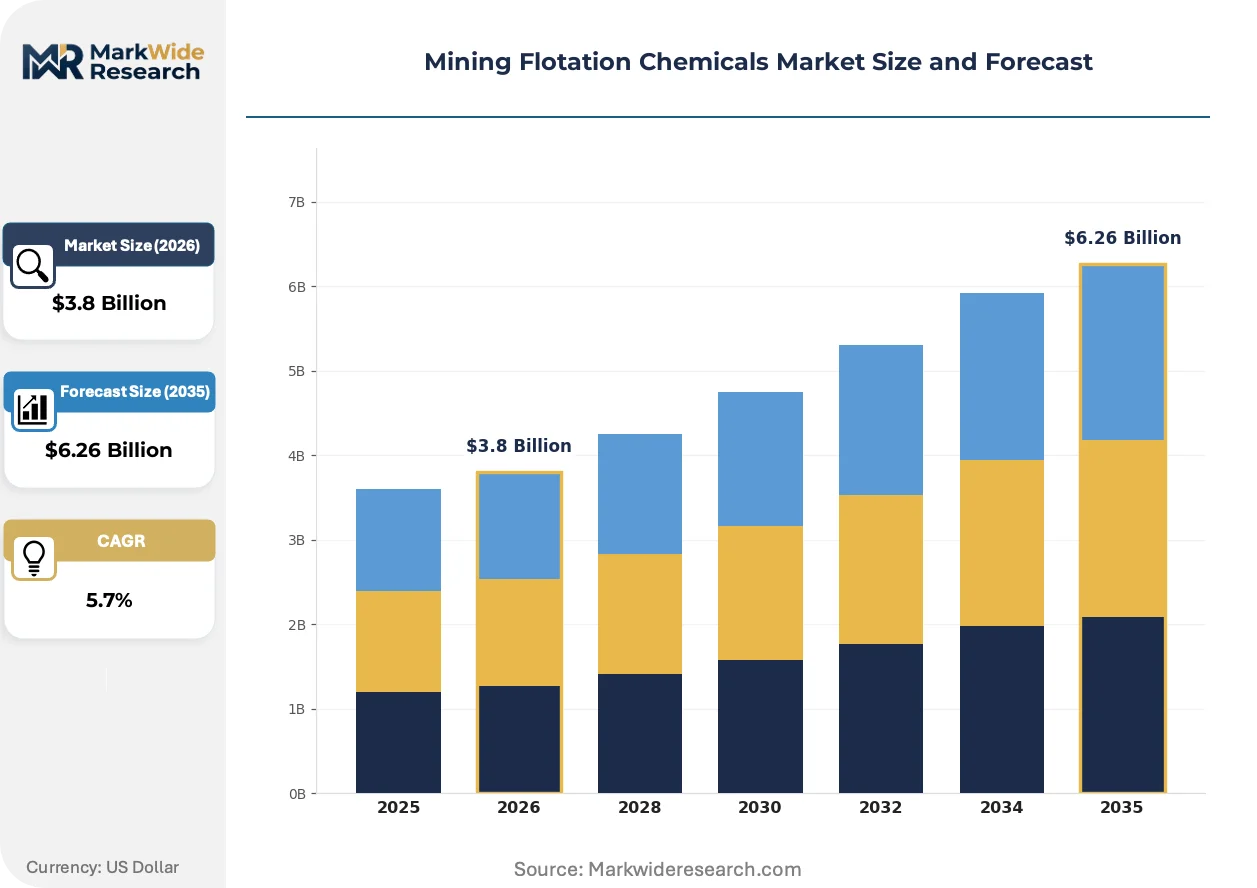
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collectors, Frothers, Modifiers, Depressants Application: Copper, Lead, Zinc, Nickel End User: Mining Companies, Mineral Processing Plants, OEMs, Traders Distribution Channel: Direct Sales, Distributors, Online Platforms, Retailers |
| Companies Covered | BASF SE, Clariant, Solvay, Arkema, Kemira, Chevron Phillips Chemical, Dow, SNF, Huntsman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Flotation Chemicals Market Strategic Shifts
Bio-based collector chemistry is crossing technical viability thresholds while automated process control systems rewrite how reagents are specified and procured in concentrator operations.
Thioester-modified fatty acid collectors are supplanting traditional xanthate formulations in complex polymetallic circuits. Chilean copper-molybdenum operations are piloting these reagents at 15-20% dosage reduction rates. The technology is compressing reagent opex while enabling processing of previously uneconomic transitional ore zones.
REACH authorization requirements for N-methyl-2-pyrrolidone and select frother alcohols are forcing European formulators toward solvent substitution programs. Industrial consequence includes accelerated R&D timelines for water-based dispersant systems. Nickel sulfide processors in Finland and Sweden face the steepest compliance cost escalations and are pre-qualifying alternative chemistries two years ahead of sunset dates.
Technical service unbundling from bulk chemical supply is restructuring buyer-vendor relationships in the sector. Major mining houses now separate reagent procurement from metallurgical consulting contracts, enabling direct engagement with specialized boutique formulators. This pattern is most pronounced in Australia's nickel laterite sector where junior developers bypass integrated suppliers for direct collector sourcing.
Mining Flotation Chemicals Market Segmentation
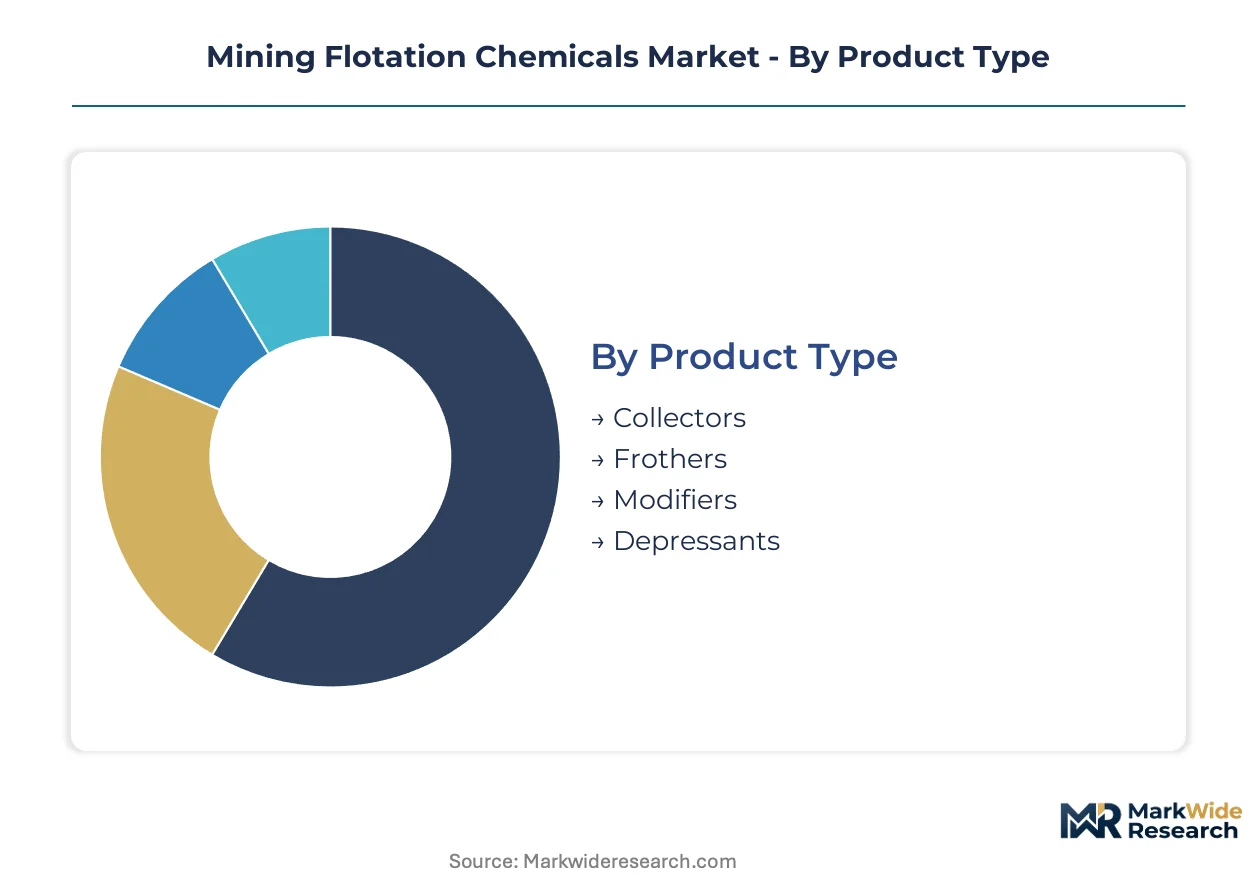
Segmentation in mining flotation chemicals reveals how reagent procurement channels diverge by technical complexity and volume scale. Understanding these patterns exposes where formulation partnerships concentrate versus where transactional spot purchasing dominates.
Product Type:
Collectors move primarily through direct sales channels anchored by long-term supply agreements, while frothers and modifiers flow more heavily through distributor networks serving mid-tier concentrators.
- Collectors:Xanthate derivatives and fatty amine formulations constitute the chemistry backbone for base-metal separation. Chilean copper concentrators in the Antofagasta region account for substantial offtake as declining ore grades force higher dosage rates per tonne milled.
- Frothers:Alcohol-based and polyglycol formulations stabilize froth phase in mechanical flotation cells. Australian nickel sulfide processors in Western Australia's Kambalda district are expanding methyl isobutyl carbinol consumption as they commission expanded rougher-scavenger circuits.
- Modifiers:pH regulators and dispersants including lime, caustic soda, and sodium silicate adjust slurry chemistry. Brazilian iron ore operations in Minas Gerais deploy starch-based depressants for reverse flotation of siliceous gangue.
- Depressants:Organic and inorganic formulations selectively inhibit unwanted mineral surfaces. Canadian polymetallic circuits in British Columbia use cyanide complexes for pyrite depression in gold-copper concentrates.
By volume, collectors lead. By growth pace, depressants are climbing the fastest as complex ore blends proliferate.
Application:
Cost tier stratification separates premium chelating formulations for refractory nickel laterites from commodity xanthate pricing in mature copper districts.
- Copper:Porphyry and sediment-hosted deposits drive bulk collector consumption. Peruvian operations in the Arequipa region are retrofitting molybdenum separation circuits that demand specialized thioester collectors unavailable from standard suppliers.
- Lead:Galena flotation in polymetallic veins requires selective collectors discriminating against sphalerite and pyrite. Mexican operations in Zacatecas are expanding capacity as silver-lead-zinc replacement deposits enter production.
- Zinc:Sphalerite activation with copper sulfate precedes fatty acid or amine collector attachment. Irish operations at Navan represent European demand concentration for high-grade zinc concentrate production.
- Nickel:Laterite limonite and saprolite processing demands chelating collectors that conventional sulfide reagents cannot address. Indonesian projects in Sulawesi are commissioning atmospheric acid leach circuits requiring imported specialty formulations.
Copper applications anchor revenue concentration. Nickel applications are expanding most quickly as laterite projects displace diminishing sulfide reserves.
End User:
Customer type determines procurement sophistication, with integrated majors demanding embedded technical service while junior developers prioritize cost minimization.
- Mining Companies:Majors and mid-tiers operating captive concentrators negotiate multi-year formulation supply contracts. Vale's Carajás complex in Brazil sources fatty amines through direct procurement with specification lock-in.
- Mineral Processing Plants:Independent toll treatment facilities serving artisanal and small-scale miners purchase through distributors. Ghanaian gold gravity plants in Ashanti region rely on spot market frother availability.
- OEMs:Flotation equipment manufacturers bundle reagent starter packages with cell and column sales. Outotec and FLSmidth include preliminary collector selection guidance in commissioning protocols.
- Traders:Commodity chemical merchants arbitrage regional price differentials for standard xanthate grades. Shandong-based traders supply African copperbelt operations through Dubai re-export hubs.
Mining companies dominate contract value. Mineral processing plants are gaining share fastest as toll milling expands in artisanal gold districts.
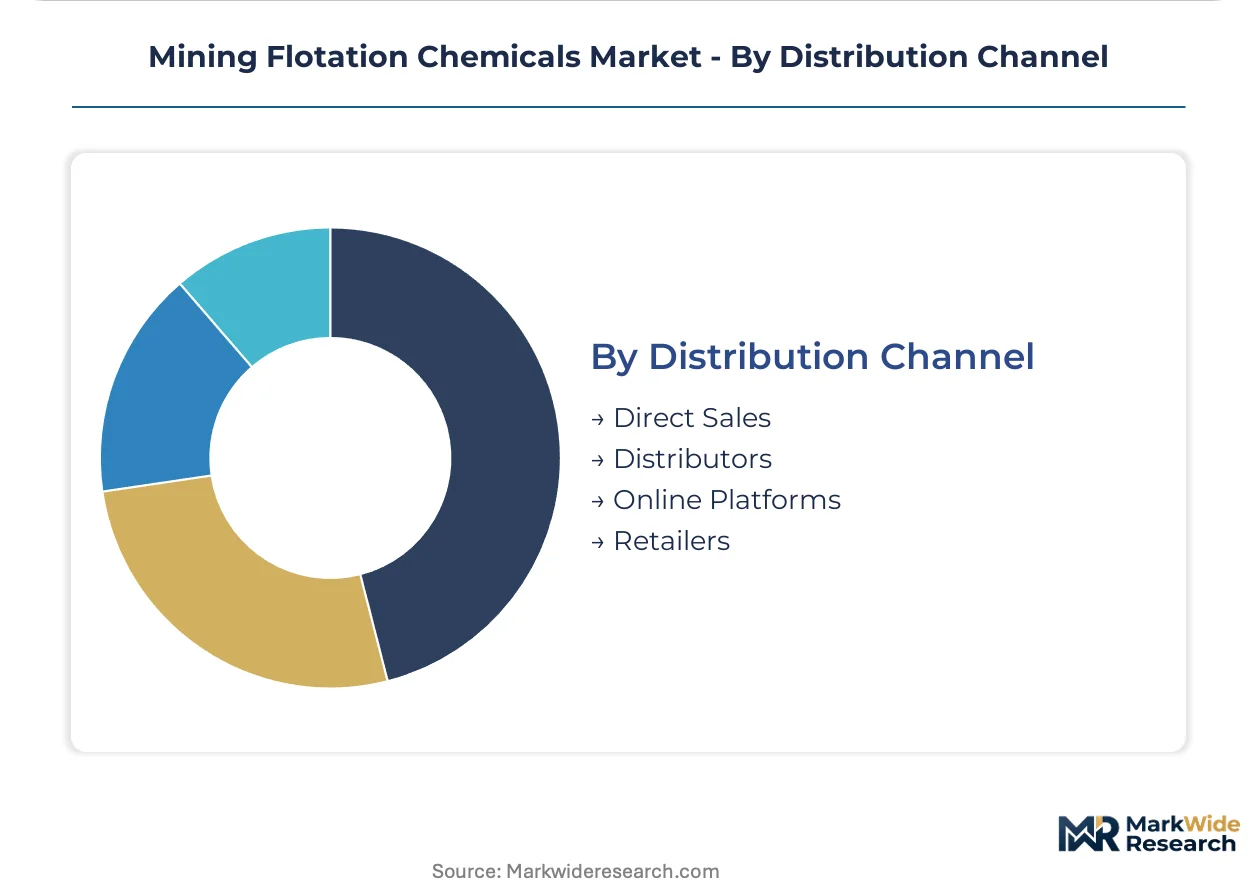
Distribution Channel:
Supply concentration in Chinese xanthate precursor manufacturing shapes channel economics, with direct sales bypassing intermediaries where volume thresholds justify dedicated logistics.
- Direct Sales:Bulk reagent producers maintain technical sales teams embedded at major concentrator sites. BASF SE deploys metallurgical specialists to Chilean copper operations for circuit optimization alongside chemical supply.
- Distributors:Regional chemical merchants hold inventory positions for just-in-time delivery to remote mine sites. Clariant's Brazilian distributor network covers iron ore reverse flotation demand across the Carajás belt.
- Online Platforms:Digital procurement portals emerge for standardized frother and modifier grades. South African mining suppliers list sodium isobutyl xanthate through Johannesburg-based commodity exchanges.
- Retailers:Limited to laboratory reagent quantities and trial samples for greenfield project evaluation. Perth-based mining supply houses serve Western Australian exploration juniors with collector test kits.
Direct sales capture the largest contract value. Online platforms are climbing the fastest as procurement digitization penetrates mid-tier mining houses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailings effluent rules and Brazil's ANM dam safety protocols are reshaping reagent specifications across the Americas, while Australia's state licensing frameworks and China's GB wastewater standards create divergent compliance zones for flotation chemical suppliers.
Chile
Declining ore grades in the Antofagasta copper belt are forcing higher xanthate dosage rates per tonne milled. The country's environmental superintendent enforces stricter residual reagent discharge limits for new concentrator permits. Codelco's Chuquicamata and El Teniente complexes anchor demand concentration as they retrofit molybdenum separation circuits requiring specialized thioester collectors.
Australia
Nickel laterite projects in Western Australia's Kambalda district are expanding methyl isobutyl carbinol consumption for rougher-scavenger circuits. State-based environmental licensing frameworks in Western Australia and Queensland are elevating reagent performance standards for new mine approvals. BHP's Nickel West operations and emerging limonite developers in the Goldfields-Esperance region are commissioning atmospheric acid leach circuits requiring imported chelating collector formulations.
Brazil
Vale's Carajás iron ore complex drives fatty amine demand for reverse flotation of high-silica ores. ANM dam safety protocols are forcing circuit redesigns that extend project approval timelines and mandate reactive reagent handling upgrades. The Minas Gerais iron ore belt is deploying starch-based depressants as operations adapt to stricter tailings management requirements.
Peru
Copper-molybdenum operations in the Arequipa region are piloting thioester-modified fatty acid collectors at dosage reduction rates. The Ministry of Energy and Mines is tightening permissible chemistries in flotation effluents for new porphyry projects. Southern Copper's Toquepala and Cuajone concentrators anchor collector consumption as they process increasingly complex transitional ore zones.
Indonesia
Laterite-to-matte projects in Sulawesi and Halmahera lack established local reagent supply chains for chelating collectors. The Ministry of Environment and Forestry is implementing stricter wastewater discharge standards for nickel processing facilities. Chinese-owned industrial parks in Morowali and Weda Bay are importing specialty formulations as domestic capacity for limonite and saprolite reagents remains undeveloped.
Mining Flotation Chemicals Market Competitive Environment
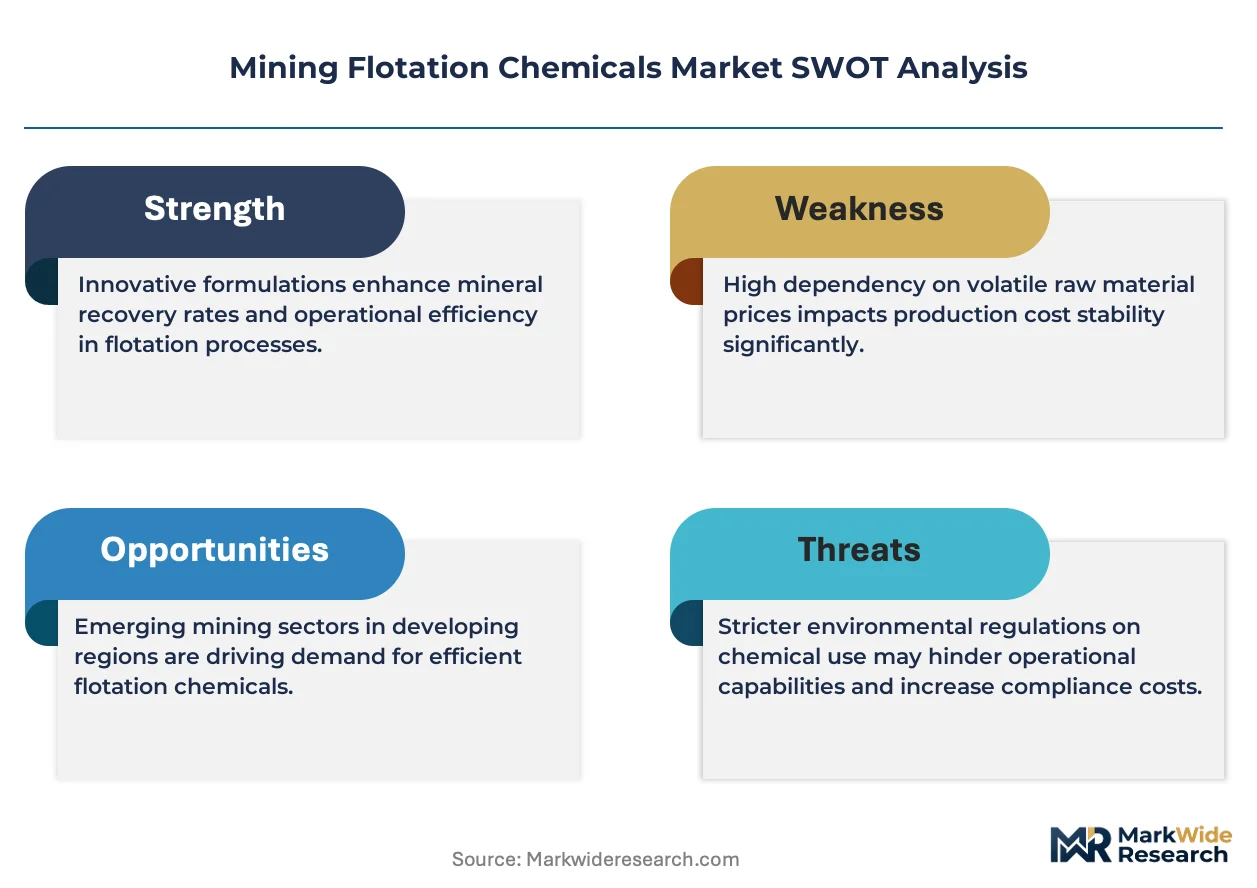
A small set of integrated leaders sits above a broader specialist tier in mining flotation chemicals. BASF SE and Clariant anchor the upper tier through captive precursor supply and regional formulation networks, while mid-scale players compete on technical service unbundling and boutique collector development. The market structure rewards backward integration into xanthate precursors and forward integration into metallurgical consulting. Dominant competitive moves include geographic expansion into Indonesian nickel projects and portfolio diversification toward biodegradable collector alternatives.
Among European-based integrated suppliers, BASF SE exemplifies the captive-production archetype through its Ludwigshafen complex, while Clariant occupies a specialist position in fatty amine collectors for reverse flotation. Solvay represents the diversified chemical conglomerate model with cross-sector reagent capabilities. These three companies anchor the competitive landscape as suppliers navigate divergent regulatory requirements across Chilean, Australian, and Brazilian jurisdictions.
| Leading Market Players |
|---|
| BASF SE |
| Clariant |
| Solvay |
| Arkema |
| Kemira |
| Chevron Phillips Chemical |
| Dow |
| SNF |
| Huntsman |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions in Europe and EPA tailings effluent rules in the United States simultaneously gate supplier qualification and create price differentiation between biodegradable and conventional collector formulations. Regulatory compliance costs concentrate in specialty chelating reagents for nickel laterite processing, where premium pricing reflects both technical complexity and limited qualified supply sources.
Pricing Analysis
Chilean copper concentrators pay 15-25% premiums over Brazilian iron ore operations for equivalent collector volumes due to remote logistics and dosage intensity requirements. Three-tier pricing structure across premium chelating collectors, standard xanthate derivatives, and economy fatty amine formulations reflects certification grade and volume scale differentiation. Cost compression in standard xanthate tiers is intensifying because Chinese precursor concentration exposes non-integrated formulators to feedstock volatility. Junior nickel laterite developers in Indonesia exhibit highest price sensitivity, while integrated majors in Australia prioritize performance guarantees over unit cost.
Supply Chain Analysis
Remote mine sites in Western Australia and the Chilean Atacama carry 6-8 week safety stock positions for reactive xanthate reagents due to seasonal logistics constraints. Manufacturing concentrates in China, Germany, and Brazil, with carbon disulfide and caustic soda feedstocks drawing from petrochemical complexes in Shandong, Ludwigshafen, and Camacari. Single-source vulnerability clusters in Shandong province xanthate precursor capacity expose non-Chinese miners to supply interruption. Distribution runs through direct technical sales teams for major concentrators and regional chemical distributors for mid-tier operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as technical service unbundling from bulk chemical supply creates niches for boutique formulators serving complex ore blends. Nickel laterite processing expansion in Indonesia and Australia generates demand segments where incumbent integrated suppliers lack established metallurgical expertise.
For Market Incumbents: Compound technical service capabilities through embedded metallurgical teams at major concentrator sites, defending against boutique specialists capturing laterite formulation partnerships. Deepen upstream control over xanthate precursor supply through captive production or long-term offtake agreements with Shandong manufacturers, mitigating feedstock volatility exposure. Prioritize biodegradable collector R&D investment to preempt REACH regulatory displacement in European markets. For New Entrants and Emerging Players: Technical service gaps in Indonesian nickel laterite projects offer white-space entry where established suppliers lack local metallurgical presence. Target atmospheric acid leach circuit operators in Sulawesi and Halmahera with direct collector sourcing partnerships bypassing integrated distributors. Deploy machine-vision froth analysis integration as differentiated go-to-market positioning for retrofits in South African and Zambian aging concentrators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical platforms holding regional formulation networks but lacking global scale. Five-to-ten year viability favors targets with backward integration into xanthate precursors or forward integration into metallurgical consulting. Watch for inflection in Chinese GB wastewater standard enforcement reshaping export formulation requirements for suppliers serving Chinese-owned overseas assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Xanthate Precursors | Captive supply of carbon disulfide derivatives insulates BASF from Shandong price volatility. |
| Biodegradable Collector Development | REACH-compliant formulations preempt regulatory displacement in European copper circuits. |
| Technical Service Unbundling | Direct engagement with Australian nickel laterite juniors bypasses integrated supplier markups. |
| Indonesian Formulation Partnerships | Greenfield supply chains in Sulawesi address laterite-to-matte project demand concentration. |
| Digital Reagent Dosing Systems | Machine-vision froth analysis retrofits open automation revenue in South African concentrators. |
Study Parameters
Desk research of trade customs data, SEC chemical sector filings, and ANM regulatory bulletins preceded structured interviews with concentrator plant managers, procurement leads at mining majors, flotation equipment OEM technical directors, and specialty chemical distribution partners. Primary fieldwork across Chilean copper operations, Australian nickel laterite projects, and Brazilian iron ore complexes validated secondary estimates. Bottom-up volume modeling triangulated against top-down chemical consumption intensity benchmarks.
Variance decomposition across ore grade decline trajectories, regulatory compliance cost escalations, and laterite project commissioning timelines shaped projection sensitivity bands. Segmentation dimensions modeled include reagent chemistry type, target mineral application, end-user procurement sophistication, and regional regulatory framework cluster. CAGRs derived from intensity-per-tonne coefficients applied to named mine production forecasts, with nickel laterite processing expansion and copper ore grade decline as primary demand drivers.
Forecasts assume regulatory continuity in REACH authorization timelines and EPA tailings effluent enforcement; material policy acceleration or relaxation would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Superplasticizer Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Immunochemicals Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Industrial Odor Management Market
Chemicals
Global Phenoxyethanol Market
Chemicals
Ferric Fluoride Market
Chemicals
Glyoxal Market
Chemicals
Iscotrizinol Market