
 Global P-Phenylenediamine Market | 2026-2036
Global P-Phenylenediamine Market Size, Share, and Industry Trends Forecast 2026-2036
Global P-Phenylenediamine Market Foresight
Project finance for specialty chemical intermediates is rewriting competitive access in P-phenylenediamine, allowing mid-scale producers to fund capacity without full balance-sheet commitment. LANXESS leverages its integrated aromatics platform to sustain European supply reliability. BASF anchors global technical-grade output through backward integration into nitrobenzene feedstock. Zhejiang Longsheng Group dominates Asian derivative production with captive reduction capacity.
P-phenylenediamine (PPD) is an aromatic diamine with the formula C₆H₄(NH₂)₂, produced primarily through catalytic hydrogenation of p-nitroaniline or nitrobenzene derivatives, serving as a critical coupling agent and antioxidant intermediate across polymer and colorant systems. Technical-grade PPD commands the largest volume share due to rubber-processing demand, while reagent-grade output carries the steepest premium margin pool for photographic and analytical applications. Hair coloring applications within cosmetic end-use are expanding fastest as oxidative dye formulations disperse across emerging markets.
REACH registration requirements in Europe, GB standards enforcement by China's SAMR, and EPA toxic substance reporting in the United States collectively elevate purity documentation burdens and restrict crude-grade import pathways. ECHA's skin-sensitization classifications for PPD derivatives are reshaping cosmetic formulation standards and substitution research priorities. Stakeholders must monitor regulatory divergence between EU hazard-based restrictions and Asia-Pacific performance-based standards to align product registration strategies with market access timelines.
Market Dynamics
REACH skin-sensitization classifications for PPD derivatives are compressing cosmetic formulation windows and accelerating substitution research across European personal-care supply chains. This regulatory pressure is reshaping competitive positioning between incumbent producers and bio-based alternatives.
Growth Catalysts
- Hair coloring demand:Oxidative dye formulations are dispersing across emerging-market cosmetic producers, pulling technical-grade PPD into mid-tier personal-care manufacturing clusters.
- REACH compliance:European purity documentation requirements are filtering out crude-grade imports and consolidating supply around certified producers with full toxicological dossiers.
- Rubber antioxidant applications:Tire manufacturers in China and India are absorbing technical-grade volumes as domestic automotive production scales.
Market Restraints
- Nitrobenzene feedstock volatility:Crude oil and benzene price swings transmit directly into PPD production economics, squeezing margin predictability for non-integrated producers.
- Asian supply concentration:Zhejiang and Shandong provinces host disproportionate reduction capacity, creating single-point vulnerability for global derivative supply.
- ECHA substitution pressure:The European Chemicals Agency's hazard-based restrictions on skin-sensitizing diamines are forcing cosmetic formulators toward para-aminophenol alternatives.
Strategic Opportunities
- Indian manufacturing expansion:Domestic cosmetic producers are localizing oxidative dye production under BIS quality mandates, opening captive PPD offtake agreements.
- Bio-based diamine R&D:Fermentation-derived phenylenediamine precursors are approaching pilot-scale viability, offering regulatory-compliant pathways for European cosmetic applications.
- Reagent-grade premium capture:Photographic chemical and analytical laboratory segments tolerate steep purity premiums, rewarding producers with pharmaceutical-grade certification.
Industry Challenges
- Catalytic hydrogenation expertise scarcity:Safe operation of high-pressure reduction reactors requires specialized chemical engineering talent concentrated in legacy aromatics clusters.
- Multi-jurisdiction registration timelines:Simultaneous compliance with REACH, EPA toxic substance reporting, and China's SAMR GB standards extends product launch cycles by 18-24 months.
- Legacy equipment retrofit costs:Existing nitrobenzene-to-PPD plants face capital-intensive upgrades to meet tightening MEE environmental discharge standards in China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global P-Phenylenediamine Market |
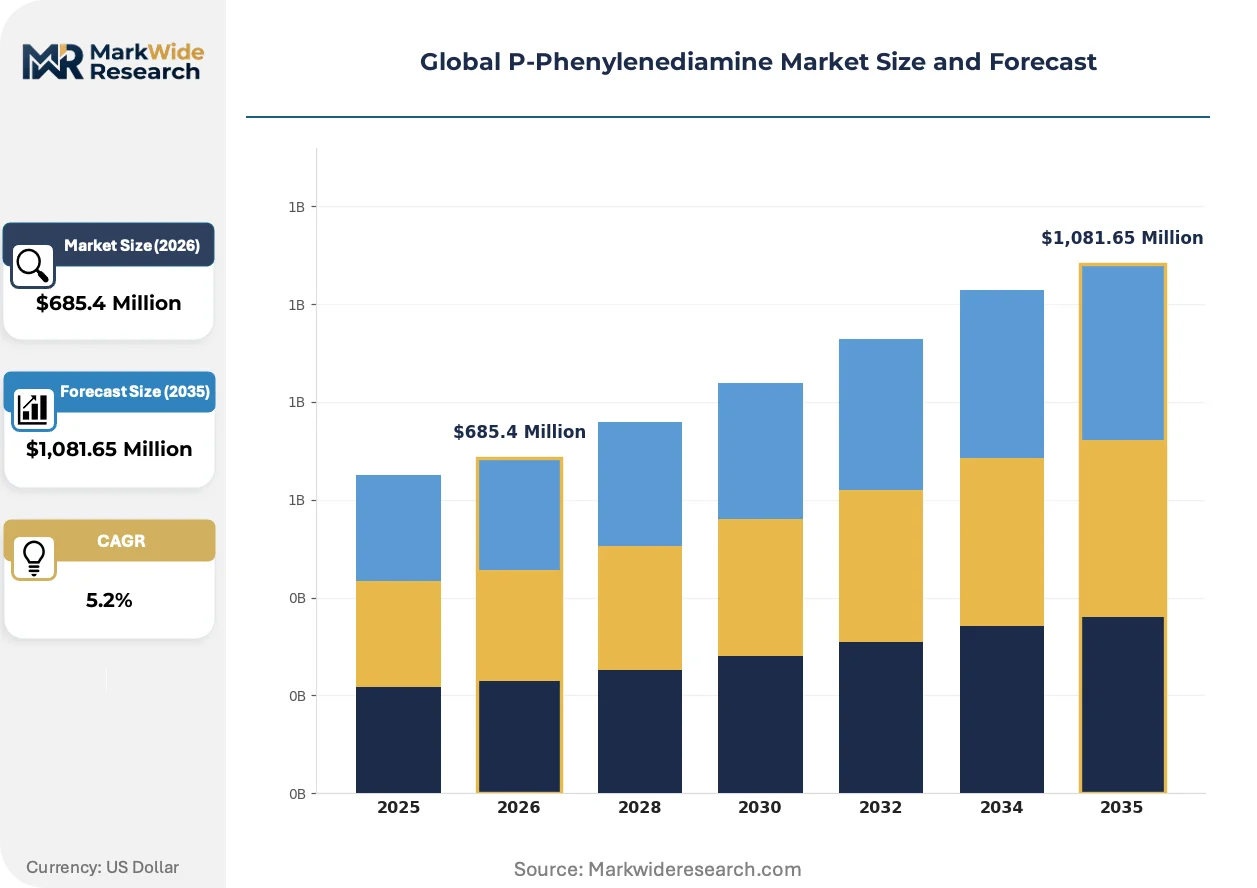
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure P-Phenylenediamine, Derivatives, Crude Grade, Technical Grade, Reagent Grade Application: Hair Coloring, Rubber Processing, Dye Manufacturing, Textile Treatment, Photographic Chemicals End User: C hemical Manufacturers, Cosmetic Producers, Polymer Plants, Textile Finishers, Photographic Labs Packaging Type: Drums, Bulk Bags, Carboys, Barrels, Intermediate Bulk Containers |
| Companies Covered | LANXESS, DuPont, BASF, Chizhou Fangda Technology, Anhui Xianglong Chemical, Deepak Nitrite, Zhejiang Longsheng Group, Aarti Industries, Huntsman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global P-Phenylenediamine Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine acceptable purity thresholds across cosmetic and industrial PPD applications. Three distinct vectors are compressing legacy production models while opening premium niches for compliant producers.
Continuous-flow hydrogenation reactor technology is migrating from batch processing paradigms toward integrated aromatics platforms. Specialty chemical engineers at European tire manufacturers are piloting these systems to reduce solvent waste and improve lot-to-lot consistency. This migration from conventional stirred-tank reduction is enabling real-time purity monitoring that satisfies REACH documentation burdens without batch-release delays.
ECHA's 2023 amendment to skin-sensitization classification criteria for aromatic diamines is forcing cosmetic formulators to revalidate entire oxidative dye portfolios. The industrial consequence is a bifurcation between legacy PPD-reliant formulations and reformulated para-aminophenol blends. Hair-colorant producers in Germany and France are most affected, accelerating partnerships with bio-based precursor suppliers to preempt regulatory exclusion.
Direct procurement contracts between cosmetic brand owners and certified PPD producers are displacing traditional distributor intermediaries in European supply chains. Specialty chemical distributors in the Netherlands and Belgium are losing volume to audited supplier networks that guarantee batch-level REACH compliance. This channel consolidation is most visible in German personal-care manufacturing clusters, where formulation houses now require full substance identity documentation upstream.
Global P-Phenylenediamine Market Segmentation
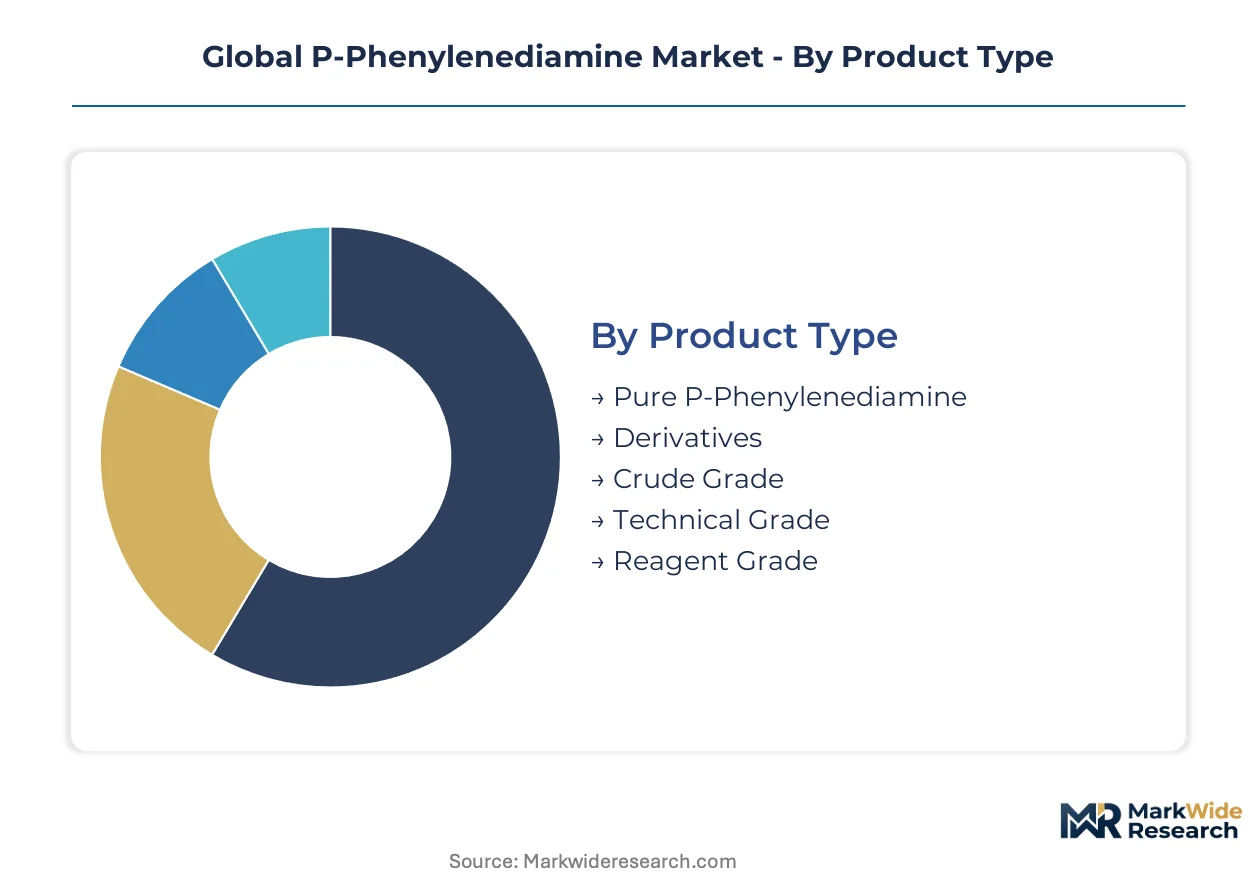
Segmentation in P-phenylenediamine reveals how purity grades, application chemistry, and packaging economics split procurement decisions across industrial and cosmetic value chains. Each dimension carries distinct margin profiles and regulatory compliance burdens.
Product Type:
Mature commodity grades dominate volume flows while specialty purities capture expanding premium pools in regulated applications.
- Technical Grade:Contains 95-98% purity PPD with controlled moisture and ash specifications. Tire manufacturers in China and India absorb the largest volumes as domestic automotive production scales, though nitrobenzene feedstock volatility squeezes margin predictability for non-integrated producers.
- Reagent Grade:Achieves 99.5%+ purity through multi-stage recrystallization and sub-micron filtration. Photographic chemical and analytical laboratory segments in Germany and France tolerate steep purity premiums, rewarding producers with pharmaceutical-grade certification and full REACH toxicological dossiers.
- Pure P-Phenylenediamine:Refers to crystalline material meeting specific melting point and chromatographic purity standards without formulated additives.
- Derivatives:Encompasses N-substituted and ring-modified variants produced for specialized coupling reactions in polymer stabilization.
- Crude Grade:Represents intermediate reduction output requiring further purification; increasingly filtered from European supply by REACH documentation requirements.
Technical grade retains volume leadership; reagent grade holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity industrial absorbents from specification-driven cosmetic and imaging chemistry.
- Hair Coloring:Oxidative dye formulations rely on PPD as a primary coupling agent for permanent color development. Cosmetic producers in India are localizing manufacturing under BIS quality mandates, pulling technical-grade material into mid-tier personal-care clusters.
- Rubber Processing:Antioxidant applications in tire and industrial rubber goods represent the foundational demand anchor. Domestic automotive production in China and India absorbs technical-grade volumes, though ECHA substitution pressure on skin-sensitizing diamines is forcing reformulation research.
- Dye Manufacturing:Serves as an intermediate for azo and sulfur dye synthesis in textile coloration systems.
- Textile Treatment:Applies to fiber stabilization and color-fastness enhancement in synthetic fabric processing.
- Photographic Chemicals:Requires ultra-high purity for developer and bleach-fix formulations in analog and specialty imaging.
Rubber processing commands the deepest volume base; hair coloring is climbing the fastest as emerging-market cosmetic production localizes.
End User:
Customer type determines whether procurement prioritizes certified supply chains or spot-market economics.
- Chemical Manufacturers:Intermediate producers integrating PPD into downstream antioxidant and dye chemistry.
- Cosmetic Producers:Formulation houses requiring batch-level REACH compliance documentation and full substance identity upstream.
- Polymer Plants:Tire and industrial rubber manufacturers absorbing technical-grade volumes through direct procurement contracts.
- Textile Finishers:Fabric treatment operations purchasing derivative grades for color-fastness applications.
- Photographic Labs:Specialty imaging facilities demanding reagent-grade certification with pharmaceutical-grade documentation.
Polymer plants anchor procurement volume; cosmetic producers are gaining share fastest as direct-audited supplier networks displace distributor intermediaries.
Packaging Type:
Supply concentration in Zhejiang and Shandong provinces shapes how material moves through ocean freight and inland distribution.
- Bulk Bags:Flexible intermediate containers dominate ocean freight for tire manufacturer direct delivery.
- Drums:Steel and fiber containers serve cosmetic and chemical manufacturer batch processing requirements.
- Intermediate Bulk Containers:Rigid composite tanks enable automated handling at polymer plant receiving facilities.
- Carboys:Glass or plastic containers protect reagent-grade material from moisture and light degradation.
- Barrels:Traditional steel containers retain position in legacy textile finishing supply chains.
Bulk bags retain volume leadership; intermediate bulk containers hold the steepest expansion curve as automated handling spreads through polymer plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH skin-sensitization classifications and China's GB standards enforcement are fragmenting regulatory pathways across major production zones. Manufacturers must navigate divergent purity documentation requirements while serving tire, cosmetic, and photographic chemical demand.
China
Domestic automotive production scales are absorbing technical-grade PPD volumes for rubber antioxidant applications. MEE environmental discharge standards are forcing capital-intensive upgrades at legacy nitrobenzene-to-PPD plants. Zhejiang and Shandong provinces host disproportionate reduction capacity, creating single-point vulnerability for global derivative supply chains.
Germany
ECHA's 2023 amendment to skin-sensitization classification criteria is forcing cosmetic formulators to revalidate oxidative dye portfolios. REACH registration requirements filter crude-grade imports and consolidate supply around certified producers with full toxicological dossiers. German personal-care manufacturing clusters now require audited supplier networks guaranteeing batch-level compliance documentation.
India
Domestic cosmetic producers are localizing oxidative dye production under BIS quality mandates, opening captive PPD offtake agreements. The country's national chemical regulator is tightening import documentation for aromatic diamine intermediates. Maharashtra and Gujarat industrial corridors are attracting mid-scale producers seeking project finance for specialty chemical capacity.
United States
EPA toxic substance reporting requirements elevate purity documentation burdens for PPD importers and domestic manufacturers. Photographic chemical and analytical laboratory segments in specialty imaging tolerate steep reagent-grade premiums. Gulf Coast petrochemical corridors provide backward integration opportunities for nitrobenzene feedstock security.
Japan
METI industrial standards for high-performance rubber goods are sustaining technical-grade demand from domestic tire manufacturers. Pharmaceutical-grade certification requirements protect premium margins for reagent-grade producers serving analytical and imaging chemistry. Osaka and Nagoya industrial zones maintain specialized catalytic hydrogenation expertise for aromatic diamine production.
Global P-Phenylenediamine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification and purity-grade segments. The vendor base organizes around three strategic archetypes: integrated aromatics platforms with captive nitrobenzene supply, mid-scale specialists with project-financed reduction capacity, and reagent-grade purifiers capturing photographic chemical premiums. Dominant competitive moves include backward integration into feedstock security and geographic expansion through direct-audited supplier networks displacing distributor intermediaries.
Within the integrated platform tier, LANXESS and BASF exemplify European supply reliability through aromatics integration and technical-grade scale. Zhejiang Longsheng Group anchors Asian derivative production capacity. These three occupy positions spanning REACH-compliant European supply and emerging-market volume absorption.
| Leading Market Players |
|---|
| LANXESS |
| DuPont |
| BASF |
| Chizhou Fangda Technology |
| Anhui Xianglong Chemical |
| Deepak Nitrite |
| Zhejiang Longsheng Group |
| Aarti Industries |
| Huntsman |
| Others |
Supply & Pricing Matrix
Undercapacity in European catalytic hydrogenation facilities is compressing technical-grade availability and pushing cosmetic manufacturers toward premium-certified supply tiers. This utilization squeeze tightens supplier bargaining power while forcing buyers to absorb documentation-heavy procurement costs.
Pricing Analysis
Certification level (REACH-compliant vs. crude-grade) creates the primary spread between reagent-grade and technical-grade quotations. Contract-based long-term offtake dominates tire manufacturer procurement, while spot-market exposure concentrates among mid-scale cosmetic formulators lacking direct-audited supplier relationships. Price differentiation stems from purity documentation burdens and backward integration into nitrobenzene feedstock. Cost compression in technical-grade tiers is intensifying because Zhejiang and Shandong capacity expansions outpace domestic automotive absorption. Polymer plants exhibit lowest price sensitivity due to volume-scale leverage; photographic chemical labs tolerate steepest premiums for pharmaceutical-grade certification.
Supply Chain Analysis
Nitrobenzene feedstock security anchors supply chain economics for integrated aromatics platforms. Production concentrates in China, Germany, and India, with Zhejiang province hosting disproportionate reduction capacity. The chain draws from benzene derivatives, catalytic hydrogenation expertise, and REACH-compliant logistics infrastructure. Single-source vulnerability in Shandong reduction clusters threatens global derivative availability. Distribution runs through direct-audited supplier networks displacing traditional Dutch and Belgian distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The P-phenylenediamine market is cycling through a recovery phase as tire production normalization in China and India restarts technical-grade volume absorption.
For Market Incumbents: Entrench REACH-compliant supply positions by securing backward integration into nitrobenzene feedstock and expanding catalytic hydrogenation capacity in Maharashtra industrial corridors. ECHA substitution pressure on skin-sensitizing diamines demands accelerated bio-based precursor R&D partnerships to preempt regulatory exclusion from European cosmetic formulations.
For New Entrants and Emerging Players: Build out project-financed reduction capacity targeting Indian domestic cosmetic producers localizing oxidative dye manufacturing under BIS quality mandates. The most penetrable white-space sits in reagent-grade purification for photographic chemical segments, where pharmaceutical-grade certification tolerates steep margin capture. A direct-audited supplier network go-to-market model bypasses distributor intermediaries consolidating in German personal-care clusters.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated aromatics platforms with captive nitrobenzene supply and full REACH toxicological dossiers. Long-term viability over the next decade rests on regulatory compliance depth rather than volume-scale commodity positioning. Acquisition targets should display catalytic hydrogenation expertise concentration and audited supplier network penetration. The signal to watch is ECHA amendment velocity on aromatic diamine hazard classifications, which would accelerate substitution research timelines and compress legacy formulation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrobenzene | Secures feedstock economics for LANXESS and BASF against benzene price volatility. |
| REACH Compliance Certification | Filters crude-grade competitors from European cosmetic supply chains. |
| Continuous-Flow Hydrogenation Scale-Up | Reduces solvent waste for tire manufacturers piloting real-time purity monitoring. |
| Bio-Based Precursor R&D Partnership | Preempts ECHA regulatory exclusion through fermentation-derived phenylenediamine pathways. |
| Direct-Audited Supplier Network Expansion | Displaces Dutch and Belgian distributors in German personal-care manufacturing clusters. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant managers at catalytic hydrogenation facilities, procurement leads at tire manufacturers, cosmetic formulation R&D directors, and distribution channel partners; and secondary validation through customs/trade data, Cefic sector reports, SEC 10-K filings, and REACH registration databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators.
Forecast inputs considered grade tier, end-use industry, packaging format, and regional production hub segmentation across the analysis window. CAGRs were derived from elasticity-adjusted demand projections incorporating nitrobenzene feedstock cost trajectories and regulatory compliance timeline assumptions. Industry-specific inputs included automotive production scaling in China and India, plus ECHA classification amendment velocity.
Stress conditions across benzene price volatility, REACH enforcement intensity, and substitution technology maturation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from feedstock shocks or regulatory divergence. Cross-checking against Cefic aromatics trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hydrophobing Agents Market
Chemicals
Allyl Chloride Market
Chemicals
Aluminium Chloride Market
Chemicals
Ferric Oxide Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Canada Methanol Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Di Nitro Toluene Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
Global Construction Chemical Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Valeronitrile Market
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Scouring Agents Market