
 Canada Methanol Market | 2026-2036
Canada Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Methanol Market Insights
Multi-source feedstock procurement is repositioning supply security for Canadian methanol consumers. Methanex Corporation dominates North American production capacity with integrated natural gas-to-methanol operations. HELM Proman Methanol AG leverages global trading networks to serve Canadian industrial buyers. Zagros Petrochemical Company competes through cost-advantaged Middle Eastern supply reaching Canadian ports.
Methanol is a light, volatile alcohol (CH₃OH) produced primarily through steam methane reforming of natural gas, with specifications typically requiring purity above 99.85% for chemical-grade applications. It serves as a foundational chemical building block for formaldehyde, acetic acid, and methyl tert-butyl ether synthesis, while emerging fuel applications exploit its high hydrogen-to-carbon ratio and clean-burning characteristics. Chemical Methanol occupies the dominant value share due to entrenched demand from formaldehyde and acetic acid manufacturers. Bio-Methanol represents the fastest-expanding product category as Canadian refiners seek renewable-content credits under federal clean fuel rules. Fuel Methanol applications are maturing in marine and heavy-transport segments where bunker fuel substitution protocols are tightening.
Environment and Climate Change Canada administers the Clean Fuel Regulations mandating progressive carbon-intensity reductions for liquid transportation fuels. Health Canada and the PMRA jointly govern methanol purity standards for consumer and industrial chemical applications. Provincial regulators in Alberta and British Columbia coordinate hydrogen hub development that will reshape methanol's role as a hydrogen carrier. Stakeholders must track regulatory alignment between federal carbon pricing and provincial hydrogen strategies to anticipate feedstock cost trajectories and offtake contract structures.
Market Dynamics
The Clean Fuel Regulations from Environment and Climate Change Canada are compressing carbon-intensity benchmarks for transportation fuels. This regulatory pressure is redirecting methanol demand toward bio-methanol pathways and hydrogen carrier applications while tightening specifications for conventional chemical-grade supply.
Growth Catalysts
- Clean Fuel Regulations:Environment and Climate Change Canada's mandates for liquid transportation fuels are pulling refiners toward methanol blending and bio-methanol procurement to meet progressive carbon-intensity reduction schedules.
- Alberta hydrogen hub investments:Provincial coordination of hydrogen infrastructure in Alberta is embedding methanol as a hydrogen carrier for heavy-transport and industrial feedstock applications.
- Marine bunker substitution:International Maritime Organization protocols tightening sulfur and carbon limits are accelerating methanol adoption for vessel propulsion systems calling at Vancouver and Prince Rupert ports.
Market Restraints
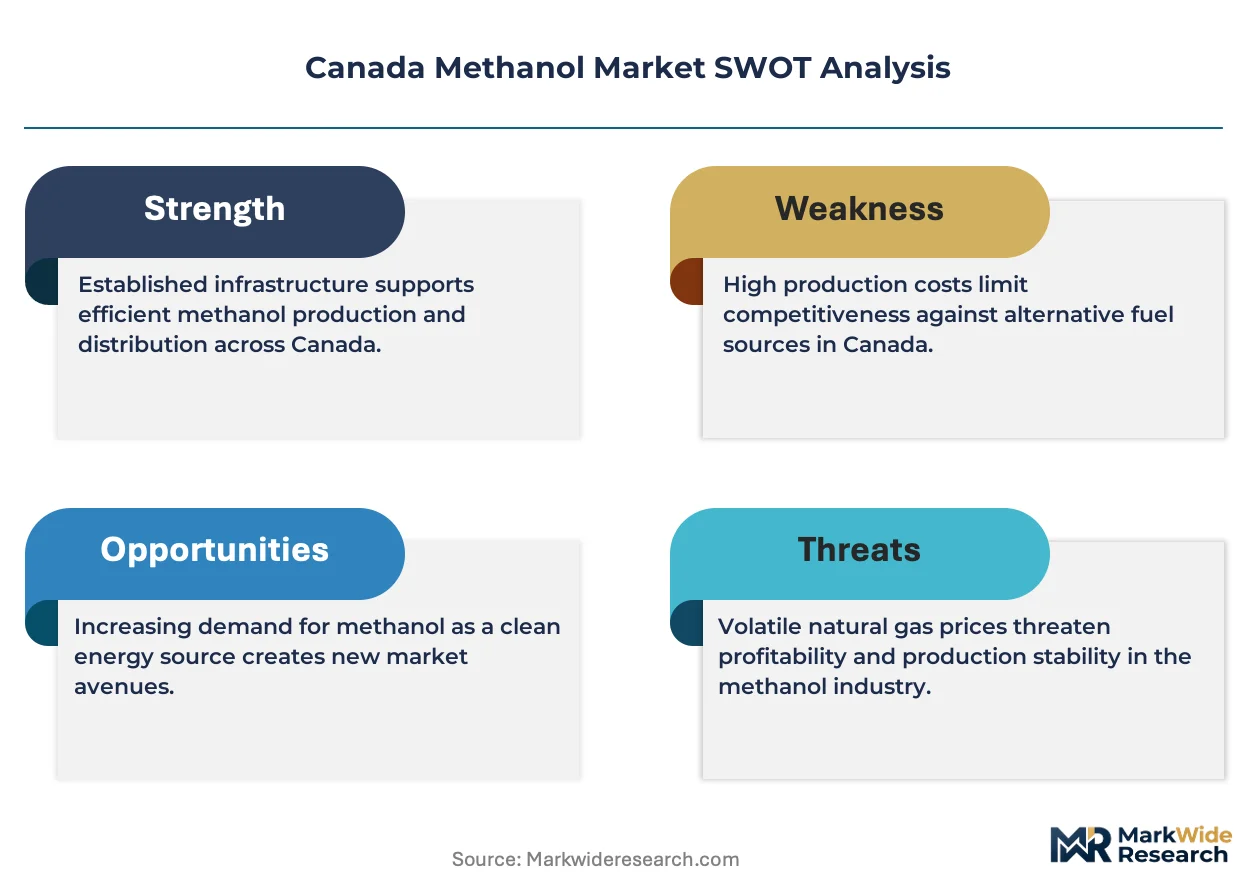
- Natural gas price volatility:Steam methane reforming economics for conventional methanol production fluctuate with Alberta and British Columbia natural gas benchmarks, compressing margin predictability for domestic producers.
- Middle Eastern supply concentration:Cost-advantaged production from Persian Gulf exporters reaches Canadian ports through Vancouver and Montreal terminals, limiting pricing power for North American manufacturers.
- Electrolytic hydrogen competition:Direct green hydrogen production via electrolysis is displacing methanol-mediated hydrogen pathways in some industrial decarbonization roadmaps.
Strategic Opportunities
- Bio-methanol certification pathways:Federal renewable-content credits under Clean Fuel Regulations are opening premium pricing tiers for waste-feedstock and biomass-derived methanol supplied to British Columbia refiners.
- Fuel-cell vehicle deployment:British Columbia's zero-emission vehicle mandate is converging with methanol-to-hydrogen reforming technology for long-haul trucking corridors between Vancouver and Alberta.
- Carbon capture integration:Alberta's carbon sequestration hub infrastructure enables blue methanol production with documented carbon intensity reductions qualifying for regulatory credits.
Industry Challenges
- Process safety engineering talent:Methanol's toxicity and flammability specifications require specialized hazard and operability expertise that Canadian petrochemical employers struggle to source domestically.
- Clean Fuel Regulations compliance timeline:Refiners face compressed certification cycles for bio-methanol provenance documentation to satisfy Environment and Climate Change Canada audit protocols.
- Legacy formaldehyde plant retrofits:Chemical-grade methanol consumers in Ontario and Quebec confront capital-intensive equipment upgrades to handle variable bio-methanol feedstock compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Methanol Market |
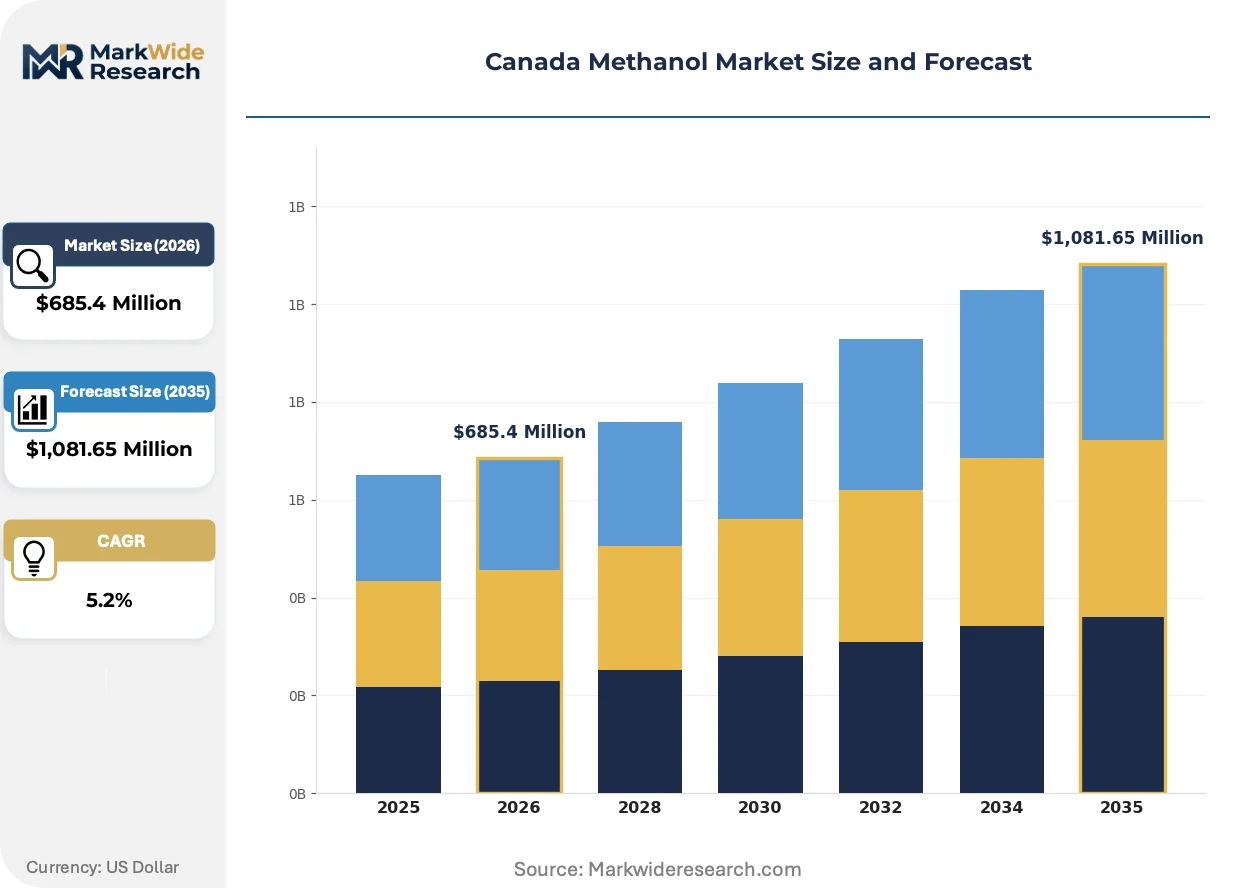
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Methanol, Chemical Methanol, Bio-Methanol, Industrial Methanol End User: Automotive, Chemicals, Energy, Construction Application: Solvents, Feedstock, Fuel, Production Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | HELM Proman Methanol AG, Zagros Petrochemical Company, Methanex Corporation, Exxon Mobil Corporation, Celanese Corporation, SABIC, Yankuang Energy Group Company Limited, Johnson Matthey, Valenz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Methanol Market Trends and Innovations
Carbon accounting transparency is reshaping procurement specifications across Canadian methanol offtake contracts. Buyers now require documented lifecycle emissions data that differentiates conventional, blue, and bio-methanol pathways.
Modular small-scale reforming units are unifying distributed hydrogen production with on-site methanol conversion. Remote mining operations in northern Alberta and British Columbia are piloting containerized systems that eliminate cryogenic hydrogen transport. This technology is compressing logistics costs for off-grid industrial decarbonization while creating captive methanol demand outside traditional petrochemical corridors.
Environment and Climate Change Canada's Clean Fuel Regulations are mandating granular carbon-intensity reporting for liquid transportation fuels. Refiners must now source methanol with verified lifecycle emissions data to calculate compliance credits accurately. British Columbia's integrated biorefinery projects are responding by securing long-term bio-methanol supply contracts with third-party certification.
Refinery procurement teams are consolidating supplier relationships around integrated carbon-accounting platforms. Spot-market methanol transactions are declining as Alberta and British Columbia fuel blenders pursue multi-year offtake agreements with embedded emissions verification. This concentration is most visible in the marine fuel segment, where Vancouver bunker suppliers now require methanol vendors to provide ISO-compliant carbon footprint documentation.
Canada Methanol Market Segmentation
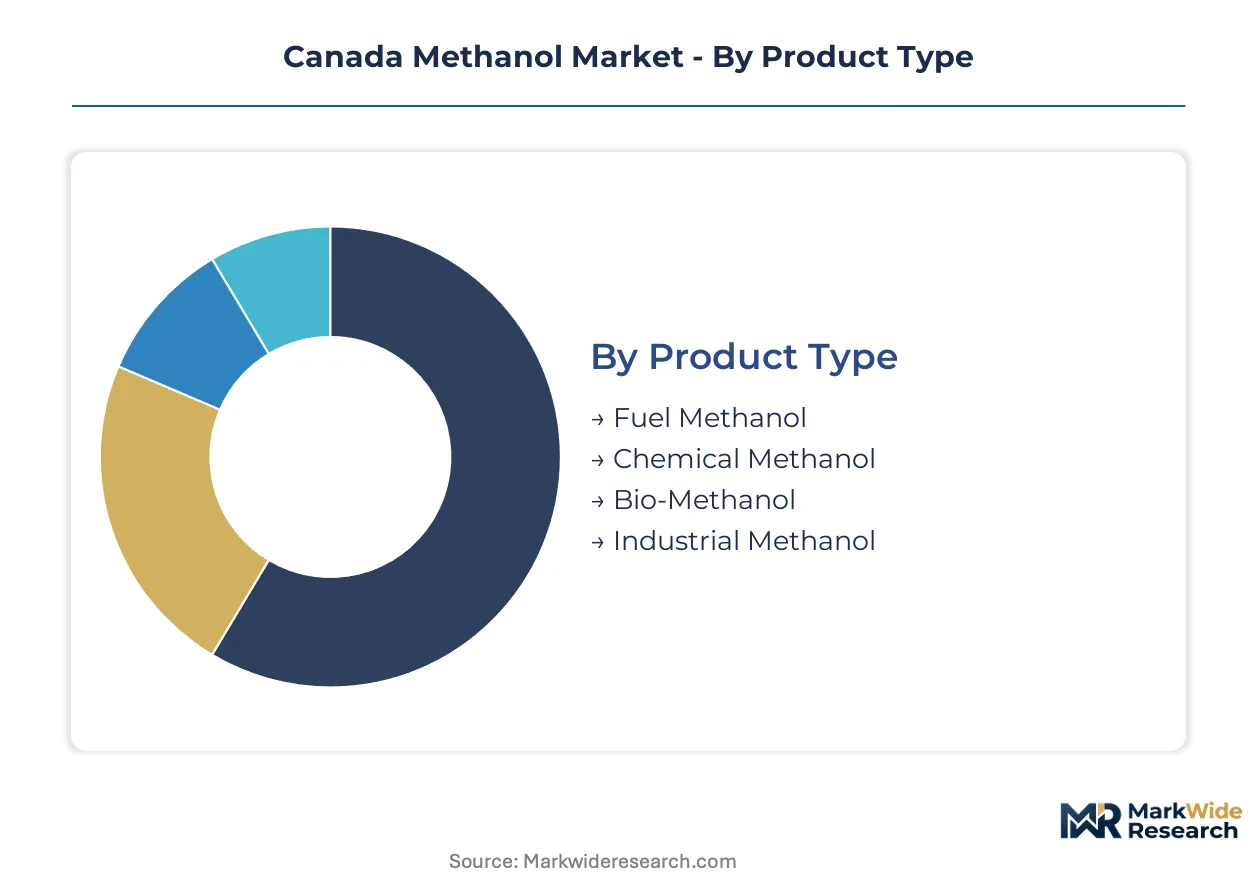
Canada's methanol market segments reflect divergent purity specifications and carbon-intensity requirements across fuel, chemical, and industrial applications. Procurement patterns increasingly favor supply with documented lifecycle emissions data for Clean Fuel Regulations compliance.
Product Type:
Standardization dominates fuel and chemical grades, while bio-methanol carries premium certification variability.
- Chemical Methanol:Purity specifications above 99.85% serve formaldehyde and acetic acid synthesis. Demand concentrates in Ontario and Quebec chemical corridors where legacy plants require consistent feedstock composition.
- Bio-Methanol:Waste-feedstock and biomass-derived variants qualify for federal renewable-content credits. British Columbia refiners are securing long-term supply contracts with third-party carbon certification to meet Environment and Climate Change Canada audit protocols.
- Fuel Methanol:Marine and heavy-transport applications exploit clean-burning characteristics for bunker fuel substitution at Vancouver and Prince Rupert ports.
- Industrial Methanol:Lower-purity grades serve solvent and extraction processes in mining and manufacturing operations across Alberta.
Most installed capacity flows through Chemical Methanol. Expansion is steepest in Bio-Methanol.
End User:
Volume concentration versus margin capture varies sharply across customer categories.
- Chemicals:Formaldehyde and acetic acid manufacturers in Ontario and Quebec represent the largest volume offtake. These consumers face capital-intensive equipment upgrades to handle variable bio-methanol feedstock compositions.
- Automotive:Fuel blending and fuel-cell applications are gaining traction as Alberta hydrogen hub investments embed methanol as a hydrogen carrier for long-haul trucking corridors.
- Energy:Power generation and heating applications serve remote industrial facilities with limited pipeline access.
- Construction:Formaldehyde-based resins for wood panel manufacturing drive steady demand from British Columbia forest products sector.
Procurement scale peaks with Chemicals. Technology transition is most pronounced in Automotive.
Application:
Functional role determines specification stringency and contract structure.
- Feedstock:Chemical synthesis applications demand consistent purity and supply reliability. Multi-year offtake agreements dominate procurement as Alberta and British Columbia fuel blenders seek embedded emissions verification.
- Fuel:Transportation and marine propulsion applications require ISO-compliant carbon footprint documentation. Vancouver bunker suppliers now mandate verified lifecycle emissions data from methanol vendors.
- Solvents:Industrial cleaning and extraction processes use lower-grade supply with flexible purity tolerances.
- Production:On-site methanol-to-hydrogen reforming serves remote mining operations in northern Alberta and British Columbia through containerized modular units.
Contract duration extends longest in Feedstock. Spot market erosion is fastest in Fuel.
Distribution Channel:
Supply chain configuration aligns with customer scale and technical service requirements.
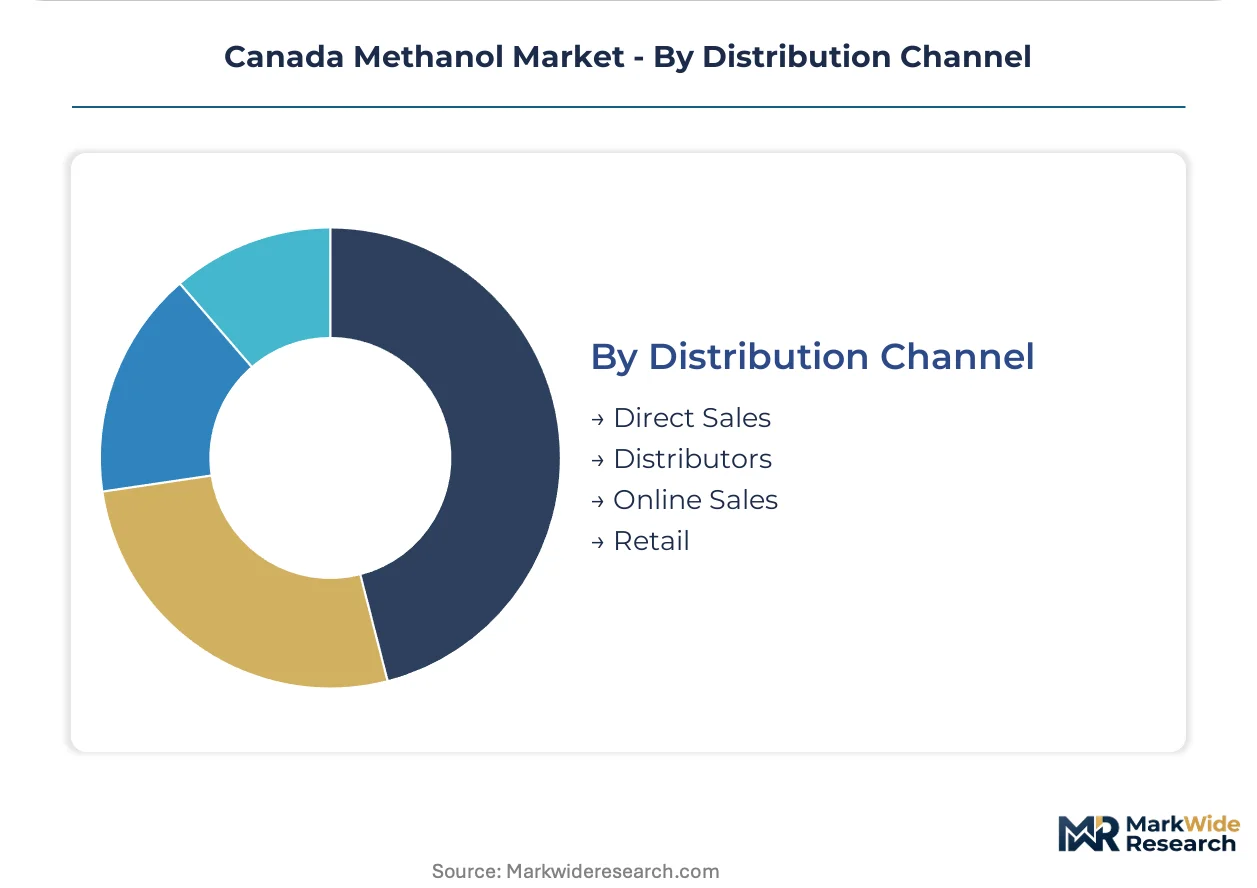
- Direct Sales:Large-volume chemical and fuel blenders negotiate multi-year agreements with integrated carbon-accounting platforms. Methanex Corporation and HELM Proman Methanol AG serve major Canadian industrial buyers through direct relationships.
- Distributors:Regional intermediaries handle fragmented construction and small industrial accounts across Ontario and Quebec.
- Online Sales:Digital procurement platforms serve specialty solvent applications with standardized specifications.
- Retail:Limited presence for consumer-grade methanol products governed by Health Canada and PMRA purity standards.
Revenue concentration sits with Direct Sales. Channel experimentation is most active in Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alberta's petrochemical corridor anchors Canadian methanol demand through integrated natural gas processing and emerging hydrogen hub investments. Provincial regulators in British Columbia and Alberta coordinate industrial decarbonization strategies that reshape methanol's role as a fuel and hydrogen carrier. Sub-regional concentration patterns reflect feedstock access, port infrastructure, and clean fuel policy implementation timelines.
Ontario
Formaldehyde and acetic acid manufacturers in the Sarnia-Ontario chemical corridor represent the largest volume methanol offtake in central Canada. Health Canada and the PMRA jointly govern purity standards for industrial chemical applications serving wood panel and resin producers. Toronto-area procurement teams face capital-intensive equipment upgrades to handle variable bio-methanol feedstock compositions from emerging suppliers.
Quebec
Construction sector demand from formaldehyde-based resins drives steady methanol consumption across the province's forest products sector. Provincial industrial regulators coordinate with federal Clean Fuel Regulations implementation timelines for transportation fuel blending. Montreal port terminals handle cost-advantaged Middle Eastern methanol supply reaching Canadian markets through established maritime routes.
Alberta
Steam methane reforming economics concentrate methanol production capacity near Edmonton and Calgary natural gas processing infrastructure. Provincial hydrogen hub development embeds methanol as a hydrogen carrier for heavy-transport corridors connecting to British Columbia. Carbon sequestration hub infrastructure enables blue methanol production with documented carbon intensity reductions qualifying for regulatory credits.
British Columbia
Zero-emission vehicle mandates converge with methanol-to-hydrogen reforming technology for long-haul trucking corridors between Vancouver and Alberta. Environment and Climate Change Canada's Clean Fuel Regulations pull refiners toward bio-methanol procurement with third-party carbon certification. Vancouver and Prince Rupert ports accelerate methanol adoption for marine bunker fuel substitution under International Maritime Organization protocols.
Canada Methanol Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-methanol certification and modular hydrogen carrier applications. The Canadian market structures around three archetypes: integrated natural gas-to-methanol operators, global trading houses with maritime logistics networks, and cost-advantaged Middle Eastern exporters. Strategic moves concentrate on multi-year offtake agreements with embedded emissions verification and carbon-accounting platform integration.
Within the integrated production tier, Methanex Corporation exemplifies North American capacity concentration through captive natural gas supply arrangements. HELM Proman Methanol AG represents global trading network leverage serving Canadian industrial buyers through direct relationships. Zagros Petrochemical Company anchors cost-advantaged Middle Eastern supply reaching Canadian ports through Vancouver and Montreal terminals.
| Leading Market Players |
|---|
| HELM Proman Methanol AG |
| Zagros Petrochemical Company |
| Methanex Corporation |
| Exxon Mobil Corporation |
| Celanese Corporation |
| SABIC |
| Yankuang Energy Group Company Limited |
| Johnson Matthey |
| Valenz |
| Others |
Pricing and Supply Chain Analysis
Alberta natural gas benchmarks cascade through Canadian methanol supply chains into three distinct pricing tiers tied to carbon-intensity certification. Environment and Climate Change Canada's Clean Fuel Regulations compress margin structures for uncertified supply while opening premium capture for bio-methanol pathways with third-party verification.
Pricing Analysis
Input-cost pass-through from steam methane reforming economics dominates methanol pricing structures across Canadian markets. Pricing stratifies across premium bio-methanol with renewable-content credits, standard blue methanol with carbon capture documentation, and economy chemical-grade supply without certification. Cost compression in the standard tier intensifies because Middle Eastern exporters reach Vancouver and Montreal terminals at landed costs below domestic production. Chemical manufacturers in Ontario and Quebec demonstrate highest price sensitivity due to legacy equipment constraints, while British Columbia refiners purchasing marine bunker fuel show lowest sensitivity given regulatory compliance premiums.
Supply Chain Analysis
Dual-sourcing requirements from Alberta and British Columbia fuel blenders mandate multi-supplier qualification to mitigate single-source vulnerability during carbon-intensity audit cycles. Supply concentrates in Trinidad and Tobago through Methanex Corporation's integrated operations, the United States via Gulf Coast exporters, and Iran through Zagros Petrochemical Company's cost-advantaged Middle Eastern production reaching Canadian ports. Raw material dependencies center on natural gas feedstock, specialized catalysts for reforming processes, and carbon capture equipment for blue methanol certification. Tariff exposure runs through potential trade measure adjustments affecting Persian Gulf supply routes. Distribution runs through direct sales relationships for large-volume chemical and fuel blenders, with regional distributors handling fragmented construction and small industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada Methanol Market functions as a stable compounder anchored by irreversible regulatory tightening under Clean Fuel Regulations that mandate progressive carbon-intensity reductions.
For Market Incumbents: Anchor market position through backward integration into Alberta carbon sequestration hub infrastructure to secure blue methanol certification. Deepen captive natural gas supply arrangements and invest in modular reforming unit deployment for remote hydrogen carrier applications. Electrolytic hydrogen competition threatens methanol-mediated pathways in industrial decarbonization roadmaps. For New Entrants and Emerging Players: Containerized methanol-to-hydrogen reforming technology offers entry into off-grid mining operations in northern Alberta and British Columbia. Target bio-methanol certification pathways for British Columbia refiners seeking renewable-content credits under federal clean fuel rules. Pursue long-term offtake agreements with embedded emissions verification as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated producers possessing carbon capture capabilities and established maritime logistics networks. The five-to-ten-year viability window favors operators with documented lifecycle emissions data and multi-year refinery contracts. Acquisition target archetype: mid-scale bio-methanol ventures with third-party certification and Alberta or British Columbia offtake relationships. Monitor International Maritime Organization bunker fuel protocol tightening as the inflection indicator for marine methanol demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Enables blue methanol production qualifying for Environment and Climate Change Canada regulatory credits. |
| Bio-Methanol Certification Investment | Secures premium pricing tiers under federal renewable-content credit frameworks for British Columbia refiners. |
| Modular Reforming Unit Deployment | Serves remote Alberta and British Columbia mining operations with on-site hydrogen production eliminating cryogenic transport. |
| Long-Term Offtake Agreement Structuring | Locks in multi-year revenue visibility with Alberta and British Columbia fuel blenders requiring emissions verification. |
| Hydrogen Hub Partnership Development | Embeds methanol as carrier molecule within provincial Alberta infrastructure coordinating heavy-transport decarbonization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply estimates for Canadian methanol markets. Primary engagement captured perspectives from petrochemical plant managers, refinery procurement leads, hydrogen hub project developers, and marine bunker fuel suppliers. Secondary validation drew from Environment and Climate Change Canada regulatory filings, Alberta Energy Regulator hydrogen infrastructure disclosures, customs trade data through Vancouver and Montreal port authorities, and SEC 10-K filings from North American methanol producers. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic indicators.
Segment-weighting approaches distributed volume and value projections across product type, end user, application, and distribution channel dimensions. Chemical-grade, bio-methanol, fuel-grade, and industrial-grade purity tiers each carried distinct growth assumptions reflecting Clean Fuel Regulations compliance timelines. End-use segmentation weighted formaldehyde and acetic acid manufacturing, automotive fuel blending, marine propulsion, and construction resin applications. CAGRs derived from regression analysis against natural gas price trajectories, carbon credit pricing, and hydrogen infrastructure investment flows.
The model holds under sustained regulatory enforcement of carbon-intensity benchmarks; deviation in International Maritime Organization protocol implementation timing or Alberta hydrogen hub funding commitments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Tin Chemicals Market
Chemicals
Carcinogenic Chemical Alternatives Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Ruthenium Tetroxide Market
Chemicals
Waterborne Curing Agents Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
Brazil Methanol Market
Chemicals
De-Icing Agents Market
Chemicals
Tromethamine Market
Chemicals
Fluorene Market
Chemicals
Europe Tertiary Amines Market
Chemicals
Egypt Construction Chemicals Market
Chemicals
Fluorochemicals Market
Chemicals
Whitening Ingredients Market