
 Precious Metal Plating Chemicals Market | 2026-2036
Precious Metal Plating Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Precious Metal Plating Chemicals Market Outlook
IATF 16949 qualification for automotive plating supply chains is rotating the competitive set toward vendors with certified process control. Atotech leverages its captive precious metal refining to sustain margin stability across gold and palladium salt portfolios. Johnson Matthey anchors aerospace qualification pathways through AS9100-adherent rhodium and platinum electroplating systems. Technic Inc. competes on specialty electrolytic solutions for high-reliability electronics substrates.
Precious metal plating chemicals comprise formulated electrolytes, electroless baths, and pre-treatment cleaners containing dissolved gold, silver, platinum, or palladium salts, typically operated at controlled pH and temperature parameters to deposit thin metallic coatings onto conductive or catalyzed surfaces. These formulations serve critical functions in corrosion protection, electrical conductivity enhancement, and wear resistance across precision manufacturing sectors. Electroless plating solutions command premium positioning due to their ability to deposit uniform coatings on complex geometries without external power, while electrolytic solutions dominate volume throughput in high-speed reel-to-reel electronics processing. Cleaners represent a mature, cost-competitive segment where formulation differentiation hinges on substrate compatibility rather than precious metal content.
EPA effluent guidelines constrain cyanide-bearing discharge from plating operations in the United States, while REACH registration requirements in Europe mandate full substance toxicity dossiers for imported precious metal salts. Japan's METI chemical management framework imposes additional reporting burdens on palladium compound handlers, collectively elevating compliance costs for non-integrated distributors. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory positions as formulation standards tighten.
Market Dynamics
Semiconductor packaging miniaturization is compressing plating bath lifecycles and forcing reformulation cycles from 18 months toward 9-month intervals. This acceleration favors integrated suppliers with captive analytical laboratories over commodity distributors.
Growth Catalysts
- Advanced Packaging Migration:Flip-chip and 2.5D/3D integration architectures in Taiwan and South Korea are consuming palladium-nickel barrier layers at elevated volumes. Taiwan Semiconductor Manufacturing and Samsung Foundry qualification protocols are locking in chemistry suppliers.
- RoHS and REACH Compliance:European electronics OEMs are redirecting specification sheets toward cyanide-free gold and silver formulations. ECHA substance dossier requirements are filtering out non-compliant importers.
- Automotive Sensor Electrification:LiDAR and camera module manufacturers in Germany and Japan are specifying rhodium flash coatings for connector reliability under thermal cycling.
Market Restraints
- Palladium Price Volatility:Automotive catalyst demand and Russian supply uncertainty are transmitting 40-60% annual cost swings into electroplating salt pricing.
- Specialized Waste Treatment:Cyanide-bearing effluent requires sodium hypochlorite destruction or thermal hydrolysis, adding $0.08-0.15 per liter disposal cost in EPA-regulated US facilities.
- Substitute Material Threat:Conductive polymer coatings for EMI shielding in consumer electronics are displacing electroless nickel-immersion gold on non-critical substrates.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme beneficiaries including Dixon Technologies and Lava International are qualifying local plating chemical sources for smartphone PCB fabrication.
- Hydrogen Electrolyzer Stacks:Proton exchange membrane manufacturers are specifying platinum-iridium coated titanium bipolar plates, opening industrial-scale demand outside traditional electronics.
- Closed-Loop Metal Recovery:Urban mining partnerships with German precious metal refiners are enabling toll-refining models that stabilize raw material costs for mid-tier formulators.
Industry Challenges
- Analytical Chemist Shortage:Atomic absorption spectroscopy and cyclic voltammetry expertise for bath control is retiring faster than vocational programs replace it in US and Japanese facilities.
- IATF 16949 Certification Burden:Automotive plating suppliers face 12-18 month audit cycles with document retention requirements spanning 15 years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precious Metal Plating Chemicals Market |
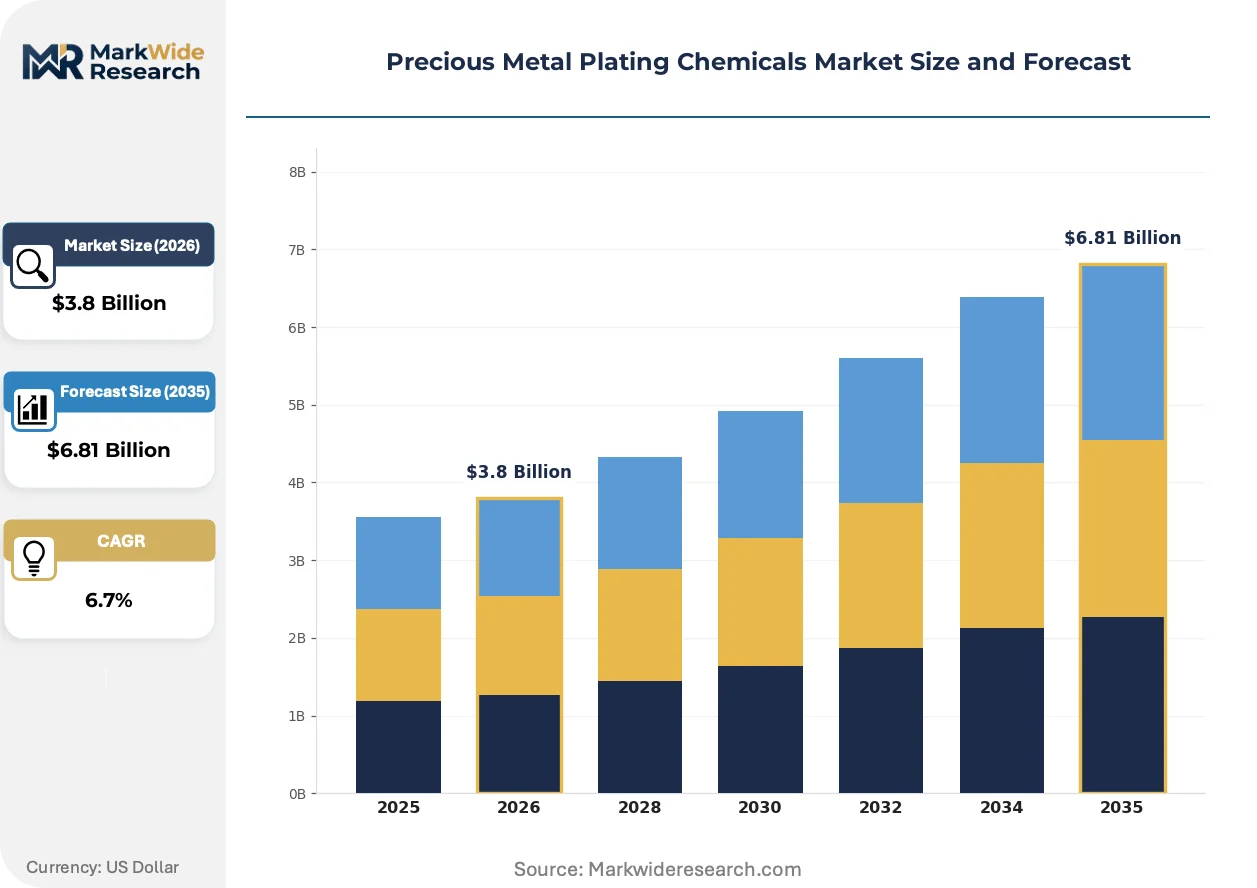
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroless Plating Solutions, Electrolytic Solutions, Anodizing Solutions, Cleaners Application: Electronics, Automotive Components, Jewelry, Aerospace Parts End User: Manufacturers, Retailers, Distributors, Contractors Chemical Composition: Gold, Silver, Platinum, Palladium |
| Companies Covered | Atotech, MacDermid Enthone, Umicore, Johnson Matthey, Technic Inc., BASF, Metalor Technologies SA, Heraeus Holding, SAXONIA Edelmetalle GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precious Metal Plating Chemicals Market Strategic Shifts
Formulation science is diverging toward application-specific molecular architectures rather than universal electrolyte platforms. This specialization is fragmenting R&D budgets and reshaping supplier-customer technical partnerships.
Electroless palladium-phosphorus deposition chemistry is fragmenting the established nickel-gold under bump metallization stack for fine-pitch wafer-level chip-scale packages. Advanced packaging houses in Hsinchu and Yongin are qualifying 3-5 microinch palladium barriers as direct copper wire bond surfaces. This displacement is compressing gold salt volumes per wafer start while elevating palladium compound purity requirements to 99.99% minimum.
EPA effluent guideline revisions under the Clean Water Act are mandating zero discharge of cyanide-complexed metals from new plating facility permits issued after 2024. US-based job shops are retrofitting ion exchange and electrowinning recovery systems at $2-4 million per facility. Surface finishing operations serving aerospace and medical device OEMs face the steepest compliance timelines due to existing master service agreement renewal cycles.
Specification-driven supplier consolidation is concentrating qualified vendor lists at major EMS providers. Foxconn and Jabil are reducing plating chemistry sources from 6-8 per region to 2-3 with integrated technical service capabilities. This consolidation is most visible in Shenzhen and Penang, where supplier scorecards now weight on-site analytical support equally with unit pricing.
Precious Metal Plating Chemicals Market Segmentation
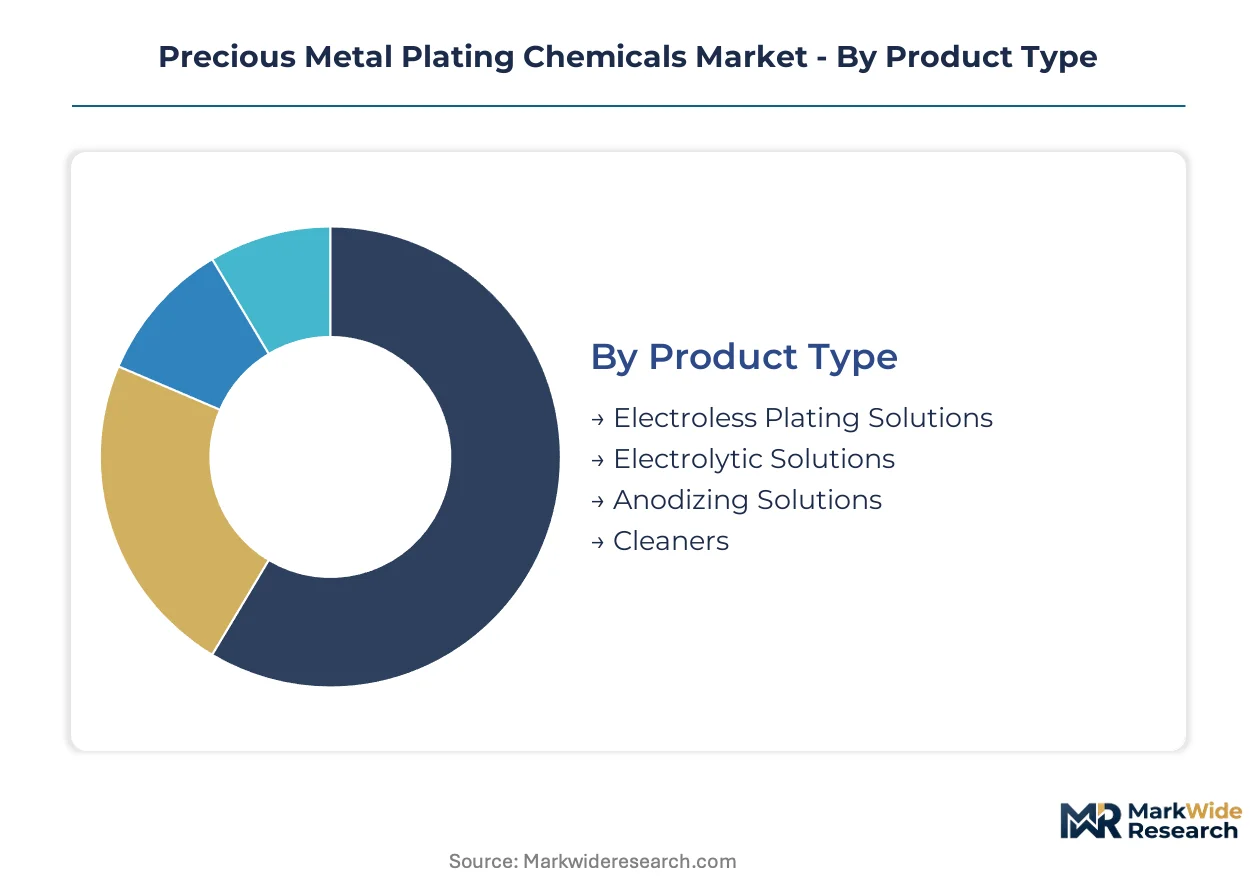
Segmentation in precious metal plating chemicals reveals how formulation chemistry, end-use specifications, and metal volatility intersect to create distinct competitive arenas. Each dimension carries unique regulatory exposure and margin profiles that reshape supplier positioning across electronics, automotive, and aerospace verticals.
Product Type:
EPA effluent guidelines and REACH substance dossier requirements are fragmenting competitive positioning across formulation categories, with cyanide-bearing chemistries facing steeper compliance burdens than cyanide-free alternatives.
- Electroless Plating Solutions:Self-catalyzing baths deposit uniform metal layers without external current, enabling complex geometries in semiconductor packaging. Taiwan Semiconductor Manufacturing and Samsung Foundry qualification protocols are locking in suppliers for palladium-phosphorus barrier layers in Hsinchu and Yongin.
- Electrolytic Solutions:Externally powered electrolytes dominate high-speed reel-to-reel processing for PCB fabrication. China's Dongguan and Shenzhen clusters consume the largest volumes for connector and contact plating under MIIT environmental discharge standards.
- Anodizing Solutions:Electrochemical conversion coatings for aluminum substrate protection in aerospace and medical device housings. Boeing and Airbus master service agreements specify sulfuric acid anodizing with sealed chromate-free finishes.
- Cleaners:Pre-treatment formulations for substrate degreasing and oxide removal prior to plating activation. Mature segment where differentiation hinges on compatibility with lead-frame alloys rather than precious metal content.
Electrolytic solutions handle the majority of throughput; electroless plating solutions are climbing the fastest on share as advanced packaging architectures proliferate.
Application:
End-use concentration in electronics manufacturing is elevating qualification barriers, with automotive and aerospace segments demanding IATF 16949 and AS9100 certifications that filter out commodity distributors.
- Electronics:PCB fabrication, semiconductor packaging, and connector plating consume formulated chemistries at scale. South Korea's memory chip foundries and China's PCB clusters in Kunshan and Wuxi anchor regional demand under divergent REACH and GB standard compliance frameworks.
- Automotive Components:Sensor housings, connector systems, and fuel cell bipolar plates specify rhodium flash and platinum-iridium coatings. German LiDAR manufacturers and Japanese camera module suppliers are driving thermal cycling reliability specifications.
- Jewelry:Decorative gold and silver electrodeposition for fashion and luxury goods. Italian and Indian manufacturing centers prioritize cyanide-free formulations under tightening ECHA and BIS substance restrictions.
- Aerospace Parts:High-reliability coatings for turbine blades, fasteners, and avionics connectors. AS9100-adherent rhodium and platinum systems from qualified suppliers serve Boeing, Airbus, and Safran tier-1 networks.
Electronics commands the dominant revenue share; automotive components are expanding most quickly as sensor electrification and hydrogen electrolyzer stacks open new demand channels.
End User:
Procurement concentration among integrated OEMs is compressing qualified vendor lists, with technical service capabilities now weighted equally against unit pricing in supplier scorecards.
- Manufacturers:OEMs and EMS providers with captive plating operations in Taiwan, South Korea, and China. Foxconn and Jabil are reducing regional chemistry sources from 6-8 to 2-3 with on-site analytical support.
- Retailers:Jewelry and decorative goods sellers specifying finished plating services from contract finishers. Italian and Indian retail chains are qualifying local formulators under PLI scheme incentives and ECHA compliance filters.
- Distributors:Chemical merchants serving job shops without direct supplier relationships. Margin pressure from integrated competitors is forcing specialization in niche alloys or geographic pockets.
- Contractors:Independent plating shops serving aerospace, medical device, and industrial OEMs. EPA zero-discharge mandates for new permits are driving $2-4 million recovery system retrofits at US facilities.
Manufacturers absorb the largest volume flows; contractors face the steepest compliance cost inflation as effluent standards tighten across EPA and MEE jurisdictions.
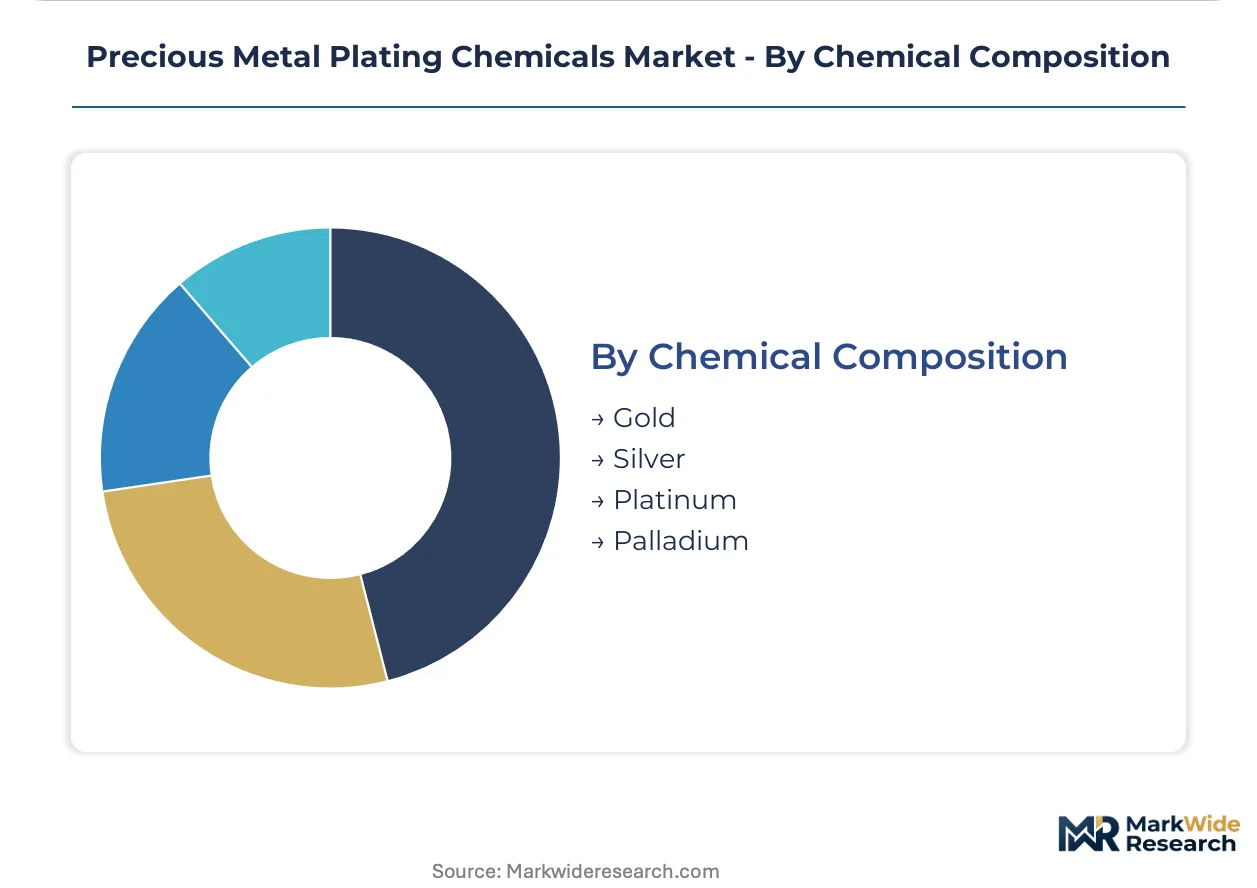
Chemical Composition:
Metal price volatility and supply concentration are reshaping formulation economics, with palladium and platinum facing automotive catalyst competition while gold and silver navigate electronics miniaturization pressures.
- Gold:Cyanide and cyanide-free salts for high-conductivity coatings in semiconductor wire bonding and PCB edge contacts. Taiwan and South Korea packaging houses are compressing gold volumes per wafer start as palladium barriers displace traditional nickel-gold stacks.
- Silver:Antimicrobial and high-conductivity deposits for medical devices, power electronics, and RF shielding. European OEMs are redirecting specifications toward REACH-compliant cyanide-free alternatives under ECHA substance dossier requirements.
- Platinum:Corrosion-resistant coatings for hydrogen electrolyzer bipolar plates and aerospace spark plug electrodes. Proton exchange membrane manufacturers are opening industrial-scale demand outside traditional electronics applications.
- Palladium:Barrier layers for copper wire bonding and automotive catalytic converter substrates. Russian supply uncertainty and automotive catalyst demand are transmitting 40-60% annual cost swings into electroplating salt pricing.
Gold maintains the largest installed base; palladium is gaining share fastest as advanced packaging architectures and hydrogen infrastructure buildouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and China's dual carbon goals are redirecting plating chemical procurement toward certified regional suppliers. Taiwan and South Korea packaging foundries anchor advanced semiconductor demand. EPA zero-discharge mandates and REACH dossier requirements are elevating compliance costs across US and European facilities.
China
Dongguan and Shenzhen PCB clusters consume electrolytic gold and palladium salts at industrial scale for connector plating. MIIT environmental discharge standards under GB frameworks are forcing job shops toward closed-loop recovery systems. Kunshan and Wuxi surface finishing operations are consolidating supplier lists to 2-3 qualified vendors with on-site analytical support.
South Korea
Samsung Foundry and SK Hynix memory packaging lines are qualifying palladium-phosphorus barrier chemistries for copper wire bonding applications. METI-aligned chemical management protocols impose additional reporting burdens on palladium compound handlers. Yongin and Pyeongtaek advanced packaging houses are compressing gold volumes per wafer start as palladium displaces nickel-gold stacks.
United States
Aerospace OEMs in Seattle and Wichita specify AS9100-adherent rhodium and platinum systems for turbine blade coatings. EPA effluent guidelines mandate zero discharge of cyanide-complexed metals from new plating permits issued after 2024. Connecticut and California job shops face $2-4 million retrofit costs for ion exchange and electrowinning recovery infrastructure.
Germany
LiDAR and camera module manufacturers in Stuttgart and Munich are specifying rhodium flash coatings for automotive sensor connector reliability. REACH substance dossier requirements through ECHA are filtering out non-compliant precious metal salt importers. Solingen and Pforzheim jewelry finishing centers are redirecting specifications toward cyanide-free gold formulations.
India
PLI scheme beneficiaries including Dixon Technologies and Lava International are qualifying local plating chemical sources for smartphone PCB fabrication. BIS substance restrictions are tightening on cyanide-bearing formulations in decorative and electronics applications. Noida and Chennai EMS clusters are reducing chemistry sources from 6-8 per region to 3-4 with integrated technical service capabilities.
Precious Metal Plating Chemicals Market Competitive Environment
Listed leaders compete with private specialists across formulation certification and captive metal refining capabilities. The vendor base concentrates around integrated suppliers with IATF 16949 and AS9100 qualifications that commodity distributors cannot replicate. Three archetypes dominate: precious metal refiners with backward integration into salt production; specialty chemical formulators with captive analytical laboratories; and regional distributors surviving on niche alloy specialization. Competitive moves center on M&A for certification assets and strategic partnerships for urban metal recovery toll-refining.
Within the integrated refiner-formulator tier, Atotech leverages captive precious metal refining to sustain margin stability across gold and palladium salt portfolios. Johnson Matthey anchors aerospace qualification pathways through AS9100-adherent systems. Technic Inc. occupies a position among specialty electrolytic solution providers for high-reliability electronics substrates. These three exemplify how metal price volatility and regulatory compliance burdens favor suppliers with upstream control over raw material costs and in-house analytical capabilities.
| Leading Market Players |
|---|
| Atotech |
| MacDermid Enthone |
| Umicore |
| Johnson Matthey |
| Technic Inc. |
| BASF |
| Metalor Technologies SA |
| Heraeus Holding |
| SAXONIA Edelmetalle GmbH |
| Others |
Value Chain & Pricing Dynamics
Captive precious metal refining capacity at scale anchors margin stability for integrated suppliers, compressing price floors for commodity distributors while elevating barriers for non-integrated formulators serving EPA-regulated US facilities and REACH-governed European job shops.
Pricing Analysis
Certification level creates the primary spread between qualified suppliers and commodity distributors, with IATF 16949 and AS9100 adherence commanding 15-25% premiums over uncertified alternatives. Three-tier pricing structure separates aerospace-grade formulations from automotive-qualified systems from economy-grade job shop chemicals. Pricing pressure stems from palladium salt cost volatility transmitted from automotive catalyst demand. Contract manufacturers in Shenzhen and Penang exhibit highest price sensitivity due to consolidated supplier scorecards, while aerospace tier-1 networks show lowest sensitivity given master service agreement renewal cycles.
Supply Chain Analysis
Strategic stockpiling of palladium salts prevails among automotive plating suppliers facing Russian supply uncertainty, while electronics manufacturers prefer just-in-time delivery from Hsinchu and Yongin packaging clusters. Raw material supply concentrates in South Africa and Russia for platinum group metals, China for gold salt precursors, and Germany for high-purity electrolyte additives. Single-source vulnerability runs through palladium sponge supply channels. Distribution feeds from integrated refiner-formulators through regional technical service centers to captive OEM plating lines and independent job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced packaging miniaturization is compressing plating bath lifecycles and accelerating reformulation velocity, creating high-growth disruption as 9-month qualification intervals favor suppliers with captive analytical laboratories over commodity distributors.
For Market Incumbents: Fortify backward integration into precious metal refining to buffer margin exposure from palladium price volatility. Deepen certification assets through AS9100 and IATF 16949 audit preparation services for downstream customers. Lock in multi-year technical partnerships with Taiwan and South Korea packaging foundries before competitor qualification cycles complete. For New Entrants and Emerging Players: Differentiate on cyanide-free formulation portfolios targeting European electronics OEMs under REACH substance dossier requirements. Target India's PLI scheme beneficiaries in Noida and Chennai EMS clusters lacking qualified local chemistry sources. Pursue toll-refining partnerships with German urban mining specialists to stabilize raw material cost structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated refiner-formulators with captive precious metal recovery operations and long-term master service agreements. Mid-tier formulators with IATF 16949 credentials and regional analytical laboratories represent prime acquisition targets. Watch hydrogen electrolyzer stack procurement announcements as inflection indicators for platinum-iridium coating demand outside traditional electronics verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metal Refining | Captive palladium and gold salt production buffers margin exposure from automotive catalyst demand competition. |
| Cyanide-Free Formulation Development | REACH-compliant portfolios unlock European electronics OEM specification sheets under ECHA substance dossier mandates. |
| Urban Mining Partnership Establishment | Toll-refining agreements with German precious metal recyclers stabilize raw material costs for mid-tier formulators. |
| Analytical Laboratory Capacity Expansion | On-site bath control capabilities satisfy Foxconn and Jabil supplier scorecards weighting technical service equally with pricing. |
| Hydrogen Electrolyzer Stack Qualification | Platinum-iridium coating specifications for proton exchange membrane manufacturers open industrial-scale demand channels. |
Study Parameters
Cross-validation between primary interviews with plating plant managers, OEM procurement leads at automotive sensor manufacturers, precious metal refinery technical directors, and EPA compliance officers anchors the qualitative findings against secondary validation from SEC 10-K filings, customs trade data, and ECHA substance dossier registrations. Bottom-up demand modeling from individual facility consumption patterns triangulates against top-down precious metal salt import flows.
Sensitivity analysis across metal price volatility scenarios, regulatory implementation timelines, and substitution elasticity parameters shapes the analytical framework over the projection horizon. Segmentation dimensions span formulation chemistry type, end-use industry vertical, certification tier, and regional production cluster. CAGRs derive from installed base expansion rates, content-per-unit trajectories in advanced packaging architectures, and hydrogen infrastructure buildout assumptions.
The analysis sits within stated boundaries; outcomes outside sustained palladium supply disruption or accelerated EPA zero-discharge enforcement would require recalibration. Forecasts reflect assumptions regarding qualification cycle durations, metal price correlation structures, and regulatory harmonization trajectories. Revision becomes warranted when hydrogen electrolyzer deployment crosses industrial-scale thresholds or when REACH substance restrictions expand beyond current cyanide-bearing formulation categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
US Methanol Market
Chemicals
Global Photoresist Chemicals Market
Chemicals
Lime Sulfur Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Muriatic Acid Market
Chemicals
Hexamine Market
Chemicals
Valeronitrile Market
Chemicals
Spirodiclofen Market
Chemicals
Potassium Alum Market
Chemicals
Methanol to Gasoline Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Global Amines Market
Chemicals
Maleic Acid Market
Chemicals
Potassium Hydrogen Fluoride Market