
 Aseptic Carton Bottles Market | 2026-2036
Aseptic Carton Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Carton Bottles Market Analytics
Food-grade barrier certification is collapsing the gap between conventional aseptic cartons and premium bottle formats. Tetra Pak leverages its laminated packaging heritage to anchor European dairy supply chains. SIG Combibloc competes through rotary filling systems that sustain high-output beverage contracts. Greatview Aseptic Packaging dominates Chinese domestic volume with regionally optimized paperboard formulations.
Aseptic carton bottles are multi-layer liquid containers combining paperboard substrates with polyethylene and aluminum barriers, sterilized through hydrogen peroxide or steam treatment before filling to achieve ambient shelf stability without preservatives. The primary purpose is extending distribution reach for heat-sensitive beverages, dairy, and liquid pharmaceuticals while minimizing refrigeration infrastructure. Composite containers lead material-efficient design among packaging types, while barrier solutions represent the fastest-growing segment as oxygen and light transmission specifications tighten. Unit packs anchor retail channel economics, though bulk packs for foodservice and institutional buyers command stronger per-unit margins through volume commitment structures.
FDA food contact notification rules and EU F-Gas Regulation phase-down mandates are reshaping sterilization technology selection and refrigerant-dependent cold chain requirements across North American and European operations. China's SAMR enforces GB standards for composite food packaging migration limits, creating compliance differentiation between domestic and export-oriented manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as post-consumer carton collection infrastructure and recycling certification become decisive factors in brand procurement decisions.
Market Dynamics
EU Green Deal packaging waste directives are forcing dairy processors across Germany and France to replace conventional refrigerated distribution with ambient-stable aseptic carton bottle formats, compressing capital deployment timelines and reshaping supplier qualification criteria.
Growth Catalysts
- EU Green Deal Packaging Directives:Extended producer responsibility frameworks in Germany and France mandate recyclable mono-material structures, accelerating pulp-based barrier adoption for extended-shelf-life milk applications.
- Yangtze River Delta Manufacturing Cluster:China's domestic pulp-based barrier technology is displacing imported multi-layer structures, concentrating demand in food manufacturing hubs around Shanghai and Jiangsu province.
- Hydrogen Peroxide Sterilization:FDA food contact notification rules favor vapor-phase hydrogen peroxide systems over legacy steam methods, enabling faster line changeovers for heat-sensitive beverage processors.
Market Restraints
- Aluminum Barrier Supply Concentration:Thin-gauge aluminum foil for oxygen barriers concentrates among a limited supplier base in Western Europe, creating input cost volatility and qualification bottlenecks for new entrants.
- F-Gas Phase-Down Mandates:EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants complicate cold chain-dependent legacy dairy infrastructure, forcing parallel investment in ambient distribution networks.
- Polyethylene Copolymer Technical Limitations:Current food-grade polyethylene adhesives exhibit migration threshold constraints under China's GB standards, limiting high-temperature fill applications for export-oriented manufacturers.
Strategic Opportunities
- Underpenetrated Indian Dairy Sector:India's FSSAI enforcement of composite food packaging standards creates first-mover advantage for aseptic carton bottle suppliers targeting ambient distribution of flavored milk and lassi products.
- Liquid Pharmaceuticals:Sterile intravenous solutions and ophthalmic preparations represent an emerging application where aseptic carton bottles displace glass vials through reduced breakage and logistics cost compression.
- Rotary Filling System Convergence:Integration of hydrogen peroxide sterilization modules with high-speed rotary fillers enables beverage contracts above 30,000 units per hour, opening foodservice bulk pack channels.
Industry Challenges
- Barrier Migration Testing Expertise:Certification timelines for GB standards compliance in China require specialized analytical chemistry capabilities that concentrate among third-party laboratories in Shanghai and Beijing, extending product launch cycles.
- Post-Consumer Collection Infrastructure:Extended producer responsibility frameworks in multiple jurisdictions demand investment in carton-specific recycling streams, yet collection density varies sharply between urban and rural distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Carton Bottles Market |
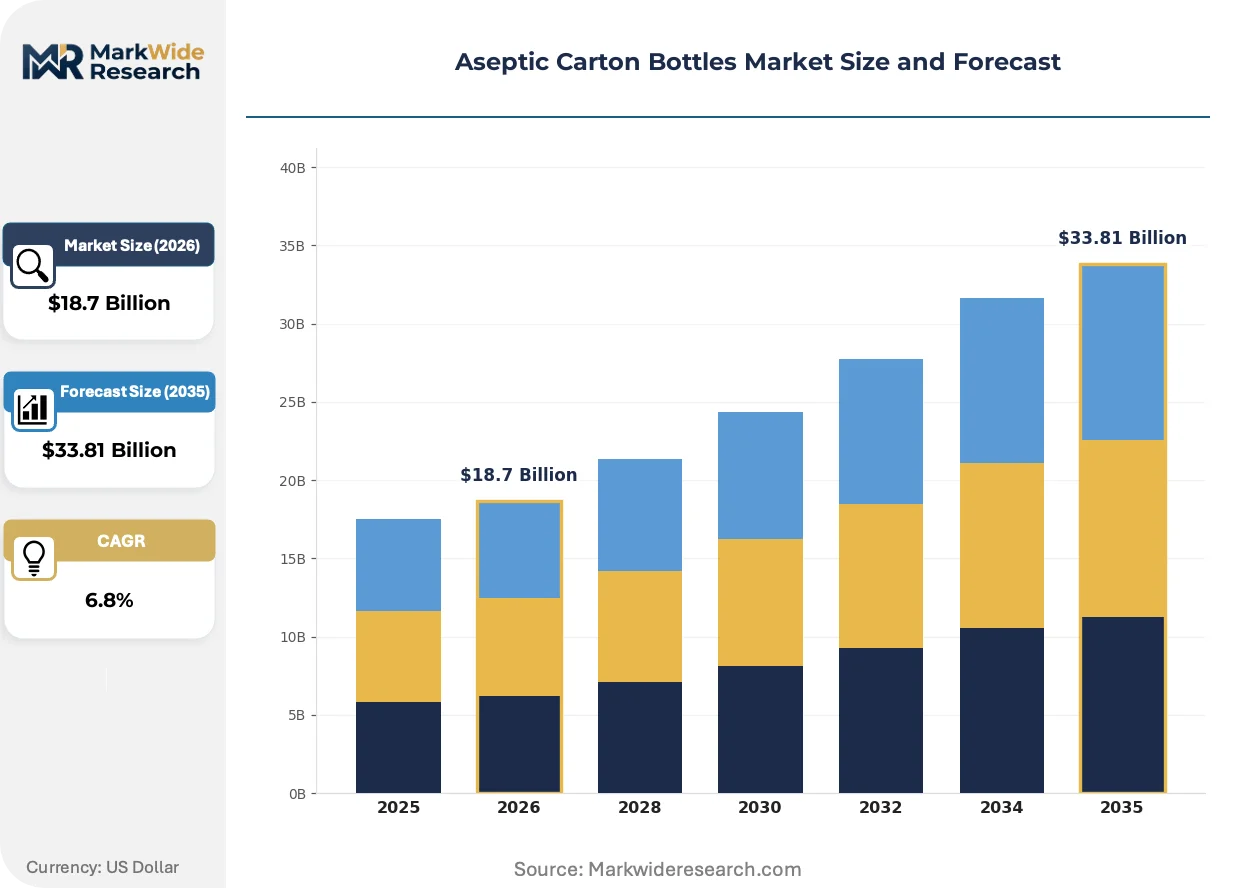
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Bottles, Composite Containers, Barrier Solutions, Multi-layer Cartons Material: Pulp, Polyethylene, Aluminum, Paperboard End User: Beverage Industry, Dairy Sector, Food Processing, Pharmaceuticals Packaging Type: Unit Packs, Bulk Packs, Retail Packs, Custom Packs |
| Companies Covered | Tetra Pak, SIG Combibloc, Elopak, Greatview Aseptic Packaging, Amcor, Nippon Paper Industries, Mondi, DS Smith, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Carton Bottles Market Evolving Landscape
Pulp-based barrier technology is actively fragmenting competitive positioning between European laminated packaging heritage and Chinese domestic formulation capabilities, with sterilization method selection becoming a decisive technical differentiator.
Aluminum-free barrier coatings are bifurcating the oxygen transmission specification market. Food-grade ethylene vinyl alcohol copolymers and silicon oxide vapor-deposited films now achieve sub-0.1 cc/m²/day oxygen permeability. Premium organic juice and plant-based beverage brands in Germany and France are adopting these structures to meet EU Green Deal recyclability targets. This technology is compressing aluminum foil demand in sub-500ml retail formats while reinforcing aluminum's position in bulk institutional packs.
REACH authorization requirements for hydrogen peroxide sterilization residuals are tightening migration limit enforcement across European dairy operations. Industrial consequence includes accelerated validation protocols for vapor-phase concentration monitoring systems. Extended-shelf-life milk processors in Bavaria and Normandy are most affected, responding through inline spectroscopic detection equipment upgrades to maintain EFSA compliance margins.
Buyers are consolidating supplier relationships around integrated barrier-filling system providers. Regional dairy cooperatives in China's Yangtze River Delta are displacing discrete component procurement with single-source packaging line contracts. This pattern is most visible in Jiangsu province, where domestic pulp-based barrier manufacturers now bundle rotary filling equipment to capture multi-year volume commitments from emerging plant-based beverage brands.
Aseptic Carton Bottles Market Segmentation
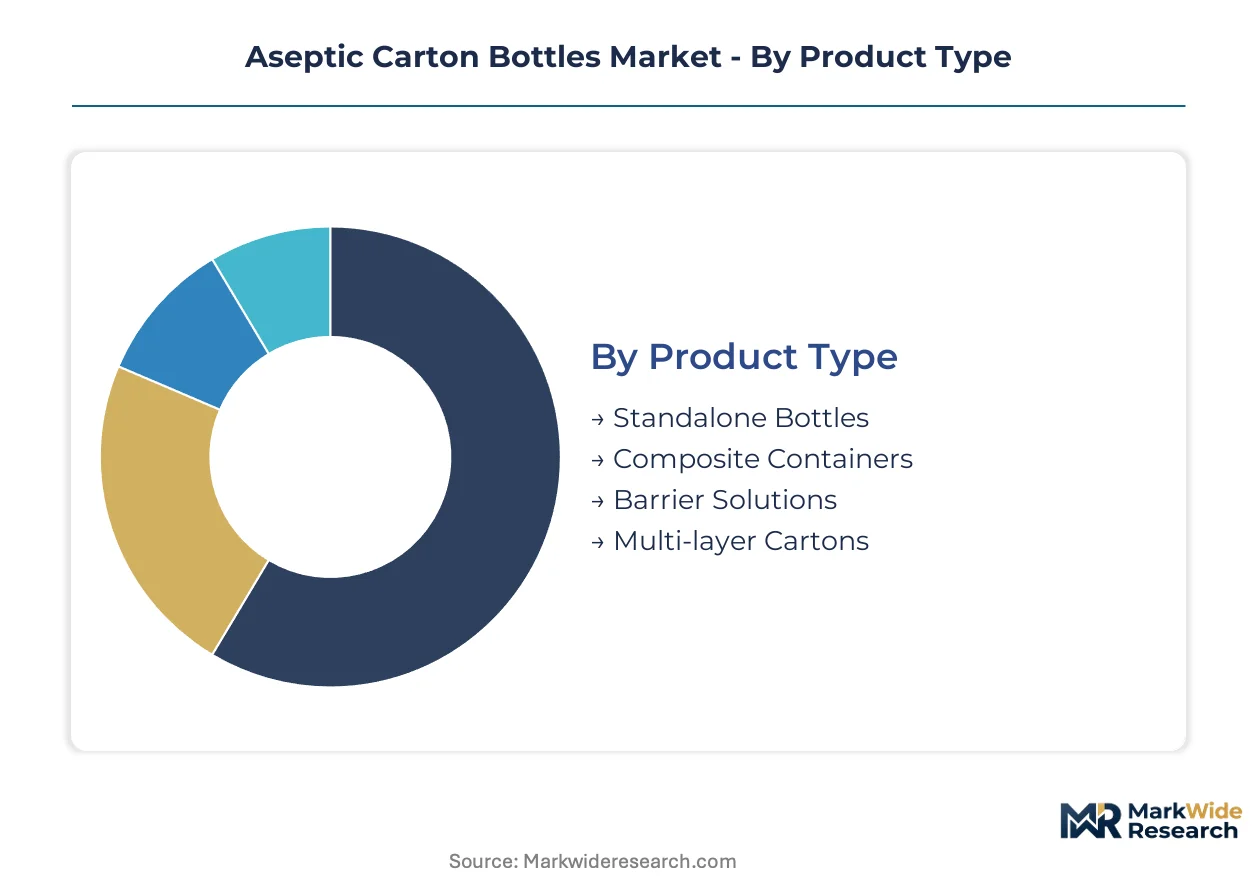
Segmentation in aseptic carton bottles reveals how material choices and packaging formats determine sterilization compatibility, shelf-life performance, and regulatory compliance across dairy, beverage, and pharmaceutical applications. Product architecture decisions directly constrain barrier technology selection and filling line investment.
Product Type:
Composite containers face the strongest substitution pressure from aluminum-free barrier coatings, while standalone bottles compete against conventional PET and glass formats in premium beverage positioning.
- Composite Containers:Multi-layer structures combining paperboard substrates with polyethylene and aluminum barriers achieve the tightest oxygen transmission specifications. Dairy processors in Bavaria and Normandy deploy these for extended-shelf-life milk under EFSA migration limits enforced through inline spectroscopic detection.
- Barrier Solutions:Ethylene vinyl alcohol copolymers and silicon oxide vapor-deposited films now achieve sub-0.1 cc/m²/day oxygen permeability without aluminum. German and French organic juice brands adopt these structures to meet EU Green Deal recyclability targets for sub-500ml retail formats.
- Standalone Bottles:Single-structure pulp-based formats optimized for hydrogen peroxide sterilization in China's Yangtze River Delta manufacturing cluster.
- Multi-layer Cartons:Conventional laminated packaging heritage formats with polyethylene-aluminum-paperboard sequencing for ambient distribution networks.
Composite containers anchor the volume base while barrier solutions gain share at the steepest rate.
Material:
Cost tier differentiation separates commodity pulp formulations from specialized barrier polymers and thin-gauge aluminum supply concentrated in Western Europe.
- Pulp:Regionally optimized paperboard formulations from domestic Chinese manufacturers displace imported multi-layer structures in Jiangsu province food manufacturing hubs. Yangtze River Delta dairy cooperatives bundle rotary filling equipment with pulp-based barrier contracts.
- Aluminum:Thin-gauge foil for oxygen barriers concentrates among limited Western European suppliers, creating input cost volatility and qualification bottlenecks. Bulk institutional packs above 500ml retain aluminum-dependent specifications.
- Polyethylene:Food-grade copolymers face migration threshold constraints under China's GB standards, limiting high-temperature fill applications.
- Paperboard:Structural substrate for all laminated formats, with certification timelines varying by SAMR compliance requirements.
Pulp dominates procurement volumes for domestic Chinese supply chains while aluminum commands premium positioning in export-oriented European dairy infrastructure.
End User:
Application maturity varies sharply, with pharmaceuticals representing emerging displacement of glass vials while dairy and beverage sectors drive current capacity deployment.
- Dairy Sector:Extended-shelf-life milk processors across Germany and France replace conventional refrigerated distribution with ambient-stable formats. EU Green Deal packaging waste directives compress capital deployment timelines and reshape supplier qualification criteria.
- Beverage Industry:Plant-based beverage brands and organic juice processors adopt aluminum-free barriers for recyclability certification. Hydrogen peroxide sterilization enables faster line changeovers for heat-sensitive formulations.
- Pharmaceuticals:Sterile intravenous solutions and ophthalmic preparations emerge as glass vial alternatives through reduced breakage and logistics cost compression.
- Food Processing:Liquid food applications including sauces and soups requiring ambient stability without preservative addition.
Dairy anchors installed filling capacity while pharmaceuticals expand most quickly as regulatory pathways for composite packaging mature.
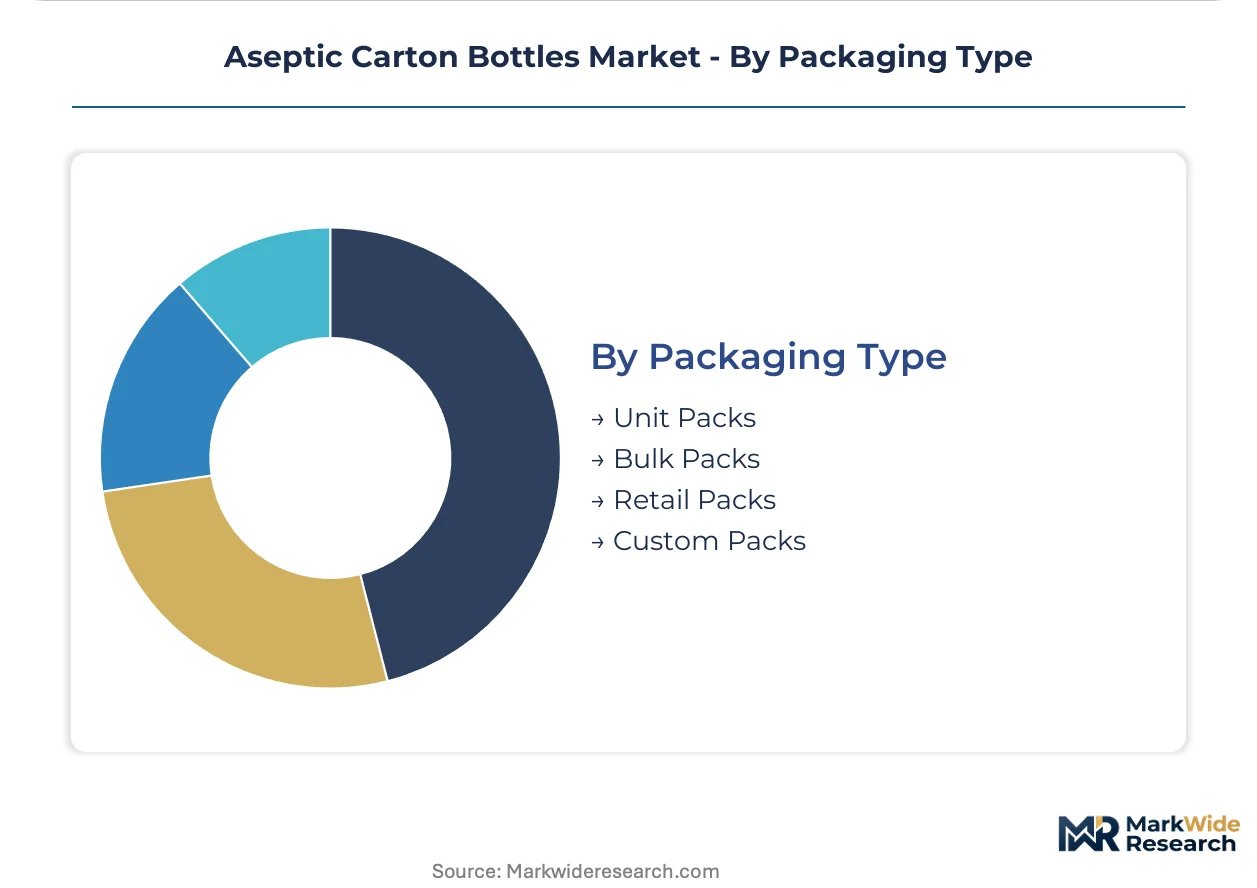
Packaging Type:
Volume scale separates retail channel economics from foodservice margin structures tied to commitment-based contracting.
- Unit Packs:Sub-500ml retail formats dominate consumer-facing shelf presence. Aluminum-free barrier adoption concentrates here as German and French brands pursue EU Green Deal recyclability targets.
- Bulk Packs:Foodservice and institutional channels command stronger per-unit margins through multi-year volume commitments. Rotary filling systems above 30,000 units per hour enable this segment.
- Retail Packs:Multi-unit configurations for club store and supermarket distribution.
- Custom Packs:Specification-driven formats for pharmaceutical and specialized food applications.
Unit packs structure competitive positioning around barrier certification while bulk packs capture margin through equipment-integrated supply contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in aseptic carton bottles tilt toward surplus in Chinese manufacturing clusters while European dairy processors absorb technology imports to meet regulatory compliance deadlines. Germany and France remain net importers of barrier film components despite finished packaging exports to neighboring markets.
China
Yangtze River Delta food manufacturers deploy domestic pulp-based barriers at scale for extended-shelf-life dairy and plant-based beverages. SAMR enforces GB standards for composite food packaging migration limits, creating compliance differentiation between domestic and export-oriented producers. Shanghai and Jiangsu province concentrate rotary filling system integration contracts that bundle equipment with multi-year pulp supply agreements.
Germany
Bavarian dairy cooperatives retrofit refrigerated distribution networks with ambient-stable aseptic carton bottle lines under EU Green Deal packaging waste directives. EFSA migration limit enforcement through REACH authorization requirements accelerates inline spectroscopic detection equipment upgrades. The Baden-Württemberg industrial corridor hosts thin-gauge aluminum foil qualification facilities serving barrier film converters across Central Europe.
France
Normandy extended-shelf-life milk processors compress capital deployment timelines to meet recyclability mandates for mono-material structures. ANSM pharmaceutical packaging standards open regulatory pathways for sterile intravenous solutions in composite containers. The Île-de-France region concentrates organic juice brand headquarters adopting aluminum-free barrier coatings for sub-500ml retail formats.
India
FSSAI enforcement of composite food packaging standards creates first-mover positioning for ambient distribution of flavored milk and lassi products in Maharashtra and Gujarat. DGFT import tariff structures on barrier film equipment shape domestic machinery sourcing decisions. Karnataka's Bangalore-Tumkur food processing belt attracts pilot aseptic carton bottle installations for regional dairy cooperatives.
United States
FDA food contact notification rules favor vapor-phase hydrogen peroxide sterilization systems in California and Wisconsin dairy operations. EPA refrigerant phase-down schedules under SNAP program accelerate parallel investment in ambient distribution networks. The Pacific Northwest pulp and paperboard supply base feeds barrier substrate demand from beverage processors seeking domestic sourcing alternatives.
Aseptic Carton Bottles Market Competitive Landscape
Concentration sits with integrated barrier-filling system providers that bundle rotary equipment with multi-year material supply contracts. Three structural tiers separate heritage laminated packaging specialists from domestic Chinese pulp formulators and diversified multinational converters. Strategic moves center on regional manufacturing footprint expansion and technology licensing partnerships that transfer sterilization module specifications to local equipment fabricators.
Among heritage European specialists, Tetra Pak and SIG Combibloc exemplify the integrated system archetype through their laminated packaging lineage and rotary filling heritage. Greatview Aseptic Packaging occupies a position within the domestic Chinese tier, representing regional optimization of paperboard formulations and supply chain proximity to Yangtze River Delta manufacturing clusters. These three anchors illustrate how competitive positioning fragments between technology-licensing heritage players and regionally embedded volume suppliers.
| Leading Market Players |
|---|
| Tetra Pak |
| SIG Combibloc |
| Elopak |
| Greatview Aseptic Packaging |
| Amcor |
| Nippon Paper Industries |
| Mondi |
| DS Smith |
| WestRock Company |
| Others |
Value Network & Pricing Analysis
Multi-year equipment-bundling contracts from Yangtze River Delta dairy cooperatives lock in pulp-based barrier supply access and flatten price volatility for domestic Chinese manufacturers while compressing margin visibility for imported multi-layer structure suppliers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the aseptic carton bottle market. Premium tiers command aluminum-dependent composite containers with sub-0.1 cc/m²/day oxygen permeability for EU dairy export certification, while economy tiers serve domestic Chinese volume through pulp-based standalone formats. Cost compression in standard-tier polyethylene copolymer adhesives is intensifying because GB standards migration testing concentrates among Shanghai and Beijing third-party laboratories. Foodservice bulk pack buyers exhibit lowest price sensitivity due to rotary filling equipment lock-in, whereas emerging plant-based beverage brands in Jiangsu province drive hardest volume negotiation.
Supply Chain Analysis
Thin-gauge aluminum foil qualification bottlenecks in Western Europe's limited supplier base concentrate oxygen barrier input costs and extend new entrant validation timelines for extended-shelf-life dairy processors. Raw material flows draw from Chinese domestic pulp formulations, German polyethylene copolymer specialists, and French aluminum rolling capacity. Single-source vulnerability in vapor-phase hydrogen peroxide sterilization module fabrication elevates risk for Bavarian and Normandy retrofit projects. Distribution runs through integrated barrier-filling system providers that bundle rotary equipment with multi-year material commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aseptic carton bottle market represents high-growth disruption as EU Green Deal packaging waste directives force ambient-stable format conversion across refrigerated dairy infrastructure.
For Market Incumbents: Shield laminated packaging heritage through captive supply of thin-gauge aluminum foil qualification capacity in the Baden-Württemberg corridor. Deepen backward integration into hydrogen peroxide sterilization module fabrication to offset rotary filling equipment bundling pressure from Chinese pulp-based barrier manufacturers. Aluminum-free coating substitution threats from German organic juice brands demand accelerated EVOH and silicon oxide vapor-deposition R&D investment. For New Entrants and Emerging Players: Post-consumer carton collection infrastructure gaps in rural Indian distribution networks present white-space targeting for FSSAI-compliant ambient dairy formats. Maharashtra and Gujarat flavored milk cooperatives remain underpenetrated by integrated system providers. Karnataka's Bangalore-Tumkur belt offers pilot installation leverage through regional dairy cooperative relationships without incumbent equipment lock-in. For Investors and Strategic Acquirers: Domestic Chinese pulp formulators with SAMR GB standards compliance capabilities and bundled rotary filling integration contracts represent the priority acquisition archetype. Long-term viability hinges on aluminum barrier displacement velocity and pharmaceutical packaging regulatory pathway maturation. Monitor ANSM sterile intravenous solution composite container approvals as inflection signal for glass vial substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Barrier Substrate | Yangtze River Delta manufacturers capture margin from imported multi-layer displacement under SAMR enforcement. |
| Hydrogen Peroxide Sterilization Module Licensing | European dairy processors accelerate Bavarian and Normandy line retrofits under REACH authorization timelines. |
| Aluminum-Free Barrier Coating Scale-Up | German and French organic juice brands meet EU Green Deal recyclability targets for sub-500ml retail formats. |
| Rotary Filling System Convergence | Jiangsu province cooperatives bundle equipment with multi-year pulp supply for plant-based beverage contracts. |
| Pharmaceutical Packaging Regulatory Pathway | ANSM sterile intravenous standards open composite container displacement of glass vial logistics costs. |
Research Methodology
Operator-level perspectives from dairy processing engineers, rotary filling equipment procurement leads, barrier film technical directors, and SAMR compliance specialists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through EU F-Gas Regulation implementation tracking, FDA food contact notification filings, and Chinese GB standards migration limit databases. Bottom-up volume modeling from equipment installation records and top-down cross-check against pulp and aluminum trade flows ensured triangulation integrity.
Sensitivity analysis across sterilization technology selection, aluminum barrier substitution rates, and extended producer responsibility framework adoption patterns shaped the analytical framework. Segmentation dimensions modeled include product architecture, barrier material composition, end-use application maturity, and packaging format scale. CAGRs were derived from installed base expansion rates and replacement cycle compression under regulatory deadline pressure, with hydrogen peroxide sterilization adoption curves and pharmaceutical packaging certification timelines as key forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal implementation, FDA food contact notification enforcement, and SAMR GB standards migration limits; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down schedules and aluminum-free barrier coating technical validation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market