
 Aseptic Formulation Processing Market | 2026-2036
Aseptic Formulation Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Formulation Processing Market Outlook
Single-use polymer systems are hardening as the preferred contact material over stainless steel in multi-product biologics suites. STERIS Corporation leverages its sterilization expertise to anchor integrated processing lines for vaccine manufacturers. GEA Group sustains technology leadership through advanced isolator engineering that reduces contamination risk during filling operations. Syntegon Technology competes aggressively on robotic aseptic filling platforms that eliminate human intervention in critical zones.
Aseptic formulation processing encompasses the sterile preparation, filling, and sealing of pharmaceutical products under conditions that exclude microbial contamination, typically requiring ISO 5 environments with HEPA-filtered laminar airflow and validated sterilization-in-place protocols. The primary purpose is to deliver injectable and biologic therapies with absolute sterility assurance, where any microbial breach renders entire batches unusable. Pre-filled syringes command the strongest margin pools as chronic self-administration therapies expand, while isolator technology outpaces cleanroom construction on growth rates due to faster validation timelines and lower facility retrofit costs. Robotic systems within filling machines are capturing the fastest expansion trajectory as manufacturers pursue closed, gloveless operations for high-potency compounds.
FDA's sterile drug guidance and EMA's Annex 1 revision are tightening particulate and bioburden limits, forcing capital redeployment into validated isolator infrastructure. The EU GMP Annex 1 requirements for continuous viable and non-viable monitoring are reshaping equipment procurement specifications across European contract manufacturing organizations. China's NMPA alignment with PIC/S standards is accelerating domestic upgrade cycles for filling line automation. Stakeholders must weigh isolator-versus-cleanroom capital commitments against portfolio flexibility as multi-product biologics facilities become the dominant manufacturing model.
Market Dynamics
Isolator-based processing is displacing conventional cleanroom infrastructure as biologics manufacturers confront sterility assurance failures and faster facility validation demands. This shift concentrates capital deployment decisions around gloveless robotic filling lines and closed-system architecture.
Growth Catalysts
- FDA Sterile Drug Guidance:Tightened particulate limits are compelling vaccine manufacturers to retrofit filling suites with validated isolator enclosures. This regulatory pressure accelerates equipment replacement cycles across United States contract manufacturing organizations.
- Monoclonal antibody pipeline expansion:Chronic therapy administration is driving demand for pre-filled syringe formats that require specialized aseptic filling capabilities. Biologics developers are scaling sterile capacity to match clinical-stage molecule progression.
- Single-use polymer adoption:Multi-product biologics facilities favor disposable contact surfaces over stainless steel to eliminate cross-contamination risk. This material transition reduces cleaning validation burden and enables faster product changeovers.
Market Restraints
- Specialized fluoropolymer supply concentration:High-purity polymer membranes for isolator gloves and single-use assemblies depend on limited Japanese and German chemical suppliers. Input scarcity extends lead times for critical barrier components.
- EMA Annex 1 compliance friction:Continuous viable monitoring mandates impose sensor integration costs that strain mid-tier contract manufacturers. Smaller European facilities face capital constraints meeting real-time environmental surveillance requirements.
- Stainless steel residual preference:High-volume commercial biologics with established cleaning validation protocols resist polymer conversion due to sunk infrastructure costs. Legacy equipment depreciation schedules delay material transition timelines.
Strategic Opportunities
- Chinese domestic biologics manufacturing:NMPA alignment with PIC/S standards is accelerating upgrade demand for automated filling lines among domestic vaccine and biosimilar producers. Local equipment vendors lack advanced isolator engineering expertise.
- Cell therapy personalized manufacturing:Patient-specific autologous therapies require modular, small-batch aseptic processing capabilities distinct from traditional blockbuster-scale infrastructure. This application demands flexible isolator configurations with rapid batch turnaround.
- Robotic-gloveless convergence:Integration of collaborative robotics with isolator technology eliminates human intervention in critical zones. This convergence enables processing of high-potency oncology compounds with enhanced operator safety.
Industry Challenges
- Aseptic processing engineering talent scarcity:Qualified specialists capable of integrating isolator, robotics, and continuous monitoring systems command premium compensation. Training programs lag behind equipment complexity advancement.
- Legacy cleanroom retrofit complexity:Existing facilities face structural constraints installing isolator lines without complete HVAC reconfiguration. Building infrastructure limitations force greenfield construction decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Formulation Processing Market |
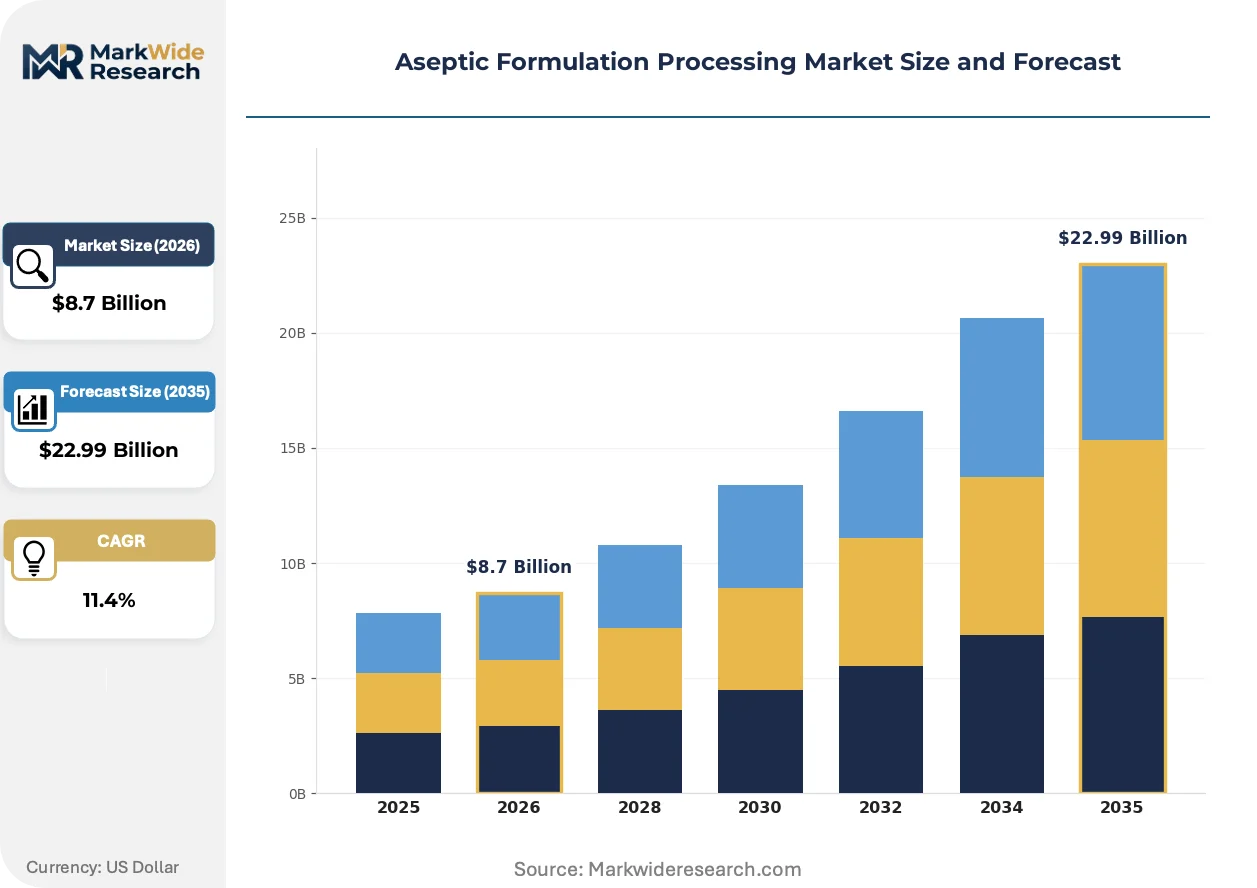
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-filled Syringes, Vials, Ampoules, IV Bags Technology: Robotic Systems, Isolators, Cleanroom Technology, Filling Machines Application: Injectables, Biologics, Vaccines, Hormones End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Biotechnology Firms, Research Institutions |
| Companies Covered | STERIS Corporation, GEA Group, IMA Group, Syntegon Technology, Getinge, Sartorius AG, Robert Bosch Packaging Technology, Bausch+Strobel, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Formulation Processing Market Strategic Shifts
Closed-system architecture is compressing contamination risk profiles while accelerating validation timelines for multi-product biologics facilities. Equipment specifications now prioritize modularity and rapid reconfiguration over fixed-line throughput optimization.
Magnetic levitation pump technology is electrifying aseptic fluid transfer by eliminating mechanical seals and bearing surfaces that generate particulate contamination. Cell therapy manufacturers are adopting these pumps for shear-sensitive biologic handling where conventional peristaltic systems degrade product quality. This technology is electrifying competitive differentiation among isolator-integrated processing lines by enabling gentler product movement with reduced maintenance intervention.
EMA's revised Annex 1 requirements for continuous viable and non-viable environmental monitoring are mandating sensor density increases across European filling operations. Pharmaceutical manufacturers must deploy real-time particle counters and active air sampling systems with automated alert protocols. Contract manufacturing organizations in Germany and Switzerland are restructuring facility layouts to accommodate centralized monitoring infrastructure before regulatory inspection deadlines.
Biologics developers are consolidating procurement authority for aseptic filling services among fewer strategic contract manufacturing partners with proven isolator capabilities. This concentration favors large-scale organizations with validated multi-product suites over smaller regional players. The United States exhibits the most pronounced buyer consolidation as sponsors prioritize partners with FDA pre-approval inspection histories and established biologics portfolios.
Aseptic Formulation Processing Market Segmentation
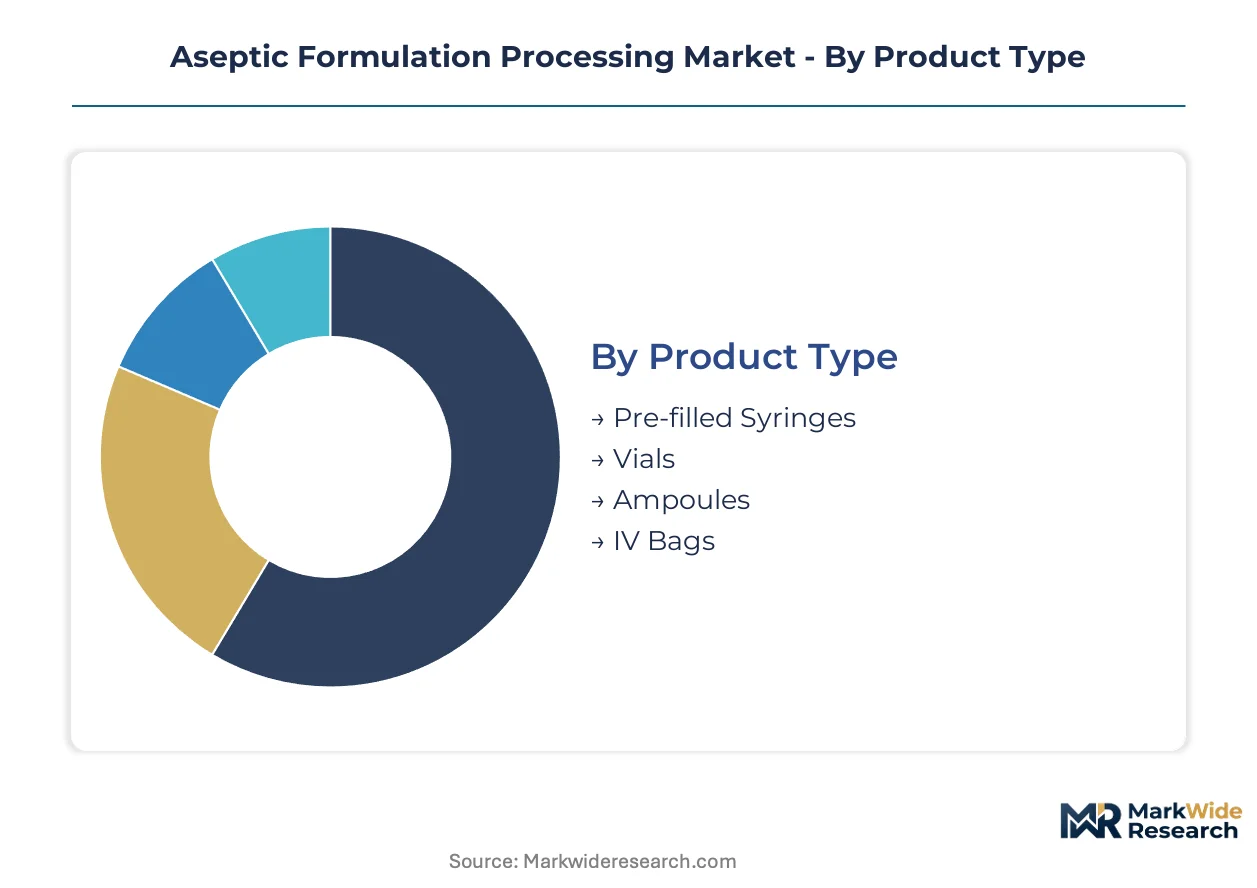
Aseptic formulation processing equipment varies dramatically by product containment format, automation technology, and therapeutic application. Procurement decisions hinge on sterility assurance requirements, batch scale, and regulatory jurisdiction complexity.
Product Type:
Supply concentration in pre-filled syringe component molding favors integrated filling line vendors with captive polymer sourcing.
- Pre-filled Syringes:Glass-barrel and polymer-barrel formats with integrated needle safety systems. Demand concentrates among United States biologics developers launching chronic self-administration therapies for rheumatoid arthritis and diabetes, where patient compliance drives format preference over traditional vials.
- Vials:Borosilicate glass or cyclic olefin polymer containers sealed with elastomeric stoppers and aluminum crimps. High-volume monoclonal antibody commercialization in Germany and Switzerland sustains vial dominance despite slower fill speeds versus syringe lines.
- Ampoules:Single-dose glass containers with flame-sealed necks, primarily for emergency injectables and anesthetics.
- IV Bags:Large-volume parenteral containers for infusion therapies, requiring specialized peristaltic filling and port-sealing equipment.
Today's leader: Vials. Tomorrow's challenger: Pre-filled Syringes.
Technology:
Cost tier stratification separates validated isolator platforms from legacy cleanroom retrofits, with robotic systems commanding premium positioning.
- Robotic Systems:Collaborative and SCARA robots executing gloveless filling, capping, and inspection operations within closed isolator enclosures. Cell therapy manufacturers in Boston and San Francisco adopt these systems for high-potency oncology compounds where operator exposure limits mandate zero human intervention.
- Isolators:Rigid-barrier enclosures with unidirectional HEPA-filtered airflow and vaporized hydrogen peroxide decontamination cycles. EMA Annex 1 compliance deadlines in Germany, France, and Italy accelerate isolator deployment over conventional cleanroom infrastructure.
- Cleanroom Technology:ISO 5-8 classified spaces with laminar flow hoods and personnel garbing protocols, now relegated to secondary packaging and non-critical operations.
- Filling Machines:Rotary piston, peristaltic, and time-pressure dosing systems integrated with upstream formulation tanks and downstream inspection stations.
Isolators dominate current procurement volumes. Robotic systems are expanding most quickly.
Application:
Volume concentration in injectable generics contrasts with margin concentration in complex biologics requiring specialized cold-chain handling.
- Biologics:Monoclonal antibodies, recombinant proteins, and fusion molecules requiring low-shear filling and strict temperature control. United States and Chinese facilities scale capacity to match pipeline progression from clinical to commercial stages.
- Vaccines:Live-attenuated, inactivated, and mRNA formulations with adjuvant compatibility requirements. Domestic manufacturing mandates in India and Brazil drive regional filling line installation.
- Injectables:Small-molecule parenterals including antibiotics, anesthetics, and emergency cardiovascular therapies.
- Hormones:Peptide and steroid formulations with potency handling constraints and specialized containment needs.
Biologics command the steepest expansion trajectory. Vaccines offer volume stability.
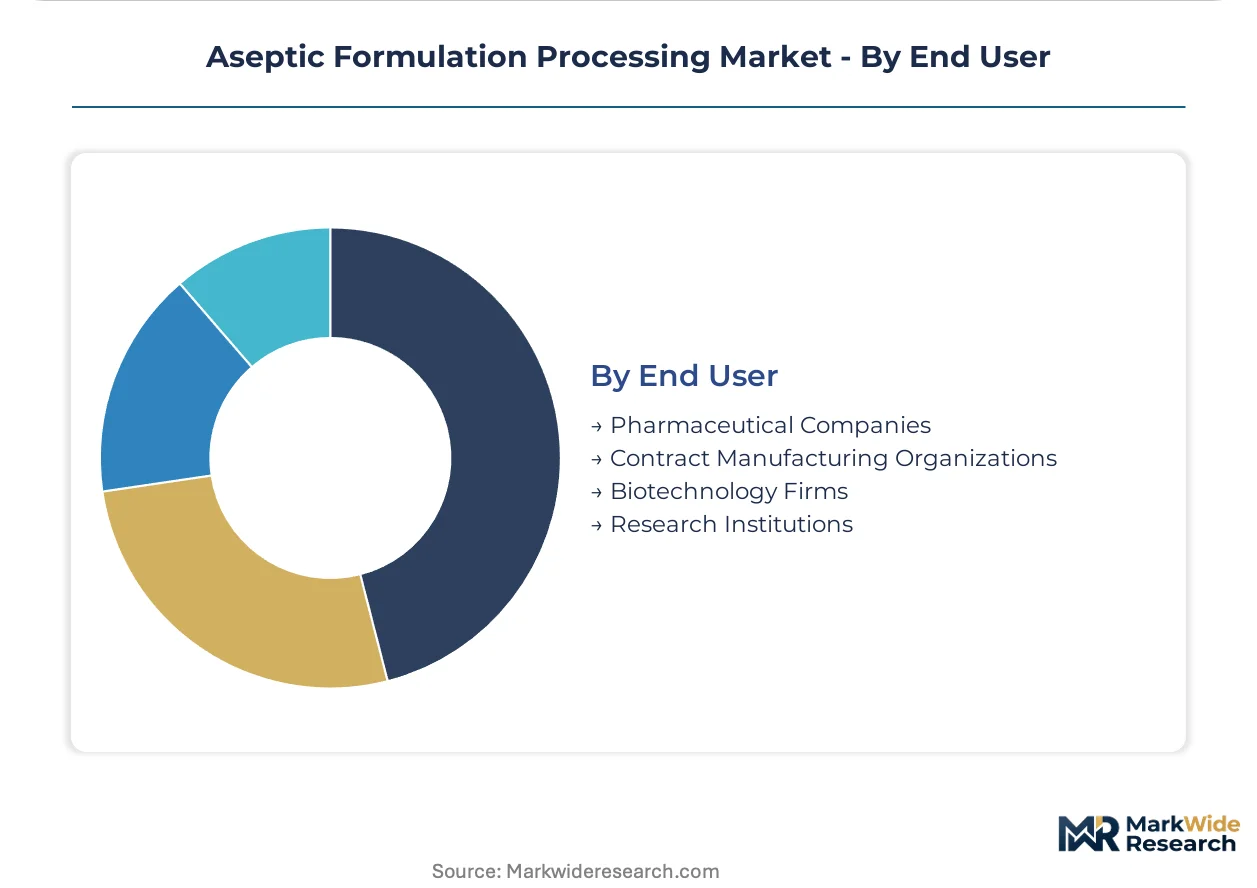
End User:
Customer type determines equipment specification complexity, with pharmaceutical companies demanding multi-product flexibility and CMOs prioritizing rapid changeover capability.
- Contract Manufacturing Organizations:Multi-tenant facilities serving diverse sponsor portfolios with validated isolator suites and single-use polymer systems. European CMOs in Germany, Switzerland, and Ireland consolidate market share through FDA and EMA dual-inspection histories.
- Pharmaceutical Companies:Captive manufacturing operations for blockbuster molecules with dedicated high-throughput lines and established stainless steel cleaning validation protocols.
- Biotechnology Firms:Emerging developers with clinical-stage assets requiring flexible, small-batch isolator configurations and rapid scale-up pathways.
- Research Institutions:Academic and government laboratories with early-phase formulation development and limited GMP production needs.
Contract Manufacturing Organizations lead equipment procurement volumes. Biotechnology firms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor concentrates North American demand for isolator-based aseptic processing equipment. FDA sterile drug guidance revisions are accelerating capital redeployment toward validated robotic filling lines across United States contract manufacturing networks.
United States
Monoclonal antibody commercialization and cell therapy manufacturing expansion drive equipment procurement in Massachusetts, North Carolina, and California clusters. FDA's tightened particulate limits under sterile drug guidance compel vaccine manufacturers toward isolator retrofits. Greater Boston biotechnology firms are scaling gloveless robotic filling capacity for high-potency oncology compounds.
Germany
High-volume monoclonal antibody production and established biologics contract manufacturing sustain vial filling line dominance in Baden-Württemberg and Bavaria. EMA Annex 1 continuous monitoring mandates force sensor integration investments across Rhine-Main pharmaceutical corridors. Heidelberg and Stuttgart equipment vendors are engineering advanced isolator enclosures for European CMO compliance deadlines.
China
Domestic vaccine and biosimilar manufacturing scale-up is propelling automated filling line demand in Jiangsu and Zhejiang provinces. NMPA alignment with PIC/S standards accelerates upgrade cycles among domestic producers lacking advanced isolator engineering expertise. Shanghai and Suzhou biologics parks are attracting foreign equipment vendors for technology transfer partnerships.
Switzerland
Specialized biologics manufacturing and high-value injectable production concentrate aseptic processing investment in Basel and Zurich regions. Swissmedic requirements for environmental monitoring systems reshape procurement specifications among contract manufacturers. The Basel pharmaceutical cluster is consolidating multi-product isolator suites for international sponsor portfolios.
India
Injectable generics export manufacturing and emerging biosimilar production drive filling line installation in Maharashtra and Telangana. CDSCO quality enforcement is raising barrier-to-entry for regional equipment suppliers lacking validated isolator platforms. Hyderabad and Mumbai CMO corridors are retrofitting cleanroom infrastructure to meet FDA pre-approval inspection standards.
Aseptic Formulation Processing Market Competitive Environment
Isolator technology licensing dominates the current landscape as equipment vendors race to anchor integrated processing lines. The vendor base stratifies across three tiers: multinational automation conglomerates with sterilization expertise, specialized German engineering houses with precision filling heritage, and emerging Asian fabricators competing on cost-adjusted delivery timelines. Strategic archetypes include sterilization-anchored integrators, precision mechanics specialists, and robotic platform developers. Capacity expansion and technology licensing represent the dominant competitive vectors as manufacturers confront EMA Annex 1 compliance deadlines.
Within the sterilization-anchored integrator tier, STERIS Corporation exemplifies equipment vendors leveraging contamination control expertise to capture vaccine manufacturer procurement. Among German precision engineering houses, GEA Group and Sartorius AG occupy positions reflecting advanced isolator and single-use system specialization. Syntegon Technology represents the robotic platform developer archetype, with its name signaling automated filling system orientation. These three anchors illustrate how competitive positioning concentrates around regulatory compliance capability rather than throughput metrics alone.
| Leading Market Players |
|---|
| STERIS Corporation |
| GEA Group |
| IMA Group |
| Syntegon Technology |
| Getinge |
| Sartorius AG |
| Robert Bosch Packaging Technology |
| Bausch+Strobel |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
EMA Annex 1 compliance deadlines for continuous viable monitoring are forcing European contract manufacturers toward premium-priced isolator retrofits, compelling equipment vendors to absorb fluoropolymer input inflation or risk losing procurement decisions to validated competitors with captive polymer sourcing.
Pricing Analysis
Specialized fluoropolymer membrane costs pass through directly to isolator glove and single-use assembly pricing, with Japanese and German chemical suppliers commanding premium positioning. Pricing stratifies across FDA-validated premium tiers, EMA-compliant standard tiers, and emerging-economy economy tiers lacking dual-inspection histories. Cost compression in mid-tier European CMOs is intensifying because EMA Annex 1 sensor integration mandates strain capital budgets. Biotechnology firms exhibit highest price sensitivity due to clinical-stage funding constraints, while large pharmaceutical companies prioritize sterility assurance over unit economics.
Supply Chain Analysis
Freight costs for precision-engineered isolator enclosures from Germany and Switzerland to United States biologics clusters add material landed-cost premiums versus domestic Asian fabrication. High-purity polymer membranes draw from concentrated Japanese and German specialty chemical producers, with stainless steel components sourcing from Italian and Chinese metalwork specialists. Single-source vulnerability in fluoropolymer supply creates extended lead-time exposure for critical barrier components. Distribution runs through direct vendor-to-manufacturer relationships for validated equipment, with aftermarket service contracts anchoring long-term revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage favors equipment vendors establishing Chinese assembly partnerships to capture NMPA-aligned domestic demand while maintaining European engineering centers for EMA Annex 1 compliance credibility, exploiting the cost differential between Basel-precision labor and Jiangsu manufacturing wages.
For Market Incumbents: Cement isolator technology leadership through backward integration into fluoropolymer membrane production, eliminating Japanese supplier dependency that threatens margin stability. Acquire validated European CMOs with FDA pre-approval inspection histories before EMA Annex 1 deadlines consolidate procurement authority among fewer strategic partners. Prioritize robotic-gloveless convergence R&D to defend against Syntegon Technology's automated filling platform encroachment. For New Entrants and Emerging Players: The premium-economy price-point gap in Chinese domestic vaccine manufacturing creates white-space entry opportunity for mid-tier isolator vendors lacking Swissmedic or FDA dual-certification. Target Jiangsu and Zhejiang province biologics parks with cost-adjusted isolator platforms that meet NMPA PIC/S alignment without European regulatory overhead. Pursue technology transfer partnerships with Shanghai-based foreign joint ventures as credibility-building go-to-market mechanism. For Investors and Strategic Acquirers: Asymmetric upside sits with German precision engineering houses possessing advanced isolator IP but limited Asian manufacturing footprint, as NMPA alignment accelerates Chinese demand for imported automation expertise. Five-to-ten year viability hinges on regulatory compliance capability rather than throughput metrics alone. Monitor EMA Annex 1 inspection deadline compliance rates among European CMOs as inflection indicator for equipment vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Licensing | Enables STERIS and GEA to anchor integrated vaccine processing lines with contamination control IP. |
| Fluoropolymer Backward Integration | Reduces Japanese supplier dependency that currently extends critical component lead times unpredictably. |
| Robotic-Gloveless Platform Development | Addresses high-potency oncology compound demand from Boston and San Francisco cell therapy manufacturers. |
| Chinese Domestic Assembly Partnership | Captures NMPA-aligned demand in Jiangsu province while preserving European regulatory credibility. |
| EMA Annex 1 Compliance Certification | Qualifies equipment for Rhine-Main pharmaceutical corridor procurement decisions before inspection deadlines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biologics manufacturing executives, regulatory affairs leads at FDA and EMA-inspected facilities, isolator engineering specialists, and contract manufacturing procurement directors with secondary validation through FDA sterile drug guidance filings, EMA Annex 1 revision documentation, NMPA PIC/S alignment notices, and SEC 10-K equipment vendor disclosures. Bottom-up facility capacity modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Comparable historical periods anchored the forecast window to pre-pandemic and pandemic-era capacity expansion cycles, with analytical framework segmenting by product containment format, automation technology tier, therapeutic application, and end-user archetype across the modeling period. CAGRs derived from facility installation pipeline analysis and regulatory compliance deadline scheduling, incorporating biologics pipeline progression from clinical to commercial stages and cell therapy manufacturing scale-up trajectories as industry-specific forecast inputs.
Caveats apply where fluoropolymer supply disruptions, EMA inspection timeline delays, or NMPA regulatory enforcement shifts could materially shift the outlook for equipment procurement volumes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market