
 Plastic Retort Cans Market | 2026-2036
Plastic Retort Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Retort Cans Market Outlook
Capital-intensity divergence between co-injection molding specialists and conventional converters is rotating competitive advantage toward barrier-layer control. Amcor leverages its multilayer PP-EVOH platform across ASEAN food processing contracts. Sonoco sustains North American dominance through captive PET sheet supply. Kortec anchors European pharmaceutical retort can demand with oxygen-scavenging closure systems.
Plastic retort cans are multilayer thermoplastic containers engineered to withstand 121°C sterilization cycles while maintaining oxygen transmission rates below 0.1 cc/can/day, replacing metal cans in shelf-stable food and drug packaging. Polypropylene coextrusions with ethylene vinyl alcohol barrier layers dominate food processing applications due to thermal stability and microwave compatibility. Round cans lead unit volume in pet food and ready meals, while custom shapes command premium positioning in pharmaceutical single-dose formats where differentiation justifies higher closure complexity. Snap-on lids compete aggressively with resealable covers in beverage applications, though screw caps retain pharmaceutical share due to child-resistance mandates.
US FDA 21 CFR 177.1390 governs laminate structures for retort applications, while EU EFSA migration limits under Regulation 10/2011 constrain recycled content claims. Japan's METI container quality standards create additional testing burdens for exporters. Buyers must monitor evolving state-level extended producer responsibility frameworks and decide between regional compliance investments or standardized global product platforms.
Market Dynamics
Barrier-layer coextrusion control is concentrating margin capture among converters with captive EVOH supply chains, while commodity sheet producers face displacement from ASEAN food processors demanding oxygen transmission below 0.05 cc/can/day.
Growth Catalysts
- US FDA 21 CFR 177.1390 compliance:Laminate structures meeting retort sterilization thresholds unlock pharmaceutical packaging contracts previously held by metal cans. EMA's migration testing protocols create parallel certification pathways for European drug manufacturers.
- Urban ready-to-eat meal demand:Southeast Asia's food processing corridor concentrates procurement of microwave-compatible polypropylene coextrusions. Bangkok and Ho Chi Minh City processing clusters drive volume specifications for 121°C thermal stability.
- Ethylene vinyl alcohol barrier advancement:Five-layer coextrusion lines achieve sub-0.1 cc/day oxygen transmission without aluminum oxide coatings. This process shift enables transparent retort cans for premium pet food positioning.
Market Restraints
- EVOH resin supply concentration:Three Japanese and Korean polymer suppliers control high-barrier grade availability, exposing converters to ethylene price volatility and force majeure allocation protocols.
- EU EFSA Regulation 10/2011 migration limits:Recycled content claims above 30% trigger extended testing timelines for retort laminate approval, constraining circular economy messaging.
- Metal can residual cost advantage:Tinplate and aluminum remain price-competitive for high-acid food categories where thermal cycling demands exceed plastic retort temperature thresholds.
Strategic Opportunities
- India's FSSAI processed food expansion:Underpenetrated shelf-stable dairy and curry segments present first-mover positioning for retort can converters establishing local coextrusion partnerships.
- Oxygen-scavenging closure integration:Convergence of active packaging chemistry with injection-molded lid systems extends shelf life for ambient pharmaceutical single-dose formats.
- Japan METI container quality standards:Exporter certification requirements create defensive moats for converters investing in Yokohama testing laboratory partnerships.
Industry Challenges
- Multilayer coextrusion technician scarcity:Die gap calibration and barrier layer thickness uniformity require specialized operators absent from conventional thermoforming labor pools.
- Retort validation cycle duration:Each new laminate structure requires 90-day accelerated aging protocols before commercial approval, compressing product development timelines.
- Legacy metal can line integration:Filling equipment designed for cylindrical steel containers demands retrofit investment for oval and rectangular plastic retort geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Retort Cans Market |
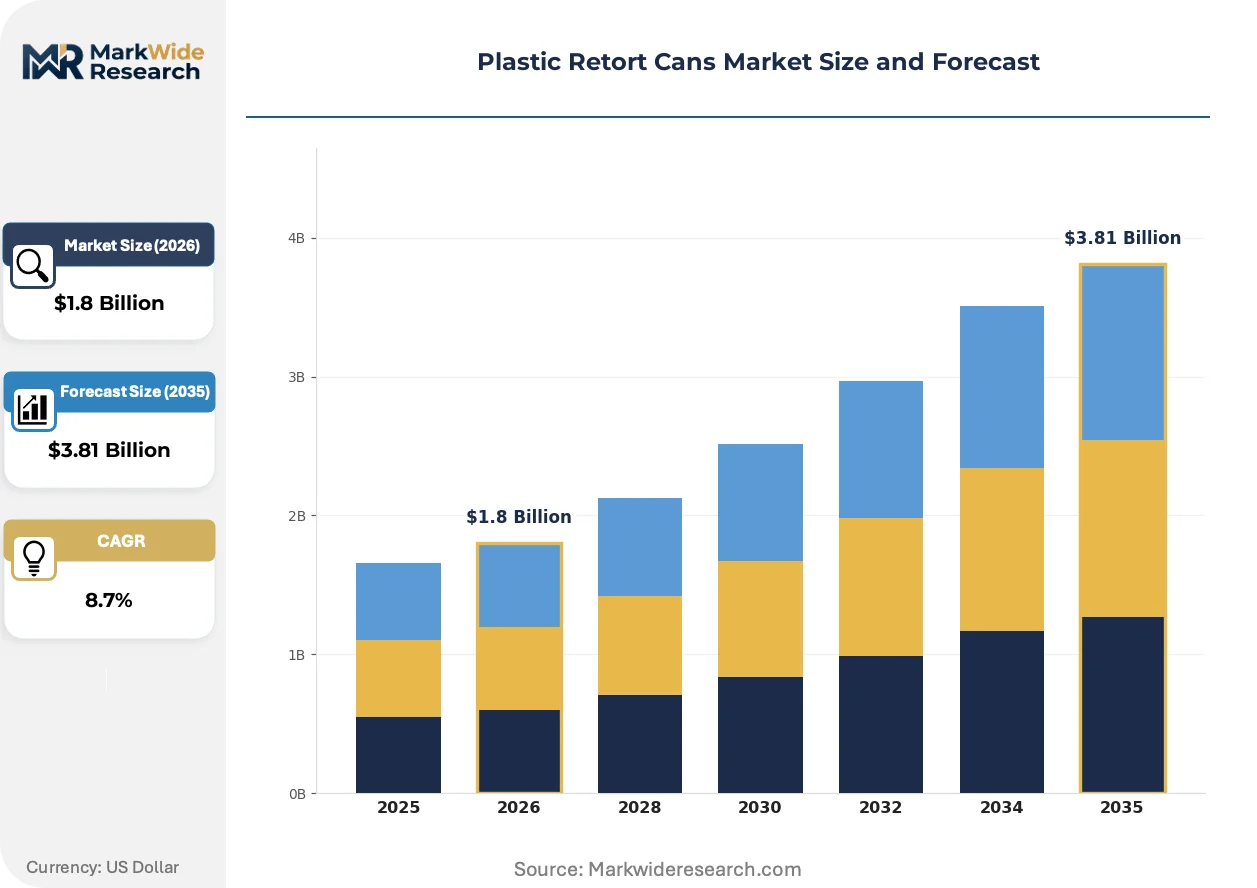
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Cans, Square Cans, Rectangular Cans, Custom Shapes End Use Industry: Food Processing, Pharmaceuticals, Beverages, Pet Food Material: Polypropylene, Polyethylene, PVC, PET Closure Type: Screw Caps, Snap-On Lids, Resealable Covers, Others |
| Companies Covered | Amcor, Sonoco, Kortec, SOPAKCO, Winpack, RPC Containers, Klear Can, Toyo Seikan, Milacron Co-Injection Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Retort Cans Market Strategic Shifts
Active barrier technologies and sterilization-compatible polymers are fragmenting traditional material hierarchies, while regulatory migration testing and procurement consolidation reshape competitive entry barriers.
High-barrier polypropylene coextrusions with nano-dispersed clay additives are bifurcating the mid-performance segment from premium EVOH-dependent structures. Pet food processors in Thailand and Vietnam are adopting these formulations for 18-month shelf life targets at 15% material cost reduction. This technology compression is enabling regional converters to challenge multinational laminate suppliers on specification compliance without barrier layer licensing fees.
EU EFSA's 2023 updated migration testing guidance for retort applications is extending approval timelines for recycled content integration. The industrial consequence is a two-track supply structure separating virgin-only pharmaceutical grades from experimental post-industrial feedstock variants. German and Swiss drug packaging specialists are responding by segregating production lines rather than pursuing blended material certifications.
Buyer consolidation among ASEAN contract food manufacturers is compressing supplier qualification cycles from 24 months to 14 months. Direct material specification authority is shifting from brand owners to toll processors in Singapore and Malaysia, who now dictate barrier layer thickness minimums. This pattern is most visible in ambient curry and dessert segments where processor scale enables dedicated extrusion line commitments.
Plastic Retort Cans Market Segmentation
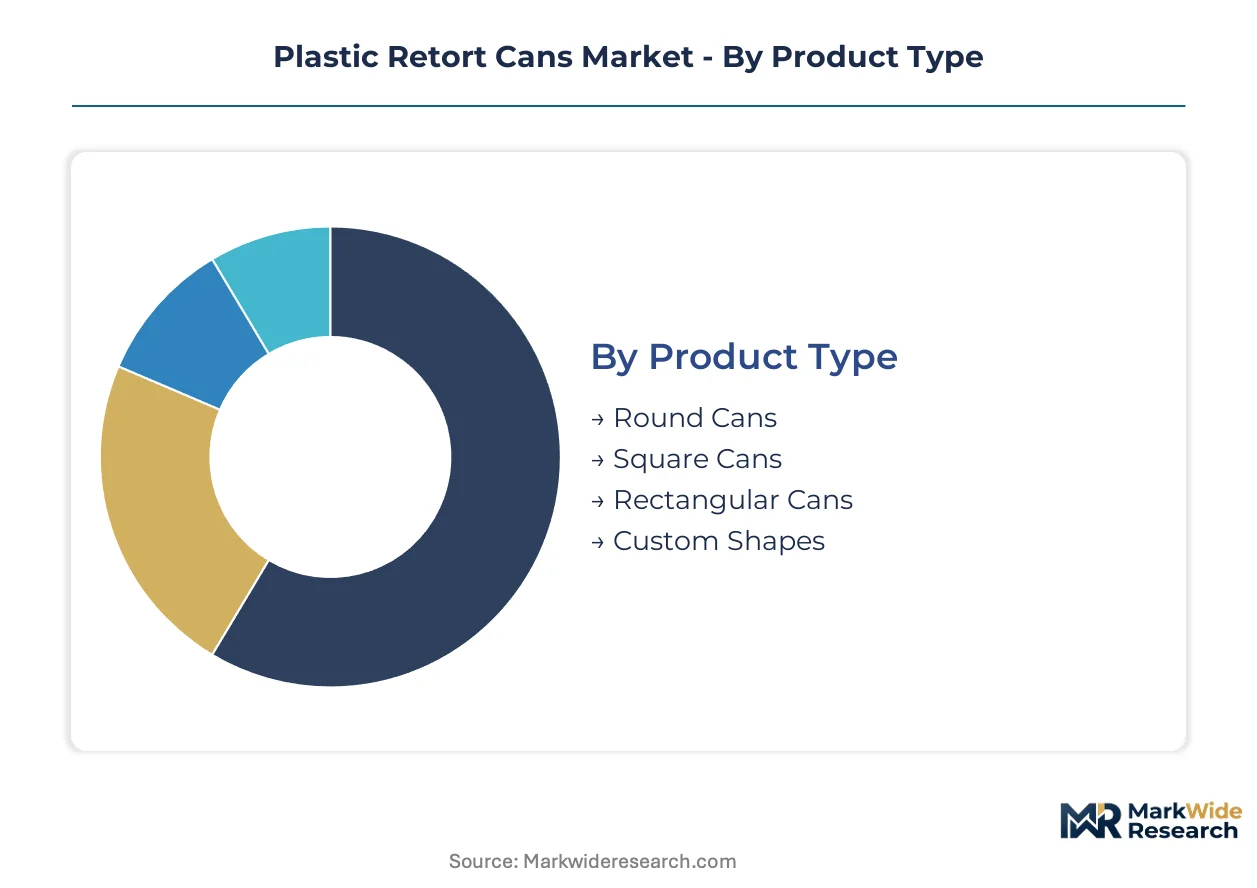
Retort can segmentation reveals divergent margin capture across geometry complexity and barrier-layer sophistication. Food processors and pharmaceutical contract manufacturers now specify multilayer structures by thermal cycle performance rather than commodity resin category.
Product Type:
Margin pools concentrate in geometries demanding specialized coextrusion die engineering and downstream filling line retrofitting.
- Round Cans:Cylindrical structures dominate unit economics through compatibility with legacy metal can filling equipment. Pet food processors in Thailand specify 300ml round formats for 121°C sterilization cycles, minimizing capital expenditure for line conversion.
- Square Cans:Rectangular profiles with radiused corners optimize pallet density for ready-to-eat meal distribution. Ho Chi Minh City processors specify these for ambient curry segments where cube efficiency reduces logistics cost per shelf-stable unit.
- Rectangular Cans:Flat-panel designs suit portion-controlled pharmaceutical single-dose formats requiring minimal headspace.
- Custom Shapes:Proprietary geometries command premium positioning in differentiated consumer categories where brand recognition justifies die investment.
Round cans hold installed capacity. Square cans are rotating up the share rankings.
End Use Industry:
Application-driven specification authority is shifting from brand owners to toll processors with dedicated extrusion line commitments.
- Food Processing:Shelf-stable ready meals and ambient curry segments drive polypropylene coextrusion demand. Bangkok processors dictate barrier layer thickness minimums for microwave-compatible 121°C thermal stability.
- Pharmaceuticals:Single-dose and multi-dose formats require oxygen transmission below 0.05 cc/can/day. Swiss drug packaging specialists segregate production lines between virgin-only and experimental post-industrial feedstock variants.
- Beverages:Retort-compatible containers for ambient juice and functional drinks compete with aseptic carton systems on total delivered cost.
- Pet Food:Premium positioning demands transparent retort cans enabled by five-layer coextrusion without aluminum oxide coatings.
Food processing anchors volume demand. Pharmaceuticals are climbing the fastest on value per unit.
Material:
Resin selection determines barrier performance tiers and regulatory compliance pathways across sterilization protocols.
- Polypropylene:Coextrusions with EVOH barrier layers dominate food applications through thermal stability and microwave compatibility. Vietnamese pet food processors adopt nano-dispersed clay additives for 18-month shelf life at reduced material cost.
- Polyethylene:Lower thermal tolerance constrains retort applications to sub-100°C pasteurization cycles in select beverage segments.
- PVC:Declining retort relevance due to plasticizer migration concerns under EU EFSA Regulation 10/2011 testing protocols.
- PET:Amorphous grades with oxygen-scavenging additives penetrate pharmaceutical formats requiring clarity and dimensional stability.
Polypropylene holds installed capacity. PET is rotating up the share rankings.
Closure Type:
Active packaging chemistry convergence with injection-molded systems is extending shelf life differentiation at the sealing interface.
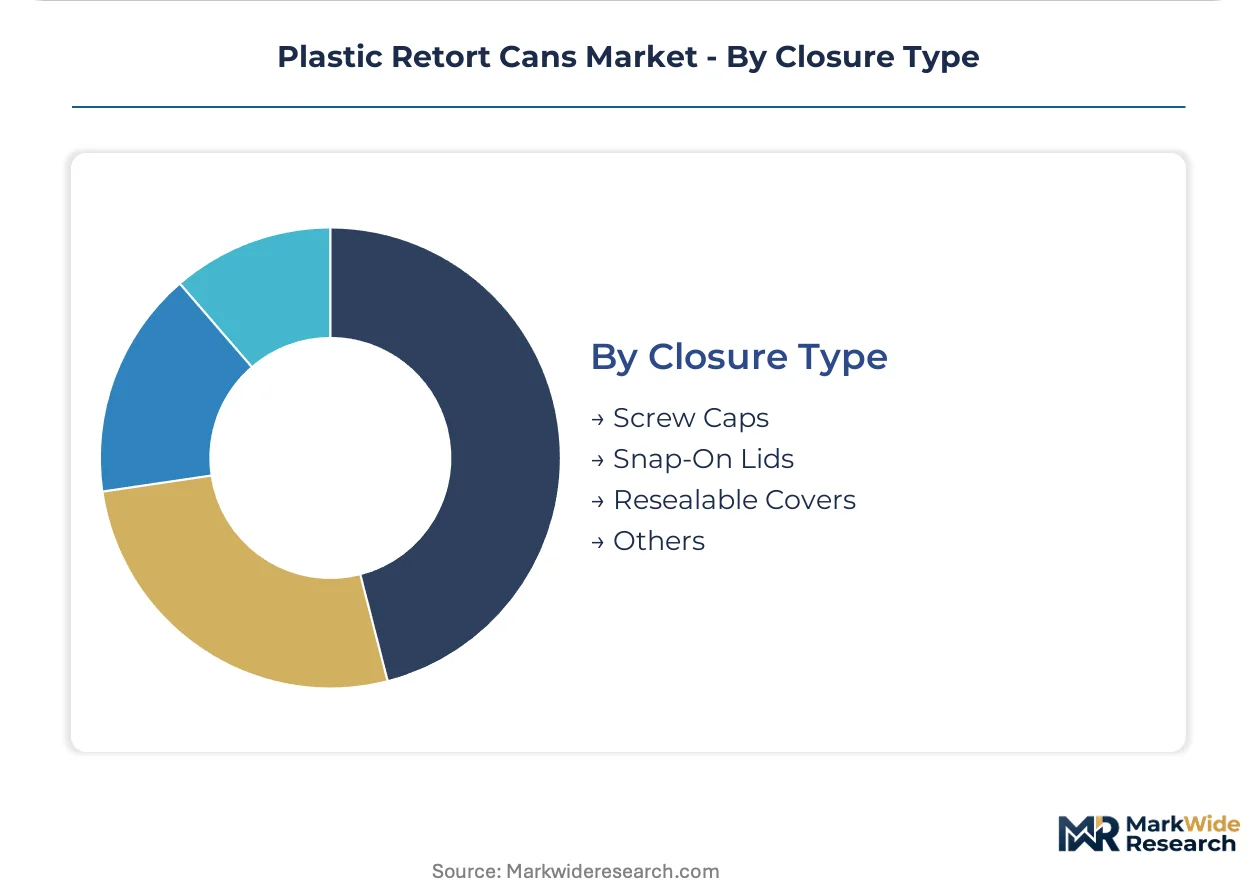
- Screw Caps:Child-resistant mandates retain pharmaceutical share despite slower line speeds versus snap-on alternatives. Kortec anchors European demand with oxygen-scavenging closure systems.
- Snap-On Lids:Aggressive cost positioning in beverage applications competes with resealable covers on convenience metrics.
- Resealable Covers:Premium ready meal positioning justifies higher unit cost through consumer reuse functionality.
- Others:Peelable foil laminates and hybrid systems serve niche pharmaceutical and diagnostic kit formats.
Screw caps hold installed capacity. Snap-on lids are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southeast Asia exhibit the highest price elasticity, driving procurement consolidation around Bangkok and Ho Chi Minh City processors. European pharmaceutical buyers show lowest elasticity, tolerating premium barrier-layer specifications for oxygen transmission below 0.05 cc/can/day. The United States sits between these poles, with food processors cost-conscious but FDA compliance requirements preventing pure commodity sourcing.
United States
Urban ready-to-eat meal adoption drives polypropylene coextrusion demand across Midwest and Southeast food processing corridors. FDA 21 CFR 177.1390 compliance mandates shape laminate structure investments, particularly for pharmaceutical packaging contracts. Chicago and Atlanta processing clusters concentrate procurement authority for 121°C sterilization-compatible formats.
Germany
Swiss and German drug packaging specialists segregate production lines between virgin-only and experimental post-industrial feedstock variants under EFSA migration limits. EU EFSA Regulation 10/2011 testing protocols constrain recycled content claims above 30%. Stuttgart and Munich industrial zones anchor European pharmaceutical retort can specification setting.
Japan
METI container quality standards create defensive certification moats for converters investing in Yokohama testing laboratory partnerships. Premium pet food positioning demands transparent retort cans enabled by five-layer coextrusion without aluminum oxide coatings. Osaka and Nagoya processing corridors concentrate microwave-compatible format procurement.
Thailand
Bangkok processors dictate barrier layer thickness minimums for ambient curry and dessert segments where processor scale enables dedicated extrusion line commitments. Nano-dispersed clay additives penetrate mid-performance applications for 18-month shelf life targets at reduced material cost. Eastern Seaboard industrial zones concentrate ASEAN food processing procurement activity.
Vietnam
Ho Chi Minh City processors drive volume specifications for square can formats optimizing pallet density in ready-to-eat meal distribution. Buyer consolidation among contract food manufacturers compresses supplier qualification cycles from 24 months to 14 months. Southern industrial provinces anchor regional pet food processor demand for transparent retort positioning.
Plastic Retort Cans Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive EVOH supply chains and multilayer coextrusion control determining margin capture. The market structure bifurcates between multinational laminate suppliers licensing barrier-layer technology and regional converters challenging on specification compliance. Three archetypes dominate: integrated resin-to-can converters with captive polymer supply, co-injection molding specialists with die engineering expertise, and toll processors with dedicated extrusion line commitments. Competitive moves concentrate on strategic partnerships with ASEAN food processors and technology licensing for five-layer coextrusion lines achieving sub-0.1 cc/day oxygen transmission.
Within the integrated converter tier, Amcor leverages its multilayer PP-EVOH platform across ASEAN food processing contracts, representing the geographic-expansion archetype. Sonoco sustains North American positioning through captive PET sheet supply, exemplifying backward integration strategy. Kortec anchors European pharmaceutical demand, occupying the active-packaging specialization niche with oxygen-scavenging closure systems.
| Leading Market Players |
|---|
| Amcor |
| Sonoco |
| Kortec |
| SOPAKCO |
| Winpack |
| RPC Containers |
| Klear Can |
| Toyo Seikan |
| Milacron Co-Injection Systems |
| Others |
Value Chain & Pricing Dynamics
US FDA 21 CFR 177.1390 compliance gates both supplier qualification and price differentiation simultaneously, creating a bifurcated market where certified pharmaceutical-grade laminates command substantial premiums over food-processing alternatives. Buyers face a forced choice between standardized global product platforms and region-specific compliance investments, with barrier-layer performance tiers determining contract accessibility across sterilization protocols.
Pricing Analysis
After-sales technical service and validation support drive lifetime value capture in retort can procurement. Three-tier pricing structure across premium, standard, and economy levels reflects oxygen transmission performance, with sub-0.05 cc/can/day pharmaceutical specifications commanding the highest tier. Price differentiation rests on EVOH barrier-layer thickness and multilayer coextrusion complexity. Cost compression in mid-performance food-grade segments is intensifying because nano-dispersed clay additives enable regional converters to undercut licensed EVOH suppliers. Contract food manufacturers in Southeast Asia exhibit highest price sensitivity, while Swiss and German pharmaceutical buyers tolerate premium specifications for oxygen-scavenging closure integration.
Supply Chain Analysis
Japan and South Korea anchor high-barrier EVOH resin production, with three polymer suppliers controlling pharmaceutical-grade availability. Raw material dependencies center on ethylene feedstock pricing, specialty coextrusion die engineering, and oxygen-scavenging additive chemistry. Single-source vulnerability concentrates in barrier-layer resin allocation protocols, exposing converters to force majeure disruption and ethylene price volatility. Distribution runs through ASEAN toll processing clusters in Bangkok and Ho Chi Minh City, where buyer consolidation compresses supplier qualification cycles and shifts specification authority from brand owners to regional processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between active packaging chemistry and injection-molded closure systems is creating platform-economics inflection, with oxygen-scavenging integration becoming the decisive ecosystem battleground for shelf-life extension contracts.
For Market Incumbents: Fortify captive EVOH supply chains through backward integration into barrier-layer resin sourcing, defending against nano-clay additive displacement in mid-performance food segments. Expand Yokohama and Bangkok testing laboratory partnerships to deepen METI and FDA compliance moats. Prioritize five-layer coextrusion line investments achieving sub-0.1 cc/day oxygen transmission without aluminum oxide coatings, as transparent retort positioning becomes the premium pet food differentiator. For New Entrants and Emerging Players: Technical service gaps in multilayer coextrusion die calibration and barrier-layer thickness uniformity present white-space entry points where incumbent labor scarcity constrains capacity expansion. Target India's underpenetrated shelf-stable dairy and curry segments through FSSAI-compliant local coextrusion partnerships. Lead with 90-day accelerated aging protocol management as a bundled service offering, compressing customer time-to-market versus established suppliers. For Investors and Strategic Acquirers: EU EFSA's updated migration testing guidance for recycled content integration reshapes the acquisition landscape toward segregated production line specialists capable of serving dual-track virgin and post-industrial feedstock demand. Long-term viability favors converters with demonstrated pharmaceutical certification pathways and ASEAN processor relationships. Monitor Japan METI container quality standard enforcement as the signal for defensive moat durability among Yokohama-certified laboratory partners.| Strategic Initiative | Industry Significance |
|---|---|
| Five-Layer Coextrusion Capacity Expansion | Enables sub-0.1 cc/day oxygen transmission for transparent pharmaceutical and premium pet food positioning. |
| Oxygen-Scavenging Closure Integration | Converges active packaging chemistry with injection-molded lid systems for ambient single-dose shelf-life extension. |
| Regional Testing Laboratory Partnerships | Yokohama METI certification investments create defensive moats against exporter qualification barriers. |
| Nano-Dispersed Clay Additive Adoption | Reduces material cost 15% for 18-month shelf life targets in Thai and Vietnamese pet food processing. |
| Segregated Production Line Configuration | Separates virgin-only pharmaceutical grades from experimental post-industrial variants under EFSA migration limits. |
Study Parameters
Initial hypotheses were tested against primary input from multilayer coextrusion technicians, ASEAN contract food manufacturer procurement directors, pharmaceutical packaging specialists, and barrier-layer resin procurement managers, and refined through secondary validation. Primary fieldwork encompassed plant-level interviews across Bangkok, Ho Chi Minh City, Stuttgart, and Yokohama processing corridors. Secondary sources included US FDA 21 CFR filings, EU EFSA migration testing guidance, Japan METI container quality standards, and customs trade data for EVOH resin flows. Bottom-up unit economics modeling triangulated against top-down market sizing across the analysis window.
Variance decomposition across product type, end-use industry, material formulation, closure system, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segmented volume and value build-ups incorporating sterilization cycle compatibility specifications, barrier-layer oxygen transmission thresholds, and processor consolidation patterns. Industry-specific forecast inputs captured coextrusion line capacity expansion timelines and EVOH resin allocation protocol stability.
Forecasts assume regulatory continuity in US FDA, EU EFSA, and Japan METI regimes; material policy shifts would require re-modeling laminate structure approval timelines and recycled content integration pathways. Specific risks include ethylene price volatility, multilayer coextrusion technician scarcity, and legacy metal can filling equipment retrofit delays. Recalibration cycles align with material shifts in barrier-layer technology adoption and ASEAN processor consolidation momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market