
 Latin America Aseptic Packaging Market | 2026-2036
Latin America Aseptic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Aseptic Packaging Market Foresight
Consolidation among multinational beverage bottlers across Brazil and Mexico is realigning procurement volumes toward suppliers with continental-scale service networks. Tetra Pak International leverages its integrated filling-system ecosystem to anchor long-term contracts with dairy processors. SIG Combibloc Group AG competes through lightweight carton geometries that reduce freight costs on Andean distribution routes. Amcor PLC sustains polymer supply advantages via backward integration into resin conversion across Argentine operations.
Aseptic packaging in Latin America employs hydrogen peroxide vapor or electron-beam sterilization of packaging substrates prior to filling, followed by hermetic sealing in a microbiologically controlled environment to achieve commercial sterility without refrigeration. Paperboard-based liquid cartons dominate unit volumes across the region's juice and milk sectors, while aluminum-laminate pouches capture faster growth in single-serve beverage formats. Tray packaging holds mature positioning in prepared-meal segments, whereas pharmaceutical-grade glass vials command concentrated margin pools amid ANVISA sterility enforcement.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia each enforce distinct sterility validation protocols that fragment compliance requirements for cross-border suppliers. Brazil's Plano Nacional de Resíduos Sólidos and Mexico's Ecolabel program are extending producer responsibility mandates to multilaminate packaging structures, reshaping material selection priorities. Stakeholders must monitor divergence between Mercosur and Pacific Alliance regulatory harmonization timelines to anticipate where unified standards might unlock scale economies or where persistent fragmentation will favor localized production investments.
Market Dynamics
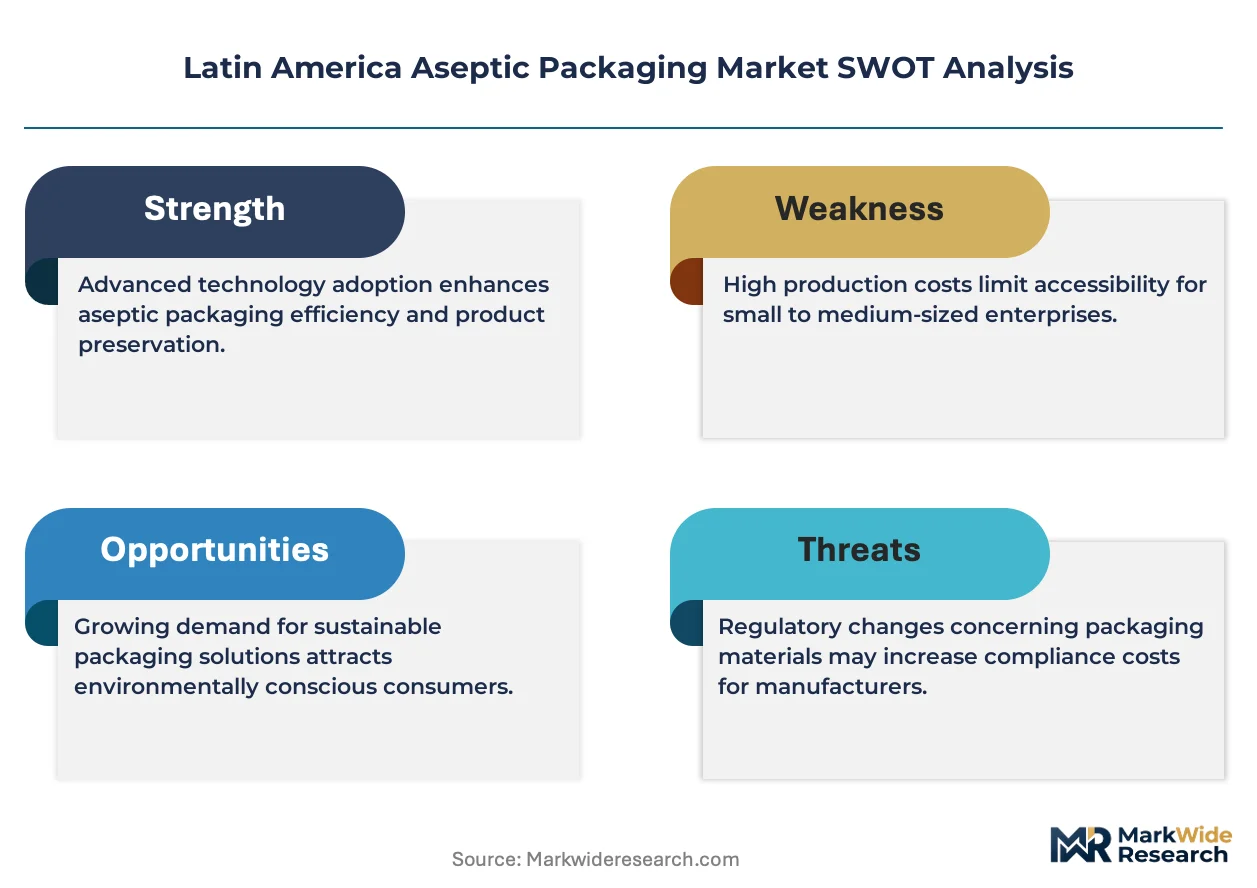
ANVISA's sterility validation tightening is forcing dairy and pharmaceutical processors across Brazil to replace legacy filling lines, triggering a capital equipment refresh cycle that concentrates procurement among suppliers offering integrated sterilization-to-sealing systems.
Growth Catalysts
- COFEPRIS pharmaceutical packaging mandates:Mexico's updated sterility protocols for injectables are accelerating validation-ready aseptic line installations across Querétaro and Guadalajara manufacturing corridors.
- Andean freight cost pressures:Lightweight carton geometries are capturing preference among juice processors shipping from Colombia's Cauca Valley to high-altitude distribution points.
- Brazilian cold-chain gaps:Dairy cooperatives in Minas Gerais are deploying aseptic brick packs to extend shelf-stable distribution into Northeastern interior markets lacking refrigerated transport infrastructure.
Market Restraints
- Resin supply concentration:Polymer substrate sourcing for multilaminate structures remains captive to Argentine petrochemical output, exposing converters to feedstock volatility during peso devaluation cycles.
- Regulatory fragmentation:Divergent sterility validation timelines between ANVISA, COFEPRIS, and INVIMA force suppliers to maintain three distinct quality management systems for cross-border contracts.
- Multilaminate recyclability limits:Brazil's Plano Nacional de Resíduos Sólidos extended producer responsibility rules impose end-of-life cost burdens that paperboard-aluminum-polymer structures cannot yet satisfy economically.
Strategic Opportunities
- Central American corridor penetration:Guatemalan and Honduran beverage processors currently reliant on imported finished goods present greenfield aseptic line installation prospects for regional dairy investors.
- Electron-beam sterilization convergence:Integration of e-beam substrate treatment with high-speed form-fill-seal equipment offers pharmaceutical contract manufacturers path to ANVISA compliance without hydrogen peroxide residue risks.
- Single-serve pouch formats:Aluminum-laminate stick packs for functional beverages are capturing shelf space in Mexican convenience retail channels ahead of equivalent carton penetration.
Industry Challenges
- Validation timeline compression:ANVISA's accelerated sterility audit schedules force pharmaceutical packagers to compress installation-to-qualification cycles, straining commissioning engineer availability across São Paulo state.
- Legacy line integration friction:Retrofitting hydrogen peroxide vapor systems onto existing dairy filling equipment requires custom mechanical interfaces that delay production restart and strain maintenance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Aseptic Packaging Market |
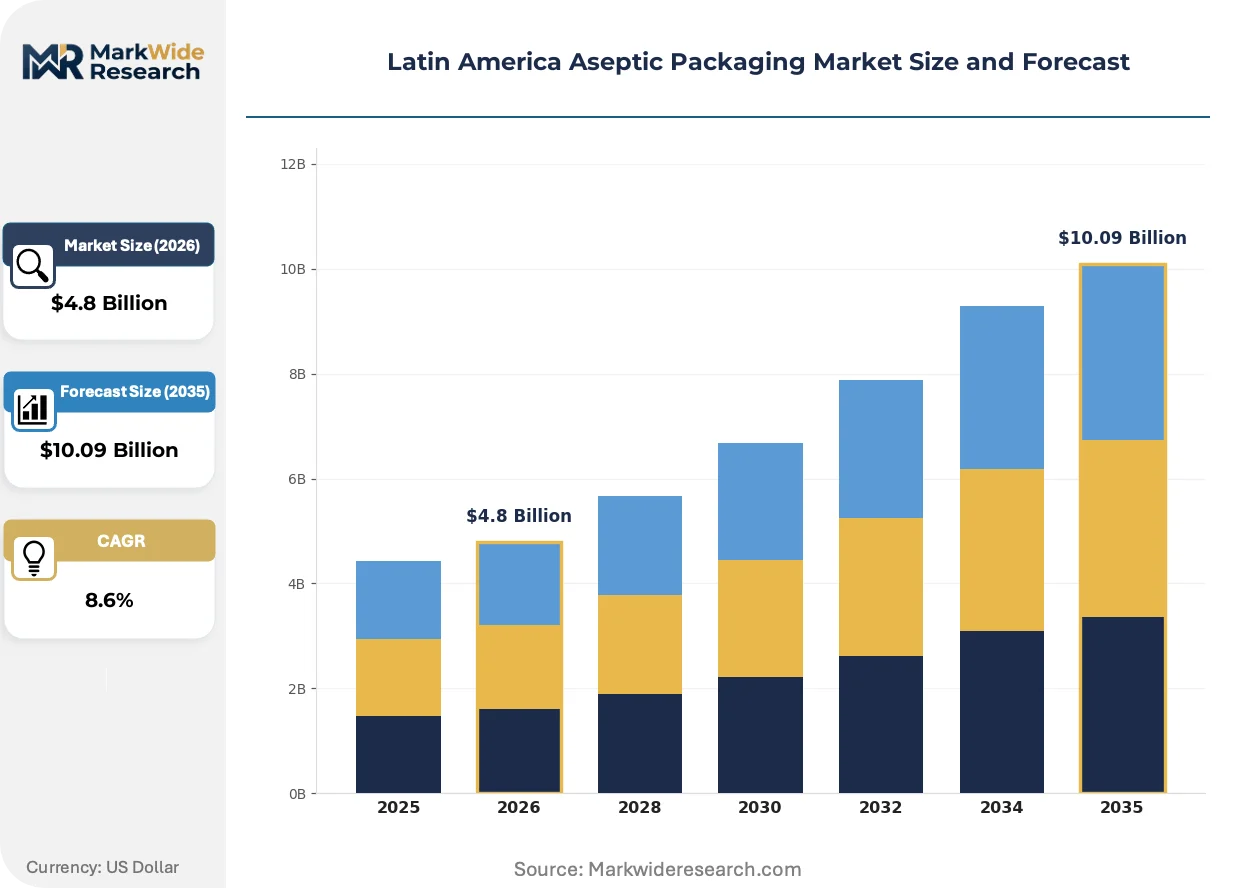
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Packaging, Tray Packaging, Bottles, Pouches Material: Plastic, Paperboard, Aluminum, Glass End User: Food & Beverage, Pharmaceuticals, Personal Care, Industrial Technology: Thermoforming, Filling, Sealing, Sterilization |
| Companies Covered | Stora Enso Oyj, Elopak AS, SIG Combibloc Group AG, Bemis Company Inc, DS Smith PLC, Tetra Pak International, Sonoco Products Company, Schott AG, Amcor PLC, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Aseptic Packaging Market Shifts & Advancements
Electron-beam sterilization is displacing hydrogen peroxide vapor across pharmaceutical-grade packaging lines, while regulatory divergence between Mercosur and Pacific Alliance jurisdictions reshapes where suppliers concentrate validation investments.
Electron-beam substrate sterilization is consolidating technical preference among ANVISA-regulated pharmaceutical packagers seeking to eliminate hydrogen peroxide residue detection risks. Brazilian injectables manufacturers in the São Paulo–Campinas corridor are adopting e-beam-equipped form-fill-seal systems at replacement-cycle pace. This technology shift is consolidating supplier relationships around equipment vendors offering integrated e-beam sources rather than modular retrofits.
ANVISA's updated Resolution RDC 430 sterility guidelines are mandating real-time environmental monitoring data integration into batch release documentation. Pharmaceutical packaging operations must now deploy continuous particle counting and viable air sampling systems linked directly to manufacturing execution software. Brazilian sterile injectables packagers are responding by prioritizing line investments that embed environmental monitoring hardware from initial qualification rather than aftermarket addition.
Buyer concentration among multinational beverage bottlers is compressing procurement decision cycles and unbundling after-sales service contracts from equipment supply agreements. Mexican dairy and juice processors in the central highlands corridor are negotiating direct spare parts sourcing rights and third-party maintenance authorization to reduce total cost of ownership. This purchasing behavior shift is most visible among processors serving Walmart de México and OXXO retail channels, where volume guarantees justify dedicated line capacity commitments.
Latin America Aseptic Packaging Market Segmentation
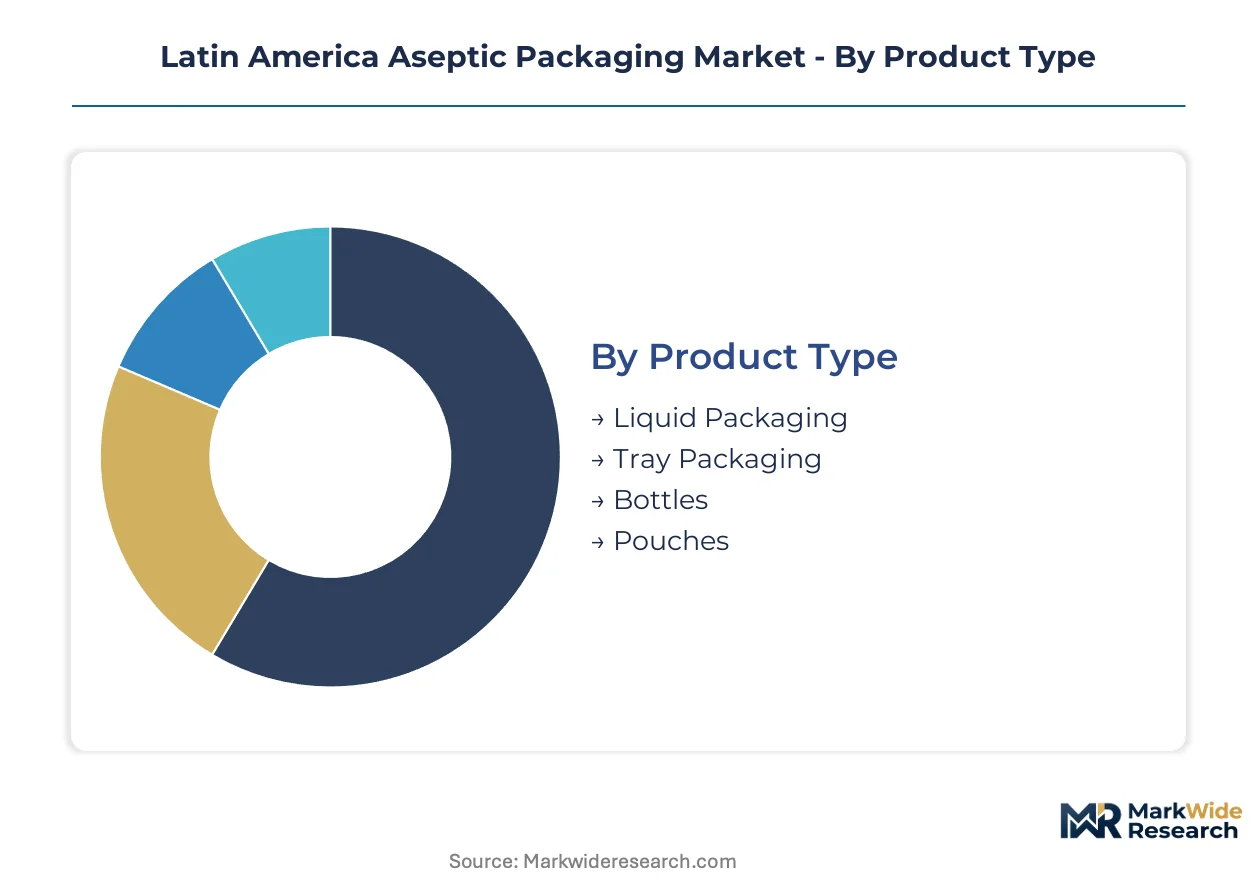
Latin American aseptic packaging procurement patterns diverge sharply between cold-chain-dependent dairy corridors and sterility-critical pharmaceutical clusters. Material selection and sterilization technology choices concentrate in distinct buyer segments with incompatible validation requirements.
Product Type:
Procurement volumes in Brazil and Mexico concentrate where shelf-stable distribution extends reach beyond refrigerated logistics networks.
- Liquid Packaging:Paperboard-aluminum-polymer laminates dominate unit shipments for milk and juice processors across Minas Gerais and São Paulo dairy corridors. Brazilian cooperatives deploy brick packs to penetrate Northeastern interior markets lacking cold-chain infrastructure.
- Tray Packaging:Polypropylene-EVOH multilayer structures serve prepared-meal segments in Mexico's central highlands manufacturing belt. COFEPRIS food-contact compliance requirements favor suppliers with validated high-barrier coating technologies.
- Bottles:HDPE and PET aseptic blow-fill-seal systems capture pharmaceutical oral dosage formats.
- Pouches:Aluminum-laminate stick packs gain shelf space in Mexican convenience retail channels.
Volume sits with liquid packaging; growth tilts toward pouches.
Material:
End-use sterility requirements and extended producer responsibility rules reshape substrate selection priorities across ANVISA, COFEPRIS, and INVIMA jurisdictions.
- Plastic:Multilaminate films with EVOH oxygen barriers serve high-acid juice applications. Argentine petrochemical supply concentration exposes converters to peso-driven feedstock volatility.
- Paperboard:Liquid carton substrates integrate renewable fiber content to satisfy Brazil's Plano Nacional de Resíduos Sólidos recovery targets. São Paulo dairy processors prioritize suppliers with certified sustainable sourcing.
- Aluminum:Foil layers provide absolute moisture and light barriers for pharmaceutical blister packs.
- Glass:Type I borosilicate vials command premium positioning in ANVISA-regulated injectables packaging.
Plastic holds volume leadership; aluminum-laminate structures are climbing the fastest.
End User:
Validation protocol intensity varies dramatically between food-contact sterility and pharmaceutical-grade aseptic requirements.
- Food & Beverage:Dairy and juice processors across Brazil's Southeast and Mexico's Jalisco-Querétaro corridor drive equipment refresh cycles. Hydrogen peroxide vapor sterilization remains standard for high-speed filling lines.
- Pharmaceuticals:São Paulo-Campinas injectables manufacturers accelerate electron-beam sterilization adoption to eliminate residue detection risks under ANVISA Resolution RDC 430.
- Personal Care:Cosmetic serum packs adopt pharmaceutical-grade barrier specifications.
- Industrial:Chemical and agricultural formulations require corrosion-resistant aseptic containment.
Food and beverage anchors procurement volume; pharmaceuticals show the steepest technology upgrade trajectory.
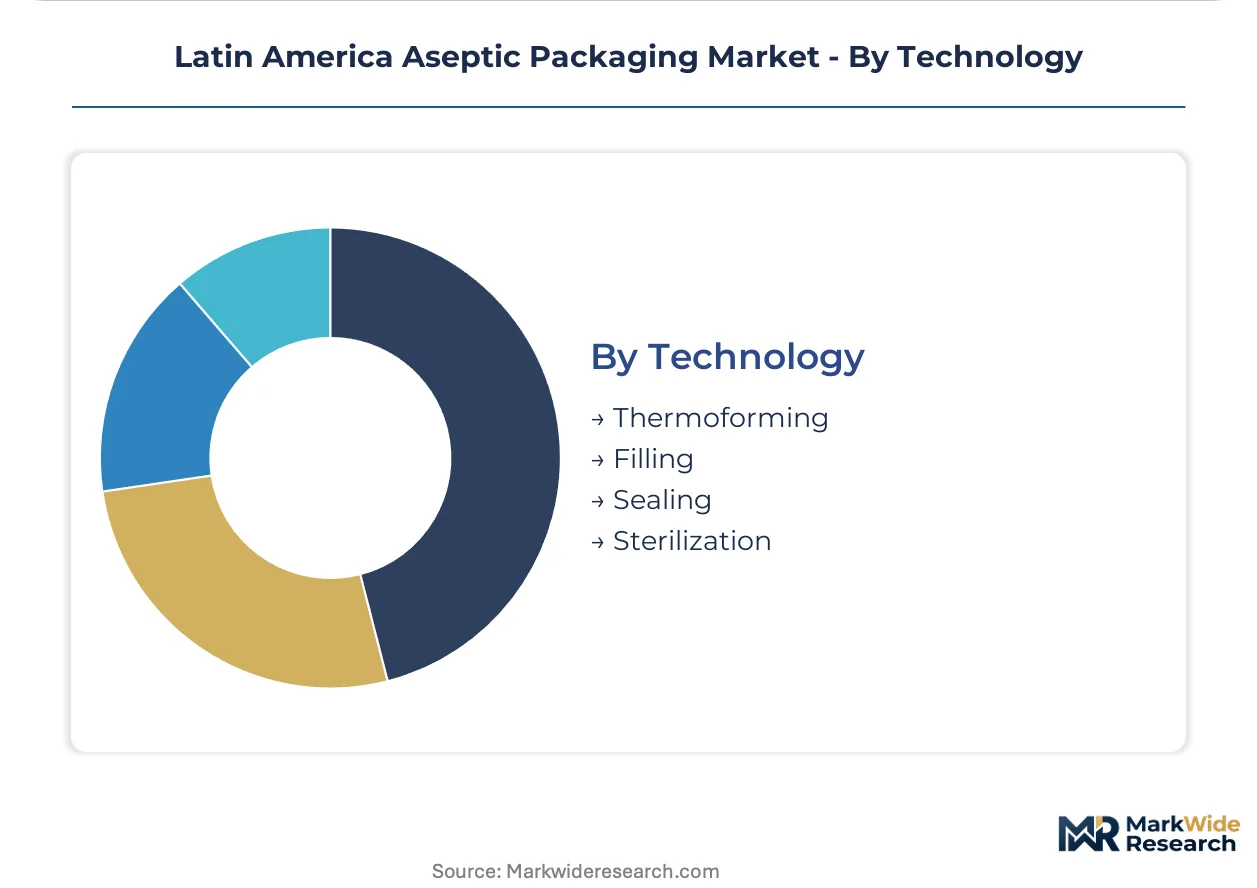
Technology:
Equipment investment cycles concentrate where regulatory deadlines force line replacement rather than incremental retrofit.
- Thermoforming:Roll-fed systems produce tray cavities for ready-meal applications. Mexican processors favor equipment with quick-change mold capabilities to accommodate SKU proliferation in retail channels.
- Filling:Isobaric and gravity filling systems handle liquid viscosity ranges from water to pulped nectars.
- Sealing:Ultrasonic and heat-seal technologies ensure hermetic integrity for shelf-stable claims.
- Sterilization:Hydrogen peroxide vapor and electron-beam substrate treatment compete for pharmaceutical validation preference.
Filling systems represent installed base concentration; sterilization technology selection is gaining share fastest as validation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's dairy corridors and Mexico's central highlands manufacturing belt, where cold-chain-independent distribution networks extend shelf-stable reach into underserved interior markets.
Brazil
Dairy cooperatives in Minas Gerais deploy aseptic brick packs to penetrate Northeastern interior markets lacking refrigerated transport infrastructure. ANVISA's Resolution RDC 430 mandates real-time environmental monitoring data integration into batch release documentation for pharmaceutical packagers. São Paulo–Campinas corridor injectables manufacturers accelerate electron-beam sterilization adoption to eliminate hydrogen peroxide residue detection risks.
Mexico
Juice and dairy processors in the Jalisco-Querétaro corridor negotiate direct spare parts sourcing rights to reduce total cost of ownership for high-speed filling lines. COFEPRIS updated sterility protocols for injectables accelerate validation-ready aseptic line installations across Querétaro and Guadalajara manufacturing corridors. Mexico's Ecolabel program extends producer responsibility mandates to multilaminate packaging structures, reshaping material selection priorities for converters serving Walmart de México and OXXO retail channels.
Argentina
Polymer substrate sourcing for multilaminate structures remains captive to Argentine petrochemical output, exposing converters to feedstock volatility during peso devaluation cycles. The country's national pharmaceutical regulator enforces distinct sterility validation protocols that fragment compliance requirements for cross-border suppliers. Buenos Aires province converters prioritize backward integration into resin conversion to sustain polymer supply advantages amid currency-driven input cost swings.
Colombia
Lightweight carton geometries capture preference among juice processors shipping from Cauca Valley to high-altitude distribution points across Andean freight routes. INVIMA enforces sterility validation protocols divergent from ANVISA and COFEPRIS timelines, forcing suppliers to maintain separate quality management systems. Bogotá-based beverage processors serving domestic retail and export channels concentrate procurement among suppliers with continental-scale service networks.
Chile
Prepared-meal segments in Santiago metropolitan region drive tray packaging demand for polypropylene-EVOH multilayer structures with high-barrier coating technologies. The country's national food safety authority aligns sterility validation approaches with Pacific Alliance harmonization timelines rather than Mercosur standards. Valparaíso corridor converters monitor regulatory divergence to anticipate where unified standards might unlock scale economies versus localized production investments.
Latin America Aseptic Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in electron-beam sterilization and lightweight substrate engineering. Tetra Pak International anchors the integrated filling-system ecosystem segment, while SIG Combibloc Group AG and Amcor PLC compete through differentiated material geometries and captive supply chain configurations. Supplier relationships concentrate around equipment vendors offering integrated sterilization-to-sealing systems rather than modular retrofits. Strategic moves emphasize long-term contract anchoring with dairy processors and backward integration into resin conversion to defend margin positions.
Within the integrated systems tier, Tetra Pak International and SIG Combibloc Group AG exemplify equipment-anchored competitive positioning, while Amcor PLC represents polymer supply advantages through in-house production capabilities. Stora Enso Oyj and DS Smith PLC occupy positions in renewable fiber-based substrate engineering. Elopak AS and Bemis Company Inc sit within specialized barrier film segments. Sonoco Products Company and Schott AG represent diversified packaging technology portfolios spanning pharmaceutical-grade containment solutions.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| Elopak AS |
| SIG Combibloc Group AG |
| Bemis Company Inc |
| DS Smith PLC |
| Tetra Pak International |
| Sonoco Products Company |
| Schott AG |
| Amcor PLC |
| Others |
Supply & Pricing Matrix
Brazil's Plano Nacional de Resíduos Sólidos recovery mandates gate qualified supply access and premium-tier pricing eligibility for converters serving ANVISA-regulated pharmaceutical and dairy segments. Compliance-certified substrates command measurable premiums over standard grades, while non-compliant suppliers face exclusion from procurement shortlists at major beverage cooperatives.
Pricing Analysis
Volume concentrates in standard-grade liquid cartons for Brazilian dairy corridors, while margins pool in pharmaceutical-grade glass vials and electron-beam sterilization systems. Three-tier pricing structure across premium, standard, and economy levels reflects ANVISA certification tier, after-sales service bundling, and geographic delivery cost to Andean distribution points. Cost compression in standard-tier paperboard laminates is intensifying because Argentine petrochemical feedstock volatility transmits directly to converter margins. Small dairy cooperatives in Brazil's Northeast interior exhibit highest price sensitivity; São Paulo-Campinas pharmaceutical contract manufacturers prioritize validation reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in São Paulo state and Mexico's Querétaro corridor anchor hub-and-spoke patterns for spare parts and technical service coverage. Raw material sourcing draws from Argentine petrochemical complexes for polymer films, Brazilian pulp mills for paperboard substrates, and domestic aluminum smelters for barrier layers. Single-source vulnerability in EVOH oxygen barrier films creates exposure to peso-driven input cost swings. Distribution runs through continental-scale service networks rather than localized converter relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron-beam sterilization technology is displacing hydrogen peroxide vapor across pharmaceutical packaging lines, compressing equipment replacement cycles and reshaping supplier consolidation opportunities.
For Market Incumbents: Extend integrated filling-system ecosystems into electron-beam sterilization partnerships to capture ANVISA-mandated equipment refresh cycles. Consolidate spare parts distribution rights in Mexico's central highlands corridor before buyer unbundling accelerates. Tetra Pak International and SIG Combibloc Group AG face emerging pressure from specialized e-beam equipment vendors seeking pharmaceutical validation contracts. For New Entrants and Emerging Players: The price-point gap between premium pharmaceutical-grade systems and economy dairy cartons presents white-space opportunity for mid-tier electron-beam retrofits. Target Brazilian dairy cooperatives in Minas Gerais seeking cold-chain extension without full line replacement. Guatemala and Honduras beverage processors offer greenfield installation prospects with lower incumbent entrenchment. For Investors and Strategic Acquirers: ANVISA's accelerated sterility audit schedule compression is the leading indicator that pharmaceutical packaging equipment demand will sustain elevated replacement velocity. Backward-integrated converters with captive resin supply in Argentina offer defensive positioning against feedstock volatility. Watch COFEPRIS-COFEPRIS regulatory harmonization progress as signal for cross-border scale economy unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Electron-Beam Sterilization Integration | ANVISA Resolution RDC 430 compliance eliminates hydrogen peroxide residue detection risks for São Paulo injectables manufacturers. |
| Backward Integration into Resin Conversion | Argentine petrochemical supply concentration rewards converters with captive polymer production during peso devaluation cycles. |
| Continental Service Network Expansion | Brazil-Mexico corridor coverage satisfies multinational beverage bottler procurement consolidation toward unified supplier relationships. |
| Lightweight Carton Geometry Engineering | Andean freight cost pressures favor SIG Combibloc Group AG geometries reducing distribution expense to high-altitude Colombian markets. |
| Real-Time Environmental Monitoring Embedding | ANVISA batch release documentation mandates drive pharmaceutical line investments with integrated particle counting from initial qualification. |
Research Methodology
Multi-period observation of equipment installation cycles, regulatory deadline compliance rates, and raw material cost transmission patterns anchored the trend analysis, supplemented by interviews with dairy processing plant managers, pharmaceutical packaging engineering directors, ANVISA regulatory affairs consultants, and aftermarket service technicians. Secondary validation drew from ANVISA resolution filings, COFEPRIS sterility protocol updates, Argentine customs trade data, and Brazilian pulp industry association reports. Bottom-up line installation counts triangulated against top-down converter revenue estimates.
Input-output matrix framing connected sterilization technology adoption curves to pharmaceutical validation timelines across product type, material substrate, end-user sector, and country-specific regulatory jurisdiction dimensions. CAGRs were derived from segmented volume trajectory modeling incorporating equipment replacement cycle compression and cold-chain infrastructure gap closure rates. Feedstock cost volatility indices and regulatory harmonization probability assessments informed scenario-weighted projections across the analysis window.
Inputs from equipment vendor order backlogs and dairy cooperative procurement announcements were available through the study window; gaps in real-time pharmaceutical line qualification timelines introduce uncertainty bands around replacement velocity assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market