
 Aseptic IBC Market | 2026-2036
Aseptic IBC Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic IBC Market Outlook
Market Context with Strategic Players
The capital-intensity divergence between stainless steel specialists and plastic-format producers is unwinding as biopharma clients demand hybrid validation protocols. Schoeller Allibert leverages its European molding infrastructure to compete on total cost of ownership for high-turnover dairy applications. Thielmann US LLC anchors its position through ASME-certified stainless steel fabrication for injectable drug logistics. Greif Inc. extends its global reconditioning network to capture recurring revenue from closed-system pharmaceutical fleets.
Technical Definition and Structural Segments
An aseptic intermediate bulk container is a sterilizable, sealed vessel typically rated between 275 and 550 gallons, engineered to maintain ISO 5 or ISO 7 cleanliness levels during liquid and semi-solid transfer operations in controlled manufacturing environments. Stainless steel formats dominate pharmaceutical applications where steam-in-place validation and multi-decade service life offset premium first cost. Plastic variants lead food and beverage throughput economics due to lighter tare weight and lower sanitization energy burden, though composite formats are gaining traction where chemical resistance and thermal stability must coexist. Closed systems command the technology hierarchy in biologics handling because open-format exposure invites endotoxin and particulate contamination that batch-release protocols cannot tolerate.
Regulatory Framework and Forward Outlook
FDA 21 CFR Part 211 and EMA Annex 1 revisions are elevating container closure integrity testing from guideline to enforceable expectation, compelling IBC suppliers to document particulate shedding and bioburden baselines. ISO 14644 cleanroom classifications now intersect with ASTM D4169 distribution simulation to form a dual compliance gate for pharmaceutical market access. Stakeholders must monitor whether MDR and EU AI Act traceability requirements migrate into sterile packaging supply chain mandates, as machine-readable batch records on reusable containers could become a non-negotiable specification.
Market Dynamics
Biologics manufacturers are consolidating their supply base around closed-system aseptic IBC formats as FDA and EMA validation timelines compress, forcing container suppliers to absorb compliance costs or exit pharmaceutical-grade segments entirely.
Growth Catalysts
- EMA Annex 1 Revision:The updated sterile manufacturing guideline mandates container closure integrity testing for all reusable vessels, compelling pharmaceutical firms to upgrade IBC fleets and creating replacement demand for validated formats.
- Cell and Gene Therapy Expansion:Autologous therapy production requires single-batch aseptic containers with rapid turnaround protocols, driving adoption of lightweight plastic IBC variants with gamma-irradiation compatibility.
- German Manufacturing Clusters:Concentrated molding and metalworking capabilities in North Rhine-Westphalia enable rapid prototyping of hybrid IBC designs, shortening qualification timelines for biopharma clients.
Market Restraints
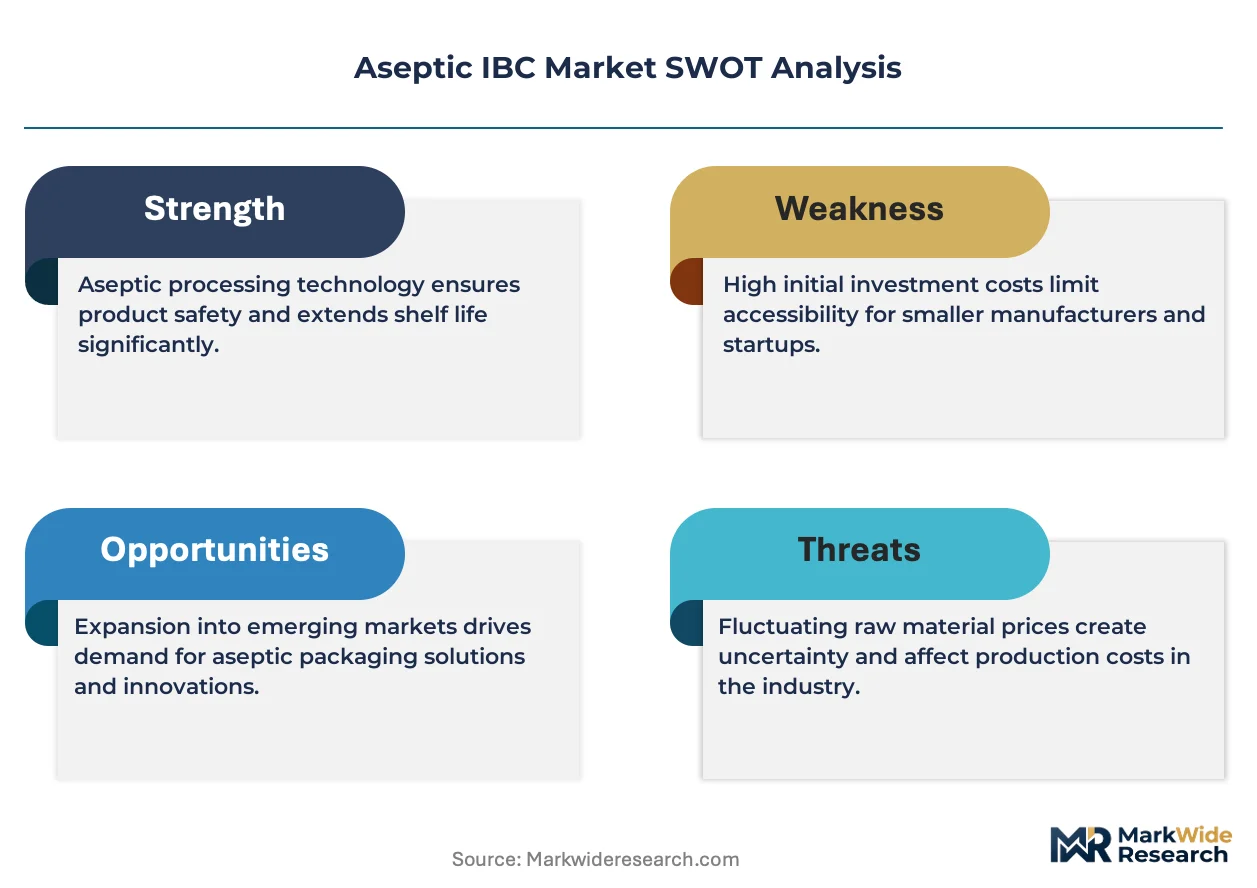
- Stainless Steel Input Volatility:Nickel price fluctuations directly compress margins for ASME-certified fabricators, forcing pass-through clauses that pharmaceutical buyers resist during multi-year contract negotiations.
- Validation Documentation Burden:FDA 21 CFR Part 211 requirements for particulate shedding baselines demand extensive third-party testing, creating a fixed cost barrier for smaller IBC suppliers without captive laboratory capacity.
- Single-Use Bag Substitution:Flexible film containment systems are capturing low-volume biologics applications where IBC capital investment cannot be amortized across limited batch frequencies.
Strategic Opportunities
- Indian Biologics Manufacturing:CDSCO's accelerated approval pathways for biosimilars are attracting contract manufacturing organizations that require aseptic IBC infrastructure without legacy European supplier relationships.
- Digital Twin Integration:Convergence of RFID-enabled IBC tracking with distributed ledger verification creates service revenue streams beyond hardware sales, particularly for temperature-sensitive vaccine logistics.
- EU Green Deal Alignment:Reusable container mandates in food and beverage processing are spilling into pharmaceutical adjacent sectors, rewarding suppliers with certified circular economy protocols.
Industry Challenges
- Cleanroom Technician Scarcity:ISO 14644 certification requirements for IBC sanitization personnel outstrip vocational training pipeline capacity, extending commissioning timelines for new production facilities.
- Legacy System Integration:Steam-in-place validation protocols for stainless steel IBCs conflict with newer plastic-format gamma-irradiation workflows, forcing manufacturers to maintain dual infrastructure or abandon hybrid client portfolios.
Report Scope
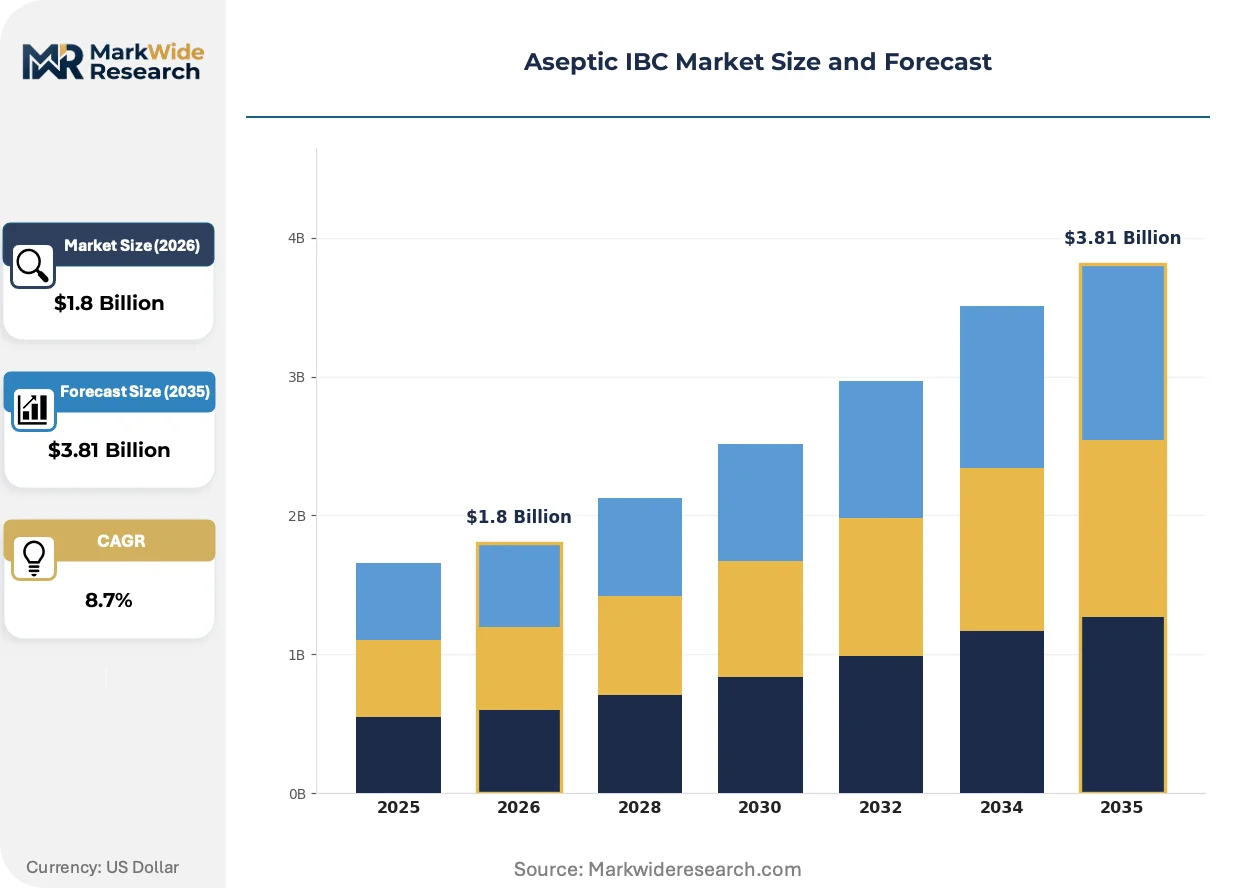
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic IBC Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Plastic, Composite, Aluminum Application: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals End User: Food Processors, Drug Manufacturers, Cosmetic Brands, Chemical Companies Technology: Closed Systems, Open Systems, Vacuum Systems, Pressure Systems |
| Companies Covered | Schoeller Allibert, Greif Inc., Mauser Group, Schütz GmbH & Co. KGaA, Berry Global Inc., Thielmann US LLC, SCHÄFER Container Systems, DS Smith, Snyder Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic IBC Market Strategic Shifts
Material science advances and regulatory digitization are compressing the traditional tradeoff between stainless steel durability and plastic-format flexibility, enabling new hybrid architectures that challenge established supplier hierarchies.
Electropolished 316L stainless steel with enhanced surface passivation is supplanting standard-grade fabrication in high-value injectable applications. Contract manufacturers serving oncology and rare disease biologics are specifying these premium formats despite 40% first-cost premiums, as the technology is supplanting multi-decade service life assumptions and reducing steam-in-place cycle frequencies by half.
REACH authorization timelines for cobalt-containing alloys are accelerating substitution toward nickel-free stainless formulations in European pharmaceutical supply chains. The industrial consequence is a qualification bottleneck for alternative metallurgies, with German and Swiss fabricators investing in electron beam welding to certify chromium-manganese grades that satisfy both ECHA substance restrictions and ASME pressure vessel standards.
Biopharma procurement teams are consolidating vendor panels around full-service IBC lifecycle providers rather than discrete equipment transactions. Contract research organizations and emerging biotechs in the Boston-Cambridge corridor are displacing traditional capital purchase models with subscription-based container pooling, transferring sanitization liability and validation documentation burden to specialized third-party operators.
Aseptic IBC Market Segmentation
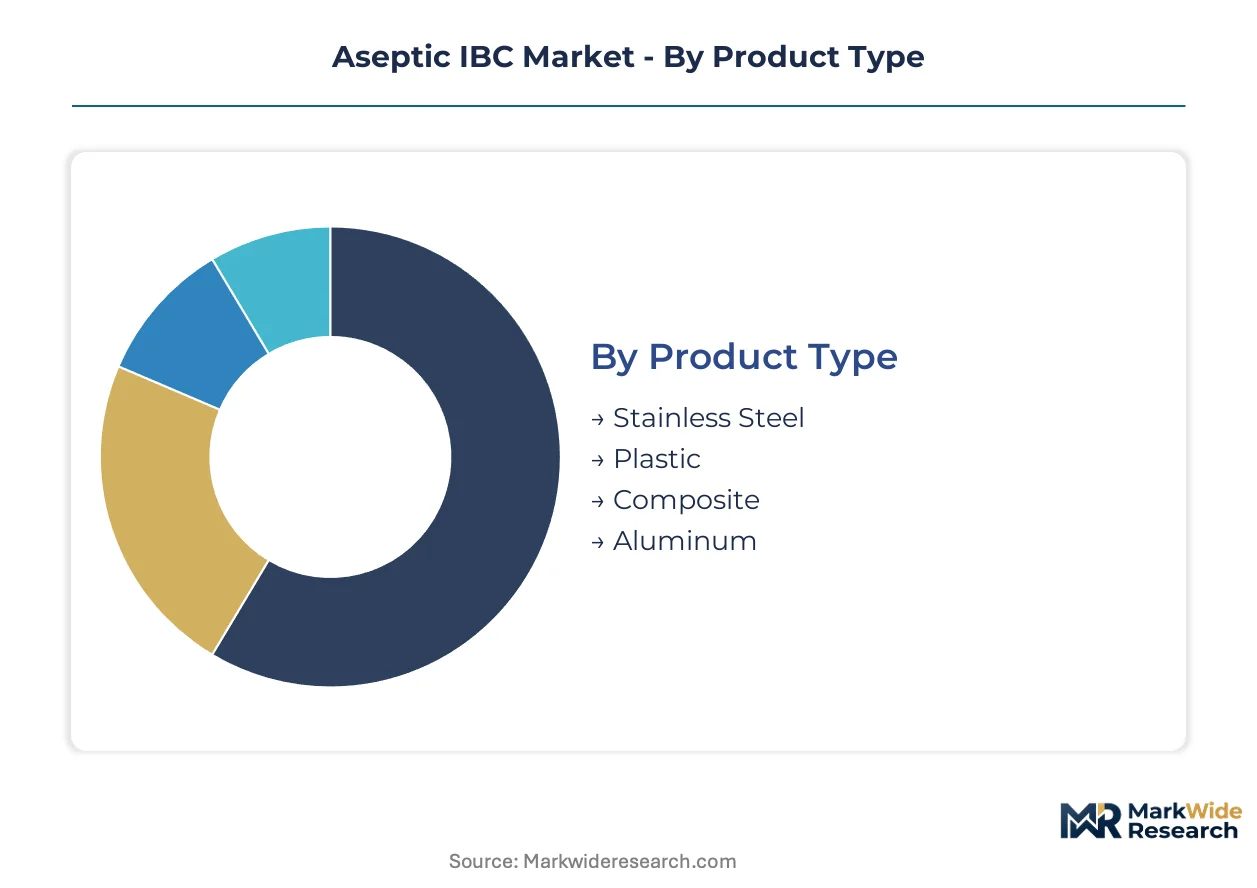
Aseptic IBC segmentation reveals divergent margin architectures across material formats and sterility technologies. Pharmaceutical-grade stainless steel commands premium pricing through validation-intensive procurement, while food-sector plastic variants compete on throughput economics and sanitization energy efficiency.
Product Type:
Margin pools concentrate in validated stainless steel formats where ASME certification and steam-in-place protocols create pricing power, while plastic variants compete on volume turnover in dairy and beverage applications.
- Stainless Steel:Electropolished 316L fabrication dominates injectable drug logistics, with surface passivation reducing steam-in-place cycle frequencies. German and Swiss metalworking clusters in North Rhine-Westphalia anchor supply for EMA Annex 1-compliant biologics manufacturers facing tightened container closure integrity mandates.
- Plastic:Gamma-irradiation-compatible polymers capture cell and gene therapy workflows requiring rapid turnaround between autologous batches. Lightweight tare weight reduces freight costs for high-frequency dairy processors, though REACH authorization timelines for cobalt-containing additives are accelerating nickel-free formulation shifts.
- Composite:Hybrid architectures merge chemical resistance with thermal stability for vaccine cold chain applications.
- Aluminum:Specialized formats serve cosmetic aerosol propellant handling where pressure vessel weight reduction matters.
Stainless steel holds installed capacity. Composite is rotating up the share rankings.
Application:
Application segmentation tracks divergent regulatory stringency, with pharmaceutical sterilization standards creating defensible margin tiers unavailable to food and beverage processors.
- Food & Beverage:High-throughput dairy and juice processors prioritize plastic IBC formats for lighter tare weight and lower sanitization energy burden. EU Green Deal reusable container mandates are spilling from food processing into adjacent sectors, rewarding certified circular economy protocols.
- Pharmaceuticals:Biologics manufacturers consolidate supply bases around closed-system formats as FDA 21 CFR Part 211 and EMA Annex 1 revisions compress validation timelines. Endotoxin and particulate contamination risks that batch-release protocols cannot tolerate make open-format exposure unacceptable.
- Cosmetics:Premium skincare and fragrance brands specify aluminum and composite formats for propellant handling and aesthetic packaging integration.
- Chemicals:Specialty chemical producers balance corrosion resistance against capital recovery periods in lower-frequency batch operations.
Food and beverage contributes volume scale. Pharmaceuticals delivers margin concentration.
End User:
End user segmentation maps procurement sophistication, with drug manufacturers demanding full-service lifecycle partnerships while food processors prioritize equipment transactions.
- Food Processors:Dairy and beverage manufacturers optimize for total cost of ownership across sanitization cycles and freight economics.
- Drug Manufacturers:Contract research organizations and emerging biotechs in the Boston-Cambridge corridor are displacing capital purchase models with subscription-based container pooling, transferring validation documentation burden to specialized operators.
- Cosmetic Brands:Premium positioning drives specification of specialized aluminum and composite formats for brand-aligned packaging aesthetics.
- Chemical Companies:Batch chemical producers amortize IBC investment across lower-frequency operations, prioritizing chemical compatibility over sterility validation.
Drug manufacturers anchor premium pricing. Food processors drive volume throughput.
Technology:
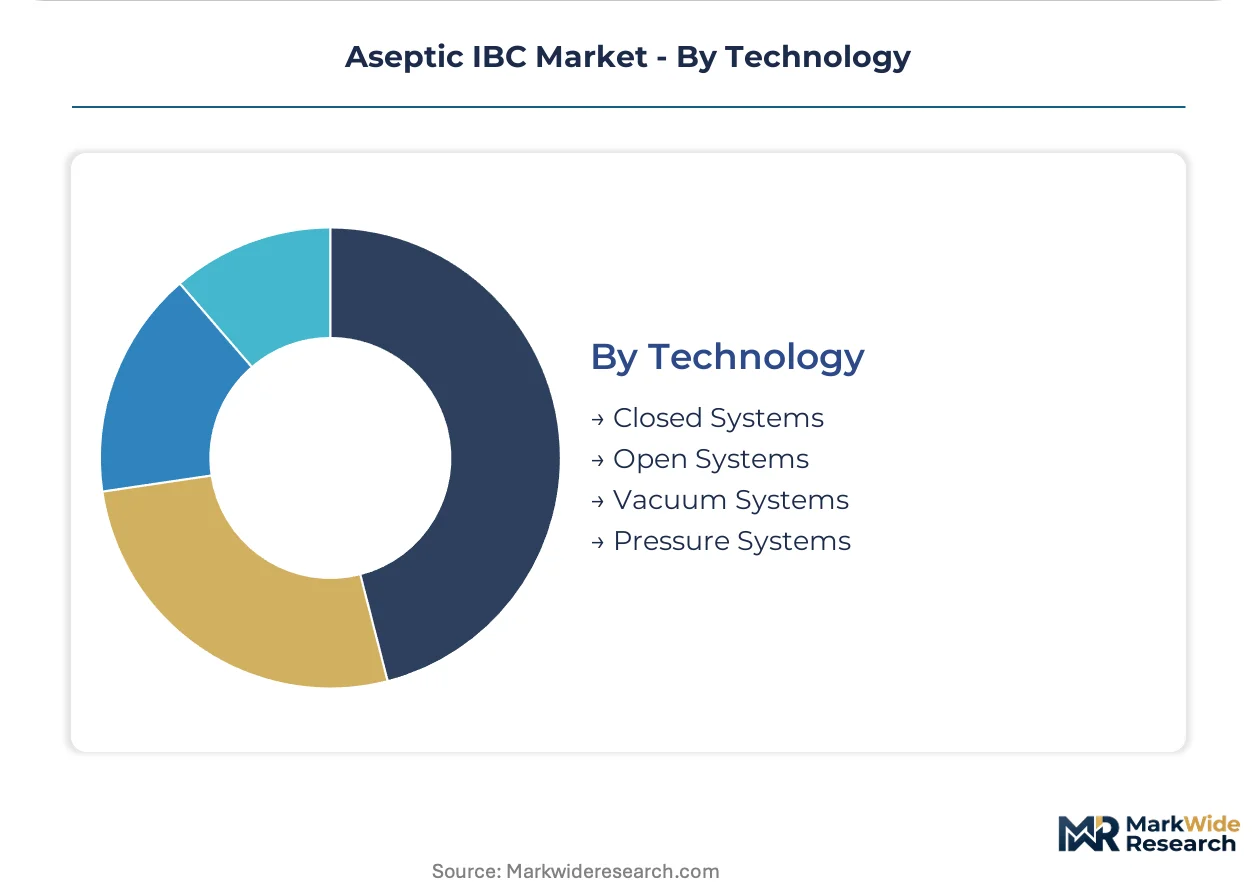
Technology segmentation reflects the hierarchy of contamination risk, with closed systems commanding definitive positioning in biologics handling where open-format exposure invites regulatory rejection.
- Closed Systems:Sealed vessel architectures with ISO 5 or ISO 7 cleanliness maintenance dominate biologics handling. FDA and EMA sterilization standards are tightening validation requirements, compelling container suppliers to document particulate shedding and bioburden baselines or exit pharmaceutical-grade segments.
- Open Systems:Lower-cost formats serve chemical and cosmetic applications where environmental exposure risks are manageable through procedural controls rather than engineered containment.
- Vacuum Systems:Specialized formats for oxygen-sensitive pharmaceutical and cosmetic formulations.
- Pressure Systems:ASME-certified fabrication for propellant handling and carbonated beverage applications.
Closed systems command technology hierarchy. Vacuum formats are climbing fastest in specialty pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss metalworking clusters where EMA Annex 1 validation commands premium margins, while Indian and Chinese fabricators compete on throughput economics for food-grade plastic formats.
Germany
North Rhine-Westphalia hosts concentrated molding and metalworking capabilities that enable rapid prototyping of hybrid IBC designs for biopharma clients. EMA Annex 1 revisions mandate container closure integrity testing, compelling local suppliers to document particulate shedding baselines. Schoeller Allibert and Schütz GmbH maintain advanced manufacturing clusters in this region, shortening qualification timelines for European pharmaceutical manufacturers.
United States
FDA 21 CFR Part 211 enforcement is elevating documentation requirements for reusable vessel validation, driving replacement demand among injectable drug logistics operators. The Boston-Cambridge corridor hosts emerging biotechs displacing capital purchase models with subscription-based container pooling. Thielmann US LLC anchors ASME-certified stainless steel fabrication capacity for domestic biologics manufacturers facing compressed validation timelines.
India
CDSCO accelerated approval pathways for biosimilars are attracting contract manufacturing organizations requiring aseptic IBC infrastructure without legacy European supplier relationships. The country's national pharmaceutical regulator is aligning sterilization standards with international benchmarks to facilitate export-oriented production. Maharashtra and Gujarat host emerging fabrication capacity serving both domestic biologics manufacturers and multinational supply chain diversification strategies.
Switzerland
Swissmedic oversight of sterile manufacturing creates exacting validation requirements that reward suppliers with established quality management systems. Geneva and Basel pharmaceutical clusters demand electropolished 316L formats for high-value oncology and rare disease biologics. Local metalworking specialists invest in electron beam welding to certify chromium-manganese grades satisfying both ECHA substance restrictions and ASME pressure vessel standards.
China
NMPA biologics manufacturing expansion is driving demand for closed-system aseptic containers in vaccine and biosimilar production. The country's dual carbon goals are pressuring energy-intensive stainless steel fabrication toward process efficiency improvements. Yangtze River Delta pharmaceutical clusters are consolidating supplier relationships around domestic IBC providers capable of ISO 14644 cleanroom certification.
Aseptic IBC Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with stainless steel specialists commanding validation-intensive pharmaceutical premiums while plastic-format producers compete on food-sector throughput economics. The market structure reflects this bifurcation: ASME-certified fabricators occupy defensible positions in injectable drug logistics, gamma-irradiation-compatible polymer suppliers capture cell and gene therapy workflows, and hybrid-format innovators challenge established hierarchies at the material science frontier. Dominant competitive moves include geographic expansion into Indian biologics manufacturing and portfolio diversification toward full-service lifecycle partnerships that transfer sanitization liability to specialized operators.
Among European-based fabricators, Schoeller Allibert exemplifies the plastic-format archetype with molded container expertise, while Schütz GmbH & Co. KGaA occupies a position within the hybrid validation protocol segment. Thielmann US LLC represents the ASME-certified stainless steel specialization that anchors premium-tier positioning in North American pharmaceutical supply chains. These three company structures illustrate the geographic and technological stratification defining competitive positioning across the market.
| Leading Market Players |
|---|
| Schoeller Allibert |
| Greif Inc. |
| Mauser Group |
| Schütz GmbH & Co. KGaA |
| Berry Global Inc. |
| Thielmann US LLC |
| SCHÄFER Container Systems |
| DS Smith |
| Snyder Industries |
| Others |
Value Chain & Pricing Dynamics
FDA 21 CFR Part 211 and EMA Annex 1 validation protocols gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified fabricators while rewarding ASME-certified specialists with configured-to-order premiums. Pharmaceutical buyers absorb 40% first-cost premiums for electropolished 316L formats because steam-in-place validation documentation creates switching costs that standard-grade competitors cannot undercut.
Pricing Analysis
The customization-premium spread separates configured-to-order ASME-certified stainless steel vessels from standard plastic-format catalogs, with electropolished 316L fabrication commanding three-tier pricing structure across premium, standard, and economy levels based on surface passitation grade and validation documentation depth. Price differentiation hinges on steam-in-place certification tier and geographic delivery cost from German metalworking clusters. Cost compression in gamma-irradiation-compatible polymers is intensifying because REACH authorization timelines for cobalt-containing additives are forcing nickel-free formulation shifts. Food processors exhibit highest price sensitivity due to throughput economics, while oncology biologics manufacturers show lowest sensitivity due to batch-release risk tolerance thresholds.
Supply Chain Analysis
Just-in-time inventory strategies dominate pharmaceutical-grade procurement where validation documentation must accompany each vessel delivery, though strategic stockpiling of nickel and chromium-manganese alloys persists among German and Swiss fabricators facing ECHA substance restriction uncertainty. Geographic supply concentration centers on Germany, Switzerland, and the United States for ASME-certified metal fabrication, while China and India host emerging plastic-format molding capacity. Raw material dependencies draw from nickel ore, 316L stainless steel billet, and gamma-irradiation-compatible polymer resins. Single-source vulnerability in electropolished surface treatment capacity creates supply chain risk. Distribution runs through specialized third-party container pooling operators serving the Boston-Cambridge biotech corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as cell and gene therapy workflows displace standardized procurement toward autologous-batch container configurations. Contract manufacturers now demand rapid-turnaround validation protocols that legacy stainless steel specialists cannot fulfill without infrastructure duplication.
For Market Incumbents: Shield pharmaceutical-grade margin pools by deepening captive supply of electron beam welding capacity for chromium-manganese certification, insulating against ECHA substance restriction migration. Consolidate around full-service lifecycle partnerships that transfer sanitization liability to specialized operators, neutralizing emerging biotech subscription-based procurement preferences that displace capital purchase models.
For New Entrants and Emerging Players: Differentiate on gamma-irradiation-compatible polymer rapid-turnaround protocols for autologous therapy production, where lightweight tare weight and batch-specific validation documentation create white-space opportunity against stainless steel incumbents. Target Indian CDSCO-aligned contract manufacturing organizations requiring aseptic IBC infrastructure without legacy European supplier relationships. Pursue digital twin integration with RFID-enabled tracking as primary go-to-market angle.
For Investors and Strategic Acquirers: EMA Annex 1 revision reshapes the acquisition landscape toward validation-intensive lifecycle service providers rather than discrete equipment fabricators, favoring long-term viability across the projection horizon for operators with documented particulate shedding baselines. Target acquisition archetype: mid-cap specialists with captive ISO 14644 cleanroom certification and existing pharmaceutical client relationships. Watch for CDSCO alignment with international sterilization benchmarks as inflection indicator for Indian manufacturing capacity valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Validation Documentation Investment | Creates defensible pricing power against uncertified competitors in biologics supply chains. |
| Gamma-Irradiation-Compatible Polymer Capacity Expansion | Captures cell and gene therapy workflows requiring rapid autologous batch turnaround. |
| RFID-Enabled Digital Twin Integration | Generates recurring service revenue beyond hardware sales for temperature-sensitive vaccine logistics. |
| Indian Manufacturing Footprint Establishment | Positions for CDSCO-aligned biosimilar contract manufacturing organization demand. |
| Electron Beam Welding Certification for Chromium-Manganese Grades | Satisfies ECHA substance restrictions while maintaining ASME pressure vessel standards. |
Study Parameters
A spread of perspectives from IBC fleet managers, pharmaceutical quality assurance directors, cleanroom sanitation technicians, and contract manufacturing procurement leads converged on the working assumptions driving segmentation and growth estimates. Primary interviews with stainless steel fabricators and polymer molding specialists combined with secondary validation from FDA 21 CFR Part 211 guidance documents, EMA Annex 1 revision drafts, ISO 14644 cleanroom classification standards, and ASTM D4169 distribution simulation protocols. Bottom-up vessel shipment analysis and top-down biologics manufacturing capacity triangulation anchored volume estimates.
Segmentation dimensions modeled include material format, sterility technology, application sector, and end-user procurement sophistication across the analysis window. CAGRs derived from regression against biologics manufacturing capacity expansion, regulatory validation timeline compression, and single-use substitution elasticity. Forecast inputs incorporated CDSCO approval pathway acceleration, EU Green Deal reusable container mandate spillover, and nickel price volatility scenarios.
Material uncertainties — regulatory interpretation divergence between FDA and EMA, REACH authorization timeline acceleration, single-use flexible film substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about validation documentation standardization and cleanroom technician training pipeline capacity. Revision becomes warranted when container closure integrity testing mandate enforcement crosses thresholds that trigger fleet replacement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market