
 Retort Grade BOPET Films Market | 2026-2036
Retort Grade BOPET Films Market Size, Share, and Industry Trends Forecast 2026-2036
Retort Grade BOPET Films Market Analytics
Polyamide is repositioning conventional multilayer structures in high-barrier retort applications, altering cost-performance trade-offs across the supply chain. Toray Industries leverages its integrated resin-to-film operations to sustain pricing power in specialty co-extruded grades. UFlex Limited anchors its competitive stance through backward integration into resin compounding and extensive South Asian distribution. DuPont Teijin Films differentiates via proprietary surface-treatment chemistries that extend bond strength in aggressive retort cycles.
Retort grade BOPET films are biaxially oriented polyethylene terephthalate films engineered to withstand sterilization temperatures exceeding 121°C while maintaining dimensional stability, optical clarity, and oxygen barrier below 0.5 cc/m²/day. These films serve as the structural backbone in retort pouches, lidding structures, and pharmaceutical blister packs where thermal processing and extended shelf life converge. Transparent films dominate current volume owing to their ubiquity in food packaging windows, though metallized variants command premium positioning in ultra-high-barrier pharmaceutical and military ration applications. Co-extruded multilayer structures represent the fastest-growing product configuration as brand owners pursue downgauging without sacrificing seal integrity or thermal resistance.
FDA food-contact notifications and EU REACH compliance govern migration limits and monomer purity requirements for retort-grade films destined for consumable and medical end uses. China's GB standards and NMPA pharmaceutical packaging directives impose additional testing protocols that filter market access for non-domestic suppliers. BIS certification in India and Japan's JIS quality benchmarks further fragment compliance obligations across major manufacturing hubs. Stakeholders must monitor regulatory divergence on per- and polyfluoroalkyl substance restrictions, as pending amendments to European F-Gas Regulation and corresponding EPA evaluations could force reformulation of certain high-performance barrier coatings.
Market Dynamics
Co-extruded multilayer architectures are absorbing capital allocation from legacy monolayer film lines as brand owners pursue downgauging without thermal performance degradation. This structural pivot concentrates investment among integrated resin-to-film operators capable of precise layer thickness control across aggressive retort cycles.
Growth Catalysts
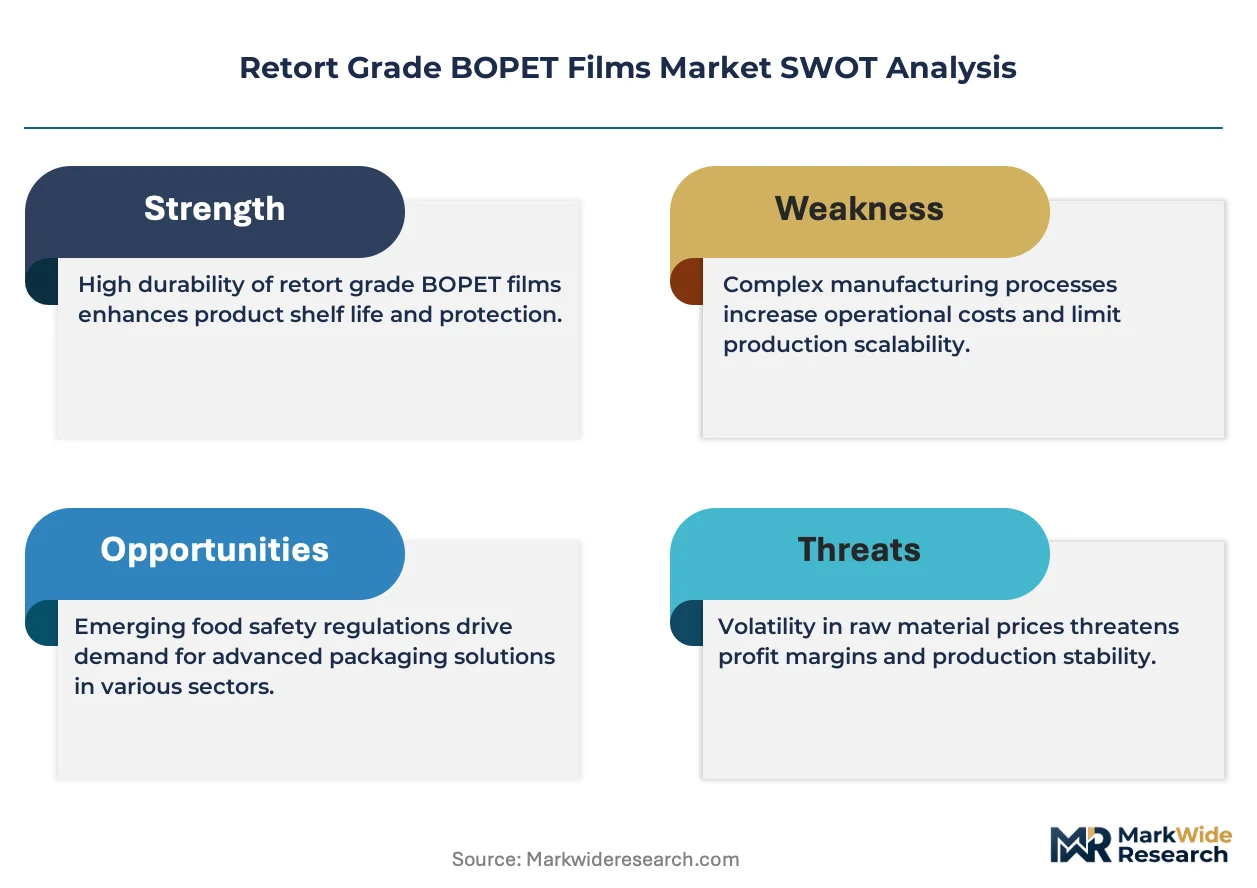
- EU F-Gas Regulation amendments:Pending restrictions on fluorinated barrier coatings are accelerating reformulation toward silicon oxide and aluminum oxide vapor-deposited alternatives in pharmaceutical blister pack applications.
- Ready-to-eat meal packaging:Military ration programs and civilian emergency food stockpiles in China and the US are expanding procurement specifications for transparent high-barrier retort pouches.
- NMPA pharmaceutical directives:China's tightened extractables and leachables testing protocols for blister pack substrates are filtering out non-compliant imports and privileging domestic certified suppliers.
Market Restraints
- Ethylene glycol price volatility:Crude oil-linked feedstock costs compress margin predictability for non-integrated film converters lacking captive PTA or MEG production.
- Supply concentration in East Asian resin:Over 70 percent of specialty PET chip capacity for retort grades clusters in China, Japan, and South Korea, creating geographic single-source exposure.
- Polyamide substitution in high-barrier laminates:Nylon 6 and MXD6 films are capturing share in ultra-high-barrier retort applications where oxygen transmission below 0.1 cc/m²/day is mandatory.
Strategic Opportunities
- India BIS certification gap:Domestic retort pouch processors face limited local supply of certified BOPET films, creating white space for import substitution by certified regional producers.
- Aluminum oxide coating convergence:Hybrid physical vapor deposition and plasma-enhanced chemical vapor deposition systems are enabling single-film barrier performance previously requiring metallized laminates.
- EU Green Deal packaging mandates:Recyclability-by-design requirements for 2030 are privileging mono-material PET structures over multi-polymer laminates in food contact applications.
Industry Challenges
- Retort cycle simulation expertise:Qualified technicians capable of correlating accelerated aging tests with real-world 121°C sterilization performance remain scarce outside major integrated producers.
- Dual certification timeline compression:Simultaneous FDA food-contact notification and EU REACH compliance documentation for new co-extruded grades extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retort Grade BOPET Films Market |
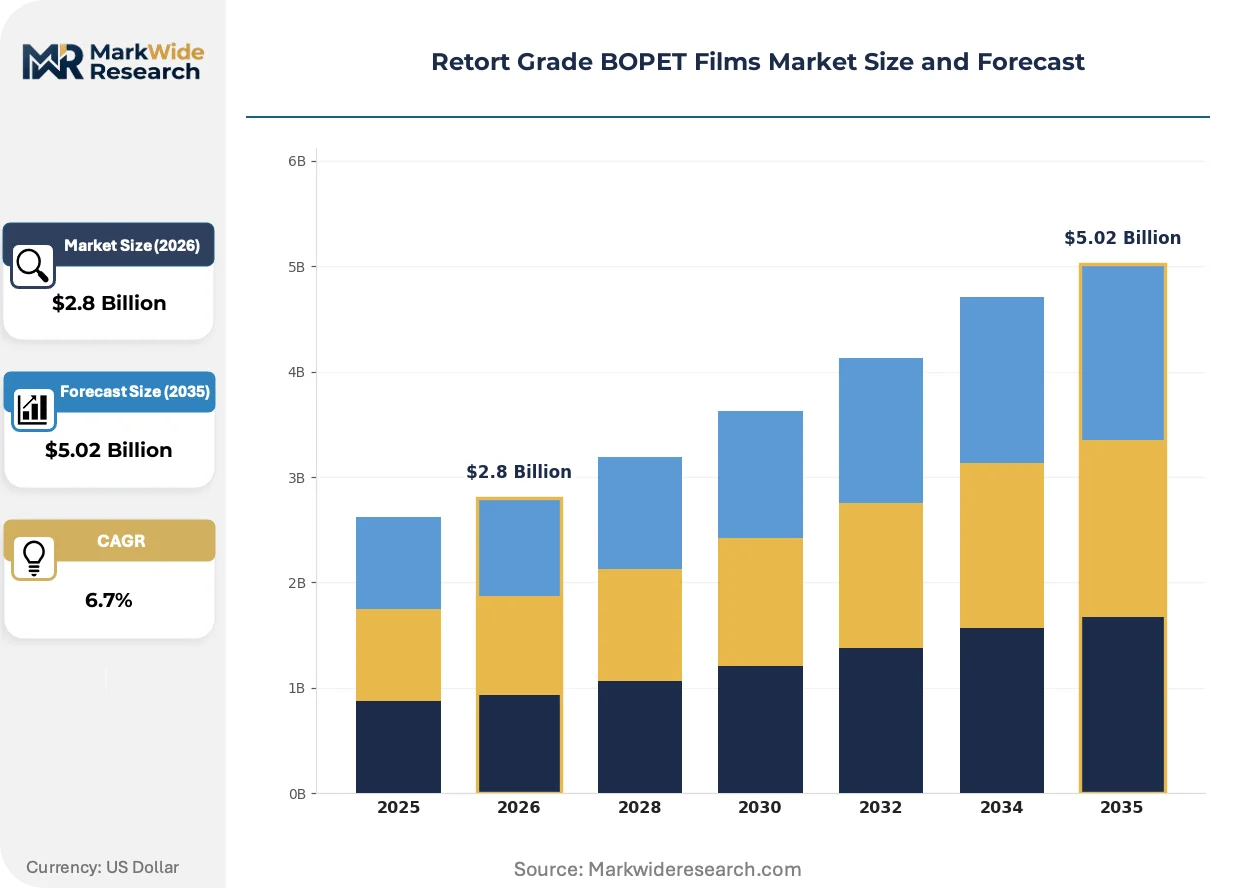
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Metallized, Co-extruded, Specialty Application: Food Packaging, Utensils, Medical Supplies, Industrial Uses Delivery Mode: Roll, Sheet, Custom Size, Bulk End User: Food Industry, Pharmaceutical, Electronics, Others |
| Companies Covered | Toray Industries, Inc., UFlex Limited, Polyplex Corporation Ltd., SRF Limited, Jindal Poly Films Ltd., DuPont Teijin Films, Mitsubishi Polyester Film, Inc., SKC, Ltd., Indorama Ventures Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retort Grade BOPET Films Market Evolving Landscape
Surface functionalization chemistries and deposition technologies are converging to redefine barrier performance benchmarks without fluorinated additives. These advances are compressing the traditional trade-off between optical clarity and oxygen impermeability.
Silicon oxide-coated BOPET films are absorbing share from metallized alternatives in pharmaceutical cold-form blister applications where pinhole sensitivity and flex-crack resistance determine shelf-life outcomes. European generic drug packagers are adopting these grades at accelerating rates. The technology is absorbing investment from vapor-deposition equipment suppliers who previously served display and semiconductor markets.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of high-performance barrier coatings ahead of formal European Chemicals Agency listings. Industrial consequence includes qualification delays for incumbent Asian exporters and accelerated partnerships between film producers and plasma-coating equipment specialists. Pharmaceutical packaging lines in Germany and the Netherlands are most affected, with converters stockpiling certified legacy grades while validating oxide-coated replacements.
Brand-owner specification consolidation is compressing approved vendor lists from regional fragmentation toward global qualification frameworks. Food multinationals are centralizing substrate approvals at headquarters level, replacing historically decentralized procurement. This concentration is most visible in North American and Western European ready-meal segments, where three global packagers now dictate technical standards across their supplier networks.
Retort Grade BOPET Films Market Segmentation
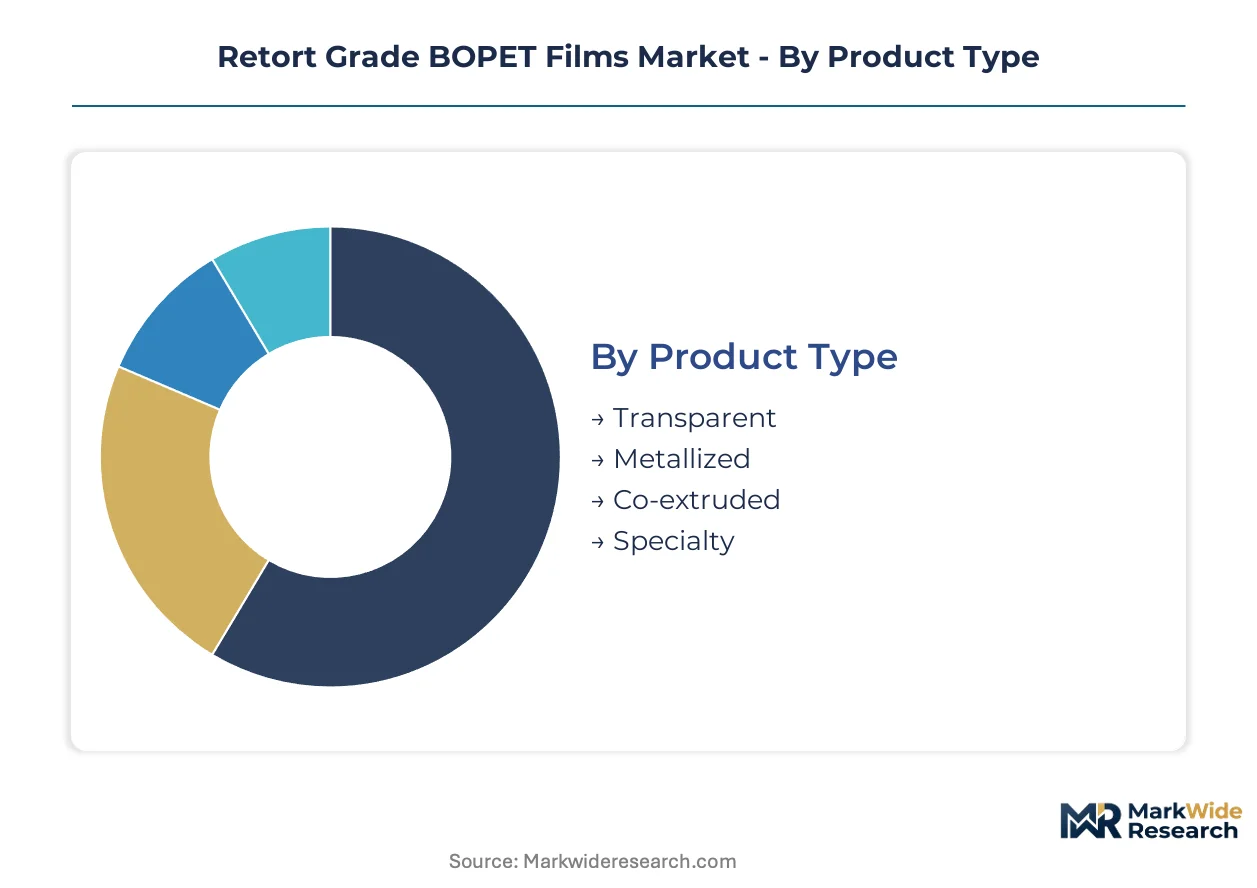
Retort grade BOPET films serve divergent performance requirements across sterilization temperatures, barrier specifications, and optical demands. Segmentation reveals where technical premiumization concentrates versus where commodity substitution threatens margin structures.
Product Type:
Transparent films anchor volume throughput while metallized and co-extruded variants capture margin expansion through barrier specialization.
- Transparent:Standard biaxially oriented PET films maintain dimensional stability above 121°C sterilization cycles. Demand concentrates in China's ready-to-eal meal export sector where optical clarity for product visibility drives specification. FDA food-contact compliance costs filter smaller regional converters.
- Metallized:Aluminum vapor-deposited layers achieve oxygen transmission below 0.1 cc/m²/day for military ration and pharmaceutical applications. European packagers facing REACH fluorinated substance restrictions are accelerating validation of metallized alternatives to oxide-coated grades.
- Co-extruded:Multilayer architectures enable downgauging without thermal performance loss through precise tie-layer engineering.
- Specialty:Surface-treated or chemically modified grades for aggressive retort chemistries and extended shelf-life protocols.
Today's leader: Transparent. Tomorrow's challenger: Co-extruded.
Application:
Food packaging dominates procurement tonnage while medical and industrial applications impose stricter extractables testing regimes.
- Food Packaging:Retort pouches, lidding films, and tray structures for thermally processed meals. China's NMPA-aligned food safety protocols and US military SPECS procurement are tightening supplier qualification requirements simultaneously.
- Medical Supplies:Pharmaceutical blister packs and sterilizable device packaging where leachables testing under USP 661 and EP 3.1 standards governs substrate selection. German and Dutch generic drug packagers are stockpiling certified grades ahead of REACH fluorinated coating bans.
- Utensils:Heat-resistant disposable and reusable cutlery films requiring lower barrier specifications.
- Industrial Uses:Protective masking and process films where thermal resistance exceeds optical requirements.
Food packaging commands current volume leadership. Medical supplies are climbing the fastest as regulatory barriers elevate pricing power for certified suppliers.
Delivery Mode:
Roll format aligns with high-speed converting economics while custom sizing captures premium from short-run pharmaceutical and specialty food processors.
- Roll:Standard mill-width rolls for continuous converting operations. Integrated resin-to-film producers in Japan and South Korea optimize roll formats for just-in-time delivery to Southeast Asian pouch converters.
- Sheet:Cut-to-dimension formats for manual packaging lines and prototype development. Indian pharmaceutical contract manufacturers source sheets to avoid capital investment in slitting equipment.
- Custom Size:Width and gauge specifications for proprietary forming and sealing equipment. European medical device packagers specify custom dimensions to minimize trim waste in cleanroom environments.
- Bulk:Palletized loose film for reprocessing and compounding operations.
Roll formats sustain cost leadership. Custom sizing is expanding most quickly as brand-owner specification consolidation reduces standardization.
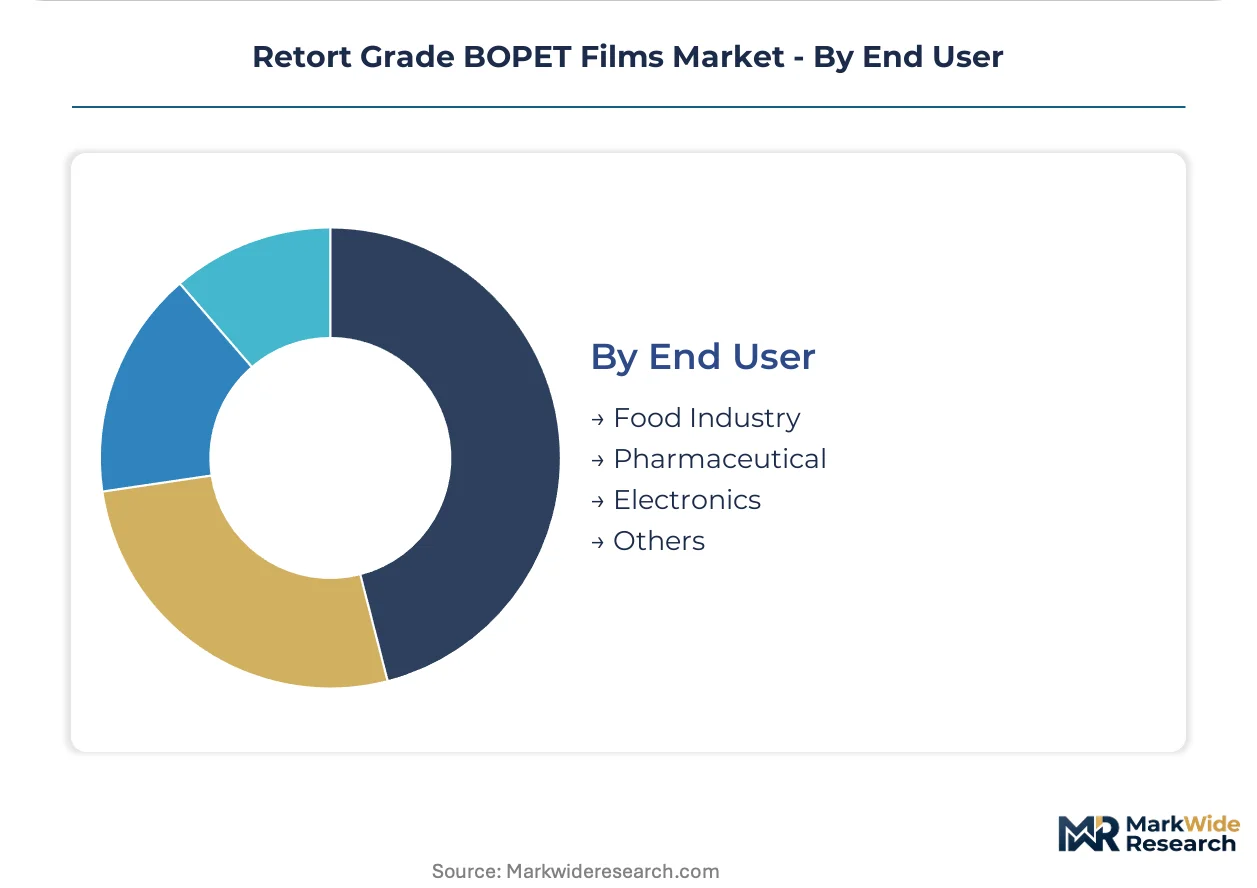
End User:
Food industry procurement runs on total delivered cost while pharmaceutical buyers weight certification durability and audit traceability more heavily.
- Food Industry:Ready-meal processors, military ration suppliers, and emergency stockpile managers. US Defense Logistics Agency and China's civilian emergency reserve programs are expanding transparent high-barrier pouch specifications in parallel.
- Pharmaceutical:Blister pack converters and sterile barrier system manufacturers. India's CDSCO and BIS certification gaps are forcing domestic processors to rely on certified imports from Thailand and Malaysia.
- Electronics:Component protection films where thermal stability supports solder reflow and sterilization processes.
- Others:Cosmetic, chemical, and agricultural applications with niche sterilization or barrier requirements.
Food industry retains volume dominance. Pharmaceutical end-use is gaining share fastest as extractables testing protocols proliferate across regulatory jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors retort pouch manufacturing capacity expansion, with domestic Chinese processors scaling sterile food packaging lines for export markets. FDA and EU REACH compliance costs filter smaller regional converters across all major production hubs.
China
NMPA pharmaceutical directives tighten extractables testing for blister pack substrates, privileging certified domestic suppliers. GB standards for food-contact materials impose additional migration limit protocols. Shanghai and Jiangsu province concentrate specialty PET chip capacity for retort grades, with local processors expanding military ration pouch output for civilian emergency stockpiles.
United States
Defense Logistics Agency procurement specifications drive transparent high-barrier retort pouch demand for military ration programs. FDA food-contact notification requirements extend qualification timelines for imported co-extruded grades. Midwest converting clusters around Chicago and Minneapolis serve ready-meal processors with just-in-time roll supply.
Germany
ECHA REACH restrictions on fluorinated barrier coatings force reformulation toward oxide-deposited alternatives in pharmaceutical blister applications. German generic drug packagers stockpile certified legacy grades while validating silicon oxide-coated replacements. The Ruhr industrial corridor hosts plasma-coating equipment specialists partnering with film producers on qualification cycles.
India
BIS certification gaps in retort-grade BOPET supply create import dependence for domestic pouch processors. CDSCO pharmaceutical packaging directives align with tightening global extractables standards. Maharashtra and Gujarat host emerging converting capacity, though certified film supply remains concentrated among Thai and Malaysian exporters.
Japan
JIS quality benchmarks and METI industrial standards maintain premium positioning for domestic resin-to-film operators. Japanese integrated producers optimize roll formats for just-in-time delivery to Southeast Asian pouch converters. The Chubu region around Nagoya concentrates biaxial orientation line technology and retort cycle simulation expertise.
Retort Grade BOPET Films Market Competitive Landscape
Global majors compete with regional champions across resin-to-film integration depth, with East Asian conglomerates facing rising South Asian specialists. The vendor base stratifies into three tiers: integrated petrochemical-to-film operators controlling specialty PET chip supply, mid-scale converters with captive compounding, and toll-coating specialists dependent on merchant resin. Two strategic archetypes dominate: backward-integrated resin producers sustaining pricing power through captive feedstock, and coating technology licensors capturing premium via surface functionalization IP. Competitive moves concentrate on co-extrusion line capacity expansion and strategic partnerships with plasma-deposition equipment suppliers.
Among integrated Japanese and South Korean fabricators, Toray Industries, Inc., SKC, Ltd., and Mitsubishi Polyester Film, Inc. occupy positions defined by captive resin supply and precision layer thickness control. These entities exemplify the archetype of petrochemical-backed film operators leveraging upstream integration into specialty PET polymerization. Indian and Southeast Asian specialists including UFlex Limited and Polyplex Corporation Ltd. represent regional champions building competitive stance through distribution density and import substitution in undercertified markets. DuPont Teijin Films sits within the technology-licensor tier, with its positioning derived from proprietary surface-treatment chemistries rather than resin integration.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| UFlex Limited |
| Polyplex Corporation Ltd. |
| SRF Limited |
| Jindal Poly Films Ltd. |
| DuPont Teijin Films |
| Mitsubishi Polyester Film, Inc. |
| SKC, Ltd. |
| Indorama Ventures Ltd. |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging mandates for 2030 recyclability targets are gating qualified supply of mono-material PET structures and premium-tier pricing access for certified retort grade films. Brand owners now face dual certification costs that filter non-compliant converters from contract eligibility.
Pricing Analysis
Ethylene glycol and purified terephthalic acid cost pass-through dominates pricing volatility for non-integrated converters lacking captive resin production. Three-tier pricing structure across premium, standard, and economy levels separates FDA-EU dual-certified co-extruded grades from single-market compliant films and commodity transparent rolls. Price differentiation hinges on certification tier and volume scale, with pharmaceutical blister pack specifications commanding substantial premiums over food packaging grades. Pricing pressure stems from polyamide substitution in ultra-high-barrier applications where oxygen transmission below 0.1 cc/m²/day is mandatory. Food industry procurement runs highest price sensitivity, while pharmaceutical buyers absorb premium tier costs for audit traceability and leachables documentation.
Supply Chain Analysis
Regional distribution centers in Shanghai, Nagoya, and Seoul anchor hub-and-spoke patterns serving Southeast Asian pouch converters with just-in-time roll formats. Geographic supply concentrates in China, Japan, and South Korea, where over 70 percent of specialty PET chip capacity for retort grades clusters. Raw material dependencies draw from crude oil-linked ethylene glycol, purified terephthalic acid, and specialty co-extrusion tie-layer resins. Single-source vulnerability pervades East Asian resin supply, with limited alternative qualified capacity outside the Yangtze River Delta and Chubu region. Distribution runs through integrated resin-to-film operators who control both polymerization and biaxial orientation assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort grade BOPET films constitute a late-cycle quality story as military ration programs and pharmaceutical blister pack specifications shift demand toward premium certified grades with extended qualification timelines.
For Market Incumbents: Cement pricing power through backward integration into captive specialty PET polymerization and precision co-extrusion line capacity expansion in Jiangsu province. Polyamide substitution in ultra-high-barrier applications threatens margin structures in military and pharmaceutical segments. Dual certification investment for FDA food-contact notification and EU REACH compliance serves as the primary defensive lever against regional import substitution. For New Entrants and Emerging Players: Begin with India's BIS certification gap, where domestic pouch processors face constrained local supply of qualified retort grade films. Maharashtra and Gujarat converting clusters present the most penetrable geography. Thailand and Malaysian exporters currently dominate this white space. A go-to-market angle anchored in CDSCO-aligned pharmaceutical packaging certification captures premium positioning absent from commodity food-grade competition. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale converters with captive compounding because certification barriers and 18-24 month qualification cycles protect incumbent revenue streams from rapid commoditization. Long-term viability centers on surface functionalization IP and plasma-deposition equipment partnerships rather than resin-scale alone. Watch for ECHA REACH amendments on fluorinated barrier coatings as the inflection signal for oxide-coated technology adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty PET Polymerization | Toray Industries and SKC sustain margin control through captive resin supply against merchant feedstock volatility. |
| Plasma-Enhanced Chemical Vapor Deposition Partnership | DuPont Teijin Films leverages Ruhr corridor equipment specialists to validate silicon oxide barrier coatings ahead of REACH restrictions. |
| Dual Certification Investment for FDA and EU REACH | UFlex Limited anchors South Asian competitive stance through documented compliance for pharmaceutical blister pack exports. |
| Co-Extrusion Line Capacity Expansion | Polyplex Corporation addresses India's BIS certification gap with regional production of qualified multilayer structures. |
| Just-in-Time Roll Format Optimization | Mitsubishi Polyester Film serves Southeast Asian converters through Nagoya-hub distribution minimizing inventory carrying costs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at biaxial orientation facilities, procurement leads at retort pouch converters, pharmaceutical packaging technical directors, and plasma-coating equipment specialists. Secondary validation drew from customs and trade data, FDA food-contact notification filings, ECHA REACH substance registrations, and NMPA pharmaceutical packaging directives. Bottom-up resin capacity modeling and top-down end-use demand estimation provided cross-check triangulation.
Segment-weighting across product type, application, delivery mode, and end user dimensions drove analytical framework construction over the projection horizon. Transparent, metallized, co-extruded, and specialty film grades each carried distinct barrier specification and certification cost assumptions. Food packaging, medical supplies, utensils, and industrial uses received separate growth trajectory modeling based on sterilization temperature requirements and extractables testing protocols. CAGRs derived from correlating installed biaxial orientation line capacity with qualified demand expansion across military ration, ready-meal, and pharmaceutical blister pack segments.
Several conditions sit outside the modeled scope, including pending amendments to European F-Gas Regulation and corresponding EPA evaluations that could force reformulation timelines. Forecasts reflect documented assumptions on resin price pass-through rates and qualification cycle durations. Ethylene glycol price volatility, polyamide substitution acceleration, and regulatory divergence on per- and polyfluoroalkyl substance restrictions present specific revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market