
 Retort Films Market | 2026-2036
Retort Films Market Size, Share, and Industry Trends Forecast 2026-2036
Retort Films Market Analytics
Polymer compounding expertise is reorganizing competitive dynamics across the retort films value chain, as specialized extrusion and coextrusion capabilities remain scarce outside a handful of integrated producers. Amcor leverages captive resin partnerships and blown film assets across Southeast Asia to secure supply continuity for multinational food brands. Toray Industries anchors its position through biaxially oriented nylon capacity, supplying high-temperature resistant substrates that withstand aggressive sterilization cycles. Berry Global competes on laminate architecture breadth, offering tailored sealant-to-barrier ratios for medical and military ration applications.
Retort films are multilayer flexible structures engineered to endure thermal sterilization at temperatures exceeding 121 degrees Celsius while preserving oxygen and moisture barriers, typically constructed from polyethylene terephthalate, cast polypropylene, oriented polyamide, and aluminum oxide-coated substrates. Their primary purpose is to replace rigid metal cans and glass jars in shelf-stable food and pharmaceutical packaging, reducing logistics weight and enabling microwave-ready consumption formats. Polyester-based retort films dominate value contribution due to dimensional stability and printability, though polylactic acid variants are gaining fastest attention among European brands pursuing bio-based packaging roadmaps. In application terms, food packaging occupies the deepest margin pool because of volume scale and formula customization, while medical packaging commands premium pricing through sterilization validation protocols and lot-traceability requirements.
FDA migration testing under 21 CFR 177.1390 governs laminate compositions for U.S. food contact, while the EU's Framework Regulation 1935/2004 and Plastics Regulation 10/2011 enforce specific migration limits that retort film exporters must certify against. China's SAMR and national food safety standards GB 4806 series impose parallel compliance burdens for imported laminate structures, creating a fragmented regulatory entry environment. Stakeholders must monitor evolving extended producer responsibility mandates and chemical disclosure rules, as these frameworks will determine which material platforms retain market access.
Market Dynamics
Polymer compounding expertise is reorganizing competitive dynamics across the retort films value chain, as specialized extrusion and coextrusion capabilities remain scarce outside a handful of integrated producers. Specialized resin formulation and multilayer lamination know-how now determine which converters can meet sterilization-grade specifications for multinational food brands.
Growth Catalysts
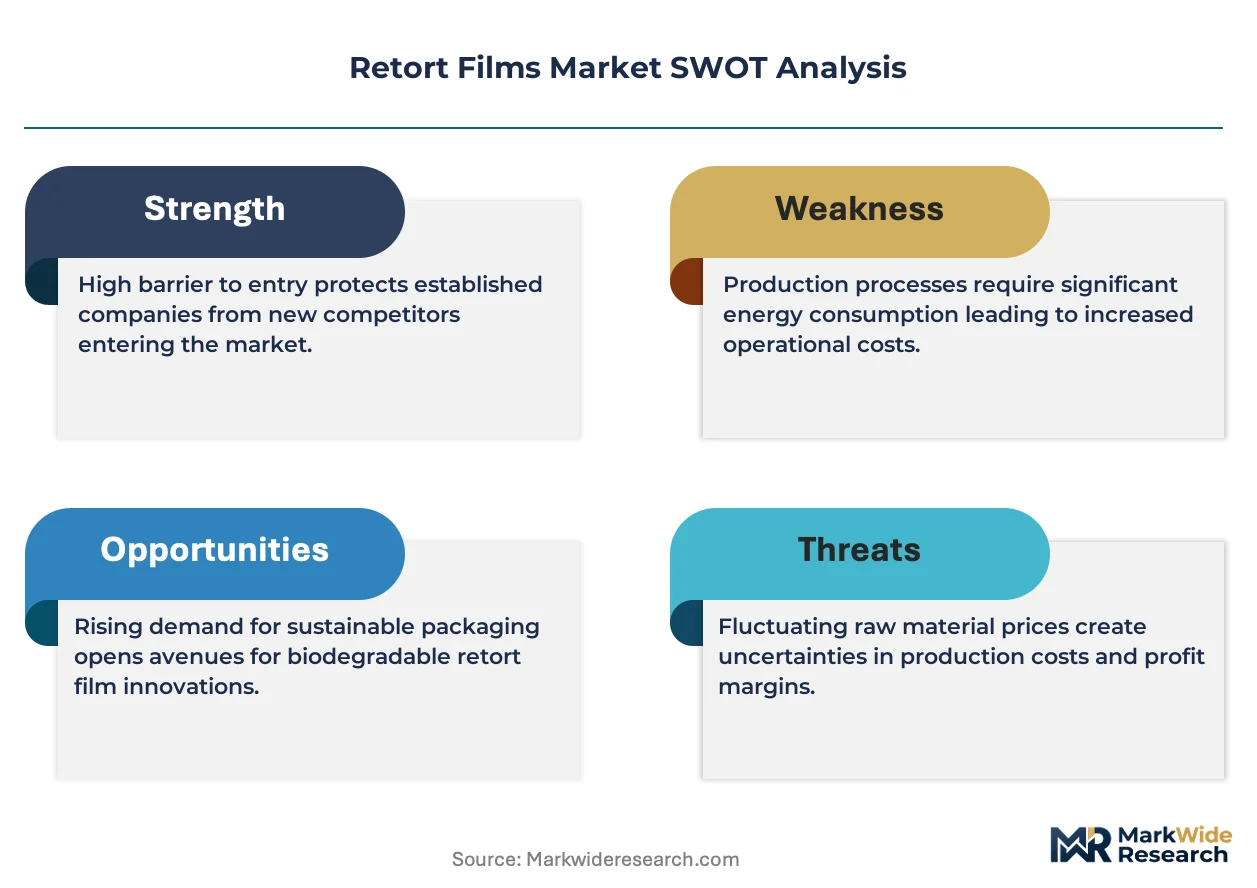
- EU Plastics Regulation 10/2011 Migration Limits:Tightening specific migration limits for heavy metals and plasticizers compel film converters to reformulate adhesive layers, creating first-mover advantage for compliant suppliers.
- E-commerce Grocery Channels:Chinese contract packagers are scaling retort-capable flexible packaging lines to serve shelf-stable meal formats demanded by urban consumers ordering through digital platforms.
- Oriented Polyamide Substrates:Biaxially oriented nylon capacity expansion enables high-temperature resistant barriers that withstand aggressive 121°C sterilization cycles in military and medical ration applications.
Market Restraints
- Aluminum Oxide Coating Input Volatility:Vacuum deposition equipment and ceramic precursor materials concentrate among Japanese and German equipment suppliers, exposing converters to capex bottlenecks and lead time extensions.
- GB 4806 Series Compliance Fragmentation:China's SAMR imposes parallel certification burdens for imported laminate structures, creating regulatory friction that delays market entry for Western film exporters.
- Metal Can Substitution Ceiling:Traditional rigid packaging retains cost advantage in low-margin commodity food categories, limiting retort pouch penetration in private-label tuna and vegetable segments.
Strategic Opportunities
- Polylactic Acid Bio-based Variants:European brands pursuing packaging roadmaps create white space for compostable retort films, though heat resistance and barrier performance remain formulation challenges.
- Medical Sterilization Validation Protocols:Lot-traceability requirements and pharmaceutical-grade certification open premium pricing tiers for converters willing to absorb extended regulatory timelines.
- India FSSAI Shelf-Stable Food Standards:Domestic food brands and contract manufacturers are investing in retort lines to serve institutional catering and defense procurement channels with extended shelf-life formats.
Industry Challenges
- Multilayer Lamination Technician Shortage:Coextrusion die setup and adhesive formulation expertise concentrate among aging workforces in Japan and Germany, constraining capacity expansion at emerging market converters.
- Sterilization Cycle Validation Timelines:FDA 21 CFR 177.1390 migration testing and EU Framework Regulation 1935/2004 compliance documentation extend new product qualification to 18-24 months, compressing innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retort Films Market |
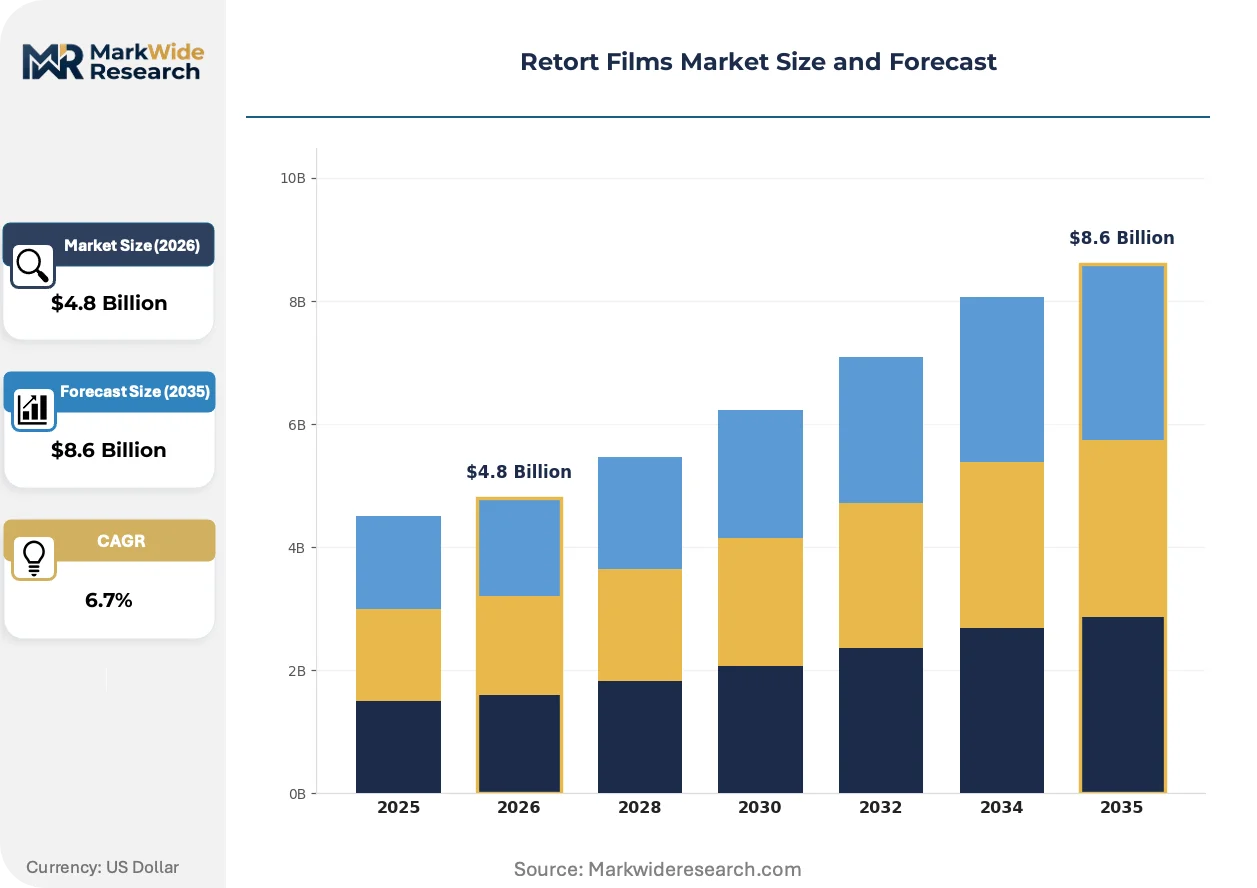
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polypropylene, Nylon, Polylactic Acid Application: Food Packaging, Medical Packaging, Consumer Goods, Industrial Applications Thickness: 50 Micron, 70 Micron, 100 Micron, 150 Micron Form: Rolls, Pouches, Bags, Laminates |
| Companies Covered | Mitsui Chemicals, Winpak, Amcor, Tredegar, Profol, Toray Industries, Berry Global, Constantia Flexibles, UFLEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retort Films Market Evolving Landscape
Active barrier technologies and substrate diversification are fragmenting established supply relationships as end-users seek alternatives to aluminum-dependent laminates. Material science advances and regulatory pressure on recyclability are forcing simultaneous innovation across three technical fronts.
Aluminum oxide-coated polyethylene terephthalate is fragmenting the traditional aluminum foil laminate market by offering comparable oxygen barrier with improved microwave transparency and sortability. Ready-to-eat meal producers in Germany and South Korea are qualifying these transparent barriers for premium positioned products. The shift is fragmenting converter relationships as brands dual-source between established foil laminators and emerging ceramic-coated film specialists.
The EU's Framework Regulation 1935/2004 and implementing Plastics Regulation 10/2011 are accelerating reformulation of polyurethane adhesives and sealant layers used in retort laminates. Film converters serving export markets must now maintain parallel inventory streams: legacy formulations for less regulated destinations and migration-optimized versions for European compliance. Medical packaging applications face the steepest requalification burden as EMA sterilization validation protocols intersect with food contact material rules.
Urban Chinese consumers are compressing purchase cycles for shelf-stable proteins through e-commerce grocery platforms, forcing retort pouch specifications toward single-serve formats with enhanced puncture resistance. Tmall and JD.com logistics networks demand packaging that survives automated sortation and last-mile delivery handling. Domestic brands like Three Squirrels and overseas entrants are converging on 80-120 gram pouch sizes that balance portion control with freight cube efficiency.
Retort Films Market Segmentation
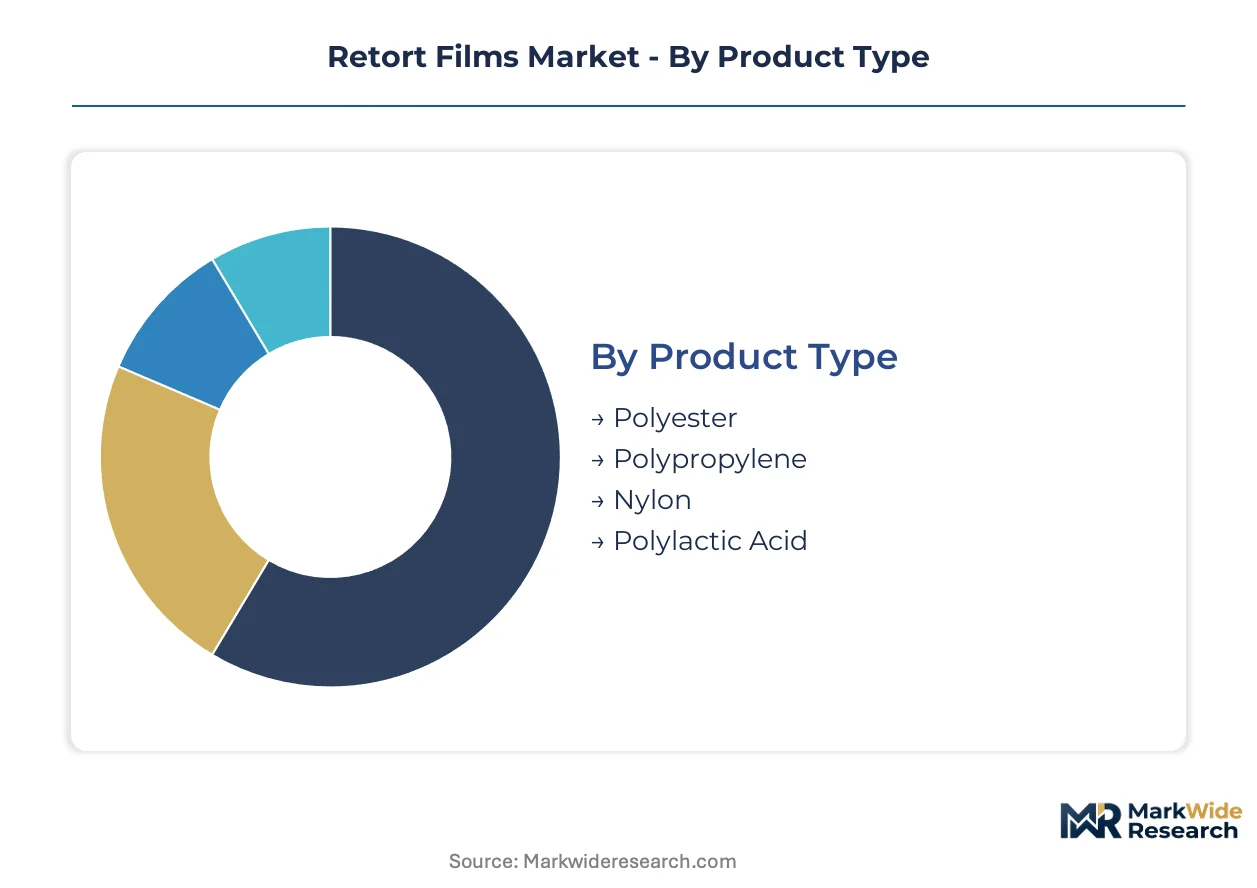
Retort films serve divergent sterilization and barrier requirements across food, medical, and industrial end-uses, forcing converters to maintain parallel product lines with distinct thermal resistance and migration compliance profiles. Each segment carries unique certification burdens and channel economics that determine which resin platforms and laminate architectures capture procurement volume.
Product Type:
Channel mix varies sharply by polymer chemistry, with polyester and polypropylene dominating foodservice and retail grocery flows while polylactic acid penetrates premium European sustainability channels.
- Polyester:Polyethylene terephthalate substrates deliver dimensional stability and high-definition printability for branded ready-to-eat meals. Demand concentrates in Germany and South Korea where microwave-transparent barriers command shelf-space premiums in e-commerce grocery channels.
- Polypropylene:Cast and oriented polypropylene variants offer cost-efficient moisture barriers for commodity tuna and vegetable applications. Procurement is shifting toward Chinese contract packagers serving Tmall and JD.com logistics networks with puncture-resistant single-serve formats.
- Nylon:Biaxially oriented polyamide withstands aggressive 121°C sterilization cycles in military and medical ration packs.
- Polylactic Acid:Bio-based PLA variants attract European brands pursuing compostable packaging roadmaps despite heat resistance formulation challenges.
By volume, polypropylene leads. By growth pace, polylactic acid is ahead.
Application:
Margin structure separates these segments, with medical and military applications absorbing extended validation timelines while food packaging runs on compressed procurement cycles.
- Food Packaging:The deepest margin pool by volume scale, spanning shelf-stable proteins, ready-to-eat meals, and institutional catering formats. Urban Chinese consumers through digital platforms are compressing specifications toward 80-120 gram pouch sizes that balance portion control with freight cube efficiency.
- Medical Packaging:Pharmaceutical-grade certification and lot-traceability requirements open premium pricing tiers. EMA sterilization validation protocols intersect with EU food contact material rules, creating the steepest requalification burden in the segment.
- Consumer Goods:Cosmetic and personal care applications demand comparable barrier performance with enhanced aesthetic finishing.
- Industrial Applications:Military rations and aerospace meal systems require extreme durability under variable temperature exposure.
Food packaging dominates absolute volume. Medical packaging shows the steepest pricing expansion trajectory.
Thickness:
Cost tier alignment follows gauge selection, with thinner films penetrating high-volume commodity categories and heavier gauges reserved for premium and medical applications.
- 50 Micron:Ultra-thin gauges serve single-serve condiment and sauce portions where material minimization drives unit economics.
- 70 Micron:Standard gauge for mainstream retort pouches balancing barrier performance with cost efficiency.
- 100 Micron:Reinforced structures for bone-in proteins and abrasive fill products requiring puncture resistance.
- 150 Micron:Heavy-gauge laminates for medical sterilization trays and military field rations demanding maximum durability.
Seventy micron films lead by unit volume. One hundred fifty micron specifications are climbing the fastest as medical and defense procurement expands.
Form:
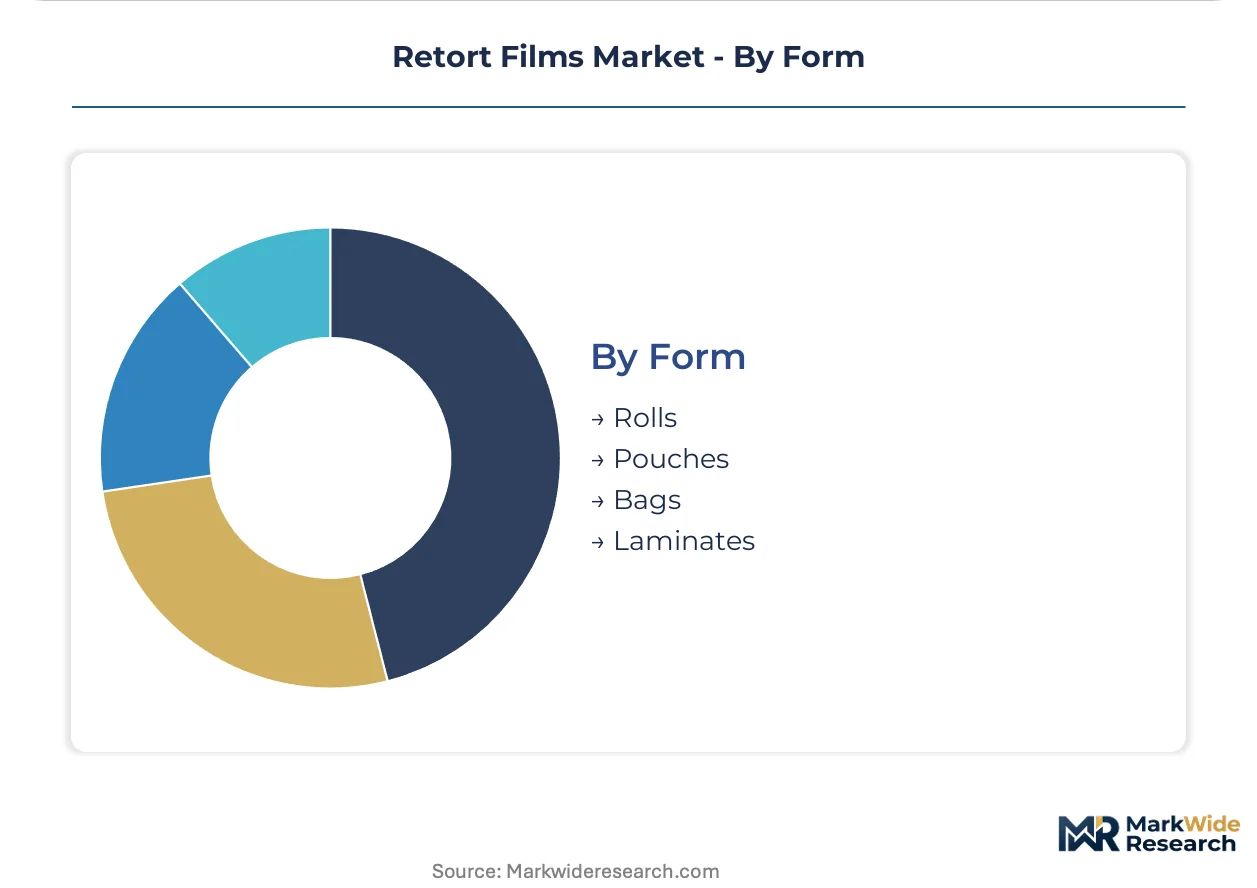
Supply concentration differs by format, with roll stock flowing to integrated converters and pre-formed pouches capturing value-added co-packing margins.
- Rolls:Unconverted film stock serves high-volume converters with captive lamination and pouch-forming equipment. Japanese and German equipment suppliers concentrate vacuum deposition capacity for ceramic-coated roll goods.
- Pouches:Pre-formed retort pouches capture downstream value from brands lacking in-house forming capability. Chinese domestic brands and contract packagers are scaling retort-capable flexible packaging lines to serve e-commerce grocery channels with finished formats.
- Bags:Gusseted and stand-up configurations for bulk institutional and foodservice applications.
- Laminates:Custom multilayer structures engineered to specific barrier-to-sealant ratios for medical and military validation protocols.
Rolls dominate by tonnage throughput. Pouches are gaining share fastest as brand owners outsource forming operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB 4806 series compliance requirements anchor procurement decisions in China, where domestic food brands and contract packagers are scaling retort-capable flexible packaging lines to serve e-commerce grocery channels with shelf-stable meal formats.
China
Urban consumers ordering through Tmall and JD.com logistics networks are compressing specifications toward 80-120 gram pouch sizes that balance portion control with freight cube efficiency. SAMR's GB 4806 series imposes parallel certification burdens for imported laminate structures, creating regulatory friction that delays market entry for Western film exporters. Yangtze River Delta converters are expanding biaxially oriented nylon capacity to supply high-temperature resistant substrates for aggressive sterilization cycles.
United States
FDA migration testing under 21 CFR 177.1390 governs laminate compositions for food contact applications, compelling converters to maintain dual inventory streams for domestic and export markets. Ready-to-eat meal producers are expanding procurement of high-barrier retort pouches as shelf-stable formats gain traction among urban consumers. Midwest flexible packaging clusters are investing in blown film assets to secure supply continuity for multinational food brands.
Germany
EU Framework Regulation 1935/2004 and Plastics Regulation 10/2011 are accelerating reformulation of polyurethane adhesives and sealant layers used in retort laminates. Aluminum oxide-coated polyethylene terephthalate is fragmenting the traditional aluminum foil laminate market by offering comparable oxygen barrier with improved microwave transparency. Bavarian converters are qualifying transparent barriers for premium positioned products in e-commerce grocery channels.
Japan
METI industrial standards and aging workforce demographics concentrate coextrusion die setup expertise among established producers, constraining capacity expansion at emerging market converters. Biaxially oriented nylon capacity anchors high-temperature resistant substrate supply for military and medical ration applications. Kanto region equipment suppliers dominate vacuum deposition capacity for ceramic-coated roll goods.
India
FSSAI shelf-stable food standards are driving domestic food brands and contract manufacturers to invest in retort lines for institutional catering and defense procurement channels. Polylactic acid bio-based variants attract sustainability-focused brands despite heat resistance formulation challenges. Maharashtra and Gujarat packaging clusters are scaling multilayer lamination capabilities to serve export markets.
Retort Films Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with polymer compounding expertise reorganizing competitive dynamics across the retort films value chain. Specialized extrusion and coextrusion capabilities remain scarce outside a handful of integrated producers, creating supply continuity premiums for multinational food brands. Three archetypes dominate: resin-integrated multinationals with captive partnerships, substrate specialists with biaxial orientation assets, and laminate architects with medical validation protocols. Competitive moves concentrate on backward integration into resin formulation and geographic expansion through Southeast Asian blown film assets.
Within the integrated multinational tier, Amcor and Toray Industries exemplify contrasting strategic positions. Amcor leverages captive resin partnerships and blown film assets across Southeast Asia, while Toray Industries anchors its position through biaxially oriented nylon capacity. Berry Global occupies a position among laminate architects, offering tailored sealant-to-barrier ratios for medical and military ration applications. These three represent how polymer compounding expertise and specialized equipment access determine sterilization-grade specification capture.
| Leading Market Players |
|---|
| Mitsui Chemicals |
| Winpak |
| Amcor |
| Tredegar |
| Profol |
| Toray Industries |
| Berry Global |
| Constantia Flexibles |
| UFLEX |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month sterilization cycle validation timelines concentrate pricing power among Japanese and German equipment suppliers with proven FDA 21 CFR 177.1390 and EU Framework Regulation 1935/2004 compliance records, while Chinese contract packagers compress procurement cycles through e-commerce grocery channel volume commitments.
Pricing Analysis
Geographic price spreads of 15-25 percentage points separate EU-compliant migration-optimized laminates from legacy formulations serving less regulated destinations, with medical sterilization validation protocols commanding the steepest premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and barrier performance, with aluminum oxide-coated polyethylene terephthalate variants capturing microwave-transparent premiums in Germany and South Korea. Cost compression in commodity polypropylene segments is intensifying because Chinese domestic brands are scaling retort-capable lines for Tmall logistics networks. Private-label tuna and vegetable processors show highest price sensitivity, while military and medical ration contractors absorb extended validation timelines for lot-traceability assurance.
Supply Chain Analysis
Vacuum deposition equipment and ceramic precursor materials concentrate among Japanese and German equipment suppliers, exposing converters to capex bottlenecks and lead time extensions that ripple through multilayer lamination capacity. Raw material flows draw from biaxially oriented nylon capacity anchored in Japan, blown film assets across Southeast Asia, and cast polypropylene resin streams from Chinese petrochemical complexes. Single-source vulnerability around coextrusion die setup expertise—concentrated among aging workforces in Kanto and Bavarian industrial clusters—constrains capacity expansion at emerging market converters. Distribution runs through roll stock channels serving integrated converters with captive lamination equipment, while pre-formed pouches capture downstream value from brands outsourcing forming operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort film incumbents face substitution defense imperatives as aluminum oxide-coated transparent barriers fragment traditional aluminum foil laminate relationships, forcing simultaneous requalification investments across sterilization-grade specifications.
For Market Incumbents: Consolidate backward integration into resin formulation partnerships and blown film assets across Southeast Asia to secure supply continuity against Chinese contract packager vertical integration. Lock in biaxially oriented nylon capacity through equipment supplier relationships in Japan to defend high-temperature resistant substrate positions against emerging ceramic-coated film specialists.
For New Entrants and Emerging Players: Lead with polylactic acid bio-based variants targeting European brands pursuing compostable packaging roadmaps, where heat resistance formulation gaps create white space for specialized extrusion partnerships. Penetrate Indian institutional catering and defense procurement channels through FSSAI shelf-stable food standard compliance, offering 80-120 gram single-serve formats that balance portion control with freight cube efficiency for domestic food brands scaling retort lines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized multilayer lamination capabilities and stranded FDA migration testing documentation assets. Long-term viability hinges on regulatory compliance infrastructure rather than commodity resin access, with EU Plastics Regulation 10/2011 reformulation timelines serving as the critical inflection signal for adhesive layer migration-optimized inventory positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive polyethylene terephthalate supply secures sterilization-grade specification continuity for multinational food brands. |
| EMA Sterilization Validation Protocol Investment | Pharmaceutical-grade certification opens premium pricing tiers through lot-traceability compliance. |
| Southeast Asian Blown Film Capacity Expansion | Regional asset placement reduces lead time exposure to Japanese and German equipment supplier concentration. |
| Aluminum Oxide Coating Qualification | Microwave-transparent barrier penetration fragments converter relationships in German e-commerce grocery channels. |
| Polylactic Acid Heat Resistance R&D Partnership | European sustainability roadmap alignment creates first-mover positioning despite formulation challenges. |
Research Methodology
Initial hypotheses were tested against primary input from film converter operations directors, adhesive formulation chemists, food brand procurement managers, and medical packaging regulatory affairs leads, and refined through secondary validation against FDA 21 CFR 177.1390 migration testing protocols, EU Plastics Regulation 10/2011 compliance documentation, SAMR GB 4806 series certification records, and customs trade flows for biaxially oriented nylon substrates. Bottom-up volume modeling from individual converter capacity announcements triangulated with top-down demand estimates from e-commerce grocery channel growth metrics.
Variance decomposition across polymer chemistry, application segment, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled included substrate type, sterilization temperature requirement, barrier-to-sealant ratio specification, and certification tier. CAGRs derived from installed capacity expansion trajectories and substitution elasticity estimates for metal can formats, with aluminum oxide coating adoption curves and polylactic acid formulation advancement serving as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU migration limit enforcement and Chinese e-commerce grocery penetration rates would require recalibration. Forecasts reflect documented assumptions regarding sterilization cycle validation timeline stability and coextrusion die setup expertise retirement patterns. Practitioners should keep alternative scenarios live as SAMR GB 4806 series enforcement intensity and Indian FSSAI shelf-stable food standard adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market