
 North America Retort Packaging Market | 2026-2036
North America Retort Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Retort Packaging Market Analytics
Multi-source procurement for high-barrier films is shifting toward vertically integrated domestic suppliers across the North American retort packaging value chain. Amcor plc leverages captive resin compounding and lamination capacity to secure supply continuity for food brand customers. Sonoco Products Company anchors its position through rigid container specialization, particularly in metal and composite can formats for shelf-stable proteins. Sealed Air competes with advanced vacuum skin and flow-wrap technologies that extend retort-compatible barrier performance.
Retort packaging comprises hermetically sealed containers—typically flexible pouches, rigid metal or composite cans, or thermoformed trays—engineered to withstand sterilization temperatures exceeding 121°C while preserving oxygen and moisture barriers for shelf-stable contents; multilayer constructions of polyethylene terephthalate, aluminum foil, and polypropylene coextrusions achieve the requisite thermal stability and seal integrity for commercial sterilization cycles. Flexible pouches occupy the fastest-expanding segment as protein processors and pet food manufacturers convert from metal cans to reduce shipping cube and retail shelf footprint. Rigid containers sustain dominant volume share in institutional food service channels where puncture resistance and stackability outweigh lightweighting benefits.
The FDA's food-contact substance notification requirements and USDA's FSIS labeling mandates for shelf-stable meat and poultry products shape converter qualification timelines and barrier specification rigor across North American supply chains. Health Canada's food packaging material safety standards create parallel compliance obligations for cross-border suppliers serving Canadian processors. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and Oregon, where post-consumer recycling targets for multilayer flexible structures could force material redesign investments before federal harmonization emerges.
Market Dynamics
Pet food manufacturers are accelerating conversion from metal cans to flexible pouches, compressing procurement cycles and forcing converters to expand high-barrier lamination capacity in the US Southeast protein processing corridor.
Growth Catalysts
- USDA FSIS labeling mandates:Shelf-stable meat and poultry processors must upgrade to retort-compatible barrier structures, pulling converter investment toward compliant multilayer films.
- Protein processing cluster concentration:Georgia, North Carolina, and Arkansas host expanding wet pet food operations that source pouches within 500-mile radii to minimize freight costs.
- Aluminum foil coextrusion advances:Sub-7-micron foil gauges now achieve 121°C sterilization stability, enabling lightweighting without oxygen transmission rate degradation.
Market Restraints
- Resin supply concentration:Polypropylene and polyethylene terephthalate feedstock dependence on Gulf Coast petrochemical complexes exposes converters to hurricane-related supply disruptions.
- Multilayer recycling incompatibility:Polyethylene-aluminum-polypropylene laminates face mechanical sorting rejection at materials recovery facilities, threatening extended producer responsibility compliance in California and Oregon.
- Retort equipment capex intensity:Continuous rotary sterilizers require $4-8 million per installation, limiting processor conversion flexibility for seasonal product lines.
Strategic Opportunities
- Canadian cross-border expansion:Health Canada's food packaging material safety standards create parallel qualification pathways for US converters with existing FDA food-contact substance notifications.
- Human-grade pet food positioning:Premium wet food brands are specifying pouch structures previously reserved for human consumption, opening margin expansion for high-barrier film suppliers.
- Mono-material retort development:Polypropylene-only constructions compatible with existing recycling streams are attracting converter R&D investment ahead of state-level post-consumer content mandates.
Industry Challenges
- Migration testing capacity constraints:FDA's updated food-contact notification requirements are extending qualification timelines to 180-240 days, delaying new product launches.
- Laminate seal integrity validation:Hermetic seal verification at 121°C requires specialized destructive testing protocols that few third-party laboratories can execute at commercial volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Retort Packaging Market |
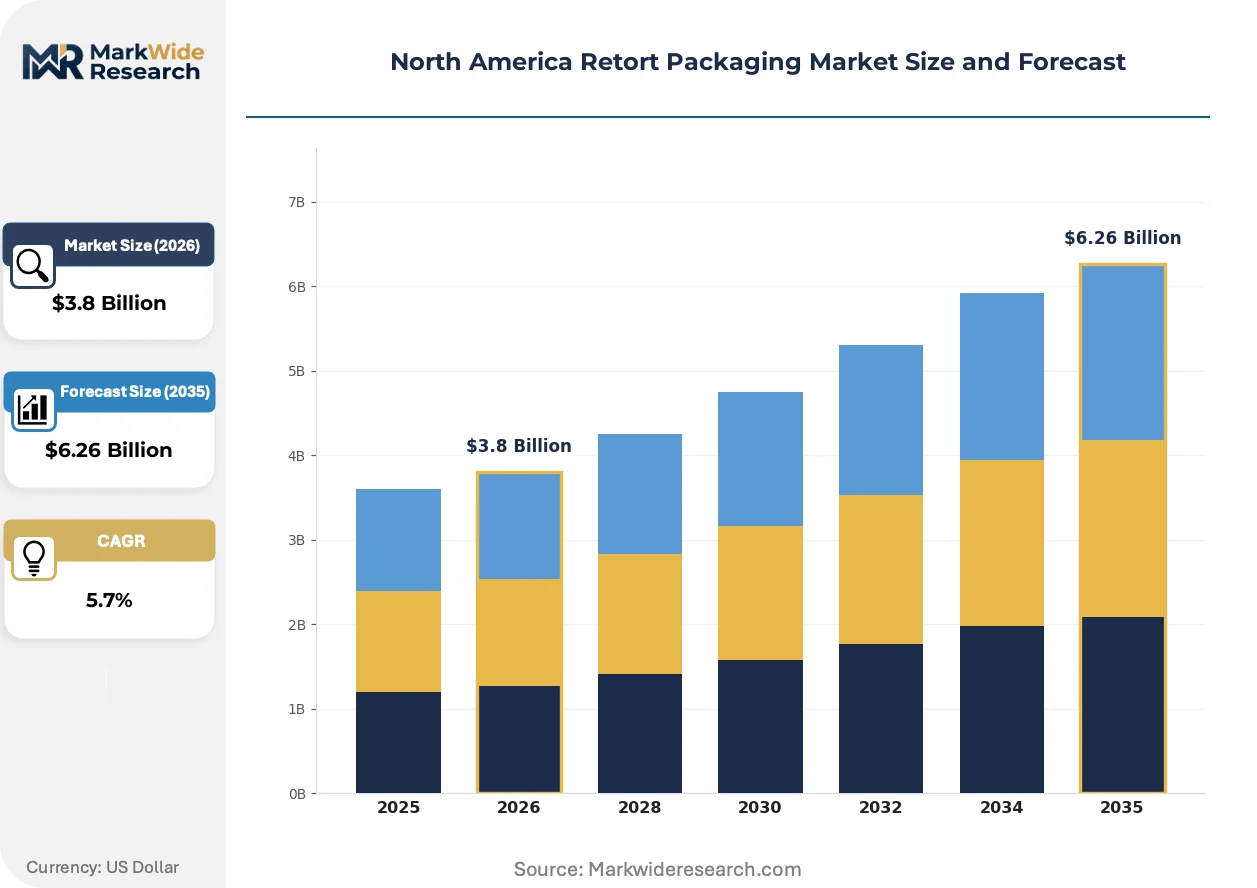
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Pouches, Rigid Containers, Trays, Stand-Up Pouches Material: Aluminum, Paperboard, Plastic, Composites Application: Food, Beverages, Healthcare, Pet Food End User: Manufacturers, Retailers, Food Service, Distributors |
| Companies Covered | FLAIR Flexible Packaging Corporation, IMPAK CORPORATION, PORTCO PACKAGING, Constantia Flexibles, Amcor plc, Sonoco Products Company, Sealed Air, WINPAK LTD., Tetra Pak, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Retort Packaging Market Evolving Landscape
Retort packaging technology is bifurcating between flexible lightweighting for retail channels and rigid durability for institutional food service, with material science investments concentrating on recyclability without thermal performance sacrifice.
High-barrier transparent polyethylene terephthalate coextrusions are absorbing share from aluminum foil laminates in premium wet pet food applications. Nestlé Purina and Mars Petcare are specifying clear window pouches for human-grade positioning at 15-20% volume premiums. This transparency shift is absorbing capital from opaque foil structures while demanding equivalent oxygen barrier performance through silicon oxide coatings.
California's SB 54 extended producer responsibility framework is mandating 30% post-consumer recycled content in flexible packaging by 2030. Converters are qualifying chemically recycled polypropylene for retort layers to meet mechanical recycling incompatibility constraints. The pet food segment faces the steepest compliance curve given multilayer laminate dominance in wet food formats.
Direct-to-subscription pet food brands are compressing packaging specification cycles from 18 months to 6 months to match formulation innovation velocity. Chewy and Amazon private-label operations are bypassing traditional distributor networks, forcing converters to maintain finished goods inventory positions near fulfillment centers. This channel disintermediation concentrates demand volatility in the US Southeast and Pacific Northwest logistics corridors.
North America Retort Packaging Market Segmentation
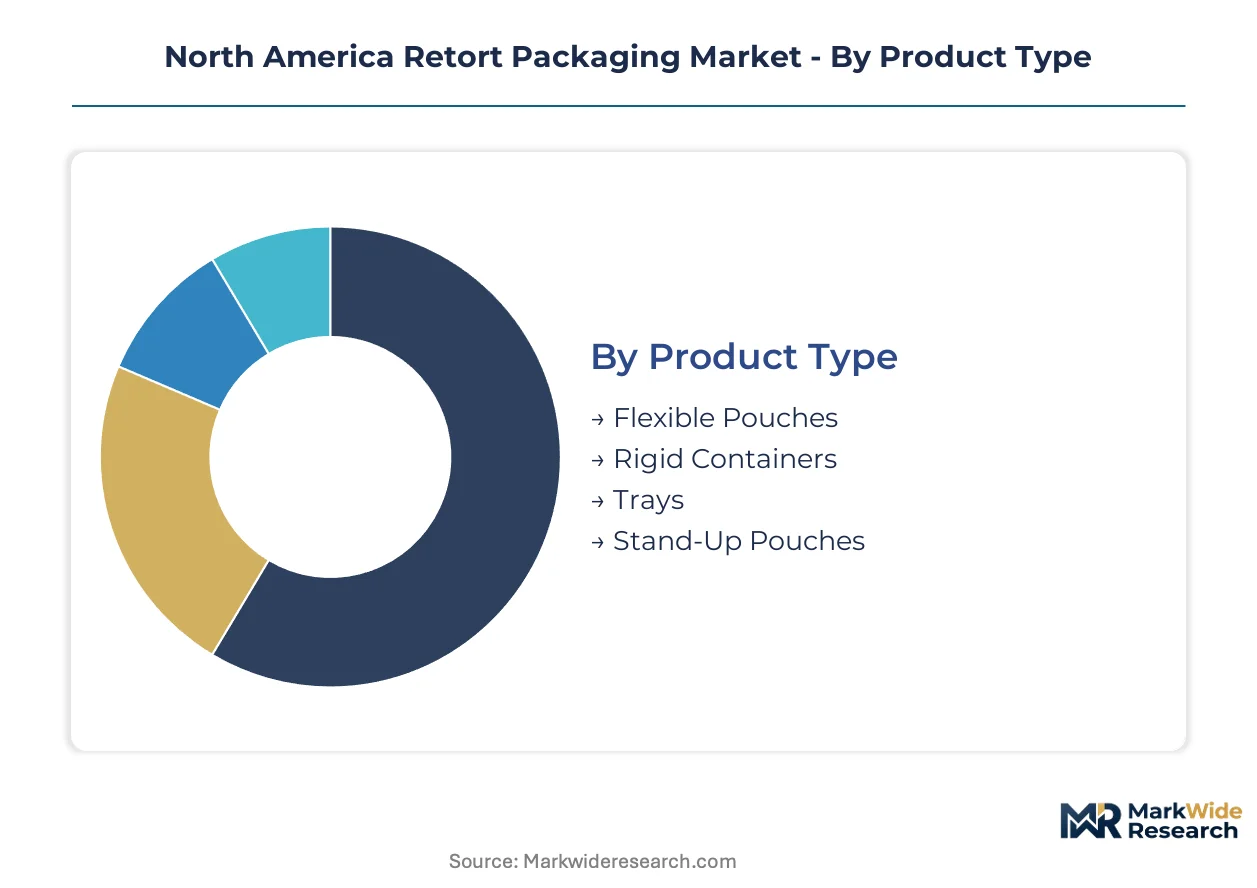
Retort packaging segmentation reflects divergent technical requirements across sterilization methods, barrier specifications, and distribution channels. Each axis shapes converter investment priorities and procurement patterns differently across protein processing and shelf-stable food supply chains.
Product Type:
Structural configuration determines thermal endurance, shipping cube efficiency, and retail merchandising flexibility.
- Flexible Pouches:Multilayer laminates of polyethylene terephthalate, aluminum foil, and polypropylene withstand 121°C sterilization while reducing freight weight 70% versus metal alternatives. Pet food processors in Georgia and North Carolina are converting can lines to pouch formats to cut logistics spend and retail shelf footprint. This segment gains share fastest as wet food brands prioritize lightweighting and e-commerce shipping efficiency.
- Rigid Containers:Metal and composite cans deliver puncture resistance and stackability for institutional food service channels where handling durability outweighs weight considerations. USDA FSIS labeling mandates for shelf-stable meat and poultry reinforce specification rigor for these structures. This segment leads on installed volume across military, school, and healthcare feeding operations.
- Trays:Thermoformed polypropylene structures with heat-sealed lidding suit ready-meal applications requiring microwave venting and portion control.
- Stand-Up Pouches:Gusseted bottom constructions improve retail shelf presence for premium wet pet food and single-serve human meals.
Flexible Pouches leads on scale; Stand-Up Pouches leads on momentum.
Material:
Barrier composition balances oxygen transmission resistance, thermal stability, and end-of-life recovery pathways.
- Composites:Polyethylene-aluminum-polypropylene laminates achieve sub-0.1 cc/m²/day oxygen transmission rates essential for 24-month shelf life in protein applications. California's SB 54 extended producer responsibility targets are forcing converters to qualify chemically recycled feedstocks for these structures. This segment dominates high-barrier wet pet food and shelf-stable meat specifications.
- Plastic:Polypropylene and polyethylene terephthalate coextrusions enable transparent window packaging for human-grade pet food positioning at retail premium. Nestlé Purina and Mars Petcare are specifying clear pouch structures previously reserved for human consumption. This segment climbs fastest as transparency trends displace opaque foil laminates.
- Aluminum:Sub-7-micron foil gauges now achieve sterilization stability without barrier degradation, enabling lightweighting in legacy can formats.
- Paperboard:Fiber-based composite cans serve dry beverage and powdered food segments with lower barrier requirements.
Composites leads on revenue concentration; Plastic leads on specification innovation velocity.
Application:
End-use category dictates sterilization protocol, regulatory pathway, and margin structure for converter output.
- Pet Food:Premium wet food lines are absorbing pouch capacity at 15-20% volume premiums over standard formats, with direct-to-subscription brands compressing specification cycles from 18 months to 6 months. FDA food-contact substance notification requirements extend qualification timelines to 180-240 days for new structures. This segment expands most quickly as human-grade positioning drives material upgrades.
- Food:Shelf-stable meat, poultry, and ready meals sustain baseline demand across retail and institutional channels, with USDA FSIS labeling mandates pulling converter investment toward compliant multilayer films. This segment anchors converter capacity utilization.
- Beverages:Retortable cartons and pouches serve ready-to-drink coffee, broth, and nutritional drinks with aseptic-equivalent barrier performance.
- Healthcare:Enteral nutrition and medical food applications demand validated seal integrity documentation for patient safety compliance.
Food leads on absolute volume; Pet Food leads on margin expansion.
End User:
Procurement authority and technical specification control vary sharply across the value chain.
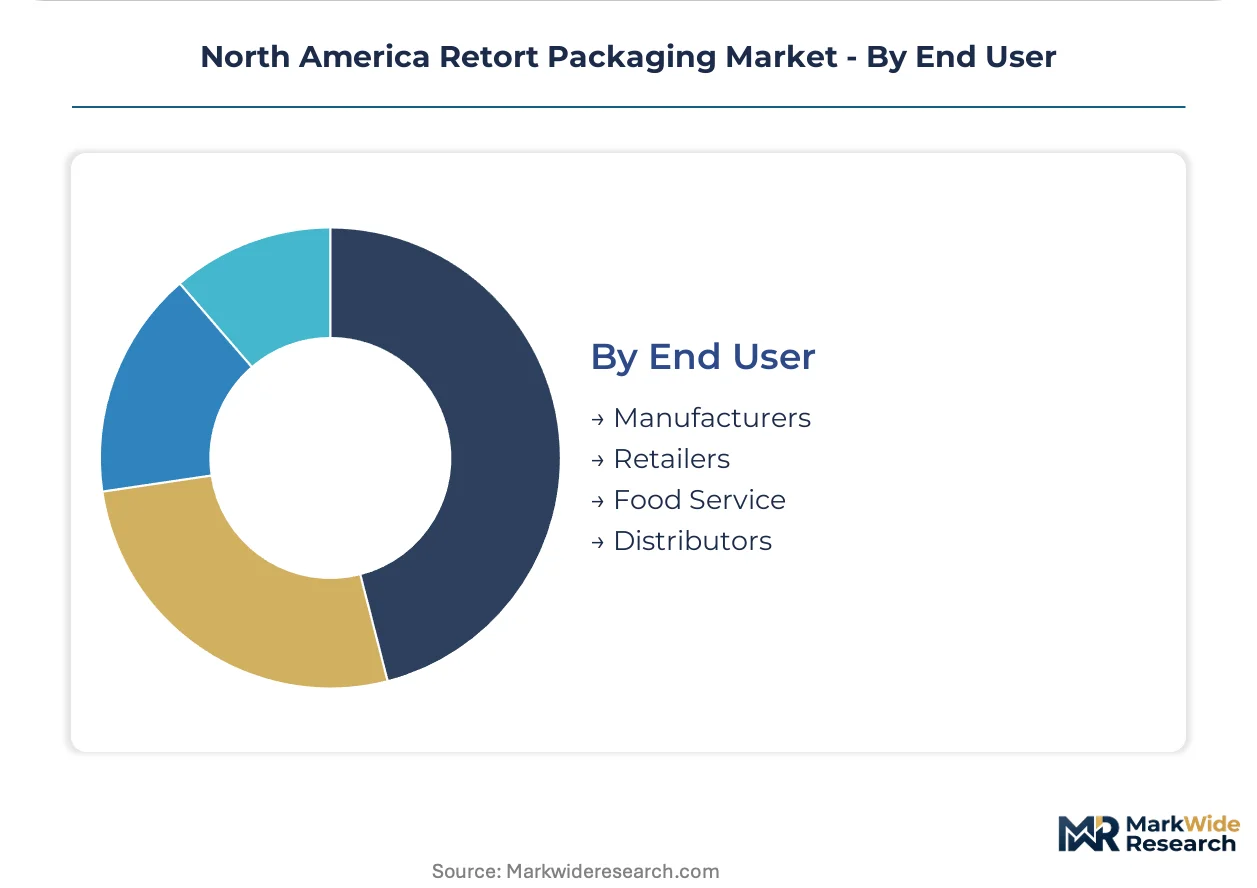
- Manufacturers:Protein processors and co-packers hold direct specification authority for pouch structures, driving converter relationships within 500-mile procurement radii of Georgia, North Carolina, and Arkansas processing clusters. This segment concentrates demand and shapes converter capacity location decisions.
- Retailers:Amazon and Chewy private-label operations are bypassing traditional distributor networks, forcing converters to maintain finished goods inventory near fulfillment centers in the US Southeast and Pacific Northwest. This segment gains influence fastest as channel disintermediation accelerates.
- Food Service:Institutional buyers prioritize puncture resistance and stackability in rigid formats for healthcare, education, and military feeding.
- Distributors:Traditional wholesale channels face margin compression as direct procurement concentrates with manufacturers and retailers.
Manufacturers leads on specification control; Retailers leads on procurement pattern disruption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Southeast protein processing corridor anchors North American retort packaging demand, with Georgia, North Carolina, and Arkansas hosting expanding wet pet food operations that source pouches within 500-mile radii to minimize freight costs.
United States
US Southeast protein processing clusters in Georgia and North Carolina drive pouch procurement for premium wet pet food lines. The FDA's updated food-contact notification requirements extend qualification timelines to 180-240 days, accelerating migration testing investments by converters. Arkansas hosts expanding co-packing operations that source high-barrier laminates from regional suppliers.
Canada
Canadian protein processors in Ontario and Alberta import retort-compatible structures from US converters with existing FDA notifications. Health Canada's food packaging material safety standards create parallel qualification pathways for cross-border suppliers. Toronto-area distribution centers serve as consolidation points for Pacific Northwest pet food brands entering the Canadian market.
Mexico
Mexican pet food manufacturers in Querétaro and Jalisco states are converting can lines to pouch formats for export-oriented production. The country's national food safety regulator enforces packaging material standards aligned with US FDA frameworks. Monterrey-based converters are qualifying high-barrier films for cross-border supply to Texas protein processors.
North America Retort Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mono-material recyclability and transparent barrier technologies. The market exhibits tiered concentration with multinational converters holding dominant positions in high-barrier laminates while regional specialists capture proximity-driven procurement in protein processing corridors. Three archetypes define competitive positioning: vertically integrated resin-to-pouch suppliers, rigid container specialists with composite can expertise, and technology licensors of advanced barrier coatings. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters secure positions near Southeast US protein clusters.
Among publicly traded packaging conglomerates, Amcor plc, Sonoco Products Company, and Sealed Air occupy positions that exemplify distinct strategic archetypes. Amcor represents the vertically integrated model with captive resin compounding and lamination capacity. Sonoco anchors the rigid container specialization vector through metal and composite can formats. Sealed Air sits within the advanced barrier technology tier competing with vacuum skin and flow-wrap innovations. These three entities collectively illustrate how scale, specialization, and technology differentiation segment competitive positioning across the retort packaging value chain.
| Leading Market Players |
|---|
| FLAIR Flexible Packaging Corporation |
| IMPAK CORPORATION |
| PORTCO PACKAGING |
| Constantia Flexibles |
| Amcor plc |
| Sonoco Products Company |
| Sealed Air |
| WINPAK LTD. |
| Tetra Pak |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up converters in the US Southeast protein corridor are consolidating lamination capacity while enforcing contract-based pricing discipline on pet food brands seeking supply security. This ownership concentration tightens margin capture at the film-converter level while forcing processors to accept longer-term offtake commitments with limited price flexibility.
Pricing Analysis
Polypropylene and aluminum foil cost pass-through clauses dominate converter-processor contracts, with resin indexation resetting quarterly. Three-tier pricing structure across premium clear-barrier, standard foil-laminate, and economy-grade specifications separates human-grade pet food pouches from institutional rigid containers. Pricing pressure stems from California SB 54 compliance investments in chemically recycled feedstocks, with direct-to-subscription brands like Chewy and Amazon private-label operations proving least price-sensitive due to compressed specification cycles.
Supply Chain Analysis
Dual-sourcing requirements from Nestlé Purina and Mars Petcare mandate qualified secondary suppliers for all high-barrier laminate structures, forcing converters to maintain redundant extrusion lines. Raw material supply draws from Gulf Coast petrochemical complexes for polypropylene, Tennessee aluminum rolling mills for foil gauges, and Ontario resin compounders for specialty coextrusions. Hurricane exposure at Gulf Coast petrochemical hubs represents the dominant structural risk, while distribution runs through processor-direct procurement within 500-mile radii of Georgia and North Carolina protein clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
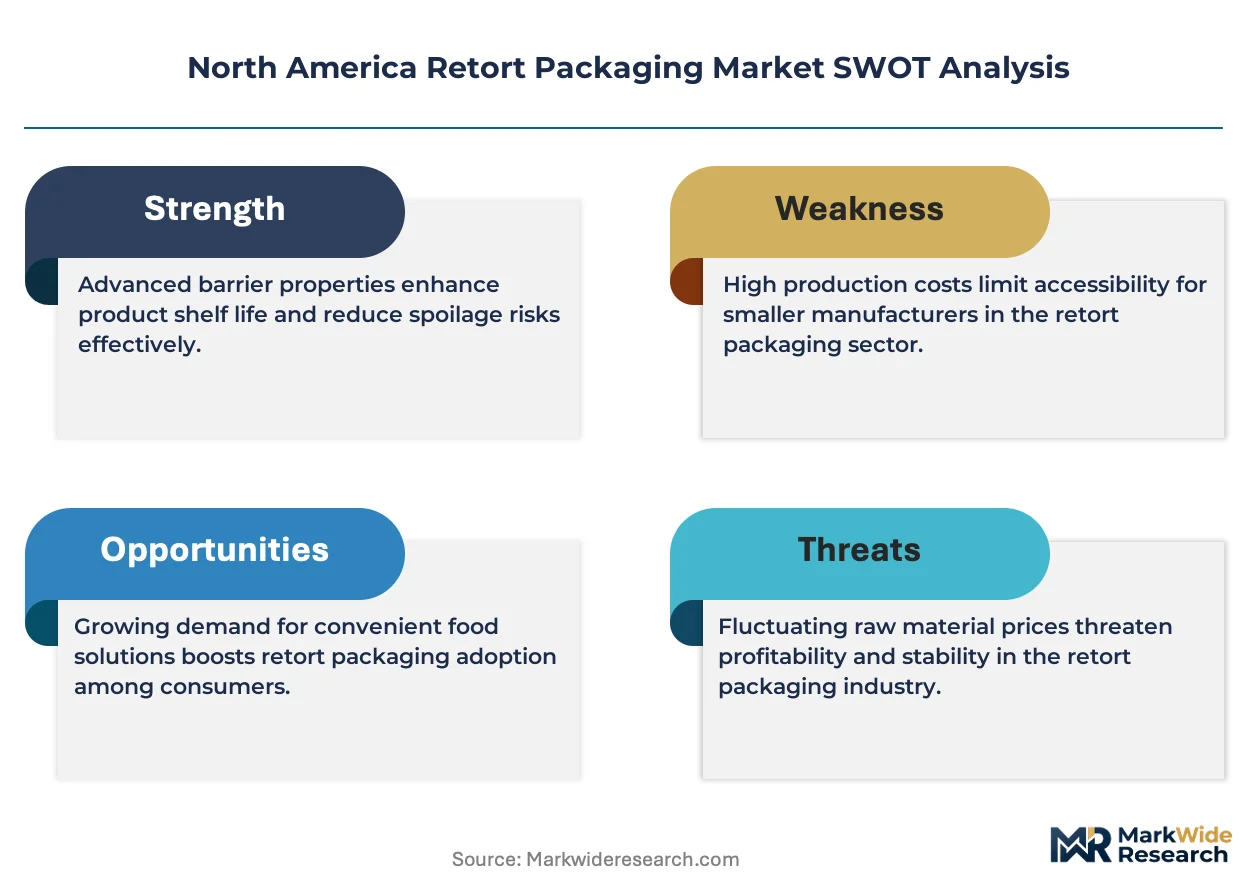
Margin expansion in North American retort packaging rests on aluminum foil lightweighting and premium transparent-barrier tier penetration, with converters capturing value from pet food brands repositioning wet food lines as human-grade.
For Market Incumbents: Anticipate mono-material polypropylene retort development as the primary defensive maneuver against California and Oregon extended producer responsibility mandates. Secure FDA food-contact notification coverage for transparent silicon oxide barrier coatings before migration testing queues extend further. Backward integration into captive resin compounding in the US Southeast defends margin position against Gulf Coast supply disruptions. For New Entrants and Emerging Players: Direct-to-subscription e-commerce channels offer the most penetrable route for regional converters lacking legacy brand relationships. Target Pacific Northwest fulfillment center proximity for Chewy and Amazon private-label supply, where inventory positioning requirements have disintermediated traditional distributors. Lead with 6-month specification cycle capability against incumbent 18-month qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap converters with FDA notification coverage but limited mono-material R&D pipelines. Five-to-ten-year viability hinges on chemical recycling infrastructure maturation for multilayer laminate compliance. Watch California SB 54 enforcement variance as the signal for forced material redesign capex inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Retort Development | Polypropylene-only constructions enable mechanical recycling compliance ahead of California's 2030 post-consumer content mandates. |
| Migration Testing Capacity Expansion | Third-party laboratory investments reduce FDA qualification timelines from 240 days for pet food brands accelerating formulation innovation. |
| Southeast Lamination Capacity Addition | Georgia and North Carolina extrusion lines capture procurement within 500-mile radii of expanding protein processing clusters. |
| Transparent Barrier Coating Qualification | Silicon oxide PET coextrusions command 15-20% premiums from Nestlé Purina and Mars Petcare human-grade positioning. |
| Chemical Recycling Feedstock Integration | Chemically recycled polypropylene layers satisfy California SB 54 requirements without sacrificing 121°C sterilization stability. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national protein processing corridor. Primary interviews with pet food brand procurement directors, converter operations managers, FDA regulatory consultants, and Southeast US protein cluster co-packers combined with secondary validation from USDA FSIS labeling guidance, Health Canada food packaging standards, FDA food-contact substance notification databases, and customs trade flow records. Bottom-up capacity utilization modeling triangulated against top-down pet food industry production estimates.
Granularity-level modeling disaggregated volume and value across product type, material composition, application segment, and end-user procurement authority. Segment-specific CAGRs derived from protein processing capacity expansion pipelines, pet food premiumization trend trajectories, and regulatory compliance investment schedules. Forecast inputs incorporated aluminum foil gauge lightweighting adoption curves and direct-to-subscription channel growth patterns.
Resin price volatility, FDA qualification timeline extension, and state-level extended producer responsibility enforcement variance are the dominant revision risks. Deviation in California SB 54 implementation stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Aseptic IBC Market