
 APAC Aseptic Packaging Market | 2026-2036
APAC Aseptic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Aseptic Packaging Market Outlook
Asset-light contract manufacturing and third-party filling arrangements is fragmenting competitive control across the APAC aseptic packaging landscape. Tetra Pak International SA leverages its integrated equipment-service model to anchor long-term customer relationships. SIG Combibloc Group competes through regional filling-machine partnerships that reduce capital barriers for mid-sized dairy processors. Greatview Aseptic Packaging specializes in domestic Chinese beverage supply, while Uflex Limited extends flexible packaging capabilities into aseptic pouch formats for Indian juice brands.
Aseptic packaging sterilizes food, pharmaceutical, or cosmetic contents separately from the container, then combines them in a sterile environment using hydrogen peroxide vapor or electron-beam treatment on multilayer cartons, bottles, or pouches with oxygen and light barriers measured in transmittance rates below specific thresholds. Paper-based materials dominate volume in ambient dairy and juice distribution due to cost efficiency and established recycling infrastructure. UHT Processing technology leads installation counts across Southeast Asian beverage plants, while pharmaceutical-grade plastic vials and ampoules command premium margins in Japan and South Korean oncology drug packaging.
China's SAMR enforces GB standards for food-contact layers that restrict certain adhesive chemistries, while India's FSSAI mandates nutritional labeling and shelf-life declarations that shape carton design specifications. Japan's PMDA imposes sterility assurance level requirements on pharmaceutical packaging that filter market entrants by validation capability. Stakeholders must monitor how BIS certification timelines and China's dual carbon goals interact with laminate sourcing decisions across the forecast horizon.
Market Dynamics
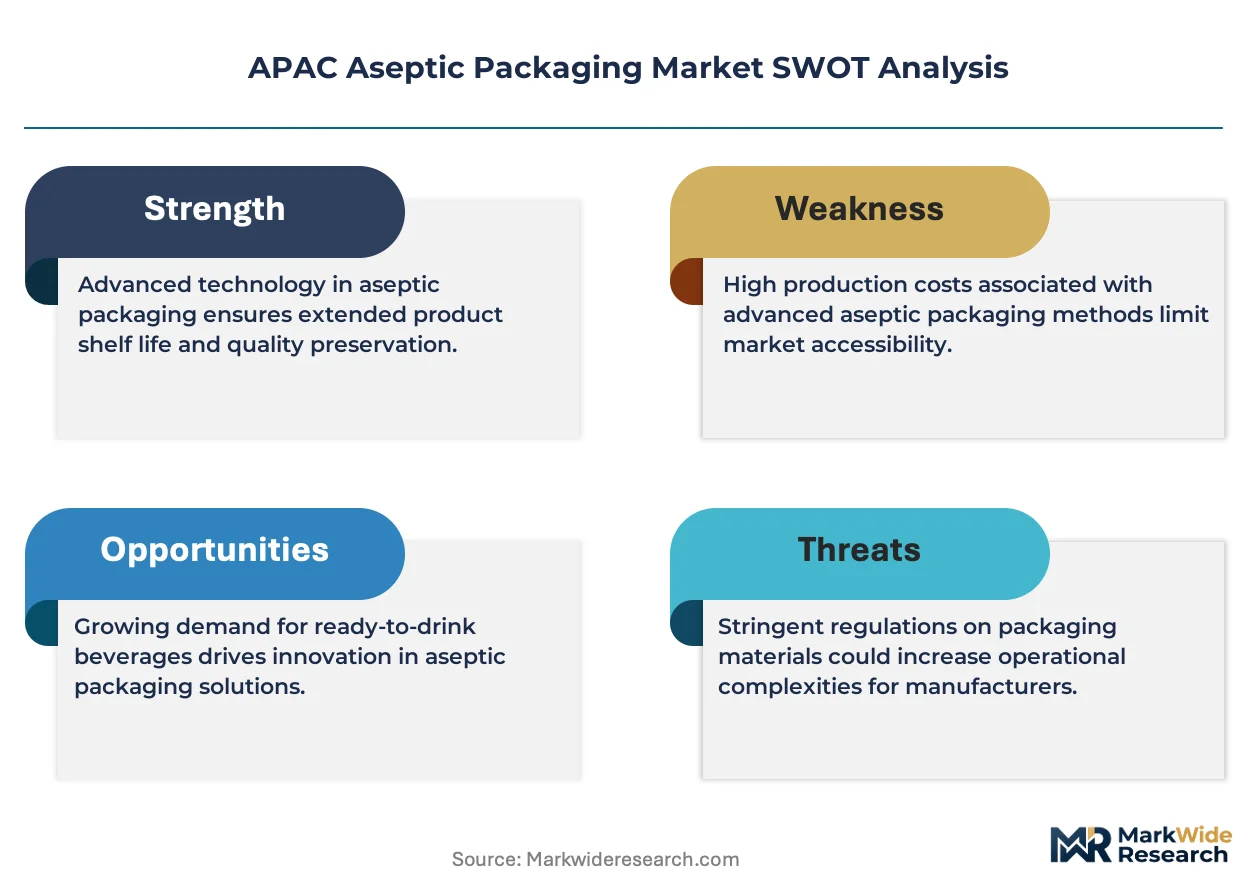
Asset-light contract manufacturing and third-party filling arrangements are fragmenting competitive control across the APAC aseptic packaging landscape. Tetra Pak International SA leverages its integrated equipment-service model to anchor long-term customer relationships while regional players exploit modular filling partnerships to bypass capital barriers.
Growth Catalysts
- UHT Processing installations:Southeast Asian beverage plants are expanding hydrogen peroxide vapor sterilization lines to serve cold-chain-free distribution networks for ambient dairy and plant-based drinks.
- China's dual carbon goals:MEE enforcement of energy-efficiency benchmarks is accelerating laminate material substitutions toward lower-carbon multilayer structures in domestic carton production.
- India's pharmaceutical corridor:Demand concentrates along the Mumbai-Hyderabad axis for sterile vials and ampoules serving oncology drug packaging with elevated sterility assurance requirements.
Market Restraints
- Aluminum foil price volatility:Oxygen barrier layers depend on primary aluminum smelter output concentrated in Chinese and Indonesian supply bases, squeezing converter margins.
- Adhesive chemistry restrictions:China's GB standards for food-contact materials ban specific epoxy-based laminating adhesives, forcing reformulation cycles and qualification delays.
- Validation capability scarcity:Japan's PMDA sterility assurance level requirements filter market entrants lacking electron-beam or vapor-phase hydrogen peroxide validation documentation.
Strategic Opportunities
- Vietnamese dairy penetration:Mid-sized processors in the Mekong Delta seek modular filling-machine partnerships to access aseptic carton capacity without integrated equipment commitments.
- Flexible aseptic pouches:Indian juice brands are piloting multilayer pouch formats with transmittance-rated barriers as alternatives to rigid carton structures for single-serve distribution.
- PLI scheme alignment:India's production-linked incentive framework for advanced manufacturing rewards domestic laminate and converting capacity expansion with tariff and tax concessions.
Industry Challenges
- Electron-beam technician scarcity:Sterilization equipment operation requires specialized training unavailable in Vietnam and Indonesia, constraining plant commissioning timelines.
- BIS certification bottlenecks:Indian laminate suppliers face extended Bureau of Indian Standards testing queues for food-contact layer approvals, delaying commercial launches.
- Legacy UHT line incompatibility:Southeast Asian processors operate pre-2015 filling machines unable to accommodate newer lightweight carton board specifications without mechanical retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Aseptic Packaging Market |
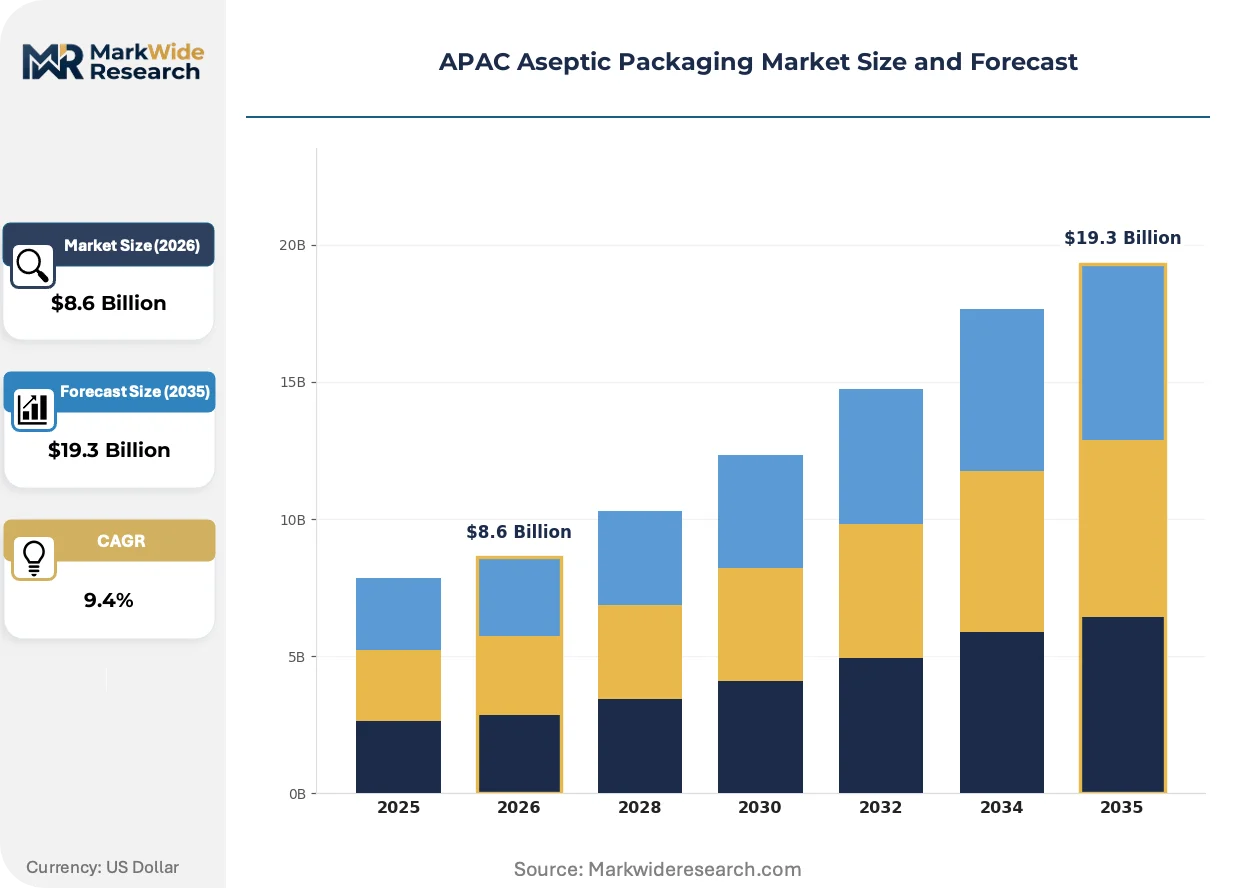
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $19.3 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Products, Solid Products, Semi-Solid Products, Gaseous Products Material: Glass, Plastic, Metal, Paper-based End User: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals Technology: Heat Treatment, UHT Processing, Filtration, Radiation |
| Companies Covered | Tetra Pak International SA, SIG Combibloc Group, Amcor PLC, Elopak ASA, Greatview Aseptic Packaging, Mondi PLC, Uflex Limited, DS Smith PLC, Sealed Air Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Aseptic Packaging Market Strategic Shifts
Sterilization modality choices and laminate material architectures are diverging across dairy, beverage, and pharmaceutical applications as regional regulatory pressures harden. Technology suppliers and converters are recalibrating R&D priorities around energy consumption, barrier performance, and end-of-life recovery pathways.
Electron-beam sterilization is migrating from niche pharmaceutical applications toward high-volume beverage cartons as Japanese and South Korean packaging lines seek to eliminate hydrogen peroxide residue concerns. Dairy processors in Thailand and Vietnam are piloting e-beam systems for ESL milk formats, compressing the traditional vapor-phase equipment supply base and forcing incumbents to defend service-contract revenue through retrofit compatibility programs.
METI energy-efficiency mandates are tightening thermal performance requirements for aseptic filling equipment operating in Japanese ambient dairy plants. The regulation forces converter selection toward lower-melt-index polyethylene sealant layers and thinner aluminum oxide barrier coatings, with pharmaceutical-grade plastic vial manufacturers absorbing premium material costs to maintain PMDA compliance.
Mid-sized dairy processors across Southeast Asia are unbundling equipment procurement from long-term consumables contracts that historically locked buyers into single-supplier carton board and closure systems. Indonesian and Malaysian cooperatives now negotiate filling-machine leases separately from laminate supply agreements, fragmenting vendor relationships that Tetra Pak and SIG Combibloc previously dominated through integrated service models.
APAC Aseptic Packaging Market Segmentation
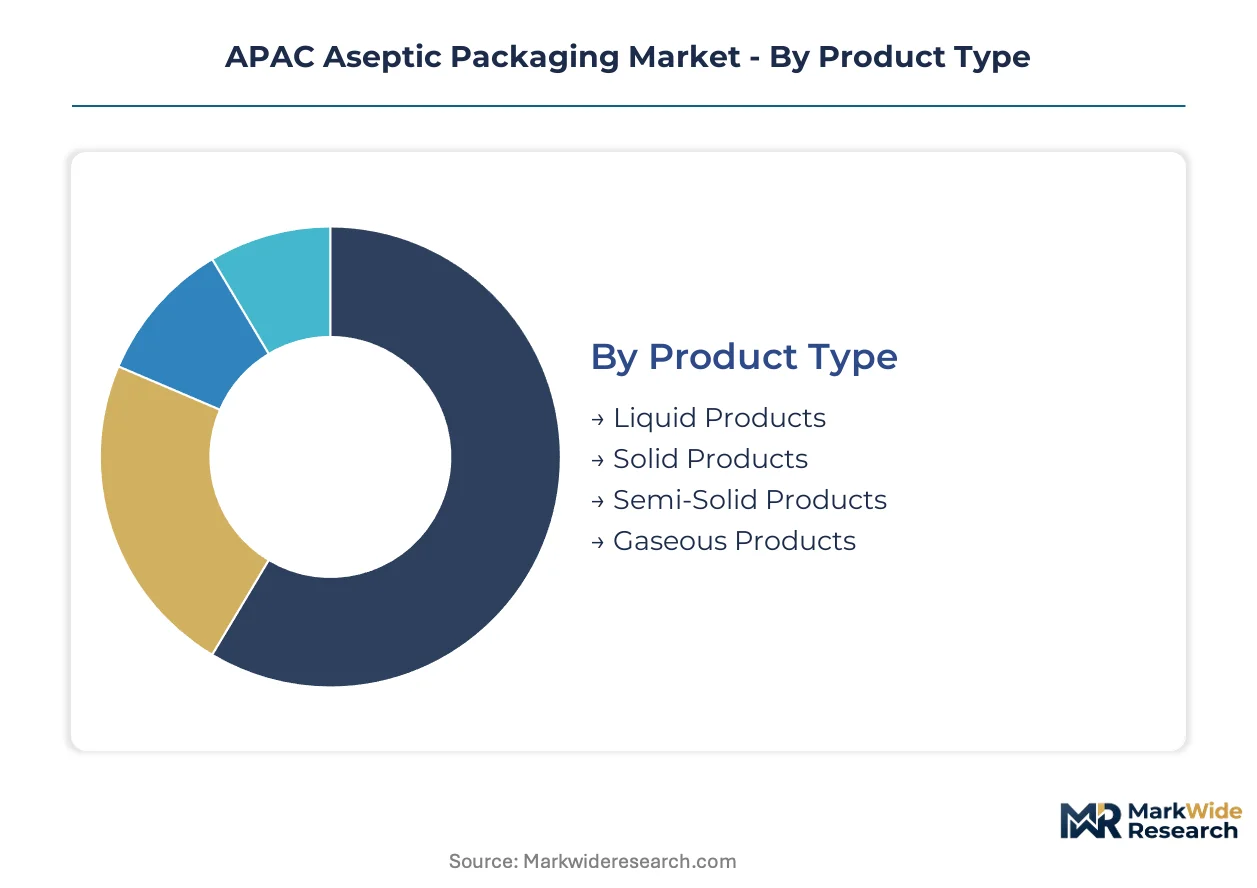
APAC aseptic packaging configurations diverge sharply across product viscosity, barrier requirements, and sterilization modality. Segment boundaries shift as pharmaceutical-grade specifications migrate into premium beverage applications and dairy processors unbundle equipment from consumables contracts.
Product Type:
Application viscosity determines sterilization protocol selection and filling equipment configuration across the region.
- Liquid Products:UHT-processed milk, plant-based beverages, and sterile pharmaceutical solutions flow through hydrogen peroxide vapor or electron-beam sterilized cartons and bottles. Demand concentrates in Southeast Asian dairy corridors and India's Mumbai-Hyderabad pharmaceutical axis where cold-chain-free distribution networks are expanding.
- Semi-Solid Products:Yogurt, purees, and cosmetic creams require modified aseptic filling heads with positive-displacement pumps and nitrogen flush systems to maintain texture integrity. Thai and Vietnamese processors are piloting ESL formats with extended ambient shelf life, compressing traditional chilled distribution requirements.
- Solid Products:Freeze-dried pharmaceuticals and dehydrated food ingredients utilize sterile pouch formats with desiccant integration.
- Gaseous Products:Aerosolized drug delivery systems and compressed culinary gases employ specialized valve-sealing aseptic technologies with limited regional penetration.
Liquid Products holds installed capacity. Semi-Solid Products is rotating up the share rankings.
Material:
Barrier performance and end-of-life recovery pathways shape converter procurement decisions under tightening regulatory frameworks.
- Paper-based:Multilayer cartons with aluminum oxide or polyethylene terephthalate barrier layers dominate ambient dairy and juice volume due to established recycling infrastructure and cost efficiency. China's GB standards for food-contact adhesives and Japan's METI energy-efficiency mandates are accelerating laminate substitutions toward lower-carbon structures.
- Plastic:Pharmaceutical-grade polyethylene and polypropylene vials, ampoules, and bottles command premium margins in oncology drug packaging with PMDA sterility assurance validation. South Korean and Japanese manufacturers absorb elevated material costs to maintain regulatory compliance.
- Glass:Borosilicate and treated soda-lime containers serve parenteral drug and high-acid food segments requiring inert contact surfaces.
- Metal:Aluminum and tinplate cans retain niche positions in retort-equivalent aseptic applications with limited regional growth.
Paper-based maintains dominant volume position. Plastic is climbing the fastest in value terms.
End User:
Customer regulatory intensity and validation requirements fragment vendor relationships across the value chain.
- Food & Beverages:Dairy processors, juice bottlers, and plant-based drink manufacturers across Indonesia, Malaysia, and Vietnam are unbundling equipment procurement from long-term consumables contracts. Modular filling-machine partnerships now allow mid-sized cooperatives to access aseptic capacity without integrated Tetra Pak or SIG Combibloc commitments.
- Pharmaceuticals:Sterile vial and ampoule demand concentrates along India's production corridor with PLI scheme incentives rewarding domestic laminate and converting capacity expansion. Japan's PMDA sterility assurance level requirements filter entrants lacking electron-beam or vapor-phase hydrogen peroxide validation documentation.
- Cosmetics:Premium skincare and sun care brands in South Korea and Japan adopt aseptic pouch formats for preservative-free formulations.
- Nutraceuticals:Probiotic and functional ingredient packaging bridges food and pharmaceutical specifications with emerging regulatory clarity.
Food & Beverages anchors installed base. Pharmaceuticals is expanding most quickly.
Technology:
Sterilization modality choices harden around energy consumption, residue concerns, and validation capability availability.
- UHT Processing:Ultra-high temperature treatment combined with hydrogen peroxide vapor sterilization leads installation counts across Southeast Asian beverage plants serving ambient distribution networks. Legacy pre-2015 filling machines in Indonesian and Malaysian facilities face mechanical retrofit requirements to accommodate newer lightweight carton specifications.
- Radiation:Electron-beam sterilization migrates from niche pharmaceutical applications toward high-volume beverage cartons as Japanese and South Korean lines eliminate hydrogen peroxide residue concerns. Technician scarcity in Vietnam and Indonesia constrains plant commissioning timelines.
- Heat Treatment:Steam and hot-air systems retain positions in glass container and metal can applications with established validation protocols.
- Filtration:Membrane and depth filtration serve liquid pharmaceutical and biotechnology applications requiring sterile bulk processing.
UHT Processing dominates installed base. Radiation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy processors and pharmaceutical manufacturers across Asia-Pacific drive divergent packaging requirements. Cold-chain-free distribution networks expand in Southeast Asian beverage corridors while sterility-assured oncology packaging concentrates in Indian and Japanese pharmaceutical clusters.
China
Domestic beverage brands and dairy cooperatives propel carton demand in the Yangtze and Pearl River Delta manufacturing belts. SAMR enforces GB standards for food-contact adhesive chemistries that restrict specific epoxy-based formulations. Shanghai and Suzhou converters accelerate laminate substitutions toward lower-carbon multilayer structures under MEE energy-efficiency mandates.
India
Juice bottlers and plant-based drink startups seek flexible pouch alternatives to rigid carton formats for single-serve distribution. FSSAI mandates nutritional labeling and shelf-life declarations that reshape carton design specifications. The Mumbai-Hyderabad pharmaceutical corridor concentrates sterile vial and ampoule demand with PLI scheme incentives rewarding domestic laminate capacity expansion.
Japan
Premium skincare brands and ambient dairy processors adopt preservative-free aseptic pouch formats. METI energy-efficiency mandates tighten thermal performance requirements for filling equipment operating in Kanto and Kansai industrial zones. Osaka and Nagoya packaging lines pilot electron-beam sterilization to eliminate hydrogen peroxide residue concerns in high-volume beverage cartons.
Vietnam
Mid-sized dairy cooperatives in the Mekong Delta seek modular filling-machine partnerships to access aseptic capacity without integrated equipment commitments. The national food safety authority enforces labeling and shelf-life declaration standards adapted from regional ASEAN frameworks. Ho Chi Minh City processors face electron-beam technician scarcity that constrains plant commissioning timelines for new sterilization lines.
Indonesia
Beverage plants serving archipelago distribution require cold-chain-free ambient packaging for dairy and plant-based drinks. The national standards body implements food-contact material testing protocols that extend BIS-equivalent certification timelines for imported laminates. Jababeka and MM2100 industrial estates outside Jakarta host pre-2015 filling machines requiring mechanical retrofit to accommodate lightweight carton board specifications.
APAC Aseptic Packaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented vendor relationships. Integrated equipment-service models anchor long-term customer commitments while modular filling partnerships reduce capital barriers for mid-sized processors. Three archetypes dominate: multinational system suppliers with captive consumables contracts, regional converters with flexible laminate capabilities, and domestic specialists serving single-country beverage supply. Competitive moves center on unbundling equipment from consumables contracts and forming strategic alliances with third-party filling operators.
Among the integrated system suppliers, Tetra Pak International SA and SIG Combibloc Group exemplify equipment-captive business models that historically locked buyers into long-term carton board and closure commitments. Greatview Aseptic Packaging occupies a position within the domestic specialist tier, representing Chinese beverage supply concentration. Uflex Limited anchors the regional converter archetype, with its Indian corporate structure supporting flexible packaging extensions into aseptic pouch formats.
| Leading Market Players |
|---|
| Tetra Pak International SA |
| SIG Combibloc Group |
| Amcor PLC |
| Elopak ASA |
| Greatview Aseptic Packaging |
| Mondi PLC |
| Uflex Limited |
| DS Smith PLC |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Chinese primary aluminum smelter concentration anchors oxygen barrier layer costs, translating downstream into margin compression for converters serving Japanese pharmaceutical and Southeast Asian dairy end-users. This upstream tethering forces laminate suppliers to absorb volatility or pass through to buyers with divergent price sensitivity across certification tiers.
Pricing Analysis
Certification level (PMDA-grade versus FSSAI-standard) creates the primary spread between Japanese oncology packaging and Indian beverage cartons, with three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade electron-beam validation commands substantial premiums over vapor-phase hydrogen peroxide systems. Cost compression in mid-tier dairy converters is intensifying because unbundled equipment leases fragment historical consumables lock-ins. Mid-sized Vietnamese cooperatives exhibit highest price sensitivity, while Japanese drug manufacturers absorb elevated material costs to maintain regulatory compliance.
Supply Chain Analysis
Export-control restrictions on electron-beam sterilization equipment limit technology flows from Japan and South Korea into Vietnam and Indonesia, constraining plant commissioning capacity. Primary aluminum sourcing draws from Chinese and Indonesian smelter bases, while laminate converting clusters in Shanghai, Suzhou, and Mumbai feed regional demand. Single-source vulnerability pervades specialized adhesive chemistries reformulated under China's GB standards. Distribution runs through converter-direct relationships with dairy processors and pharmaceutical manufacturers, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light contract manufacturing fragments vendor control across APAC aseptic packaging, creating entry niches as mid-sized processors unbundle equipment from consumables commitments. This demand-side shift rewards modular filling partnerships and flexible laminate specialists.
For Market Incumbents: Build validation capability moats through electron-beam technician training programs and PMDA documentation repositories. Tetra Pak and SIG Combibloc should retrofit legacy filling-machine installed bases to accommodate lightweight carton specifications, defending service-contract revenue against regional modular partnerships. Certification investment in China's evolving GB adhesive standards represents critical defensive positioning. For New Entrants and Emerging Players: Vietnamese dairy cooperatives in the Mekong Delta represent the most penetrable entry point, with modular filling-machine partnerships bypassing integrated equipment capital barriers. Indian flexible pouch formats for juice brands offer second white-space target, leveraging Uflex Limited's laminate capabilities as reference architecture. Go-to-market through BIS certification pre-qualification services addresses Indian laminate approval bottlenecks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional converters possessing flexible packaging capabilities but lacking electron-beam validation infrastructure. Five-to-ten year viability hinges on PLI scheme alignment in India and METI energy-efficiency mandate compliance in Japan. Monitor BIS certification queue lengths as inflection indicator for Indian commercial launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Filling Partnership Formation | Vietnamese dairy processors access aseptic capacity without Tetra Pak integrated commitments. |
| Electron-Beam Technician Training Program | Japanese equipment suppliers address scarcity constraining Vietnamese plant commissioning timelines. |
| PLI Scheme Capacity Expansion | Indian laminate suppliers secure tariff and tax concessions for domestic converting investments. |
| Lightweight Carton Retrofit Compatibility | Incumbent equipment vendors defend service-contract revenue against unbundling trends. |
| GB Standard Adhesive Reformulation | Chinese converters maintain SAMR compliance while qualifying lower-carbon multilayer structures. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, FSSAI labeling mandates, METI efficiency benchmarks, and trade customs data. Conversations with converter procurement managers, dairy plant engineers, pharmaceutical packaging directors, and electron-beam equipment technicians inform qualitative assessments. Bottom-up demand modeling from UHT installation counts and top-down value triangulation from laminate trade flows validate magnitude estimates.
Forecast inputs span product viscosity segments, sterilization modality technology choices, and end-user regulatory intensity across the analysis window. Segmentation dimensions include material barrier architecture, certification grade tiers, and geographic production hub clustering. CAGRs derive from installed capacity expansion rates cross-referenced against laminate consumption patterns. Specific inputs incorporate China's dual carbon goal enforcement trajectories and India's PLI scheme uptake curves.
Practitioners should monitor aluminum smelter output volatility, BIS certification queue extensions, and electron-beam technician training pipeline expansion for early signals. Forecasts embed assumptions around MEE energy-efficiency mandate adherence and PMDA validation documentation availability. Material shifts in Chinese export-control posture on sterilization equipment or abrupt GB standard adhesive restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market