
 Global Aseptic Paper Packaging Market | 2026-2036
Global Aseptic Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aseptic Paper Packaging Market Analysis
Packaging engineering talent is rotating toward barrier-coating chemistry and sterile filling integration, tightening labor pools in Germany and Japan. Tetra Pak International SA leverages its captive R&D network across Lund and Singapore to sustain format innovation. SIG Combibloc Group anchors European dairy supply through regional filling-machine deployment. Amcor PLC competes by extending film-lamination expertise into paper-based aseptic structures.
Aseptic paper packaging denotes multi-layer liquid-container systems combining paperboard substrates with aluminum oxide or ethylene vinyl alcohol barrier films, sterilized via hydrogen peroxide vapor or electron-beam irradiation before filling. The composite achieves six-month ambient shelf stability without preservatives, serving dairy, juice, and nutritional liquid distribution. Carton formats dominate volume throughput due to established filling-line infrastructure, while pouch configurations capture emerging demand in single-serve and on-premise channels. Beverage grade commands the widest specification latitude, though pharmaceutical grade concentrates margin pools where sterility validation requirements elevate switching costs.
FDA food-contact notification rules and EU REACH chemical restrictions jointly shape adhesive and coating selections for US and European export formats. China's SAMR enforces GB standards on heavy-metal migration limits, conditioning local production qualifications. India's FSSAI notification requirements for imported packaging materials add compliance layers for multinational suppliers. Stakeholders must monitor divergence between regional sterilization validation protocols and emerging bio-based barrier material certifications.
Market Dynamics
The EU Green Deal's material sourcing mandates are compressing aluminum oxide availability while China's dual carbon goals redirect paperboard supply toward domestic converters, forcing multinational packagers to requalify barrier-film formulations across three continents simultaneously.
Growth Catalysts
- EU Green Deal packaging waste targets:The regulation mandates 70% recyclability thresholds for liquid cartons by 2030, accelerating converter investment in fiber-based barrier coatings across German dairy processing corridors.
- Southeast Asia urban food processing:Vietnam and Indonesia's chilled dairy distribution networks are expanding ambient-stable formats to bypass refrigeration infrastructure gaps in secondary cities.
- Electron-beam sterilization:This dry sterilization method eliminates hydrogen peroxide residue concerns, enabling pharmaceutical-grade aseptic validation for nutritional supplement brands in Japan.
Market Restraints
- Aluminum oxide price volatility:Smelter energy costs in Iceland and Norway fluctuate with Nordic grid pricing, transmitting input cost spikes to laminate converters within 60-day procurement windows.
- Filling-machine supply concentration:European and Japanese equipment builders control 85% of high-speed aseptic line deployment, creating 18-month order backlogs for Brazilian and Indian dairy cooperatives.
- Ethylene vinyl oxygen barrier limitations:EVOH's moisture sensitivity restricts shelf-life extension in tropical climates, capping ambient distribution reach for Indonesian juice brands.
Strategic Opportunities
- India's FSSAI import notification streamlining:Proposed mutual recognition agreements with EU notified bodies would halve packaging material approval timelines for European suppliers.
- Single-serve pouch formats:On-premise coffee and tea chains in South Korea are piloting aseptic paper pouches as aluminum can alternatives, opening 200-300ml volume tiers.
- Bio-based barrier certification convergence:USDA BioPreferred and EU EN 13432 standards are aligning testing protocols, reducing dual-certification costs for polylactic acid coating developers.
Industry Challenges
- Sterile filling integration engineering:Dairy processors in Brazil and Mexico lack in-house automation expertise to synchronize new barrier materials with legacy hydrogen peroxide vapor lines.
- GB standard heavy-metal migration compliance:China's SAMR testing protocols for cadmium and lead differ from FDA extraction methods, forcing parallel laboratory qualification for export formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aseptic Paper Packaging Market |
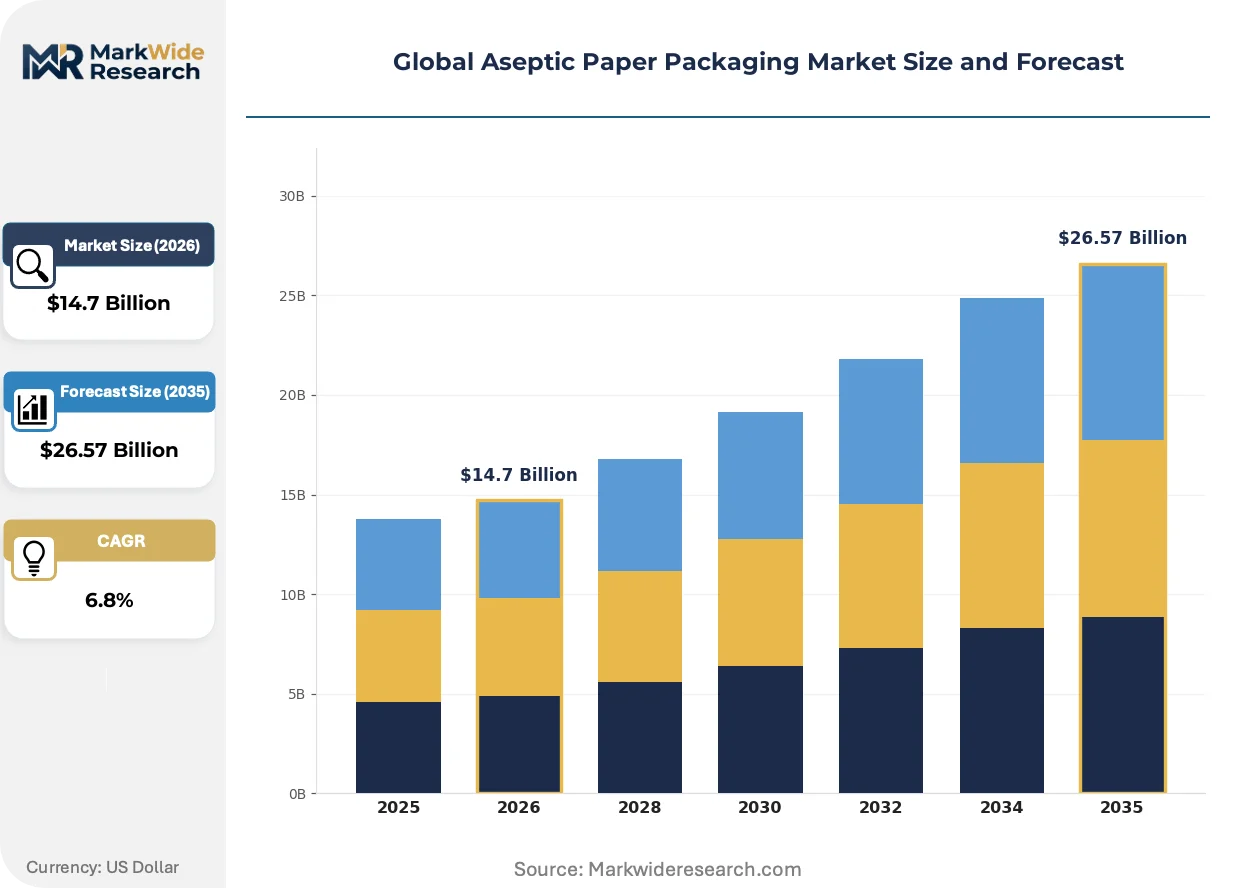
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight-Wall Containers, Gable-Top Containers, Pouch, Carton Grade: Food Grade, Beverage Grade, Industrial Grade, Pharmaceutical Grade End User: Food & Beverage, Pharmaceuticals, Personal Care, Household Goods Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Tetra Pak International SA, SIG Combibloc Group, Amcor PLC, Elopak AS, Greatview Aseptic Packaging, Evergreen Packaging, Nippon Paper Industries, Mondi PLC, IPI Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aseptic Paper Packaging Market Emerging Trajectories
Barrier-coating chemistry is fragmenting into competing technical camps while regulatory jurisdictions proliferate conflicting material certifications, compressing product development cycles and elevating qualification costs for format suppliers.
Polymer-grade cellulose nanofiber coatings are decomposing the aluminum oxide monopoly in high-barrier applications. German dairy brands are piloting these fiber-derived barriers for six-month shelf-life milk cartons, with Tetra Pak's Lund R&D facility validating oxygen transmission rates below 0.1 cc/m²/day. The technology is decomposing incumbent laminate structures by eliminating the energy-intensive metallization step while complicating existing filling-line sterilization protocols calibrated to aluminum thermal properties.
REACH chemical restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer grease barriers from paperboard food-contact layers. ECHA's 2023 PFAS restriction proposal forces converters to requalify plant-based wax and silicone alternatives across European dairy and juice formats. Beverage-grade cartons face the steepest reformulation costs, as PFAS historically enabled high-speed filling without stick-release failures on hydrophilic paper surfaces.
Direct-store-delivery networks in China's tier-two cities are compressing traditional distributor layers for ambient-stable beverages. Yili and Mengniu dairy groups are building captive last-mile fleets to bypass wholesale markets, demanding smaller 125-200ml carton formats optimized for convenience-store shelf configurations. This channel restructuring concentrates volume with domestic dairy conglomerates while marginalizing regional juice brands lacking refrigerated distribution infrastructure.
Global Aseptic Paper Packaging Market Segmentation
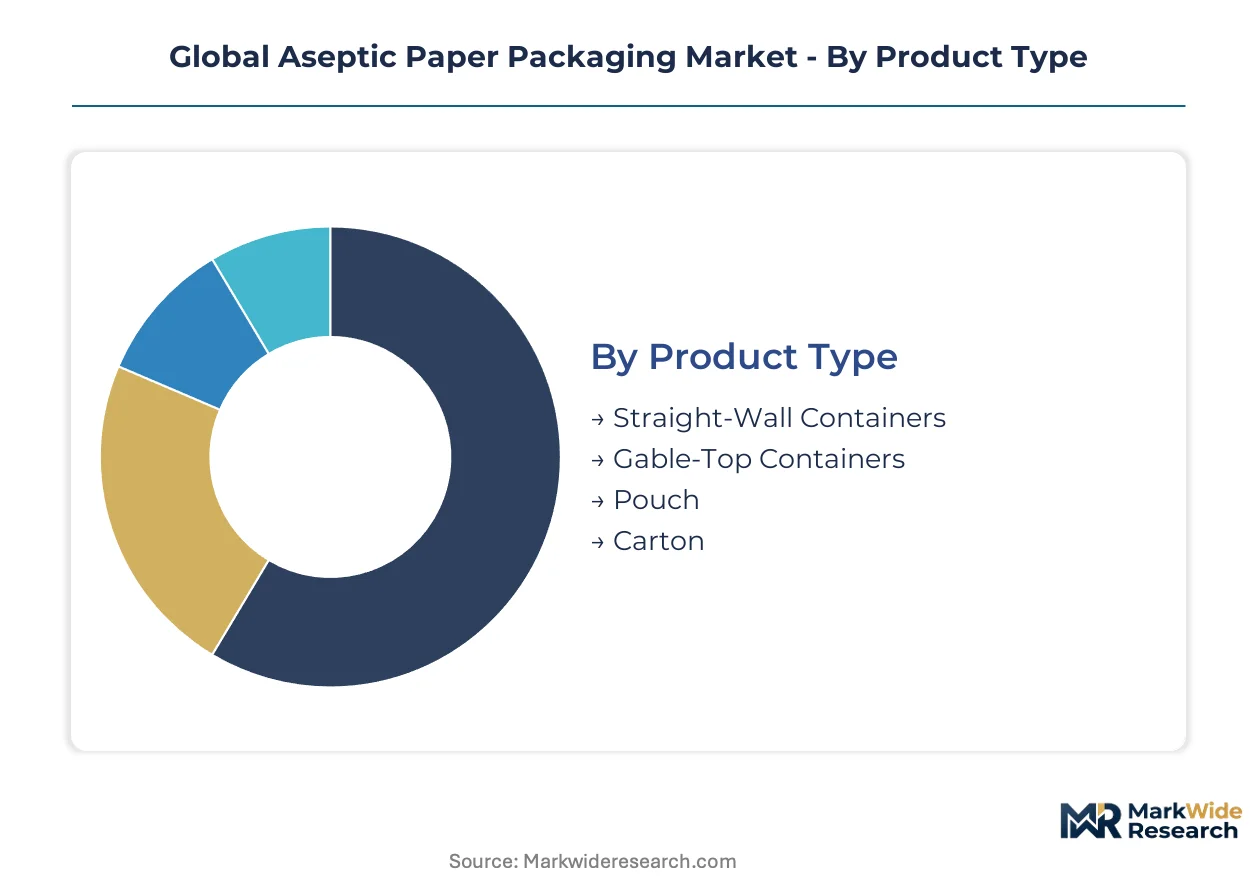
Aseptic paper packaging segments channel through distinct procurement pathways. Carton formats leverage established filling-line infrastructure while pouch configurations penetrate convenience-store and foodservice channels. Grade specifications determine regulatory qualification burden and margin capture potential across dairy, pharmaceutical, and industrial end-uses.
Product Type:
Channel mix varies sharply by format geometry. Carton and gable-top containers flow through high-volume dairy cooperatives and retail chains. Pouch and straight-wall formats penetrate on-premise consumption and single-serve retail channels.
- Carton:Multi-layer rectangular structures combining paperboard with aluminum oxide or EVOH barriers, sterilized via hydrogen peroxide vapor before filling. German and Chinese dairy processors anchor volume demand as EU Green Deal recyclability mandates accelerate fiber-based barrier coating investment.
- Pouch:Flexible laminated structures with spout or straw-fitment configurations, enabling 125-300ml single-serve formats. South Korean coffee chains and Indonesian juice brands are piloting these as aluminum can alternatives for on-premise channels.
- Gable-Top Containers:Roof-shaped cartons with pour-spout closures, common in fresh milk distribution requiring refrigerated logistics rather than ambient stability.
- Straight-Wall Containers:Cylindrical or rectangular rigid formats with flat sealing surfaces, deployed in nutritional supplement and ready-to-drink beverage segments.
Carton dominates installed base. Pouch is where expansion concentrates.
Grade:
Margin stratification follows validation rigor. Pharmaceutical and food grades command premium pricing through sterility documentation. Beverage grade operates at highest volume throughput with widest specification latitude.
- Beverage Grade:Standard six-month ambient shelf-life specifications for dairy, juice, and plant-based liquids. Tetra Pak and SIG Combibloc filling lines across Vietnam and Indonesia process this grade at highest throughput rates.
- Pharmaceutical Grade:Validated sterility assurance levels per FDA food-contact notification and EU GMP Annex 1, with electron-beam sterilization eliminating hydrogen peroxide residue concerns. Japanese nutritional supplement brands concentrate demand here.
- Food Grade:Intermediate barrier specifications for sauces, purees, and prepared foods, subject to FDA extraction testing and EU REACH adhesive restrictions.
- Industrial Grade:Non-food-contact applications including chemical and agricultural liquid containment, with reduced barrier requirements and lower unit margins.
Pharmaceutical grade captures highest margin per unit. Beverage grade represents the fastest-growing trajectory by absolute volume.
End User:
Customer concentration shapes technical service requirements. Food and beverage processors demand filling-line integration support. Pharmaceutical buyers prioritize batch documentation and audit trails.
- Food & Beverage:Dairy groups in Germany, China, and Brazil plus juice processors in Indonesia and Vietnam constitute primary demand. Yili and Mengniu are building captive last-mile fleets for tier-two Chinese cities.
- Pharmaceuticals:Nutritional liquid and oral dosage manufacturers in Japan and Europe require pharmaceutical-grade validation with full sterility documentation.
- Personal Care:Cosmetic and hygiene product brands utilize aseptic formats for preservative-free formulations, though at lower volume scale than food applications.
- Household Goods:Cleaning and maintenance product distributors, constrained by EVOH moisture sensitivity in tropical climate distribution.
Food and beverage anchors volume commitment. Pharmaceuticals is where qualification barriers protect margin.
Distribution Channel:
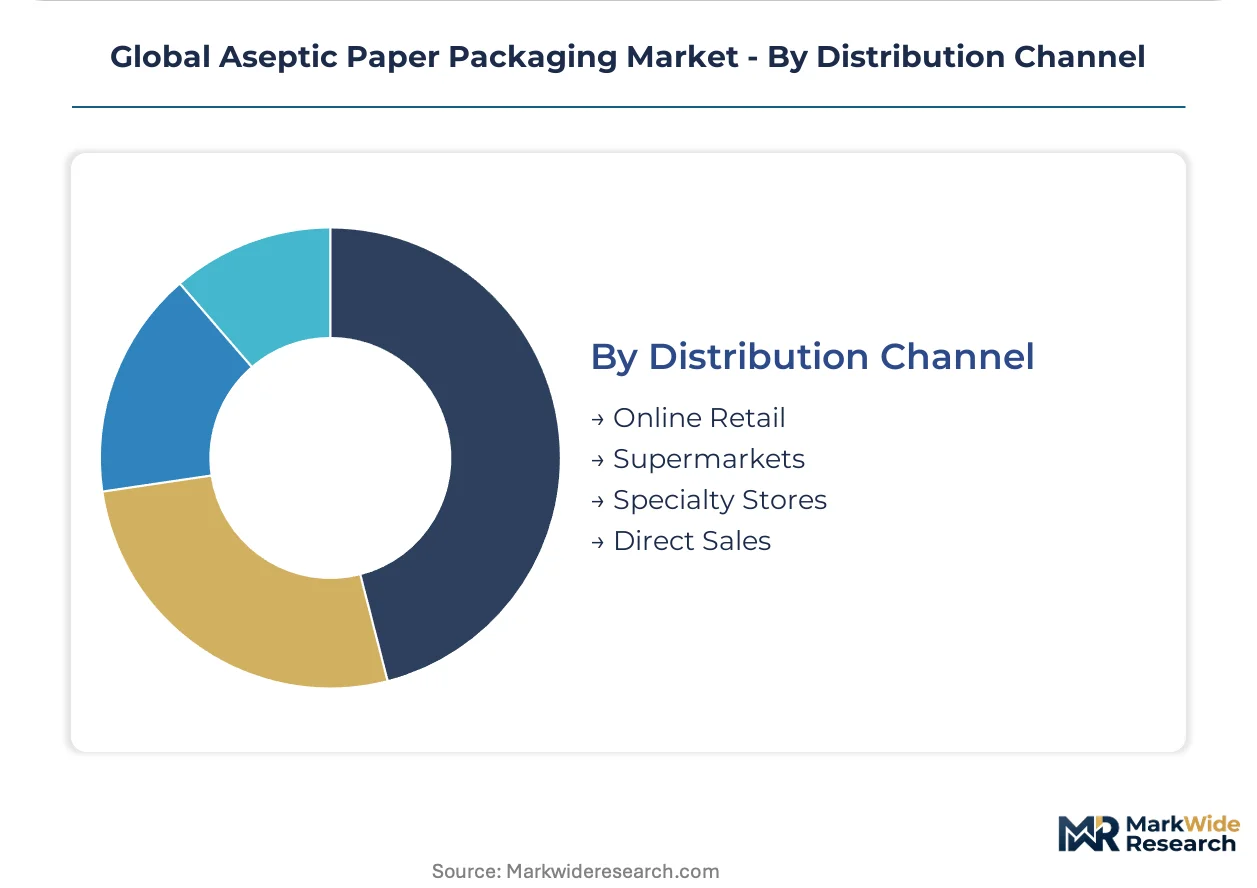
Channel restructuring in Asia is compressing traditional wholesale layers. Direct-store-delivery networks and online retail are gaining share against supermarket intermediaries.
- Supermarkets:Multi-brand retail chains in Germany and Brazil stock ambient-stable dairy and juice cartons, with shelf-space allocation driving format standardization.
- Direct Sales:Captive distribution by dairy conglomerates bypassing wholesale markets, concentrated in China's tier-two cities through Yili and Mengniu fleet investments.
- Online Retail:E-commerce platforms for subscription nutritional supplements and bulk beverage purchases, requiring damage-resistant outer packaging configurations.
- Specialty Stores:Premium organic and plant-based beverage channels in urban European markets, favoring certified sustainable barrier materials.
Supermarkets dominate historical throughput. Direct sales is where channel restructuring accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European regulatory pressure while China's SAMR enforces parallel compliance tracks, forcing multinational packagers to navigate divergent material certification regimes across three continents simultaneously.
Germany
Dairy cooperatives in Bavaria and Lower Saxony are retrofitting filling lines for fiber-based barrier coatings to meet EU recyclability mandates. ECHA's PFAS restrictions are accelerating plant-based wax requalification across carton formats. The Baden-Württemberg converter cluster is piloting cellulose nanofiber barriers for six-month shelf-life milk applications.
China
Yili and Mengniu dairy groups are building captive last-mile fleets for tier-two cities, compressing traditional wholesale distribution layers. SAMR's GB standards on heavy-metal migration differ from FDA extraction methods, forcing parallel laboratory qualification. The Yangtze River Delta converter base is redirecting paperboard supply toward domestic processors under dual carbon goals.
Brazil
Dairy cooperatives in São Paulo and Minas Gerais face 18-month backlogs for high-speed aseptic filling equipment from European and Japanese builders. ANVISA's food-contact notification requirements add compliance layers for imported barrier materials. The São Paulo industrial corridor is expanding orders for ambient-stable carton formats to bypass refrigeration infrastructure gaps in secondary cities.
Indonesia
Juice processors in Java are piloting aseptic paper pouches as aluminum can alternatives for convenience-store channels. EVOH moisture sensitivity caps shelf-life extension in tropical climates, limiting ambient distribution reach. The Jakarta-Bandung food processing corridor is expanding chilled dairy networks into ambient-stable formats.
Japan
Nutritional supplement brands are adopting electron-beam sterilization to eliminate hydrogen peroxide residue concerns for pharmaceutical-grade validation. METI's chemical management frameworks shape adhesive selections for export formats. The Kanto industrial base is concentrating barrier-coating chemistry talent toward sterile filling integration engineering.
Global Aseptic Paper Packaging Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding captive R&D networks and filling-machine deployment capabilities. The middle tier competes through film-lamination expertise and regional converter relationships. Three archetypes dominate: integrated packaging systems providers, barrier-material specialists, and regional filling-equipment fabricators. Competitive moves concentrate on strategic partnerships for bio-based barrier certification and geographic expansion into Southeast Asian dairy corridors.
Within the integrated systems tier, Tetra Pak International SA and SIG Combibloc Group exemplify the R&D-intensive archetype with captive innovation facilities. Amcor PLC occupies a position bridging film-lamination expertise into paper-based aseptic structures. These three anchors represent distinct strategic postures: Lund and Singapore-based innovation networks, European dairy supply anchoring through regional machine deployment, and materials science extension from flexible packaging into rigid paper formats.
| Leading Market Players |
|---|
| Tetra Pak International SA |
| SIG Combibloc Group |
| Amcor PLC |
| Elopak AS |
| Greatview Aseptic Packaging |
| Evergreen Packaging |
| Nippon Paper Industries |
| Mondi PLC |
| IPI Srl |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German dairy cooperatives and Nordic aluminum oxide smelters lock in barrier-film supply visibility while insulating converters from Iceland and Norway's volatile grid-driven energy pricing. These contracts anchor cost predictability for carton converters serving EU Green Deal recyclability mandates.
Pricing Analysis
Contract-based long-term offtake dominates procurement between laminate converters and aluminum oxide suppliers, with premium-mid-economy pricing differentiation separating pharmaceutical-grade validation tiers from standard beverage specifications. Cost compression in standard beverage grades intensifies as Chinese domestic paperboard redirection under dual carbon goals tightens regional supply. Dairy cooperatives in Brazil and India exhibit highest price sensitivity due to filling-equipment backlogs, while Japanese pharmaceutical brands show lowest sensitivity given sterility documentation requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian paperboard feedstock flows, yet single-source vulnerability concentrates in China's Yangtze River Delta converter base and Germany's Baden-Württemberg coating cluster. Raw material dependencies center on aluminum oxide from Nordic smelters, EVOH resin from Japanese petrochemical networks, and cellulose nanofiber pilot outputs from Lund R&D facilities. Distribution runs through direct-store-delivery networks in China's tier-two cities and traditional wholesale layers in Brazilian secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic paper packaging is approaching a platform-economics inflection as sterile filling-line interoperability becomes the binding constraint on barrier-material adoption, with Tetra Pak's captive R&D network and SIG Combibloc's regional machine deployment creating ecosystem lock-in effects.
For Market Incumbents: Compound barrier-coating chemistry expertise through captive cellulose nanofiber pilot programs in Germany and Singapore to outpace REACH PFAS restriction timelines. Defend installed base by accelerating sterile filling integration engineering support for Brazilian dairy cooperatives facing hydrogen peroxide vapor line synchronization failures. For New Entrants and Emerging Players: Differentiate on bio-based barrier certification convergence between USDA BioPreferred and EU EN 13432 protocols to reduce dual-qualification costs for polylactic acid coating developers. Target South Korean on-premise coffee chains piloting 200-300ml aseptic paper pouches as aluminum can alternatives. For Investors and Strategic Acquirers: Capital is best deployed toward regional filling-equipment fabricators with electron-beam sterilization capabilities, as dry sterilization eliminates hydrogen peroxide residue concerns for pharmaceutical-grade validation. Monitor alignment between China's SAMR heavy-metal migration testing protocols and FDA extraction methods as inflection indicator for multinational supplier qualification costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cellulose Nanofiber Production | Eliminates aluminum oxide dependency for German dairy carton barriers. |
| Electron-Beam Sterilization Line Deployment | Enables Japanese pharmaceutical-grade validation without hydrogen peroxide residue. |
| Regional Filling-Equipment Fabrication Partnership | Reduces 18-month backlogs for Brazilian dairy cooperative expansion. |
| Bio-Based Barrier Dual Certification Program | Aligns USDA BioPreferred and EU EN 13432 testing for polylactic acid coatings. |
| Direct-Store-Delivery Format Optimization | Captures Yili and Mengniu fleet investments in China's tier-two cities. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with sterile filling integration engineers, barrier-coating R&D directors, dairy procurement leads, and Southeast Asian converter operations managers; and secondary validation through EU ECHA PFAS restriction filings, China SAMR GB standard notifications, FDA food-contact submission databases, and Nordic aluminum smelter energy cost disclosures. Bottom-up volume modeling triangulated against top-down value estimates across carton and pouch format segments.
Across the analysis window, forecasts incorporated grade-tier stratification, end-use industry concentration, regional regulatory cluster divergence, and filling-line sterilization protocol fragmentation. CAGRs derived from installed base expansion rates in Vietnamese and Indonesian dairy networks, electron-beam sterilization adoption curves in Japanese pharmaceutical applications, and EU Green Deal recyclability mandate compliance timelines.
The analysis sits within stated boundaries; outcomes outside sustained aluminum oxide price volatility, REACH PFAS restriction enforcement, or China dual carbon goal acceleration would require recalibration. Practitioners should keep alternative scenarios live as sterile filling integration engineering capacity and bio-based barrier certification convergence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
APAC Aseptic Packaging Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market