
 Europe Aseptic Packaging Market | 2026-2036
Europe Aseptic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aseptic Packaging Market Foresight
The EU Green Deal's packaging waste reduction targets is expanding the addressable market for fiber-based aseptic carton systems. Tetra Pak International S.A. leverages its integrated processing and packaging equipment ecosystem to sustain long-term customer lock-in across Nordic dairy cooperatives. DS Smith Plc anchors its position through recycled paperboard supply chains that feed directly into ambient liquid carton lines. SIG Combibloc Group competes on filling speed and format flexibility for mid-sized European beverage brands.
Aseptic packaging denotes a sterilization-based containment method wherein product and packaging material undergo separate thermal or chemical decontamination before combined filling in a sterile environment, typically achieving commercial sterility with residual oxygen levels below 0.5% in the headspace. Paperboard-based cartons dominate volume flows in European ambient dairy and juice distribution due to established recycling infrastructure and lightweight logistics economics. Glass bottles command premium positioning in organic infant nutrition and pharmaceutical oral dosing where inert material properties justify higher unit costs. Plastic pouches represent the fastest-expanding format in ready-to-drink protein beverages where flexible logistics and portion control drive brand switching.
EMA guidelines on sterile pharmaceutical manufacturing and the EU F-Gas Regulation on blowing agent emissions jointly constrain material choices and equipment specifications for European producers. ECHA's REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of barrier coatings in paperboard aseptic cartons ahead of broader enforcement timelines. Stakeholders must monitor how the EU Packaging and Packaging Waste Regulation's recyclability performance grades redirect capital toward mono-material or fiber-dominant aseptic structures.
Market Dynamics
The EU Green Deal's packaging waste reduction targets are compressing capital allocation timelines for fiber-based aseptic carton conversion, forcing dairy and beverage processors to accelerate equipment replacement cycles ahead of regulatory enforcement windows.
Growth Catalysts
- ECHA REACH restrictions on PFAS:Barrier coating reformulation mandates are pulling investment into fluorine-free polymer alternatives for paperboard cartons, expanding the addressable market for compliant material suppliers.
- Ambient yogurt distribution:Cold-chain-free logistics economics are driving French and German dairy processors to expand aseptic carton lines for shelf-stable fermented beverages.
- Central European export corridors:Beverage bottling clusters in southern Germany are concentrating demand for high-speed aseptic filling equipment serving cross-border distribution networks.
Market Restraints
- Recycled paperboard supply concentration:DS Smith and limited Nordic pulp suppliers control fiber feedstock for liquid carton grades, creating input vulnerability for mid-tier converters.
- F-Gas Regulation compliance costs:Blowing agent restrictions on plastic aseptic bottle production are elevating capital requirements for European blow-molding equipment upgrades.
- Glass bottle substitution ceiling:Premium organic infant nutrition and pharmaceutical oral dosing segments retain inert material requirements that fiber cartons cannot satisfy.
Strategic Opportunities
- Poland and Romania ambient dairy:Underpenetrated markets for shelf-stable milk and plant-based beverages offer first-mover positioning for carton filling equipment deployments.
- EU Packaging and Packaging Waste Regulation recyclability grades:Mono-material and fiber-dominant aseptic structures will capture preferential capital allocation as performance grading takes effect.
- Digital printing convergence:Integration of variable-data decoration with aseptic carton forming enables batch-level customization for mid-sized European beverage brands.
Industry Challenges
- Sterile validation engineering scarcity:Qualified technicians for aseptic line commissioning and media-fill validation are concentrated among legacy dairy equipment suppliers, constraining expansion timelines.
- Legacy filling equipment interoperability:Retrofitting 1990s-era carton formers with modern hydrogen peroxide sterilization modules requires custom mechanical integration that extends project durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aseptic Packaging Market |
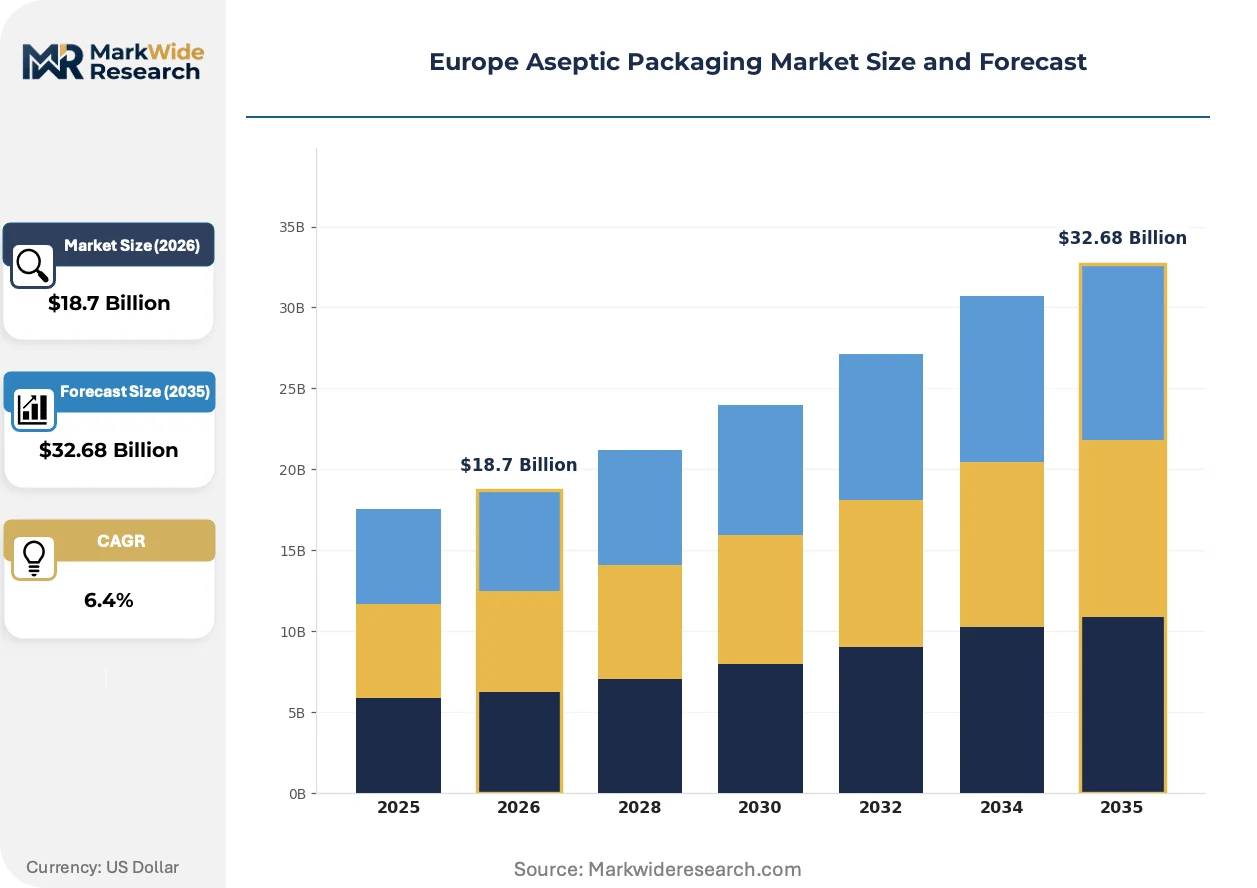
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Bottles, Pouches, Trays Material: Plastic, Glass, Paperboard, Metal End User: Food Industry, Beverage Industry, Pharmaceutical Industry, Dairy Industry Technology: Thermal Processing, Filtration, Filling, Sealing |
| Companies Covered | Tetra Pak International S.A., Schott AG, DS Smith Plc, Amcor Plc, SIG Combibloc Group, Greatview Aseptic Packaging Europe GmbH, Mondi PLC, WestRock Company, Sealed Air Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aseptic Packaging Market Shifts & Advancements
Fiber-based material systems are absorbing capital and technical attention as regulatory pressure on plastic packaging intensifies, while filling equipment automation advances compress operational labor requirements.
Barrier-coated paperboard laminates are absorbing technical development resources previously directed toward multi-layer plastic structures. German and French dairy cooperatives are adopting fluorine-free polymer coatings at pilot scale ahead of broader ECHA enforcement. This material transition is absorbing engineering capacity across European carton board mills, compressing development timelines for competing substrate innovations.
The EU F-Gas Regulation on hydrofluorocarbon blowing agents is constraining plastic bottle production economics for aseptic beverage applications. Equipment manufacturers must redesign extrusion blow-molding systems around alternative foaming chemistries or mechanical expansion methods. Southern European juice bottlers face the steepest compliance cost gradients, accelerating interest in substrate switching toward fiber cartons.
Direct-store-delivery networks for ambient beverages are consolidating procurement authority among retail chain technical buyers. These centralized purchasing functions are unbundling after-sales service contracts from equipment supply agreements, forcing machinery vendors to price maintenance separately. The restructuring is most visible in Germany's discount retail channel, where private-label beverage volumes concentrate negotiating leverage.
Europe Aseptic Packaging Market Segmentation
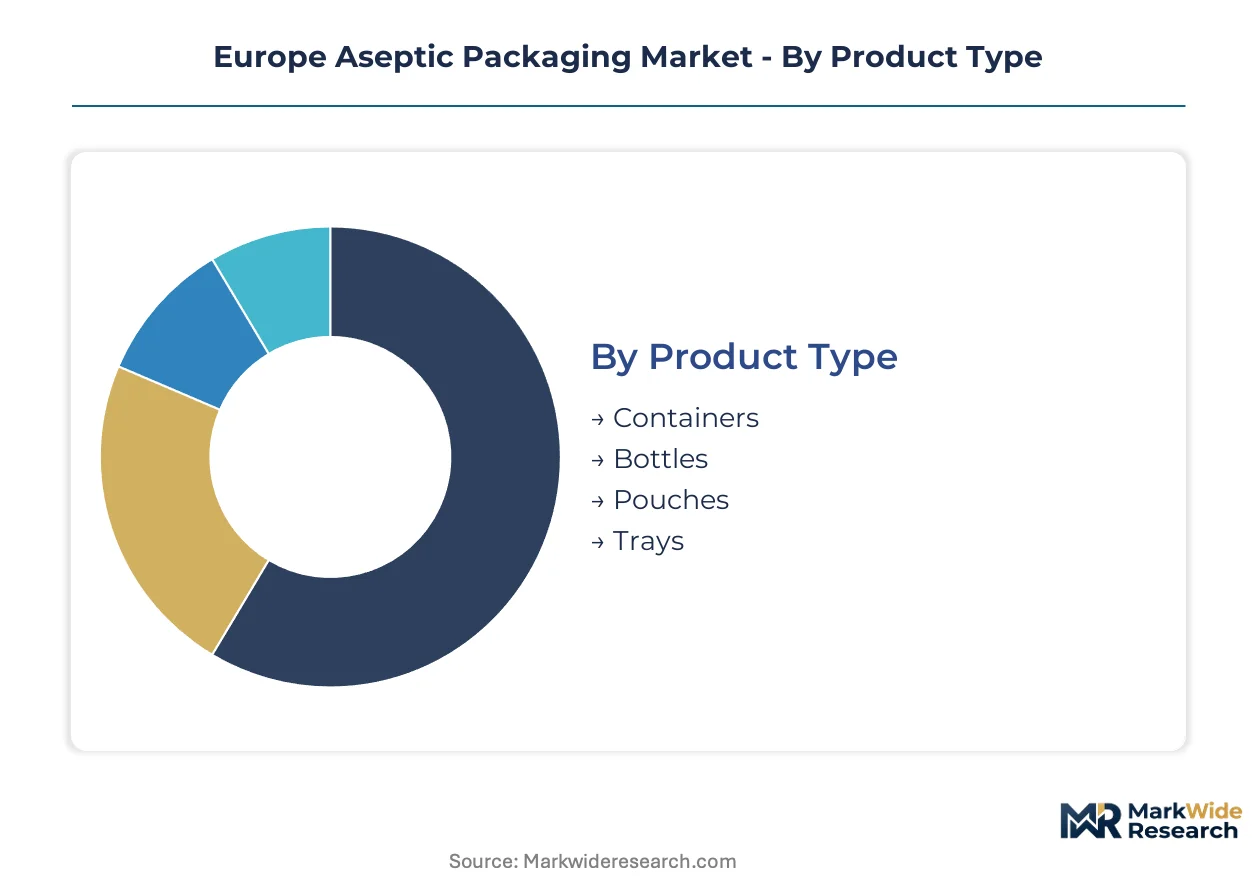
Segmentation in the European aseptic packaging market reveals how regulatory pressure and substrate economics are reallocating capital across material systems and filling technologies. Equipment specifications and barrier requirements diverge sharply between ambient dairy, pharmaceutical, and beverage applications.
Product Type:
Supply concentration in carton forming equipment favors formats with established European machinery ecosystems and aftermarket service networks.
- Containers:Paperboard-based cartons with polyethylene barrier layers dominate ambient liquid dairy distribution across Germany and France. Tetra Pak and SIG Combibloc equipment lock-in sustains container demand in Nordic cooperative supply chains.
- Bottles:High-density polyethylene and polyethylene terephthalate structures serve ready-to-drink beverages where lightweight logistics offset F-Gas Regulation compliance costs for blow-molding equipment.
- Pouches:Flexible multilayer films with aluminum oxide barriers are gaining share in portion-controlled protein beverages.
- Trays:Thermoformed polypropylene structures serve prepared meal applications requiring rigid geometry.
Containers absorb the bulk of installed capacity; pouches are expanding most quickly.
Material:
Cost tier differentiation separates premium inert substrates from volume fiber-based systems competing on recycling economics.
- Paperboard:Liquid packaging board with extruded polymer barriers commands volume leadership in European ambient dairy. Recycled fiber supply chains anchored by DS Smith and Nordic pulp producers constrain mid-tier converter access.
- Plastic:Multi-layer polyethylene and polyethylene terephthalate structures face ECHA REACH pressure on fluorinated coatings. Southern European juice bottlers are accelerating substrate switching toward fiber alternatives.
- Glass:Borosilicate and soda-lime compositions retain pharmaceutical oral dosing and organic infant nutrition applications where inert material properties justify unit cost premiums.
- Metal:Aluminum and tinplate cans serve niche aseptic beverage segments requiring absolute light and oxygen barrier performance.
Paperboard captures the dominant share of new capital allocation; plastic faces the steepest regulatory compression.
End User:
Application-specific sterility requirements and validation protocols create distinct equipment specification clusters across user categories.
- Beverage Industry:High-speed aseptic filling lines for ambient juices and ready-to-drink formulations concentrate in southern German bottling corridors serving Central European export networks.
- Dairy Industry:Cold-chain-free distribution economics drive French and German processors toward shelf-stable yogurt drink cartonization.
- Food Industry:Prepared meals and sauces require tray-based aseptic systems with extended shelf-life specifications.
- Pharmaceutical Industry:EMA sterile manufacturing guidelines constrain material choices to glass and validated polymer systems for parenteral and oral dosing applications.
Beverage applications command the largest equipment installed base; dairy is climbing the fastest as ambient distribution expands.
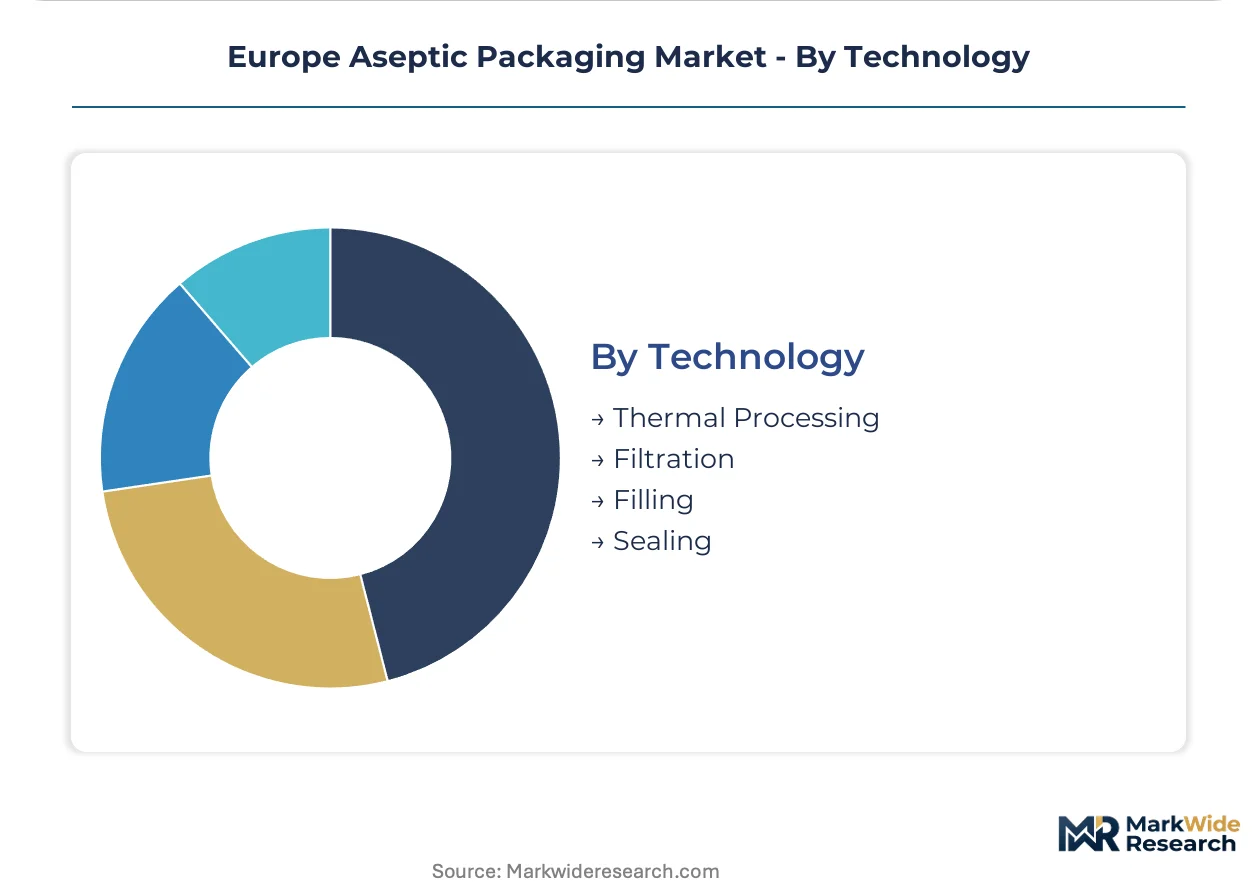
Technology:
Customer type segmentation separates pharmaceutical-grade validation requirements from beverage and dairy operational efficiency priorities.
- Thermal Processing:Ultra-high-temperature and high-temperature-short-time sterilization systems treat liquid products before aseptic filling. Dairy processors in France deploy UHT modules for ambient yogurt drink production.
- Filling:Hydrogen peroxide vapor and ultraviolet sterilization modules for packaging materials represent the critical integration point between substrate and product. Equipment vendors unbundle after-sales service contracts under pressure from German discount retail procurement consolidation.
- Filtration:Membrane and sterile filtration systems serve pharmaceutical applications requiring absolute bioburden reduction without thermal degradation.
- Sealing:Induction and conductive heat-sealing technologies complete package integrity for carton, pouch, and tray formats.
Filling technology absorbs the majority of engineering development resources; thermal processing maintains the steepest expansion trajectory in dairy applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern Germany's industrial corridor between Stuttgart and Munich concentrates beverage bottling capacity serving Central European export routes, with carton filling equipment clusters feeding distribution networks into Austria, Switzerland, and the Czech Republic.
Germany
Bavarian dairy cooperatives deploy ambient yogurt drink lines to eliminate cold-chain costs across rural distribution networks. The EU F-Gas Regulation forces blow-molding equipment upgrades at southern juice bottling facilities. Stuttgart-Munich corridor machinery vendors unbundle service contracts under pressure from discount retail procurement consolidation.
France
National dairy processors expand shelf-stable fermented beverage cartonization for North African export markets. ECHA REACH restrictions on PFAS barrier coatings accelerate fluorine-free polymer pilot programs at Normandy paperboard mills. Paris Basin technical centers coordinate reformulation testing with liquid packaging board suppliers.
Italy
Emilia-Romagna food processors adopt tray-based aseptic systems for prepared meal export lines. The EU Packaging and Packaging Waste Regulation's recyclability grades redirect investment toward mono-material structures at Bologna-area converting facilities. Northern Italian machinery builders specialize in hydrogen peroxide sterilization module integration.
Poland
Warsaw and Łódź dairy regions present underpenetrated demand for shelf-stable milk and plant-based beverage cartons. EU Green Deal waste reduction targets compress capital allocation timelines for fiber-based conversion at Mazovian processing plants. Central Polish bottling clusters serve Baltic state export corridors with ambient juice distribution.
Netherlands
Randstad logistics hubs coordinate recycled paperboard supply chains for liquid carton grades feeding Benelux and UK markets. EMA sterile manufacturing guidelines constrain pharmaceutical oral dosing applications to glass and validated polymer systems at Leiden biotech clusters. Rotterdam port infrastructure supports Nordic pulp import flows for DS Smith and competing board suppliers.
Europe Aseptic Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across equipment integration depth and barrier coating intellectual property. Integrated processing-packaging ecosystems sustain long-term customer lock-in among Nordic dairy cooperatives, while recycled fiber supply concentration creates input vulnerability for mid-tier converters. Three archetypes dominate: integrated system vendors with captive equipment ecosystems, fiber-based substrate specialists controlling pulp-to-board supply chains, and flexible machinery builders competing on format agility. Dominant competitive moves include unbundling after-sales service contracts from equipment supply agreements and accelerating fluorine-free barrier coating development ahead of ECHA enforcement.
Within the integrated system tier, Tetra Pak International S.A. and SIG Combibloc Group exemplify equipment lock-in strategies across European dairy and beverage cooperatives. DS Smith Plc anchors the fiber-based substrate specialist position through recycled paperboard supply chain control. Among diversified packaging conglomerates, Amcor Plc and Mondi PLC occupy positions spanning multiple aseptic material systems and geographic markets.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| Schott AG |
| DS Smith Plc |
| Amcor Plc |
| SIG Combibloc Group |
| Greatview Aseptic Packaging Europe GmbH |
| Mondi PLC |
| WestRock Company |
| Sealed Air Corporation |
| Others |
Supply & Pricing Matrix
Recycled paperboard feedstock costs cascade through liquid packaging board mills into three-tier pricing structures across premium, standard, and economy equipment tiers, with Nordic pulp supply concentration amplifying margin pressure at mid-tier European converters facing ECHA REACH compliance deadlines.
Pricing Analysis
Throughput-based pricing anchors equipment supply agreements, where filling speed and uptime guarantees command premium positioning against standard-tier machinery with bundled after-sales service. Price differentiation separates integrated processing-packaging ecosystems from standalone carton formers, with certification-grade pharmaceutical lines carrying the highest buyer insensitivity. Cost compression in standard-tier blow-molding equipment is intensifying because F-Gas Regulation retrofit requirements concentrate among southern European juice bottlers. Discount retail procurement functions in Germany exhibit the steepest price sensitivity, unbundling maintenance contracts to drive equipment-only negotiations.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Antwerp coordinate hub-and-spoke patterns for liquid packaging board flows feeding Benelux, UK, and Central European converting facilities. Geographic supply concentrates in Sweden, Finland, and Germany for virgin pulp, with recycled fiber processing anchored in the UK and Netherlands. Raw material dependencies span Nordic softwood pulp, extruded polyethylene barrier resins, and hydrogen peroxide sterilization chemicals. Single-source vulnerability sits with DS Smith and limited Nordic pulp suppliers controlling carton board grades. Distribution runs through Randstad logistics hubs with Rotterdam port infrastructure supporting Baltic state export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fiber-based substrate conversion as ECHA PFAS restrictions force barrier coating reformulation investments that weaker capitalized converters cannot absorb.
For Market Incumbents: Anticipate fluorine-free polymer coating shortages by securing pilot-scale partnerships with Normandy and German paperboard mills ahead of broader enforcement windows. Deepen backward integration into recycled fiber supply chains through long-term offtake agreements with Nordic pulp producers, reducing exposure to DS Smith supply concentration. Lock in sterile validation engineering capacity through captive training programs, as qualified technician scarcity constrains competitor expansion timelines. For New Entrants and Emerging Players: The gap between premium integrated ecosystems and economy-tier standalone equipment creates white-space positioning for modular hydrogen peroxide sterilization retrofit kits serving 1990s-era carton formers. Poland and Romania ambient dairy markets offer the most penetrable geography for first-mover carton filling deployments. Pursue digital printing convergence partnerships with mid-sized beverage brands seeking batch-level customization without integrated system lock-in. For Investors and Strategic Acquirers: ECHA's accelerated PFAS enforcement timeline is the leading indicator that barrier coating intellectual property will separate viable acquisition targets from stranded equipment portfolios. Target fiber-based substrate specialists with captive pulp supply relationships and fluorine-free coating pipelines over plastic-dependent machinery builders facing regulatory compression. Watch for sterilization module interoperability breakthroughs that reduce customer switching costs as the signal for ecosystem disruption risk.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Coating Development | ECHA REACH compliance secures carton board market access ahead of enforcement deadlines. |
| Recycled Fiber Supply Agreement | Long-term Nordic pulp offtake reduces input vulnerability for mid-tier converters. |
| Modular Sterilization Retrofit Launch | Hydrogen peroxide vapor modules extend legacy equipment life for budget-constrained processors. |
| Digital Printing Integration Partnership | Variable-data decoration enables batch customization without Tetra Pak ecosystem dependency. |
| Central European Equipment Deployment | Poland and Romania dairy bottling clusters capture first-mover ambient carton positioning. |
Research Methodology
Trade association filings, ECHA regulatory databases, and Nordic pulp producer sustainability reports formed the secondary backbone, cross-referenced against primary interviews with dairy processing engineers, beverage bottling plant managers, liquid packaging board procurement leads, and sterile equipment validation specialists. Bottom-up and top-down triangulation reconciled equipment shipment data with processor capacity announcements across Germany, France, and Poland.
Bottom-up modeling tracked installed base expansion and replacement cycles across carton forming, blow-molding, and pouch filling technologies, while top-down analysis validated aggregate demand through EU Green Deal packaging waste reduction targets and ambient dairy distribution economics. Segmentation dimensions spanned material substrate, filling technology, end-use application, and regional regulatory cluster. CAGRs were derived from equipment replacement timelines compressed by F-Gas Regulation and ECHA enforcement windows, with fiber carton conversion rates and pharmaceutical validation requirements as key forecast inputs.
Inputs from machinery vendor order backlogs and dairy cooperative capital expenditure disclosures were available through the study window; gaps in mid-tier converter financial transparency introduce uncertainty bands around market share estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market