
 Retort Packaging Market | 2026-2036
Retort Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Retort Packaging Market Intelligence
Market Context
Specialized polymer chemists and barrier-coating engineers is reorganizing competitive capability in retort packaging as formulations migrate from conventional multilayer films to recyclable alternatives. Amcor plc leverages its global manufacturing footprint to sustain supply continuity across diverse food processing corridors. ProAmpac differentiates through advanced pouch geometries and high-barrier substrate portfolios tailored to premium ready meal brands. Huhtamaki Oyj anchors European demand with specialized tray and lidding systems optimized for protein-based retort applications.
Technical Definition and Segment Structure
Retort packaging denotes hermetically sealed containers—typically pouches, trays, or laminated structures—engineered to withstand thermal sterilization at temperatures exceeding 121°C while preserving organoleptic properties and shelf stability for 12-36 months. The technology relies on coextruded or adhesive-laminated films incorporating aluminum oxide, ethylene vinyl alcohol, or polyamide barrier layers to prevent oxygen and moisture ingress. Pouches command the dominant position within product type segmentation due to material efficiency, consumer convenience, and compatibility with existing filling equipment; trays are gaining traction in ready meal and protein segments where rigidity and stackability matter. Composites and advanced plastics within the material dimension concentrate margin pools as metal and glass face displacement pressure from lightweighting mandates and sustainability targets.
Regulatory Frame and Outlook
The European Union's Packaging and Packaging Waste Regulation alongside REACH compliance requirements for adhesive constituents is reshaping formulation roadmaps and supplier qualification protocols. The FDA's food contact notification process and USDA's inspection standards for thermally processed foods govern market access in the United States, while China's GB standards and NMPA oversight frame import and domestic production requirements. Stakeholders must monitor evolving extended producer responsibility schemes and chemical migration thresholds as these will determine which barrier technologies achieve scalable commercialization.
Market Dynamics
Mono-material polypropylene structures are displacing aluminum-laminated films as the dominant sterilizable barrier technology, forcing retort packaging converters to requalify entire substrate portfolios across European and North American food processing corridors.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating investment in recyclable retort pouch lines across German and French converting facilities.
- Ready meal processors:Shelf-stable protein and grain bowls are expanding retort-compatible format requirements beyond traditional pouch geometries into shaped trays and bowls.
- Ethylene vinyl alcohol copolymer:High-barrier EVOH grades with enhanced thermal stability are enabling aluminum-free structures that maintain 24-month shelf life in ambient distribution.
Market Restraints
- Polypropylene resin concentration:Gulf Coast petrochemical complexes supply 40% of North American oriented polypropylene for retort applications, creating hurricane-exposed supply vulnerability.
- Adhesive qualification timelines:FDA food contact notification cycles for new laminating adhesives extend 18-24 months, freezing formulation innovation pipelines.
- Metal can substitution ceiling:Acidic tomato and fruit categories retain metal packaging preference due to sulfide staining risks with polymer-only structures.
Strategic Opportunities
- India organized retail expansion:Modern trade penetration in tier-2 cities is creating first-mover advantage for retort curry and dal pouches with 12-month ambient stability.
- Retortable paper-fiber composites:Barrier-coated molded fiber trays are converging with high-pressure processing to serve premium organic ready meal segments seeking plastic reduction.
- China dual carbon policy:Provincial energy intensity targets are incentivizing domestic converters to adopt solventless lamination and water-based printing for retort film production.
Industry Challenges
- Barrier coating technicians:Scarcity of specialists in atomic layer deposition and plasma-enhanced chemical vapor deposition is constraining pilot-to-scale transitions for ceramic-coated films.
- Legacy filling line retrofits:Integrating mono-material pouches into existing form-fill-seal equipment designed for multilayer structures requires mechanical modification and extended validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retort Packaging Market |
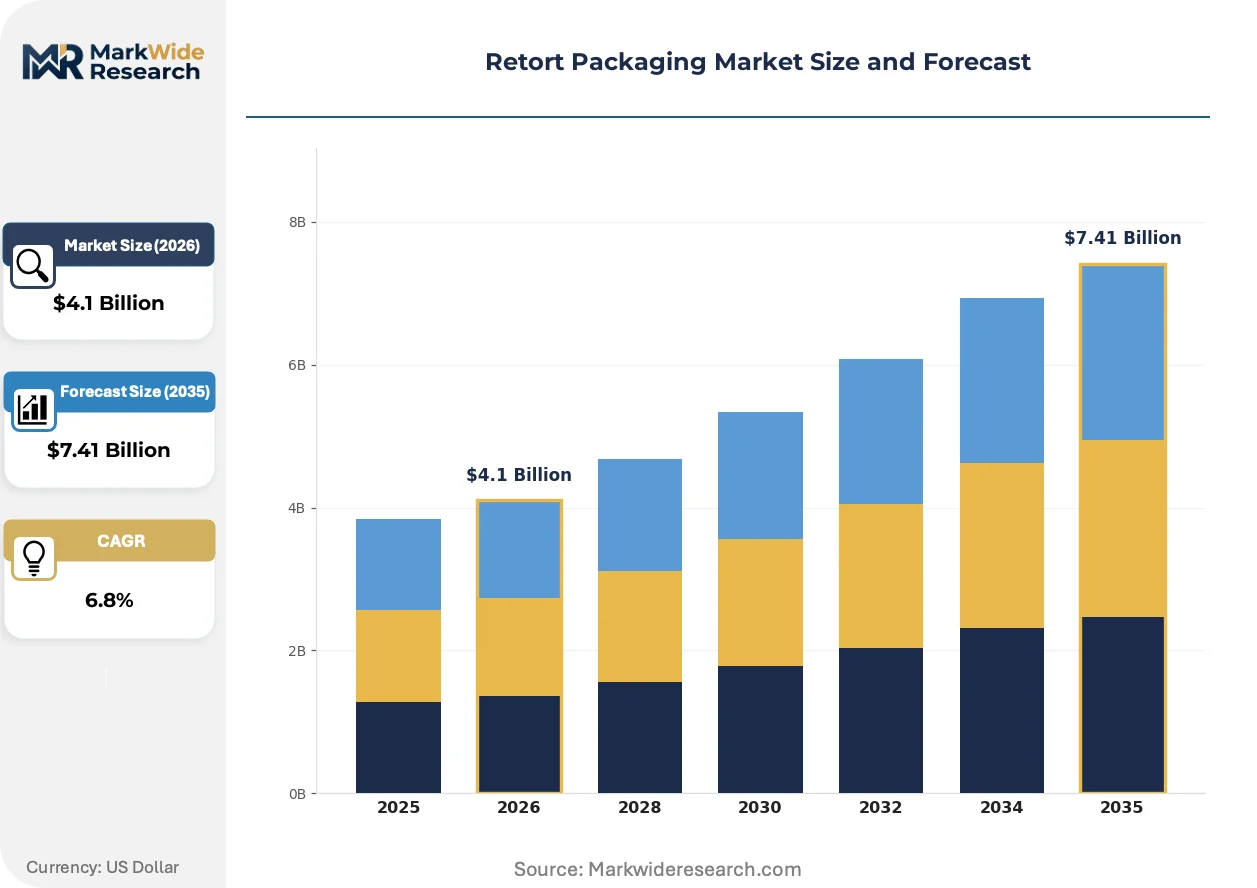
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouches, Trays, Cans, Bags Material: Metal, Plastic, Glass, Composites End User: Food Industry, Beverage Sector, Pharmaceuticals, Pet Food Application: Canned Foods, Ready Meals, Soups, Stews |
| Companies Covered | Mondi plc, ProAmpac, Amcor plc, Winpak Ltd, Huhtamaki Oyj, Sealed Air Corporation, Constantia Flexibles, Coveris Holdings SA, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retort Packaging Market Strategic Shifts & Innovations
Active barrier technologies and digital printing integration are restructuring how retort packaging converters differentiate beyond commodity substrate supply, shifting value capture toward functional performance and brand-customizable surfaces.
Transparent silicon oxide coatings deposited via plasma-enhanced chemical vapor deposition are replacing aluminum foil in premium retort applications requiring microwaveability and metal detection compatibility. Organic and natural food brands in the United States and Germany are adopting these structures for ready meal lines targeting clean-label positioning. The technology is bifurcating the retort barrier market between cost-optimized aluminum laminations for mass-market applications and premium ceramic-coated films for specialty segments commanding formulation premiums.
REACH compliance for adhesive constituents is compelling European converters to eliminate aromatic isocyanates and certain epoxy curing agents from retort lamination processes. Requalification costs for alternative polyurethane and acrylic adhesive systems are absorbing 15-20% of annual R&D budgets at mid-scale packaging firms. Italian and Spanish converters serving private-label ready meal brands are most affected, accelerating partnerships with adhesive suppliers holding pre-validated food contact dossiers.
Direct-to-retailer procurement contracts are compressing traditional distributor layers in North American retort pouch supply chains. National grocery chains and meal kit operators are establishing specifications offices that negotiate directly with film converters, bypassing regional packaging distributors. This pattern is most visible in the United States, where Kroger, Albertsons, and Target have consolidated pouch sourcing for private-label ready meal programs through single-source converter agreements.
Retort Packaging Market Segmentation
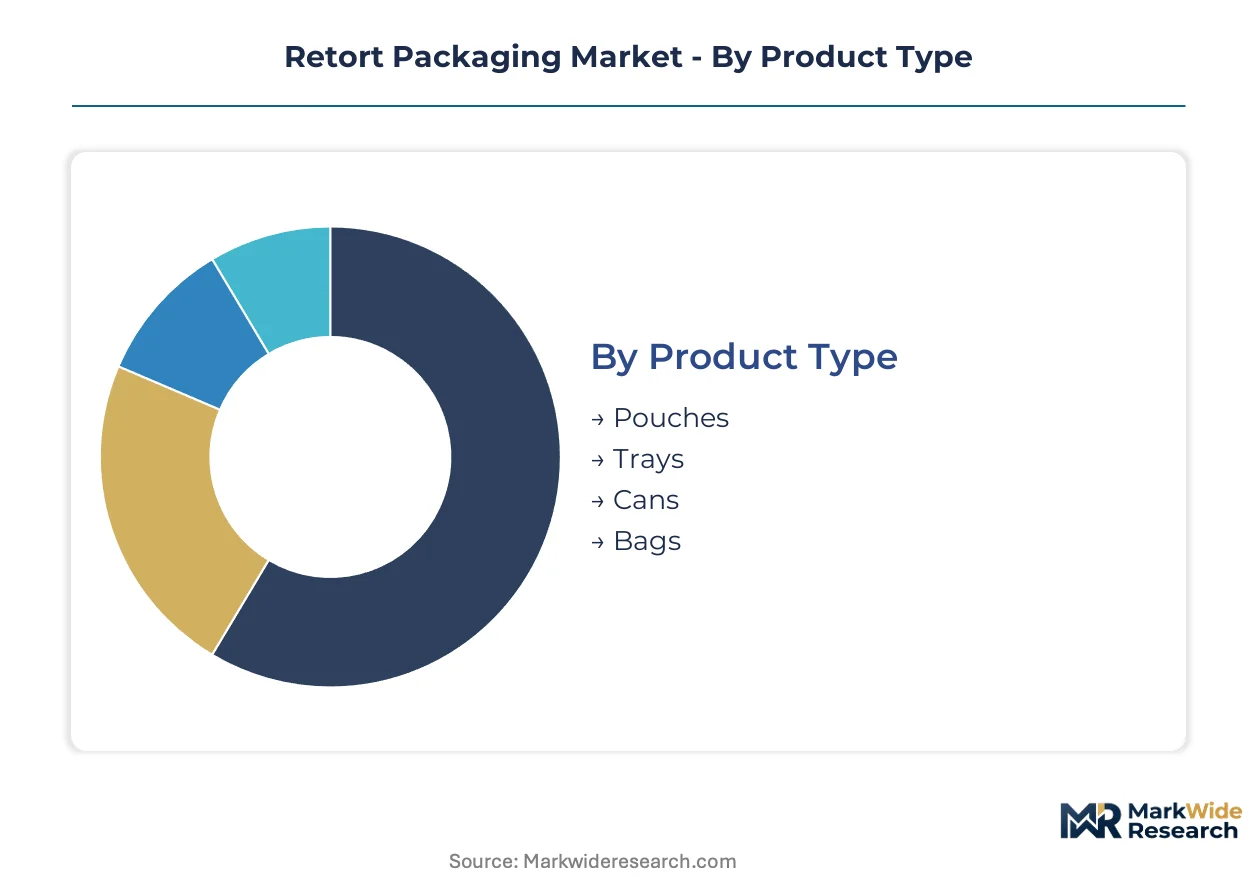
Retort packaging segmentation reveals how sterilization requirements, shelf-life demands, and retail channel specifications fragment procurement patterns across food processors and pharmaceutical manufacturers. Understanding these splits enables converters to align substrate portfolios with the technical and economic priorities of each downstream vertical.
Product Type:
Pouches flow through mass-market retail and foodservice channels, while trays concentrate in premium ready meal programs and institutional feeding contracts.
- Pouches:Flexible laminated structures of polyethylene terephthalate, aluminum oxide-coated films, or emerging mono-material polypropylene withstand 121°C sterilization cycles while minimizing material weight versus rigid alternatives. Demand concentrates in United States and German retail chains for shelf-stable curry, chili, and grain bowls where space efficiency and microwaveability drive procurement specifications.
- Trays:Rigid or semi-rigid polypropylene or polyethylene terephthalate structures with heat-sealed lidding films provide stackability and portion presentation for protein-centric ready meals. European and Japanese convenience store chains favor these formats for hot-case distribution of pasta, rice, and meat dishes requiring fork-stable platforms.
- Cans:Three-piece or two-piece metal cylinders with internal lacquer coatings retain dominance in acidic vegetable and fruit categories where sulfide staining risks exclude polymer-only structures.
- Bags:Gusseted or pillow-style flexible containers serve bulk institutional and military ration applications where cost minimization supersedes retail shelf presentation requirements.
Pouches dominate installed base. Trays are where expansion concentrates.
Material:
Cost tiers separate commodity metal and glass from engineered plastics and composites commanding formulation premiums in clean-label positioning.
- Metal:Tinplate and aluminum can bodies with epoxy-phenolic internal coatings provide absolute oxygen and light barrier performance for multi-year shelf stability in emergency rations and traditional vegetable preserves.
- Plastic:Coextruded or adhesive-laminated films incorporating ethylene vinyl alcohol, polyamide, or ceramic barrier layers enable lightweight, shatter-resistant alternatives to glass and metal with growing recyclability compliance in European markets.
- Glass:Borosilicate and soda-lime containers with lug or twist closures retain niche positions in premium baby food and organic segments where chemical inertness and consumer perception of purity justify weight and fragility penalties.
- Composites:Paper-fiber trays with barrier coatings or aluminum-plastic laminates bridge sustainability messaging with functional performance for organic ready meal brands seeking plastic reduction credentials.
Metal and glass anchor legacy volume. Plastic and composites are climbing the fastest.
End User:
Application maturity varies sharply: food and beverage procurement is saturated with qualified suppliers, while pharmaceutical and pet food segments present qualification-intensive growth corridors.
- Food Industry:Processors of canned vegetables, ready meals, and shelf-stable proteins specify retort structures validated for 12-36 month ambient stability across distribution chains spanning modern trade and traditional retail in India, China, and Brazil.
- Beverage Sector:Retortable cartons and pouches for coconut water, coffee drinks, and nutritional beverages concentrate in Southeast Asian and Latin American markets where refrigeration infrastructure remains limited.
- Pharmaceuticals:Sterilizable blister packs and vial systems for parenteral nutrition and emergency medical kits demand FDA and EMA compliance with extractables and leachables testing protocols that extend supplier qualification timelines.
- Pet Food:Wet food pouches and trays for premium dog and cat nutrition are expanding fastest in United States and United Kingdom markets where humanization trends elevate packaging quality specifications toward food-grade parity.
Food Industry commands current volume. Pet Food and Pharmaceuticals represent steepest expansion trajectory.
Application:
Customer type splits procurement: retail private-label programs prioritize shelf differentiation, while institutional buyers emphasize cube efficiency and case stacking.
- Canned Foods:Traditional vegetables, fruits, and fish products in metal or glass containers serve price-sensitive retail tiers and food bank distribution where absolute shelf stability trumps format innovation.
- Ready Meals:Complete protein-carbohydrate-vegetable combinations in pouches or trays target urban convenience seekers in Chinese and Indian metropolitan markets with limited home cooking time.
- Soups:Broth-based and cream-based formulations in stand-up pouches or gable-top cartons concentrate in North American and European retail where microwave-ready packaging drives repeat purchase.
- Stews:Chunky, high-viscosity preparations requiring robust seals and puncture resistance favor retort trays in Japanese convenience retail and European frozen-to-chilled transition segments.
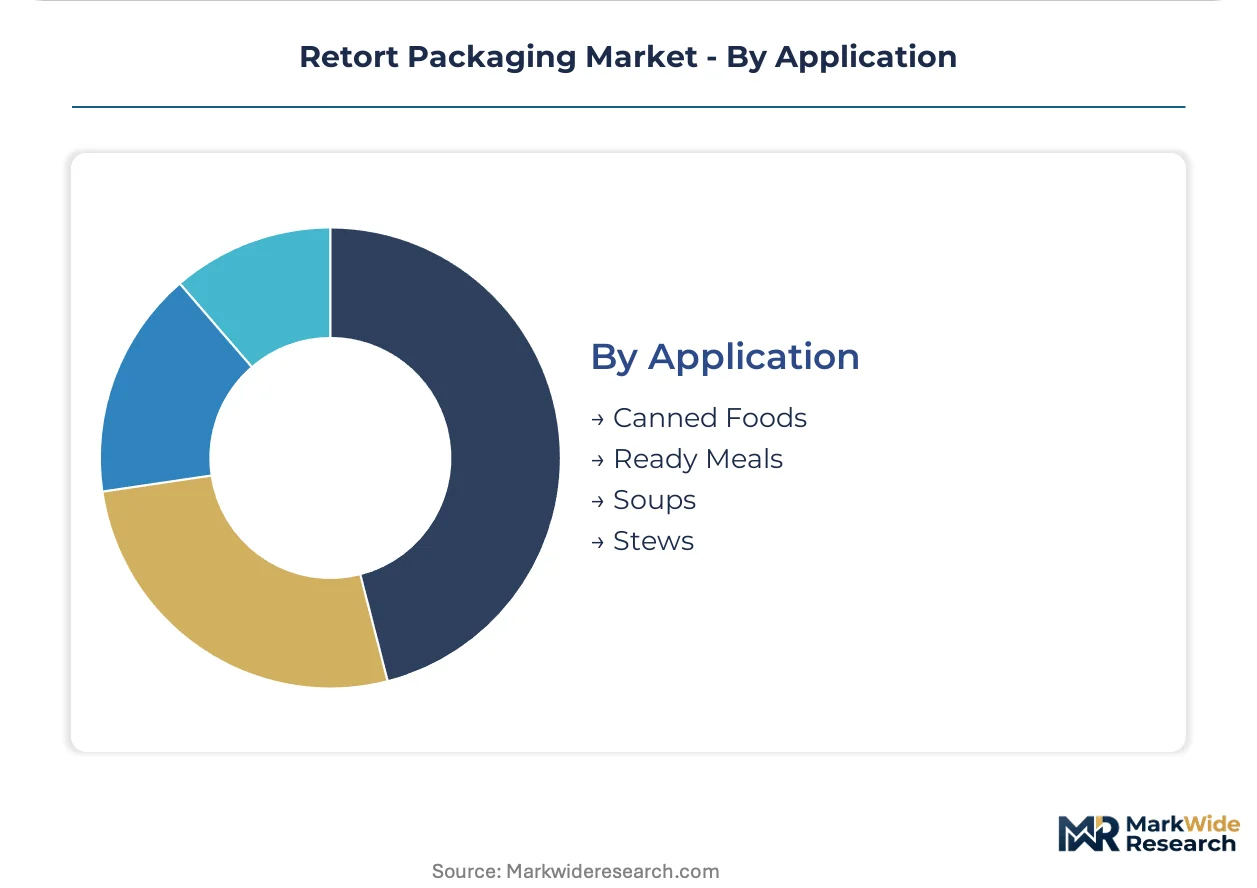
Canned Foods holds legacy position. Ready Meals is where growth concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food contact notification standards govern United States market access, while China's NMPA and dual carbon policy reshape converter investment priorities across Asian production corridors.
United States
Ready meal processors in Chicago and Sacramento corridors are expanding shelf-stable protein bowl portfolios. FDA food contact notification cycles for new laminating adhesives extend qualification timelines. Gulf Coast petrochemical complexes supply oriented polypropylene resin, exposing converters to hurricane-season supply disruptions.
China
Provincial energy intensity targets under the dual carbon policy incentivize solventless lamination adoption. NMPA oversight and GB standards frame import requirements for barrier film technologies. Yangtze River Delta converters in Shanghai and Jiangsu are retrofitting lines for mono-material polypropylene structures.
Germany
Extended producer responsibility mandates under the EU Packaging and Packaging Waste Regulation accelerate recyclable retort pouch investment. REACH compliance requirements for adhesive constituents force reformulation of lamination processes. Bavarian and North Rhine-Westphalian converting facilities serve private-label ready meal brands across European retail chains.
India
Modern trade penetration in tier-2 cities creates first-mover opportunity for retort curry and dal pouches. FSSAI standards govern food contact safety for imported and domestic packaging materials. Maharashtra and Gujarat processing corridors are qualifying aluminum-free barrier structures for 12-month ambient stability.
Japan
Convenience store chains in Tokyo and Osaka favor retort trays for hot-case distribution of pasta and meat dishes. METI industrial policy supports lightweighting mandates displacing metal and glass formats. Kansai-region converters specialize in shaped tray geometries for premium ready meal segments.
Retort Packaging Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding global manufacturing footprints and the specialist tier differentiating through substrate engineering and format innovation. The competitive landscape organizes around three archetypes: integrated multinational converters with multi-regional supply networks, regional specialists with deep customer relationships in single geographies, and technology-focused players advancing barrier coating capabilities. Dominant competitive moves include capacity expansion in mono-material retort lines and strategic partnerships between film converters and adhesive suppliers holding pre-validated food contact dossiers.
Among the integrated multinational tier, Amcor plc and Huhtamaki Oyj occupy positions exemplifying global supply continuity and regional specialization respectively. ProAmpac represents the technology-focused archetype, with its portfolio oriented toward advanced pouch geometries and high-barrier substrates. These three companies anchor the competitive structure, with Amcor plc leveraging scale across diverse food processing corridors, Huhtamaki Oyj concentrating European demand through tray and lidding specialization, and ProAmpac targeting premium ready meal brands with differentiated format capabilities.
| Leading Market Players |
|---|
| Mondi plc |
| ProAmpac |
| Amcor plc |
| Winpak Ltd |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Constantia Flexibles |
| Coveris Holdings SA |
| Sonoco Products Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between retort film converters and Gulf Coast petrochemical suppliers lock in oriented polypropylene resin access and price visibility across hurricane seasons, insulating North American converters from spot market volatility while binding them to minimum volume commitments.
Pricing Analysis
European converters command 15-25% premiums over Asian competitors due to REACH compliance costs and extended producer responsibility fees embedded in laminate pricing. Three-tier pricing structure across premium ceramic-coated films, standard aluminum-laminated structures, and economy-grade metal cans separates procurement tiers by barrier performance and recyclability credentials. Cost compression in standard pouch grades intensifies as Chinese capacity expansion floods export markets. Institutional buyers in military and emergency rations exhibit lowest price sensitivity due to multi-year shelf stability requirements, while private-label ready meal processors negotiate aggressively on per-unit film costs.
Supply Chain Analysis
Inventory cycles for ethylene vinyl alcohol copolymer and ceramic barrier coatings extend 8-12 weeks due to specialized polymerization schedules and plasma deposition batch constraints. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta converters feeding Asian food processors and Bavarian facilities serving European private-label brands. Raw material portfolios rest on polypropylene resin, aluminum oxide sputtering targets, and solventless adhesive systems. Single-source vulnerability permeates high-barrier EVOH grades dominated by Japanese and Korean chemical producers. Distribution runs through direct-to-retailer procurement contracts that displace traditional packaging distributors in North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort packaging sits in early-cycle expansion as mono-material polypropylene structures displace legacy aluminum laminations, with regulatory tailwinds from EU Packaging and Packaging Waste Regulation and China's dual carbon policy accelerating converter investment in recyclable barrier technologies.
For Market Incumbents: Consolidate adhesive supplier relationships to secure pre-validated food contact dossiers and compress FDA notification timelines from 24 months toward 12-month qualification cycles. Acquire atomic layer deposition specialists in Germany and Japan to internalize ceramic barrier coating capabilities before pilot-to-scale bottlenecks constrain premium film supply. Defend against emerging mono-material specialists by locking multi-year offtake agreements with Yangtze River Delta converters. For New Entrants and Emerging Players: Lead with aluminum-free barrier structures targeting tier-2 Indian cities where modern trade penetration creates first-mover advantage for 12-month ambient stability curry and dal pouches. Penetrate the United Kingdom pet food segment where humanization trends elevate packaging specifications toward food-grade parity with limited qualified supplier competition. Establish partnerships with solventless lamination equipment providers to bypass legacy adhesive qualification backlogs. For Investors and Strategic Acquirers: Regional specialists with captive EVOH compounding capabilities and validated European food contact dossiers represent the highest-conviction acquisition archetype as REACH compliance costs escalate. Long-term viability hinges on converter ability to transition aluminum-laminated installed base toward recyclable mono-material structures without sacrificing 24-month shelf life performance. Watch NMPA approval velocity for imported barrier films as inflection indicator for Chinese market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Solventless Lamination Adoption | Provincial energy intensity targets under China's dual carbon policy incentivize water-based printing and reduced VOC emissions. |
| Mono-Material Line Retrofit | German and French converters invest in polypropylene-only pouch capacity to meet EU Packaging and Packaging Waste Regulation recyclability mandates. |
| Ceramic Barrier Partnership | Plasma-enhanced chemical vapor deposition specialists in Japan enable aluminum-free structures with microwaveability and metal detection compatibility. |
| Direct-to-Retailer Contracting | Kroger and Target consolidate private-label ready meal pouch sourcing through single-source converter agreements bypassing distributors. |
| Adhesive Dossier Acquisition | REACH compliance pressures drive partnerships with polyurethane and acrylic adhesive suppliers holding pre-validated European food contact approvals. |
Research Approach
A standing panel of retort packaging plant managers, food processor procurement leads, adhesive R&D directors, and barrier coating equipment engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA food contact notification databases, EU ECHA REACH registration dossiers, Chinese NMPA import filings, and customs trade data for oriented polypropylene and EVOH resin flows. Bottom-up modeling of converter capacity and top-down triangulation against food processing output statistics anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, material composition, end-user industry, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating ready meal penetration rates and retail modern trade expansion trajectories. Forecast inputs incorporated adhesive qualification timeline distributions and mono-material line retrofit capex cycles.
Forecasts assume regulatory continuity in EU REACH, FDA food contact notification, and China NMPA regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Formulation Processing Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market