
 Aseptic Transfer System Market | 2026-2036
Aseptic Transfer System Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Transfer System Market Outlook
Direct-to-biopharma equipment procurement is fragmenting as large pharmaceutical manufacturers diversify supplier portfolios beyond traditional integrated vendors. Sartorius AG leverages its single-use technology platform to anchor European bioprocessing accounts with bundled transfer and filtration solutions. Thermo Fisher Scientific competes through its global service infrastructure, sustaining long-term instrument contracts across North American and Asian manufacturing sites. Merck KGaA differentiates via integrated material science capabilities, controlling polymer supply chains for disposable transfer assemblies.
An aseptic transfer system comprises enclosed mechanical or automated devices designed to move sterile materials, media, or finished products across classified environment boundaries without compromising microbiological integrity, typically employing HEPA-filtered airflow barriers and glove-port or rapid transfer port interfaces with leak-test verification down to 10⁻⁶ mbar·l/s. These systems serve primarily to eliminate human intervention in Grade A/B zones, reducing contamination risk during vial filling, lyophilization loading, and sterile API handling. Single-use transfer systems are capturing disproportionate growth momentum as biologics manufacturers prioritize elimination of cleaning validation burdens and cross-product contamination risks. Modular systems retain structural importance in facility retrofit applications where legacy isolator infrastructure demands incremental upgrades rather than greenfield replacement. Automated solutions concentrate margin pools through software-integrated traceability features that satisfy regulatory audit trail requirements.
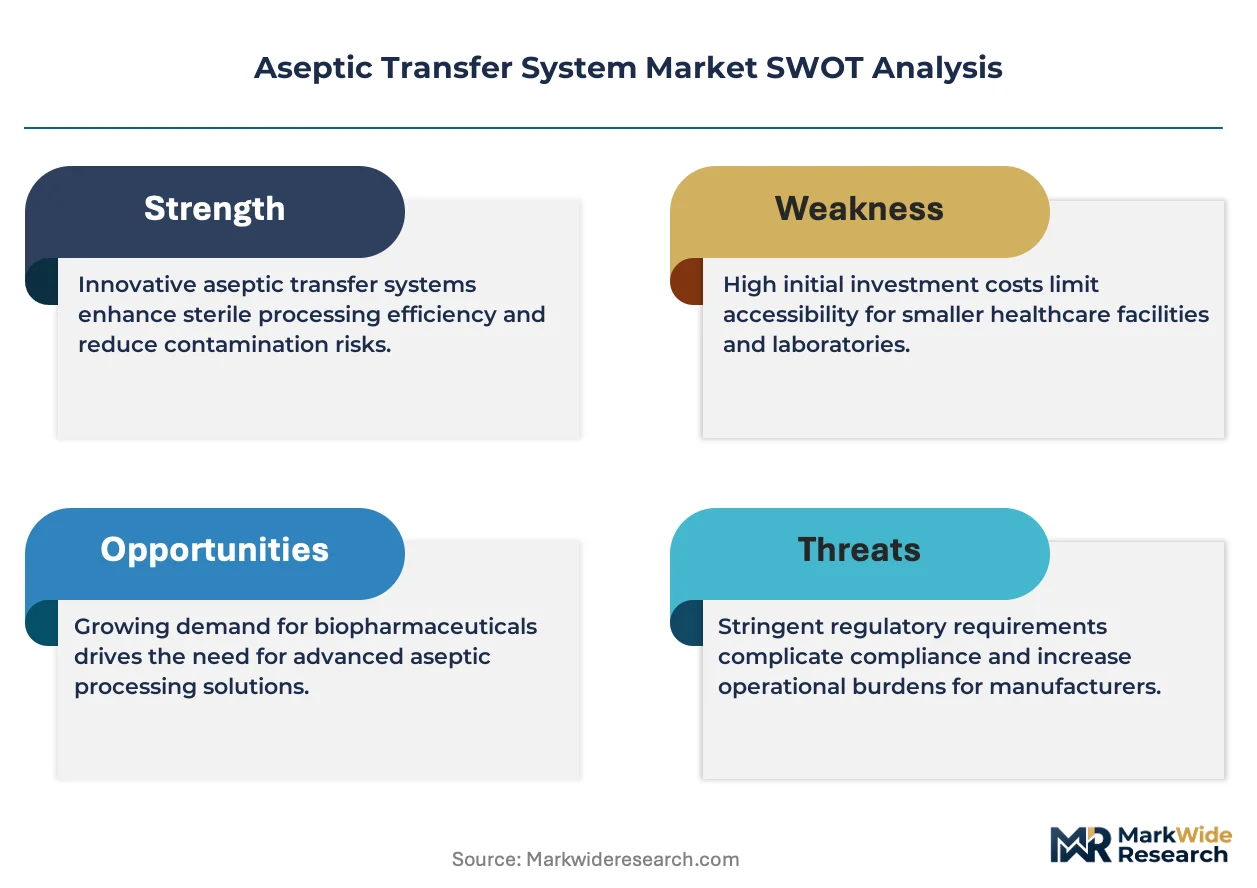
The FDA's guidance on sterile drug products produced by aseptic processing shapes equipment validation protocols and 21 CFR Part 11 electronic records compliance for automated transfer platforms. EMA's Annex 1 revision mandates continuous monitoring of barrier system integrity, directly accelerating replacement cycles for older manual transfer hatch designs across European manufacturing facilities. The EU AI Act introduces emerging compliance dimensions for machine-learning-enabled contamination detection systems integrated into next-generation transfer isolators. Stakeholders must weigh capital allocation between modular retrofit investments and fully automated greenfield installations as regulatory stringency diverges across inspection jurisdictions.
Market Dynamics
Closed-system transfer devices are displacing open-manifold designs as biologics manufacturers confront sterility assurance failures during high-potency API handling. Regulatory pressure from EMA's Annex 1 revision and FDA's updated aseptic processing guidance is compressing validation timelines for legacy equipment.
Growth Catalysts
- Annex 1 Revision:EMA's tightened barrier integrity requirements are forcing European facilities to replace manual transfer hatches with isolator-integrated solutions.
- Biologics Manufacturing:Monoclonal antibody and cell therapy production in Germany's Frankfurt-Munich corridor sustains continuous investment in single-use transfer assemblies.
- Contamination Detection:Machine-learning-enabled particle monitoring integrated into rapid transfer ports is accelerating adoption of automated verification protocols.
Market Restraints
- Specialized Polymer Supply:Medical-grade thermoplastic elastomer feedstock concentrates among three European resin suppliers, creating input cost volatility for disposable transfer assembly producers.
- Validation Burden:FDA's 21 CFR Part 11 compliance requirements for electronic batch records extend commissioning timelines for automated transfer platforms by 8-14 months.
- Skilled Technician Scarcity:Qualified isolator maintenance engineers remain concentrated in Switzerland and southern Germany, constraining facility expansion in peripheral European markets.
Strategic Opportunities
- Modular Retrofit Demand:Legacy fill-finish facilities in France and Italy require incremental isolator upgrades rather than greenfield replacement, favoring adaptable transfer interface designs.
- Cell Therapy Application:Autologous CAR-T manufacturing demands patient-specific batch isolation, creating white space for closed-system devices with rapid changeover capabilities.
- EU AI Act Alignment:Contamination detection algorithms embedded in next-generation transfer isolators qualify for streamlined conformity assessment under emerging AI system regulations.
Industry Challenges
- Commissioning Complexity:Integrated software-traceability features require simultaneous validation of hardware and electronic records systems, extending project timelines.
- Cross-Contamination Protocols:Multi-product biologics facilities demand rigorous cleaning validation for reusable transfer components, favoring single-use alternatives despite higher per-batch costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Transfer System Market |
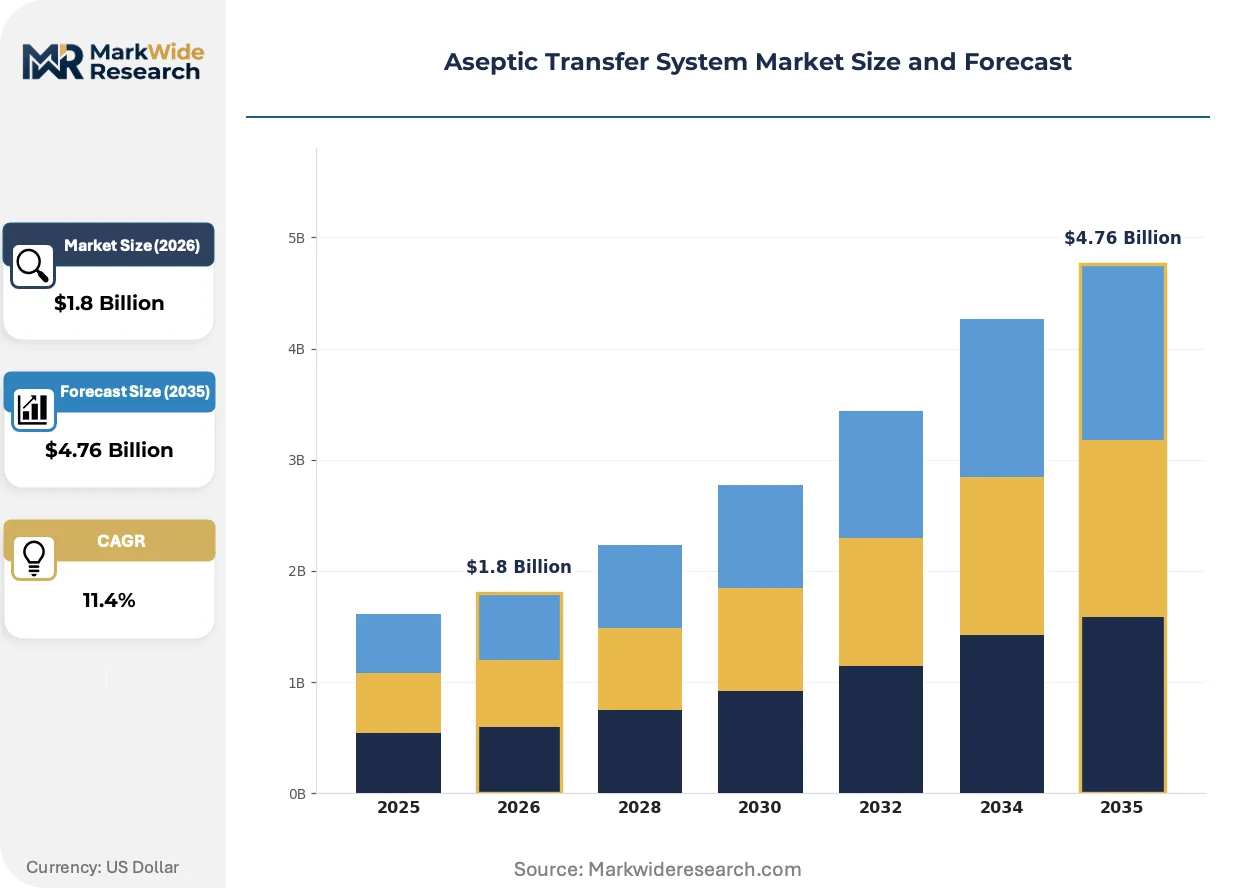
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Systems, Modular Systems, Sterilization Equipment, Transfer Hoses Application: Pharmaceutical Manufacturing, Biotechnology, Clinical Laboratories, Food Processing End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Research Institutions, Hospitals Technology: Mechanical Systems, Automated Solutions, Integrated Systems, Manual Handling |
| Companies Covered | Getinge AB, Sartorius AG, Aseptic Technologies, ABC Transfer SAS, STERIS plc, Flexifill Ltd., Central Research Laboratories, Merck KGaA, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Transfer System Market Strategic Shifts
Equipment architecture is fragmenting as biopharma procurement teams unbundle hardware, software, and service contracts previously sold as integrated packages. This disaggregation is reshaping vendor relationships and technical roadmaps.
Rapid transfer port technology is migrating from stainless steel mechanical seals to single-use polymer film interfaces. Gene therapy manufacturers in the Netherlands and Belgium are adopting these disposable barriers to eliminate cleaning validation for viral vector handling. The shift is compressing maintenance revenue pools for legacy isolator service providers while expanding consumables attach rates.
EMA's Annex 1 revision mandates continuous monitoring of barrier system integrity rather than periodic leak testing. This regulatory requirement is accelerating replacement cycles for manual glove-port designs across European manufacturing facilities. German and Swiss fill-finish sites are prioritizing automated pressure-decay verification systems to satisfy inspection readiness standards.
Buyer consolidation among contract development and manufacturing organizations is concentrating procurement leverage. Large CDMOs in Ireland and Denmark now negotiate enterprise-wide transfer system contracts with standardized validation protocols, displacing site-specific purchasing decisions. This concentration favors vendors with global service infrastructure capable of supporting multi-facility deployments.
Aseptic Transfer System Market Segmentation
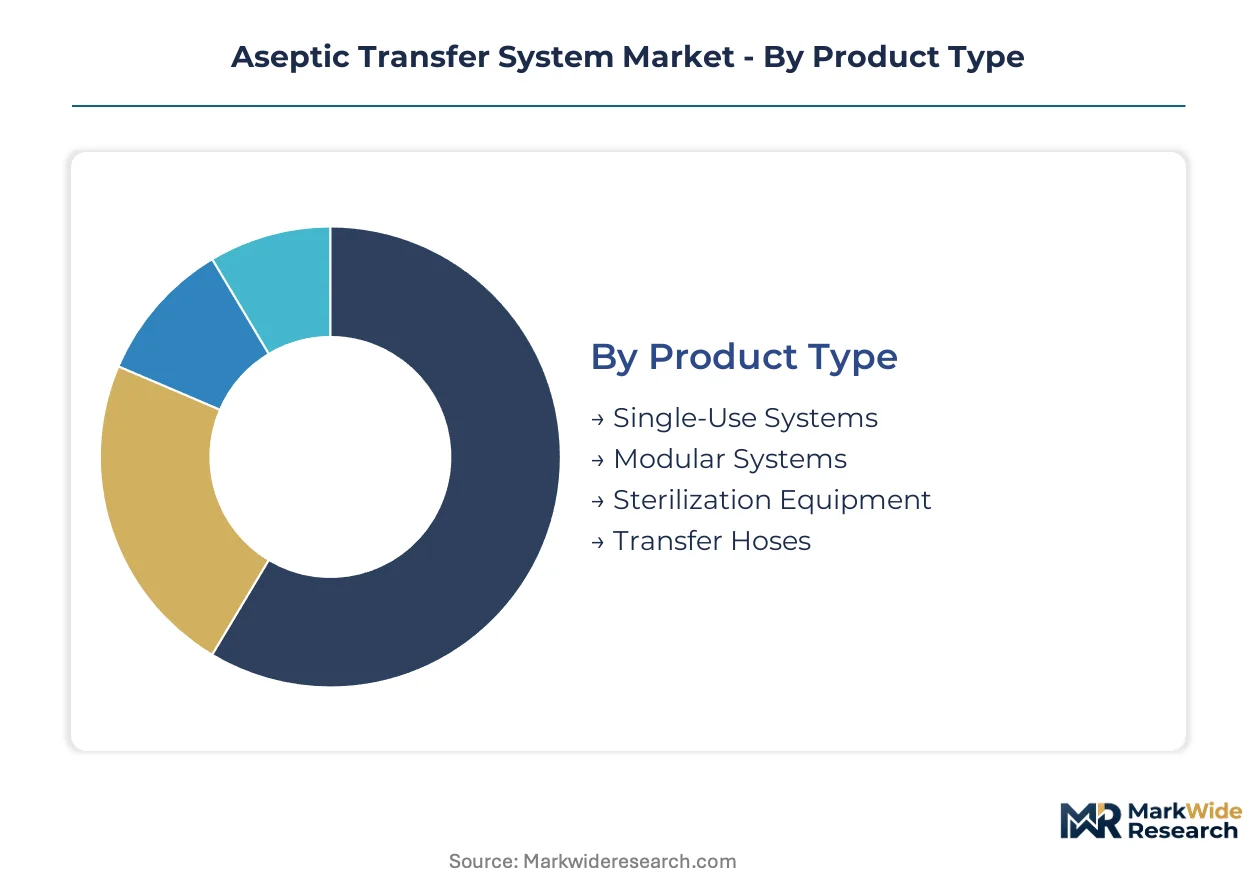
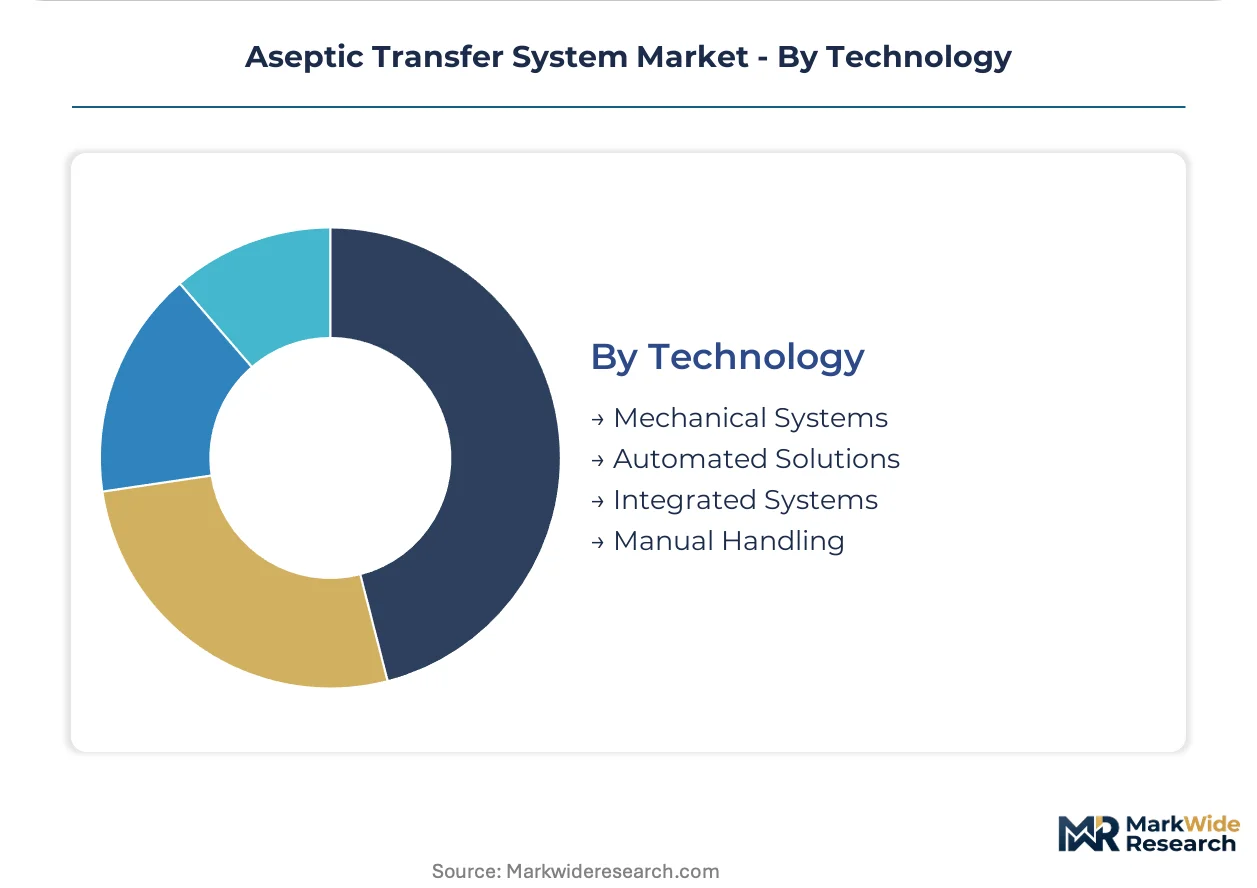
Aseptic transfer system procurement splits across four fundamental dimensions, each reflecting divergent technical requirements and compliance burdens. Product architecture choices determine cleaning validation obligations, while application context dictates barrier integrity specifications. End-user scale shapes capital deployment patterns, and technology selection governs regulatory audit trail complexity.
Product Type:
Mature stainless steel platforms coexist with emerging single-use alternatives, creating a bifurcated supply landscape where legacy infrastructure meets disposable innovation.
- Single-Use Systems:Pre-sterilized polymer film assemblies eliminate steam-in-place cycles and cross-product contamination risks. Biologics manufacturers in Germany's Frankfurt-Munich corridor deploy these for monoclonal antibody filling lines where batch-to-batch changeover speed governs facility economics.
- Modular Systems:Configurable isolator-integrated transfer interfaces enable incremental facility upgrades without greenfield construction. French and Italian fill-finish retrofit projects favor these adaptable designs where legacy infrastructure constraints block complete replacement.
- Sterilization Equipment:Autoclave-integrated transfer chambers with HEPA-filtered cooling zones.
- Transfer Hoses:Reinforced silicone or thermoplastic elastomer conduits for fluid and powder transfer.
Single-use systems handle the majority of new capacity throughput; modular systems are expanding most quickly in retrofit applications.
Application:
Cost tier differentiation separates high-value biologics processing from commodity pharmaceutical operations, with regulatory stringency scaling accordingly.
- Pharmaceutical Manufacturing:Sterile API handling and finished dose filling demand Grade A barrier isolation with continuous integrity monitoring. EMA's Annex 1 revision mandates automated pressure-decay verification for these applications across European facilities.
- Biotechnology:Cell therapy and gene vector production require patient-specific batch isolation with rapid decontamination protocols. Dutch and Belgian viral vector manufacturers adopt single-use film barriers to eliminate cleaning validation for multi-product suites.
- Clinical Laboratories:Diagnostic reagent compounding with lower throughput requirements.
- Food Processing:Aseptic packaging transfer with reduced microbiological surveillance intensity.
Pharmaceutical manufacturing commands the dominant revenue share; biotechnology is gaining share fastest on cell therapy capacity expansion.
End User:
Customer type concentration determines contract structure, with large integrated buyers extracting enterprise-wide pricing leverage unavailable to fragmented purchasers.
- Pharmaceutical Companies:Direct ownership of fill-finish assets with dedicated validation protocols and captive maintenance teams. Large German and Swiss manufacturers standardize on isolator-integrated rapid transfer ports with software-traceability features satisfying FDA 21 CFR Part 11 requirements.
- Contract Manufacturing Organizations:Multi-client facilities requiring rapid product changeover and standardized cleaning validation packages. Irish and Danish CDMOs negotiate consolidated procurement contracts with global service coverage obligations.
- Research Institutions:Academic and government laboratories with lower throughput and capital constraints.
- Hospitals:Compounding pharmacies handling patient-specific sterile preparations.
Pharmaceutical companies deploy the largest installed base; contract manufacturing organizations are climbing the fastest on biologics outsourcing trends.
Technology:
Volume concentration favors automated platforms in high-throughput biologics facilities, while manual systems retain niche presence in specialized low-batch operations.
- Mechanical Systems:Stainless steel rapid transfer ports with mechanical seal interfaces and periodic leak-test verification. Legacy installations across older European facilities face replacement pressure from EMA's continuous monitoring mandates.
- Automated Solutions:Software-integrated platforms with machine-learning-enabled particle detection and electronic batch record generation. These systems compress commissioning timelines through pre-validated software modules while extending project scope to include 21 CFR Part 11 compliance.
- Integrated Systems:Fully coupled isolator-and-transfer architectures with unified control systems.
- Manual Handling:Glove-port-based transfer with operator-dependent sterility assurance.
Mechanical systems retain the largest installed footprint; automated solutions are gaining share fastest on regulatory audit trail requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German bioprocessing clusters while Italian and Spanish facilities absorb margin compression from legacy infrastructure retrofit costs.
Germany
Frankfurt and Munich host Europe's densest monoclonal antibody production corridors, sustaining continuous investment in isolator-integrated rapid transfer ports. EMA's Annex 1 revision mandates automated pressure-decay verification systems, accelerating replacement cycles for manual glove-port designs. Bavarian fill-finish sites now prioritize machine-learning-enabled particle detection to satisfy inspection readiness standards.
United States
Massachusetts and North Carolina biologics corridors drive demand for single-use transfer assemblies eliminating steam-in-place validation burdens. FDA's 21 CFR Part 11 compliance requirements extend commissioning timelines for automated platforms by 8-14 months. Greater Boston CDMOs negotiate enterprise-wide contracts with standardized electronic batch record protocols.
Switzerland
Basel's pharmaceutical manufacturing density supports premium pricing for closed-system transfer devices with integrated software traceability. Swissmedic inspection protocols exceed EMA baseline requirements for barrier integrity documentation. Qualified isolator maintenance engineers concentrate here, constraining facility expansion in peripheral markets.
France
Paris-region fill-finish facilities face compressed validation timelines under EMA's tightened barrier integrity mandates. ANSM enforcement of continuous monitoring requirements is displacing older manual transfer hatch designs. Île-de-France biologics manufacturers prioritize modular retrofit solutions over greenfield construction.
Netherlands
Leiden and Oss gene therapy clusters adopt single-use polymer film barriers for viral vector handling. Dutch manufacturers eliminate cleaning validation burdens through disposable rapid transfer port interfaces. Belgian and Dutch facilities jointly represent the fastest-growing adoption region for contamination detection algorithms.
Aseptic Transfer System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in polymer film and seal engineering. The vendor base separates into three functional strata: diversified life science conglomerates bundling transfer systems with adjacent bioprocessing equipment; mid-scale isolator fabricators competing on retrofit adaptability; and consumables-focused suppliers capturing recurring revenue from single-use assemblies. Consolidation pressure concentrates among European isolator specialists seeking geographic coverage expansion. Technology licensing agreements between seal engineering firms and software developers are proliferating as automated verification becomes table stakes.
Among diversified European life science groups, Sartorius AG and Merck KGaA occupy positions anchoring the integrated platform tier. Sartorius leverages single-use technology bundling to secure bioprocessing accounts, while Merck KGaA's material science capabilities control polymer supply chains for disposable assemblies. Thermo Fisher Scientific represents the global service infrastructure archetype, sustaining long-term instrument contracts through multi-site coverage obligations. Getinge AB and STERIS plc exemplify the sterilization and isolation equipment specialists competing on validation protocol standardization.
| Leading Market Players |
|---|
| Getinge AB |
| Sartorius AG |
| Aseptic Technologies |
| ABC Transfer SAS |
| STERIS plc |
| Flexifill Ltd. |
| Central Research Laboratories |
| Merck KGaA |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on European medical-grade thermoplastic elastomer suppliers determines both the spread between configured-to-order and standard transfer assemblies and the geographic clustering of disposable component manufacturing. EMA's Annex 1 revision on continuous barrier integrity monitoring feeds back into procurement decisions, compressing margins for manual hatch producers while expanding premium capture for automated verification platforms.
Pricing Analysis
The customization-premium spread separates standard single-use assemblies from isolator-integrated rapid transfer ports with machine-learning-enabled particle detection. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA 21 CFR Part 11-compliant automated platforms commanding substantial premiums over modular retrofit solutions. Cost compression in standard mechanical systems is intensifying because buyer consolidation among Irish and Danish CDMOs extracts volume discounts. Contract manufacturing organizations exhibit highest price sensitivity due to multi-client margin pressure, while Swiss and German pharmaceutical companies prioritize compliance assurance over procurement savings.
Supply Chain Analysis
Upstream feedstock for disposable transfer assemblies draws from Germany, Switzerland, and the Netherlands, where three European resin suppliers control medical-grade thermoplastic elastomer production. Component dependencies span HEPA filtration media, precision-machined stainless steel seals, and polymer film barriers with validated sterility assurance levels. Single-source vulnerability concentrates in specialized elastomer feedstock, constraining capacity expansion for single-use assembly producers. Distribution runs through direct equipment procurement channels for large pharmaceutical accounts and distributor-mediated sales for mid-scale retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aseptic transfer system market sits at a platform-economics inflection where software-integrated traceability becomes the interoperability standard, with EMA's continuous monitoring mandate accelerating ecosystem consolidation around automated verification protocols.
For Market Incumbents: Insulate core bioprocessing accounts through captive polymer supply agreements and pre-validated software modules that compress customer commissioning timelines. Threat from modular retrofit specialists demands backward integration into seal engineering capabilities to preserve margin pools. Priority lever rests on multi-site service infrastructure investments that satisfy CDMO enterprise-wide contract requirements. For New Entrants and Emerging Players: Build out contamination detection algorithm development for EU AI Act conformity assessment pathways, targeting Dutch and Belgian gene therapy clusters with disposable film barrier solutions. Patient-specific cell therapy manufacturing represents the most penetrable white space, with rapid changeover capabilities as the differentiated go-to-market angle. Channel partnerships with established isolator fabricators offer faster validation than direct hardware competition. For Investors and Strategic Acquirers: EMA's Annex 1 revision reshapes the acquisition landscape toward automated verification platform providers with embedded software traceability. Long-term viability favors targets with demonstrated 21 CFR Part 11 compliance and recurring consumables revenue streams. Signal to watch is CDMO procurement standardization momentum, indicating consolidation leverage for platform vendors with global service coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Integrated Traceability Platform | EMA's continuous monitoring mandate elevates automated verification to table stakes for European fill-finish facilities. |
| Single-Use Polymer Film Barrier Expansion | Dutch and Belgian viral vector manufacturers eliminate cleaning validation through disposable rapid transfer port adoption. |
| Multi-Site Service Infrastructure Buildout | Irish and Danish CDMO enterprise contracts require global coverage obligations that favor scaled platform vendors. |
| EU AI Act Conformity Assessment Pathway | Machine-learning-enabled contamination detection algorithms qualify for streamlined regulatory approval under emerging AI system frameworks. |
| Modular Retrofit Interface Development | French and Italian legacy fill-finish facilities demand incremental isolator upgrades without greenfield construction disruption. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, EMA Annex 1 revision drafts, and isolator equipment validation protocols. Primary interviews engaged fill-finish engineering directors, regulatory affairs specialists at biologics manufacturers, CDMO procurement leads, and isolator maintenance technicians. Secondary sources included SEC filings from diversified life science conglomerates, Swissmedic inspection guidance, and hospital pharmacy compounding standards. Bottom-up capacity modeling triangulated against top-down expenditure estimates from pharmaceutical capital investment disclosures.
Forecast inputs span product architecture evolution, regulatory compliance burden trajectories, and biologics manufacturing capacity expansion across the analysis window. Segmentation dimensions modeled include transfer system type, application context, end-user scale, and technology sophistication tier. CAGRs were derived from installed base replacement cycles and new capacity absorption rates, with specific weighting for cell therapy manufacturing growth and Annex 1-driven equipment refresh demand.
Stress conditions across resin supply disruption, regulatory inspection intensity variation, and CDMO consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on barrier integrity technology adoption curves and single-use displacement rates for stainless steel platforms. Cross-checking against EMA inspection deficiency data and FDA warning letter trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Retort Machine Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
Aseptic Fillers Market
Aseptic & Retort Packaging
Asia-Pacific Retort Packaging Market
Aseptic & Retort Packaging
Plastic Retort Cans Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Aseptic IBC Market
Aseptic & Retort Packaging
Middle East and Africa Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
Retort Cartons Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market