
 Saudi Arabia Construction Market | 2026-2036
Saudi Arabia Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Construction Market Outlook
Government infrastructure agencies is bifurcating demand away from private residential developers as Saudi Vision 2030 megaprojects reshape procurement priorities. Saudi Binladin Group leverages its vertical integration across civil works and project management to sustain dominance on giga-project sites. Nesma & Partners Contracting anchors its position through marine and industrial specialization in the Eastern Province. El Seif Engineering Contracting differentiates via technology-intensive delivery methods on complex developments.
Construction encompasses the physical assembly of buildings, infrastructure, and industrial facilities using engineered materials such as reinforced concrete with compressive strengths of 30-60 MPa, structural steel grades S275 and S355, and composite systems designed for seismic and thermal performance. Its primary purpose is creating durable, code-compliant built assets that support economic activity and population settlement. Residential construction commands the largest volume share among application segments, though infrastructure projects generate superior margin pools due to complexity premiums and longer contract tenors. Green construction technology is expanding fastest as the Saudi Energy Efficiency Center mandates and LEED-equivalent certifications become standard on public tenders.
The Saudi Building Code and National Housing Company standards govern material quality and safety protocols, while the Saudi Standards, Metrology and Quality Organization enforces product conformity assessments for imported construction inputs. SFDA oversight extends to construction chemicals and admixtures, creating additional compliance layers for specialty material suppliers. Contractors and material vendors must monitor evolving procurement rules under Vision 2030 delivery vehicles, as project-specific technical specifications increasingly override generic national standards.
Market Dynamics
Government infrastructure agencies are displacing private residential developers as the dominant procurement channel across Saudi Arabia's construction landscape. Vision 2030 megaprojects concentrate capital deployment in Riyadh's corridor while tightening material specifications through the Saudi Building Code reshape contractor qualification thresholds.
Growth Catalysts
- NEOM and Qiddiya megaprojects:These giga-developments anchor contractor order books and sustain multi-year civil works demand across transportation, energy, and urban infrastructure verticals.
- Saudi Building Code enforcement:Tightening material specifications and energy-efficiency thresholds mandate upgraded concrete grades and seismic-resistant structural systems on public tenders.
- Red Sea Project tourism infrastructure:Marine and hospitality construction requirements expand specialized contractor capabilities in coastal and resort development segments.
Market Restraints
- Structural steel input volatility:S275 and S355 grade steel prices fluctuate with international scrap and billet markets, compressing fixed-price contract margins.
- Imported construction chemical concentration:SFDA-regulated admixtures and sealants rely heavily on external supply chains, creating customs clearance bottlenecks.
- Skilled project management scarcity:Complex giga-project delivery demands exceed domestic supply of certified engineers and construction managers.
Strategic Opportunities
- Eastern Province industrial expansion:Petrochemical and downstream manufacturing construction in Jubail and Ras Al-Khair offers specialized marine and heavy industrial contract pools.
- Green construction certification mandates:Saudi Energy Efficiency Center requirements and LEED-equivalent standards create premium positioning for low-carbon material suppliers.
- Modular and prefabrication convergence:Offsite manufacturing integrated with digital twin modeling compresses project timelines for repetitive housing and hospitality typologies.
Industry Challenges
- BIM and digital workflow integration:Legacy contractor operations struggle with Saudi Building Code mandated digital submission requirements and clash detection protocols.
- Specialized welding and marine certification timelines:SFDA and SASO conformity assessments for construction chemicals delay material mobilization on fast-track megaproject sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Construction Market |
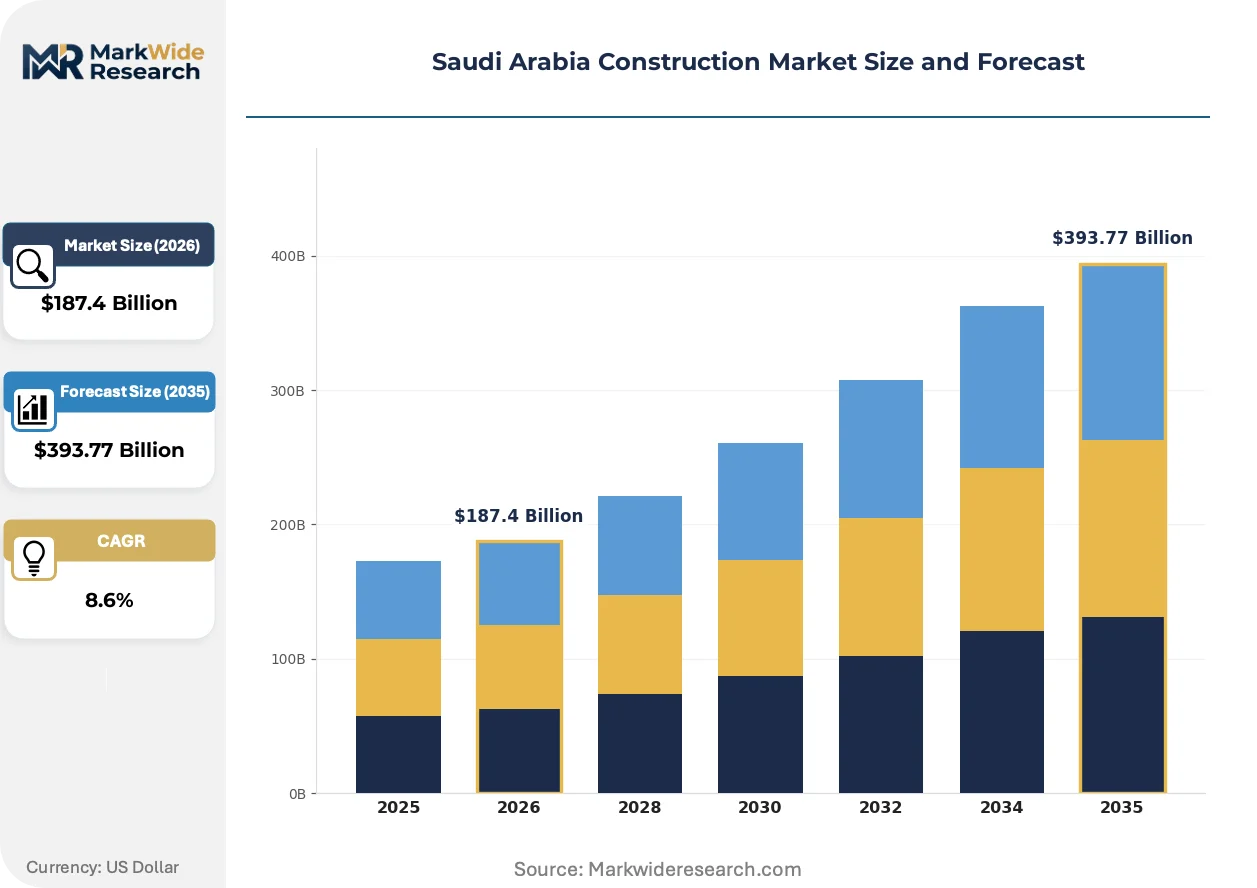
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $393.77 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Materials, Heavy Equipment, Prefabricated Structures, Construction Chemicals End User: Residential Developers, Commercial Builders, Infrastructure Agencies, Industrial Corporations Technology: Building Information Modeling, Green Construction, Modular Techniques, Smart Materials Application: Infrastructure Projects, Residential Construction, Commercial Development, Industrial Facilities |
| Companies Covered | Saudi Binladin Group, Nesma & Partners Contracting, Almabani General Contractors, El Seif Engineering Contracting, Al-Rashid Trading & Contracting, AlKifah Contracting, Al Ayuni, Al Bawani, Bechtel Saudi Arabia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Construction Market Strategic Shifts
Digital delivery methods and sustainable material specifications are actively reshaping how Saudi contractors bid, source, and execute projects. Three converging developments are compressing traditional workflows while elevating technical performance thresholds.
Building Information Modeling (BIM) integrated with generative design algorithms is bifurcating project planning workflows. Tier-one contractors on NEOM and Qiddiya sites deploy parametric modeling for clash detection and quantity takeoff, while mid-tier residential builders remain dependent on 2D documentation. This capability gap is compressing subcontractor pools as megaproject procurement prequalification mandates Level 2 BIM compliance.
The Saudi Building Code 2018 amendments and National Housing Company technical specifications now enforce thermal performance testing and seismic load calculations on all public housing tenders. Contractors must submit material test reports from SASO-accredited laboratories before mobilization. Residential developers in Riyadh and Jeddah are responding by pre-certifying concrete mix designs and window assembly U-values to accelerate approval timelines.
Consolidated procurement through Vision 2030 delivery vehicles is replacing fragmented developer-led sourcing. Single-source contracting for design-build and EPC packages concentrates volume with prequalified national contractors. This channel compression is most visible in Riyadh's megaproject corridor, where Diriyah Gate and King Salman Park development authorities bundle civil, MEP, and finishes scopes into multi-billion-riyal packages.
Saudi Arabia Construction Market Segmentation
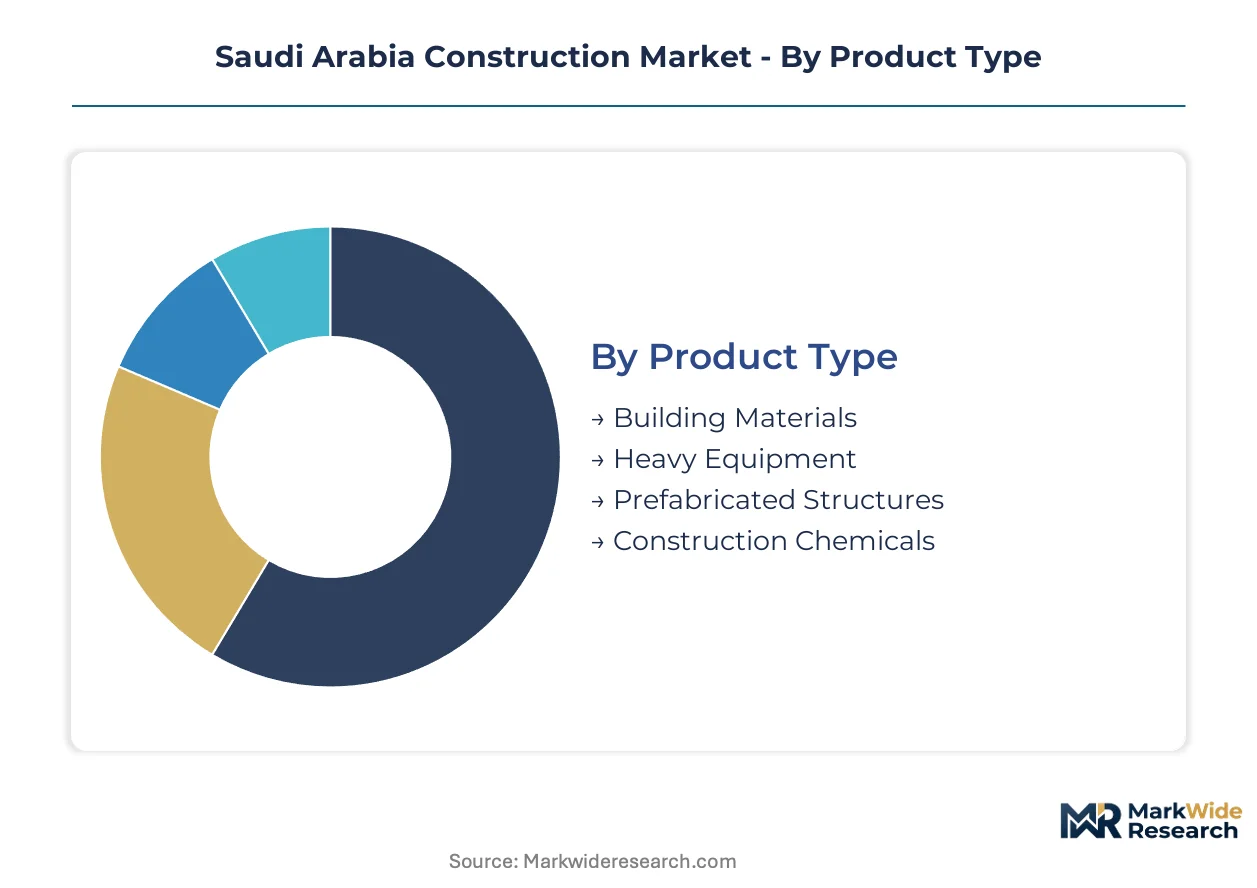
Construction procurement in Saudi Arabia channels through distinct product, user, and technology categories that reflect Vision 2030's infrastructure pivot. Understanding segment boundaries clarifies where contractor capabilities must align with Saudi Building Code mandates and giga-project technical specifications.
Product Type:
Domestic production anchors building materials and heavy equipment supply, while prefabricated structures and construction chemicals rely substantially on import flows subject to SASO conformity assessments.
- Building Materials:Reinforced concrete with 30-60 MPa compressive strength and structural steel grades S275 and S355 dominate volume procurement. Riyadh's megaproject corridor concentrates demand as NEOM and Qiddiya developers mandate upgraded seismic-resistant specifications under Saudi Building Code enforcement.
- Heavy Equipment:Earthmoving machinery, cranes, and concrete batching plants with Tier 4 emissions compliance face procurement bottlenecks. Fleet availability constraints on giga-project sites force contractors into long-term lease arrangements with equipment lessors.
- Prefabricated Structures:Offsite-manufactured wall panels and modular bathroom pods compress on-site labor requirements. SFDA-regulated adhesives and sealants in panel systems create customs clearance dependencies for European and Asian suppliers.
- Construction Chemicals:Admixtures, waterproofing membranes, and repair mortars governed by Saudi Standards, Metrology and Quality Organization import rules. Eastern Province petrochemical construction generates specialized demand for corrosion-resistant coating systems.
Building materials holds the largest share; momentum sits with prefabricated structures as modular delivery compresses giga-project timelines.
End User:
Procurement authority has shifted decisively toward public entities, with private developers receding to secondary volume positions in the current project pipeline.
- Residential Developers:Private apartment and villa builders face tightened National Housing Company technical specifications on thermal performance and window assembly U-values. Jeddah and Riyadh developers pre-certify concrete mix designs to accelerate approval timelines.
- Commercial Builders:Office, retail, and hospitality contractors compete for bundled design-build packages in King Salman Park and Diriyah Gate developments. LEED-equivalent certification requirements elevate material sourcing costs.
- Infrastructure Agencies:Public authorities for transportation, energy, and water projects displace private developers as the dominant procurement channel. Multi-billion-riyal EPC contracts concentrate with prequalified national contractors possessing civil works and project management scale.
- Industrial Corporations:Petrochemical and downstream manufacturing operators in Jubail and Ras Al-Khair drive marine and heavy industrial construction demand. Specialized welding certifications and SASO material assessments extend mobilization lead times.
Infrastructure agencies command the dominant procurement volume; industrial corporations generate the steepest expansion trajectory as Eastern Province manufacturing capacity expands.
Technology:
Adoption bifurcates between tier-one contractors deploying advanced digital workflows and mid-tier builders reliant on conventional documentation methods.
- Building Information Modeling:Parametric modeling for clash detection and quantity takeoff separates prequalified megaproject bidders from excluded competitors. Level 2 BIM compliance is now mandatory for NEOM and Qiddiya procurement prequalification.
- Green Construction:Low-carbon material specifications and energy-efficient envelope designs respond to Saudi Energy Efficiency Center mandates. Public tenders increasingly require LEED-equivalent certification as a technical minimum.
- Modular Techniques:Offsite manufacturing integrated with digital twin modeling reduces on-site labor dependencies. Repetitive housing and hospitality typologies in Red Sea Project developments favor this delivery method.
- Smart Materials:Self-healing concrete and phase-change thermal storage systems remain nascent in contractor specifications. Early deployment concentrates in demonstration projects within Riyadh's sustainable building pilot programs.
Building Information Modeling holds the largest technology investment; green construction is climbing the fastest as regulatory mandates harden.
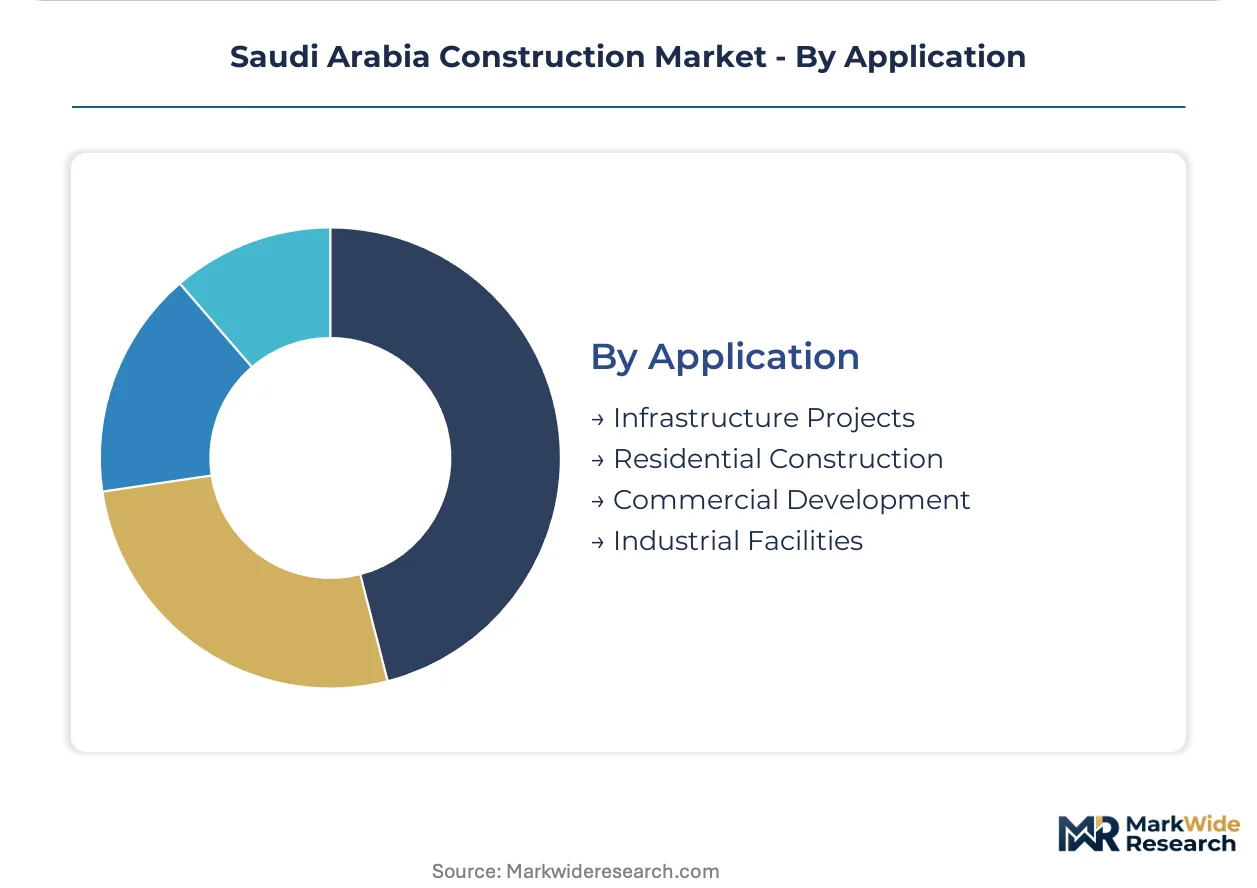
Application:
Project type determines margin structure, with infrastructure and industrial applications commanding complexity premiums over standardized residential delivery.
- Infrastructure Projects:Transportation, energy, and water systems construction generates superior margin pools through longer contract tenors and technical specialization requirements. Riyadh's megaproject corridor anchors multi-year civil works demand.
- Residential Construction:Volume leadership persists in unit counts though margin compression intensifies under National Housing Company cost controls. Pre-certified material packages accelerate approval workflows for repetitive typologies.
- Commercial Development:Mixed-use and hospitality projects in Red Sea Project and Qiddiya sites demand marine and resort construction capabilities. Bundled procurement packages concentrate scope with design-build specialists.
- Industrial Facilities:Petrochemical, refining, and downstream manufacturing construction in Jubail and Ras Al-Khair requires heavy industrial and marine engineering expertise. SFDA-regulated construction chemicals face extended conformity assessment timelines.
Residential construction retains volume leadership; industrial facilities are gaining share fastest on Eastern Province capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE construction materials flow northward into Saudi Arabia's megaproject corridor, while Indian and Chinese steel shipments arrive via Jeddah Islamic Port to supply Vision 2030 developments. This trade architecture concentrates procurement leverage in Riyadh's government infrastructure agencies.
Riyadh
Diriyah Gate and King Salman Park developments drive civil works demand across transportation and urban infrastructure verticals. The Saudi Building Code mandates seismic-resistant structural systems and thermal performance testing for all public tenders. Contractor order books concentrate here as NEOM and Qiddiya procurement authorities bundle multi-billion-riyal design-build packages.
Eastern Province
Petrochemical and downstream manufacturing construction in Jubail and Ras Al-Khair generates specialized marine and heavy industrial contract pools. SFDA-regulated construction chemicals face extended conformity assessment timelines for corrosion-resistant coating systems. Nesma & Partners Contracting anchors regional capabilities through marine engineering specialization.
Western Region
Red Sea Project tourism infrastructure expands marine and hospitality construction requirements across coastal development segments. LEED-equivalent certification standards elevate material sourcing costs for resort developers. Jeddah Islamic Port serves as the primary customs clearance node for imported prefabricated structures and European construction chemicals.
NEOM Northwest
The linear city development sustains multi-year demand for modular construction techniques and digital twin-integrated delivery methods. Level 2 BIM compliance is mandatory for procurement prequalification on giga-project sites. Offsite manufacturing of wall panels and modular bathroom pods compresses on-site labor requirements in this remote location.
Saudi Arabia Construction Market Competitive Environment
Player mix skews toward vertically integrated national champions with civil works and project management scale. Market structure concentrates procurement authority with prequalified contractors possessing giga-project delivery experience. Strategic archetypes include diversified conglomerates spanning multiple construction verticals, specialized marine and industrial contractors, and technology-intensive design-build specialists. Dominant competitive moves involve portfolio diversification into modular prefabrication and strategic partnerships with international engineering firms for complex megaproject delivery.
Within the diversified conglomerate tier, Saudi Binladin Group exemplifies vertical integration across civil works and project management capabilities. Among specialized contractors, Nesma & Partners Contracting occupies a position in marine and industrial segments, while El Seif Engineering Contracting represents the technology-intensive delivery archetype on complex developments. These three anchors sit within distinct capability clusters that align with Vision 2030 procurement segmentation.
| Leading Market Players |
|---|
| Saudi Binladin Group |
| Nesma & Partners Contracting |
| Almabani General Contractors |
| El Seif Engineering Contracting |
| Al-Rashid Trading & Contracting |
| AlKifah Contracting |
| Al Ayuni |
| Al Bawani |
| Bechtel Saudi Arabia |
| Others |
Value Chain & Pricing Dynamics
SASO conformity assessment protocols gate both supplier qualification and price differentiation across Saudi Arabia's construction inputs. Contractors face dual cost premiums: certification fees for imported materials and accelerated testing timelines for megaproject mobilization. This regulatory architecture compresses margins for uncertified vendors while rewarding prequalified suppliers with pricing power on bundled EPC packages.
Pricing Analysis
Legacy 2D documentation workflows command 15-25% cost penalties against BIM-enabled competitors on NEOM and Qiddiya tenders. Three-tier pricing structure across BIM-certified, code-compliant, and uncertified contractor tiers reflects capability gaps rather than pure quality gradients. Cost compression in residential construction intensifies as National Housing Company cost controls squeeze villa and apartment builders. Infrastructure agencies exhibit lowest price sensitivity due to complexity premiums and longer contract tenors.
Supply Chain Analysis
Jeddah Islamic Port congestion and container availability constraints on Asia-Gulf trade lanes elevate landed costs for European construction chemicals and Asian prefabricated structures. China, India, and Germany anchor supply for structural steel grades S275 and S355, SFDA-regulated admixtures, and modular wall panel systems. Single-source vulnerability concentrates in corrosion-resistant coating systems for Eastern Province petrochemical construction. Distribution runs through consolidated procurement vehicles under Vision 2030 delivery authorities rather than fragmented developer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Vision 2030's procurement consolidation fragments opportunity across specialized capability niches. Government infrastructure agencies now displace private developers as volume anchors, creating distinct competitive zones for marine industrial, digital delivery, and modular construction specialists.
For Market Incumbents: Fortify position through captive production of precast concrete elements and in-house BIM capability centers. The Saudi Building Code's Level 2 compliance mandates threaten exclusion for legacy contractors dependent on 2D documentation. Backward integration into modular fabrication facilities in Riyadh's megaproject corridor secures margin protection against fixed-price contract volatility. For New Entrants and Emerging Players: Anchor in Eastern Province marine and heavy industrial construction where Nesma & Partners Contracting's specialization has not saturated demand. Jubail and Ras Al-Khair petrochemical expansion offers penetrable white space for contractors with SASO-accredited welding certifications. Target design-build partnerships with international engineering firms as the primary go-to-market angle for giga-project prequalification. For Investors and Strategic Acquirers: Saudi Energy Efficiency Center mandates reshapes the acquisition landscape toward low-carbon material suppliers and green construction technology platforms. Long-term viability centers on contractors capable of LEED-equivalent certification delivery at industrial scale. The signal to watch is bundled procurement package concentration in Riyadh's megaproject corridor exceeding single-source thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| BIM Capability Center Investment | Level 2 compliance unlocks NEOM and Qiddiya prequalification pools. |
| Modular Fabrication Facility Buildout | Offsite manufacturing compresses timelines for Red Sea Project hospitality units. |
| SASO Accreditation Partnership | Accelerated material testing reduces mobilization delays on fast-track sites. |
| Green Construction Certification Program | Saudi Energy Efficiency Center mandates create premium positioning for compliant suppliers. |
| Marine Engineering Joint Venture | Eastern Province petrochemical expansion demands specialized corrosion-resistant capabilities. |
Study Parameters
Cross-validation between contractor procurement leads and regulatory affairs specialists anchors the qualitative findings in this study. Primary fieldwork encompassed interviews with EPC contract managers, SASO certification officers, material procurement directors, and megaproject delivery executives. Secondary sources included Saudi Building Code amendments, National Housing Company technical specifications, SFDA construction chemical regulations, and customs trade flow records. Bottom-up project pipeline aggregation and top-down macroeconomic triangulation framed the market sizing.
Sensitivity analysis around steel price volatility and BIM adoption timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, end user category, technology adoption tier, and application vertical. CAGRs derived from historical contract award patterns and announced megaproject capital deployment schedules. Industry-specific inputs encompassed SFDA conformity assessment timelines and Saudi Energy Efficiency Center mandate rollout trajectories.
Material uncertainties — commodity price swings, regulatory enforcement intensity, and skilled labor availability — sit outside the modeled envelope. Forecasts reflect documented assumptions about Vision 2030 project execution continuity and SASO accreditation capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Singapore Data Center Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
North America Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
North America Modular Construction Market
Building Construction
Mezzanine Floor Market
Building Construction
Oman Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Thailand Construction Market
Building Construction
Australia Construction Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Egypt Residential Construction Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
El Salvador Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Middle East & Africa Infrastructure Construction Market