
 Global Artemisinin Combination Therapy Market | 2026-2036
Global Artemisinin Combination Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artemisinin Combination Therapy Market Foresight
WHO prequalification standards for antimalarial medicines is rebalancing the cost-of-entry calculus for manufacturers seeking procurement contracts through international funding mechanisms. Sanofi leverages its integrated supply chain from artemisinin cultivation to finished formulation to sustain competitive positioning in endemic markets. Novartis AG anchors the Coartem franchise through long-standing agreements with the Global Fund and national malaria control programs. Cipla Ltd. competes on cost-optimized production of WHO-prequalified generics for public sector tenders.
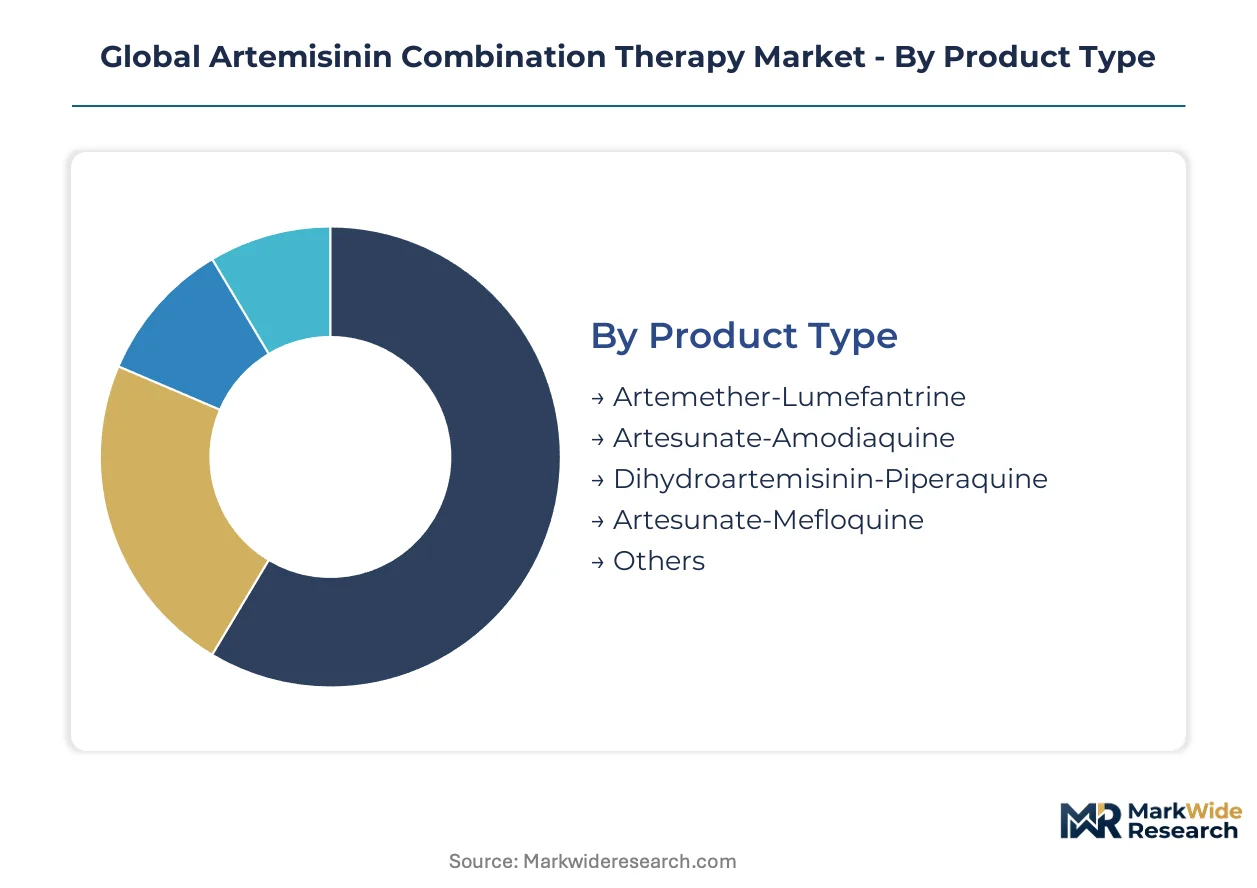
Artemisinin combination therapy comprises fixed-dose formulations pairing artemisinin derivatives with longer-acting partner drugs to ensure complete parasite clearance and resistance prevention, typically manufactured through semisynthetic or plant-extraction routes with stringent stability requirements for tropical distribution. Artemether-Lumefantrine dominates procurement volumes due to its established safety profile and broad WHO endorsement, while Dihydroartemisinin-Piperaquine extends treatment access in regions with emerging Lumefantrine tolerance. The therapy area segmentation shows uncomplicated malaria occupying the core volume base, with drug-resistant malaria representing the fastest-growing addressable subset as first-line failures multiply.
FDA, WHO prequalification, and EMA standards collectively govern product registration pathways, with WHO PQ serving as the gatekeeper for Global Fund and PMI-eligible purchases in endemic countries. National regulators in India (CDSCO) and China (NMPA) shape active pharmaceutical ingredient export licensing for downstream formulation. Stakeholders must monitor artemisinin raw material sourcing concentration in Vietnam and China, plus the pace of semisynthetic artemisinin scale-up, to assess supply vulnerability and procurement cost trajectories.
Market Dynamics
Fixed-dose combination mandates from WHO are compressing single-ingredient suppliers while concentrating procurement authority in national malaria control programs across sub-Saharan Africa. This regulatory pivot is redrawing competitive boundaries around prequalification status rather than manufacturing scale alone.
Growth Catalysts
- Semisynthetic artemisinin production:Yeast-based biosynthesis is reducing cultivation dependency on Vietnamese and Chinese agricultural cycles. Biotech platforms are stabilizing raw material costs for formulation manufacturers.
- Global Fund replenishment cycles:Multi-year grant commitments to endemic countries are creating predictable demand visibility for WHO-prequalified suppliers. Procurement volumes through this mechanism anchor manufacturer capacity planning.
- Uganda's national treatment policy revision:Updated first-line therapy guidelines are expanding Dihydroartemisinin-Piperaquine access in high-transmission districts. This geographic pivot is diversifying product mix beyond Artemether-Lumefantrine dominance.
Market Restraints
- Artemisinin agricultural concentration:Over 80 percent of botanical raw material originates from Vietnamese central highlands and Chinese Yunnan province. Climate volatility in these zones threatens active pharmaceutical ingredient supply continuity.
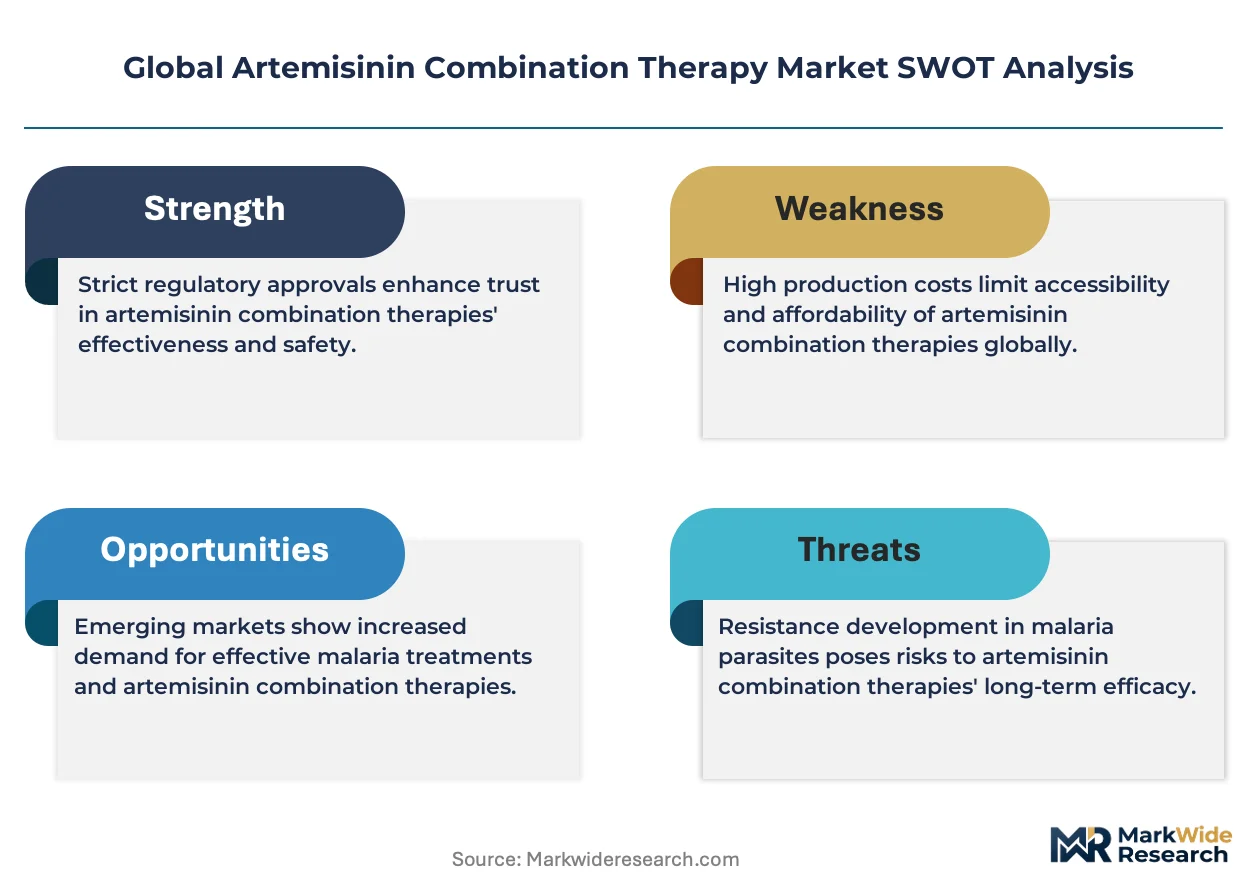
- Partner drug resistance emergence:Lumefantrine tolerance in Greater Mekong subregion is compressing effective product lifespan. This biological limitation is accelerating R&D reinvestment requirements without guaranteed returns.
- WHO prequalification timeline friction:Stringent stability testing for tropical climates extends regulatory approval cycles to 24-36 months. This procedural barrier blocks rapid generic substitution when shortages emerge.
Strategic Opportunities
- Democratic Republic of Congo private sector penetration:Informal medicine vendors serve 60 percent of fever cases outside public clinic networks. Formal distribution partnerships with accredited drug shops could capture this fragmented channel.
- Seasonal malaria chemoprevention expansion:Sahel region pilot programs are validating intermittent preventive therapy for children under five. This application extension opens pediatric formulation development pathways.
- Indian PLI scheme for active pharmaceutical ingredients:Production-linked incentives are attracting artemisinin derivative manufacturing to Gujarat and Hyderabad clusters. This policy tailwind could diversify supply geography beyond Southeast Asian concentration.
Industry Challenges
- Pharmacovigilance workforce scarcity:Post-market surveillance for adverse drug reactions requires trained clinicians in rural Nigeria and eastern DRC. This talent gap limits real-world safety data collection for resistance monitoring.
- Cold chain infrastructure deficits:Lumefantrine's temperature sensitivity demands controlled distribution through last-mile networks. Capex requirements for solar refrigeration at peripheral health posts strain procurement budgets.
- Intellectual property fragmentation across combination partners:Cross-licensing negotiations between artemisinin derivative patents and partner drug holdings create transaction complexity. This IP coordination overhead delays fixed-dose product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artemisinin Combination Therapy Market |
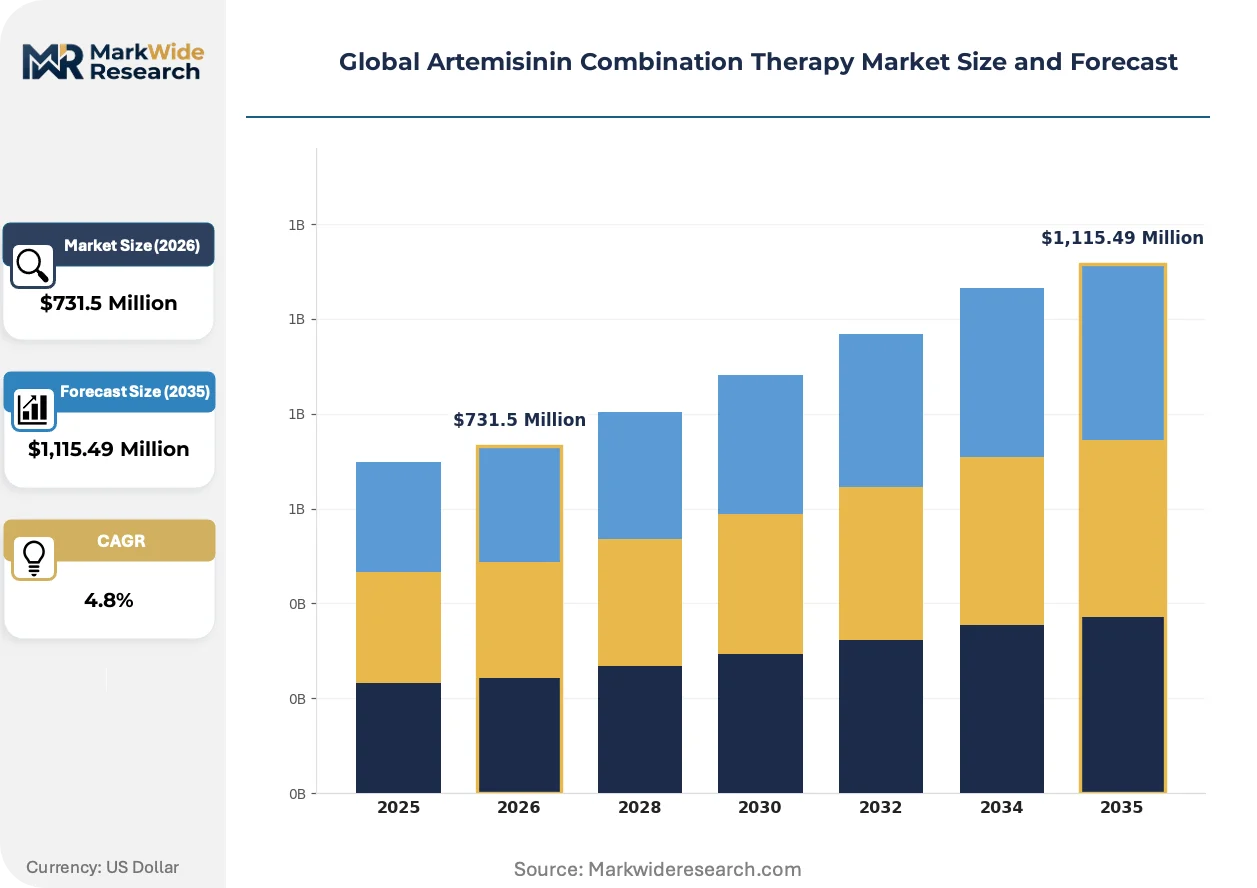
| Market Size in 2026 | $731.5 Million |
| Market Size in 2035 | $1,115.49 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artemether-Lumefantrine, Artesunate-Amodiaquine, Dihydroartemisinin-Piperaquine, Artesunate-Mefloquine, Others Therapy Area: Uncomplicated Malaria, Severe Malaria, Drug-Resistant Malaria, Mixed Malaria Infections End User: Public Health Facilities, Private Clinics, Research Institutions, Non-Governmental Organizations Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Community Health Centers |
| Companies Covered | Sanofi, Novartis AG, Cipla Ltd., KPC Pharmaceuticals, Guilin Pharmaceutical Co., Ltd, Ipca Laboratories Ltd., Calyx Chemicals and Pharmaceuticals Ltd., Fosun Pharmaceutical, AdvaCare Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artemisinin Combination Therapy Market Shifts & Advancements
Manufacturing technology and procurement architecture are converging to reshape how antimalarial therapies reach endemic populations. Three interconnected developments are compressing traditional supply timelines while elevating quality verification standards.
Continuous flow chemistry for artemisinin derivative synthesis is integrating into commercial manufacturing lines at Indian and Chinese active pharmaceutical ingredient facilities. This process technology reduces batch-to-batch variability while cutting solvent waste volumes by half. Contract manufacturers serving WHO-prequalified formulation sites are adopting these platforms to meet tightened environmental audit requirements.
EMA's revised good manufacturing practice guidelines for antimalarials are mandating real-time release testing for tropical stability parameters. European regulatory stringency is cascading into Global Fund procurement specifications through mutual recognition agreements. Suppliers without validated accelerated degradation data are losing tender eligibility across francophone West African national programs.
Nigeria's federal ministry of health is consolidating state-level procurement into centralized national tenders with prequalified supplier pools. This buyer concentration is displacing fragmented state-by-state purchasing that previously enabled substandard product infiltration. The new model rewards manufacturers with integrated quality management systems spanning cultivation through distribution.
Global Artemisinin Combination Therapy Market Segmentation
Artemisinin combination therapy markets segment across molecular formulation, clinical indication, procurement channel, and patient access point. These divisions determine manufacturing scale, regulatory pathway, and pricing architecture for suppliers competing in endemic disease programs.
Product Type:
Formulation chemistry dictates stability profiles, dosing convenience, and resistance management protocols across tropical distribution networks.
- Artemether-Lumefantrine:The fixed-dose pairing combines a rapid-acting artemisinin derivative with a longer-acting partner drug in a six-dose regimen. Nigerian public health facilities and Ghanaian national malaria control programs anchor procurement volumes through WHO-prequalified tenders.
- Dihydroartemisinin-Piperaquine:This once-daily formulation offers extended post-treatment prophylaxis through piperaquine's prolonged half-life. Uganda's revised national treatment policy is expanding access in high-transmission districts where lumefantrine tolerance has emerged.
- Artesunate-Amodiaquine:A fixed-dose alternative favored in West African francophone markets for cost-optimized procurement.
- Artesunate-Mefloquine:Reserved for specific resistance patterns in Southeast Asian border regions with stringent neurological monitoring requirements.
- Others:Includes investigational combinations and region-specific formulations awaiting WHO prequalification.
Mature deployment sits with Artemether-Lumefantrine. Newer deployment is concentrated in Dihydroartemisinin-Piperaquine.
Therapy Area:
Clinical severity stratifies manufacturing priorities, with uncomplicated cases driving volume and resistant infections demanding formulation innovation.
- Uncomplicated Malaria:Outpatient oral therapy accounts for the dominant procurement share across sub-Saharan African national programs. Fixed-dose combinations target Plasmodium falciparum clearance in ambulatory patients without organ dysfunction.
- Drug-Resistant Malaria:Artemisinin partial resistance in Greater Mekong subregion and partner drug failures in East Africa are accelerating demand for next-generation combinations. This segment is expanding most quickly as first-line therapeutic failures multiply.
- Severe Malaria:Parenteral artesunate formulations for hospitalized patients requiring rapid parasite reduction.
- Mixed Malaria Infections:Polymerase chain reaction-guided therapy for co-infections with Plasmodium vivax or Plasmodium malariae.
Volume leadership belongs to uncomplicated malaria. Steepest expansion trajectory characterizes drug-resistant malaria.
End User:
Procurement authority concentration shapes tender specifications and quality verification requirements.
- Public Health Facilities:Government clinics and district hospitals in Nigeria, Democratic Republic of Congo, and Uganda consolidate demand through national malaria control program tenders. WHO prequalification serves as mandatory entry criteria.
- Non-Governmental Organizations:Médecins Sans Frontières and Catholic Medical Mission Board operations in conflict zones drive emergency procurement with accelerated delivery timelines.
- Private Clinics:Urban fee-for-service providers in Kenyan and Tanzanian cities serving patients outside public insurance schemes.
- Research Institutions:Clinical trial sites in Burkina Faso and Thailand generating pharmacovigilance data for resistance surveillance.
Public sector procurement commands pricing benchmarks. NGO channels tolerate premium logistics costs for remote delivery.
Distribution Channel:
Last-mile infrastructure determines product integrity and patient adherence outcomes.
- Hospital Pharmacies:Centralized dispensing at referral institutions with cold chain capacity for lumefantrine storage.
- Community Health Centers:Peripheral access points in rural Ethiopia and Malawi where community health workers administer directly observed therapy.
- Retail Pharmacies:Accredited drug shops in Kenya's ADDO program and Tanzania's accredited drug dispensing outlets.
- Online Pharmacies:Emerging urban channels in South African and Nigerian metropolitan areas with temperature-controlled delivery partnerships.
Community health centers dominate rural reach. Retail pharmacy formalization is gaining regulatory traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam's Quang Nam province and China's Yunnan province concentrate artemisinin raw material cultivation, with downstream formulation clustering in Indian pharmaceutical corridors and European regulatory hubs.
Nigeria
Federal malaria control program tenders drive procurement volumes for Artemether-Lumefantrine across 36 states. The National Agency for Food and Drug Administration and Control enforces mandatory WHO prequalification for all public sector antimalarial purchases. Lagos and Kano serve as distribution hubs where cold chain infrastructure investments are expanding lumefantrine storage capacity.
Democratic Republic of Congo
Kinshasa's national malaria control program coordinates decentralized procurement through provincial health divisions. The country's national pharmaceutical regulator mandates import licensing for all antimalarial active pharmaceutical ingredients. Informal medicine markets in North Kivu and Ituri provinces present formalization opportunities for accredited drug shop networks.
Uganda
Revised national treatment guidelines are expanding Dihydroartemisinin-Piperaquine access in high-transmission districts bordering Lake Victoria. The National Drug Authority streamlined registration pathways for WHO-prequalified fixed-dose combinations. Kampala anchors pharmaceutical distribution while regional hubs in Gulu and Mbarara extend last-mile delivery to refugee settlements.
India
Production-linked incentive schemes for active pharmaceutical ingredients are attracting artemisinin derivative manufacturing to Gujarat and Hyderabad clusters. CDSCO governs export licensing for downstream formulation supply to African endemic markets. Ankleshwar and Visakhapatnam industrial zones host contract manufacturers serving WHO-prequalified tender requirements.
Vietnam
Central highlands cultivation zones in Lam Dong and Dak Lak provinces supply over half of global botanical artemisinin raw material. The Ministry of Health coordinates with agricultural extension services to stabilize farmer contract pricing. Quang Nam province's Chu Lai Open Economic Zone hosts extraction facilities with direct pipeline connections to formulation partners.
Global Artemisinin Combination Therapy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the antimalarial value chain. The market structure concentrates procurement authority around WHO prequalification status rather than manufacturing scale alone. Three archetypes dominate: integrated cultivator-formulators with agricultural-to-pharmaceutical control, generic specialists optimized for public tender cost benchmarks, and research-oriented innovators addressing resistance patterns. Competitive moves center on backward integration into raw material security and strategic partnerships with national malaria control programs.
Among integrated pharmaceutical conglomerates, Sanofi and Novartis AG exemplify the cultivator-formulator archetype with agricultural supply chain control. Cipla Ltd. occupies the generic specialist position, representing cost-optimized production for WHO-prequalified tenders. These three companies anchor the competitive landscape through distinct strategic positioning across the value chain.
| Leading Market Players |
|---|
| Sanofi |
| Novartis AG |
| Cipla Ltd. |
| KPC Pharmaceuticals |
| Guilin Pharmaceutical Co., Ltd |
| Ipca Laboratories Ltd. |
| Calyx Chemicals and Pharmaceuticals Ltd. |
| Fosun Pharmaceutical |
| AdvaCare Pharma |
| Others |
Supply & Pricing Matrix
WHO prequalification mandates for fixed-dose combinations are compressing supplier pools and forcing manufacturers to absorb extended stability-testing costs, which in turn stratifies pricing around certification tiers rather than production scale alone.
Pricing Analysis
Expedited delivery premiums for emergency procurement channels command significant markups over standard tender cycles, while spot inventory liquidations from non-prequalified suppliers trade at distressed levels. Three-tier pricing structure across premium, standard, and economy levels reflects WHO PQ status, cold chain capability, and volume commitment scale. Cost compression in the economy tier is intensifying because Indian and Chinese generic manufacturers are absorbing regulatory compliance overhead to maintain tender eligibility. National malaria control programs exhibit the highest price sensitivity, whereas Médecins Sans Frontières operations tolerate premium logistics costs for rapid deployment.
Supply Chain Analysis
Direct-to-national-program channels handle bulk procurement volumes through centralized tenders, while accredited drug shop networks extend formal distribution into informal medicine markets. Raw material extraction concentrates in Vietnam's central highlands and China's Yunnan province, with downstream formulation clustering in Gujarat and Hyderabad industrial corridors. Agricultural artemisinin harvests draw from Vietnamese Lam Dong cultivation zones and Chinese Dak Lak contract farms, while semisynthetic production rests on yeast-based biosynthesis platforms. Single-source vulnerability threatens supply continuity because climate volatility in Southeast Asian growing regions disrupts active pharmaceutical ingredient flows. Distribution runs through cold chain-dependent hospital pharmacies and community health centers with solar refrigeration at peripheral posts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around prequalification status as the primary barrier to entry, with WHO PQ timelines and capital requirements forcing subscale cultivators and formulation assemblers toward exit or acquisition.
For Market Incumbents: Lock in raw material security through backward integration into Vietnamese cultivation contracts or captive semisynthetic production capacity, while reinforcing cold chain partnerships with national malaria control programs in Nigeria and Uganda to defend tender positioning against emerging Indian generic specialists. Prioritize R&D investment in next-generation combinations addressing lumefantrine tolerance patterns in East African districts. For New Entrants and Emerging Players: Launch via accredited drug shop partnerships in the Democratic Republic of Congo's informal medicine markets, where 60 percent of fever cases bypass public clinic networks and prequalified supplier penetration remains minimal. Target pediatric formulation development for seasonal malaria chemoprevention programs in the Sahel region, leveraging the policy tailwind from pilot program validation and softer competitive density versus adult first-line therapy tenders. For Investors and Strategic Acquirers: Re-rating potential sits with integrated cultivator-formulators given the supply security premium commanded by agricultural-to-pharmaceutical control as climate volatility intensifies. Acquisition focus should center on Vietnamese extraction facilities with established farmer contract networks and WHO-prequalified Indian formulation sites with validated tropical stability data. Watch semisynthetic artemisinin scale-up rates as the inflection indicator for raw material cost trajectory and cultivation-dependent supplier margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Vietnamese and Chinese agricultural contracts secure artemisinin supply against climate disruption. |
| Semisynthetic Production Scale-Up | Yeast-based biosynthesis platforms reduce dependency on seasonal botanical harvest cycles. |
| WHO Prequalification Investment | Accelerated stability testing capabilities unlock Global Fund and PMI-eligible procurement volumes. |
| Pediatric Formulation Development | Sahel region seasonal chemoprevention programs create new addressable patient populations. |
| Accredited Drug Shop Partnerships | Formal distribution channels capture informal medicine market share in eastern DRC provinces. |
Research Methodology
Multi-period observation of WHO prequalification timelines, Global Fund disbursement cycles, and national treatment policy revisions anchored the trend analysis, supplemented by interviews with regulatory affairs leads at formulation manufacturers, procurement officers at national malaria control programs, and agricultural extension directors in Vietnamese cultivation zones. Secondary validation drew from WHO PQ listings, Global Fund grant documentation, CDSCO export licensing records, and customs data on artemisinin derivative shipments. Bottom-up tender volume aggregation and top-down disease burden modeling provided cross-verification.
Input-output matrices mapped artemisinin raw material flows through extraction, derivative synthesis, and finished formulation stages, with segmentation across molecular pairing, therapy area severity, and procurement channel authority. CAGRs were derived from projected patient volume growth, treatment policy substitution rates, and pricing trajectory assumptions across the analysis window. Forecast inputs incorporated semisynthetic production scale-up pace, partner drug resistance emergence patterns, and national tender consolidation trends in Nigerian federal procurement.
Artemisinin agricultural yield volatility, WHO prequalification timeline extensions, and partner drug resistance acceleration are the dominant revision risks that could alter projected supply-demand balances. Forecasts reflect documented assumptions regarding biosynthesis adoption rates and policy substitution timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Apixaban Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Hypertension Drug Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Ketoprofen API Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Global Olanzapine Market