
 Arrowroot Starch Market | 2026-2036
Arrowroot Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Arrowroot Starch Market Outlook
Market Context
Subscription-based ingredient sourcing platforms is recalibrating how food manufacturers procure arrowroot starch, shifting volume commitments from spot purchases to contracted annual deliveries. McCormick & Company leverages its spice and seasoning distribution network to secure preferential access to Caribbean and Southeast Asian arrowroot supply chains. Bob's Red Mill Natural Foods anchors the North American retail channel through its gluten-free specialty positioning and direct-to-consumer fulfillment infrastructure. NOW Foods competes on certified organic volume, operating dedicated clean-room milling facilities that meet pharmaceutical-grade specifications.
Technical Definition and Segments
Arrowroot starch is a refined carbohydrate extracted from the rhizomes of Maranta arundinacea, yielding a fine white powder with approximately 23% amylose content and neutral flavor profile that gelatinizes at lower temperatures than cornstarch. The extract serves primarily as a thickening agent, stabilizer, and texturizer across food processing, pharmaceutical excipient, and cosmetic formulation applications. Powder form dominates current volume throughput due to its compatibility with industrial-scale blending operations, while the gluten-free segment commands premium pricing multiples as celiac-safe certification becomes a non-negotiable specification for major food brands. Organic form is expanding fastest as EU Green Deal agricultural standards and USDA National Organic Program rules tighten residue limits on imported starches.
Regulatory Frame
FDA food additive regulations, USDA organic certification requirements, and EU REACH chemical safety standards collectively govern arrowroot starch market access, with compliance costs rising for suppliers lacking documented traceability systems. The FDA's Food Safety Modernization Act mandates hazard analysis for imported starches, while EU EFSA novel food assessments delay entry for unconventional extraction methods. Stakeholders must monitor evolving allergen labeling mandates and carbon border adjustment mechanisms that will reshape sourcing economics between tropical origin regions and end-use markets.
Market Dynamics
Clean-label certification requirements are restructuring supplier qualification criteria across the arrowroot starch value chain, forcing tropical origin processors to document traceability systems that satisfy FDA and USDA organic standards.
Growth Catalysts
- EU Green Deal agricultural standards:Tightening residue limits on imported starches are accelerating organic arrowroot conversion in Caribbean and Southeast Asian growing regions.
- Gluten-free bakery expansion:Celiac-safe certification has become a non-negotiable specification for major food brands, pulling arrowroot-derived thickeners into premium formulation pipelines.
- Paleo diet adherence:Consumer rejection of grain-based starches in the United States is displacing cornstarch and wheat flour in home cooking and commercial foodservice.
Market Restraints
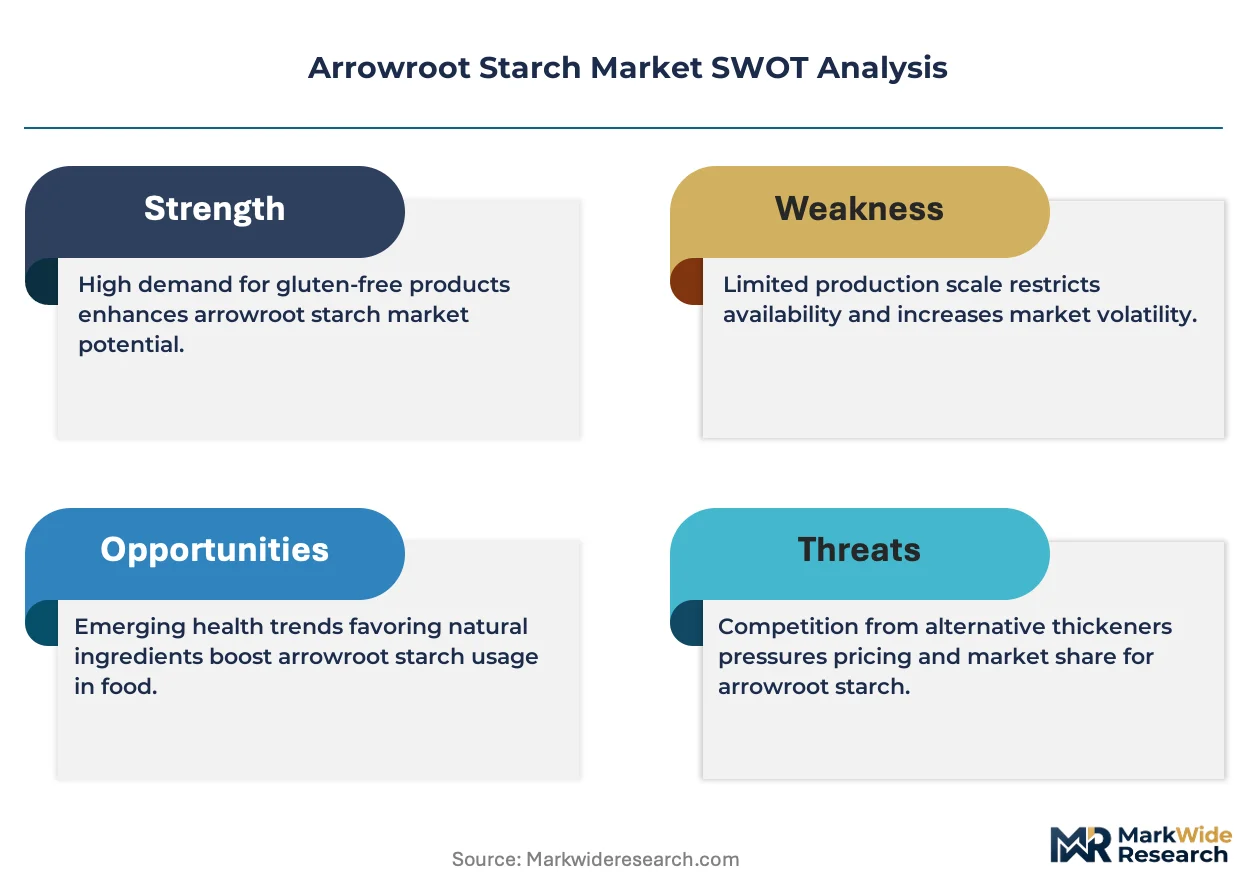
- Input cost volatility:Rhizome harvest yields fluctuate with monsoon patterns in tropical growing regions, compressing processor margins during poor weather cycles.
- Supply concentration risk:Over-reliance on smallholder farming networks in St. Vincent and the Grenadines creates volume instability when extreme weather disrupts collection infrastructure.
- Substitution threat:Tapioca starch from cassava offers equivalent functional properties at lower unit economics, pressuring arrowroot positioning in cost-sensitive industrial applications.
Strategic Opportunities
- Pharmaceutical excipient expansion:Clean-room milling capabilities that meet pharmaceutical-grade specifications are opening high-margin channels in tablet binding and capsule filling.
- Subscription sourcing platforms:Annual contracted deliveries are replacing spot purchases, enabling processors to secure forward financing for organic certification investments.
- Carbon border adjustment mechanisms:EU carbon accounting requirements will reward low-emission tropical supply chains with preferential market access against higher-carbon alternatives.
Industry Challenges
- Organic certification timelines:USDA National Organic Program transition periods require three years of documented chemical-free cultivation before premium pricing eligibility.
- Traceability system integration:Smallholder networks lack digital infrastructure to satisfy EFSA novel food assessment documentation requirements for unconventional extraction methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arrowroot Starch Market |
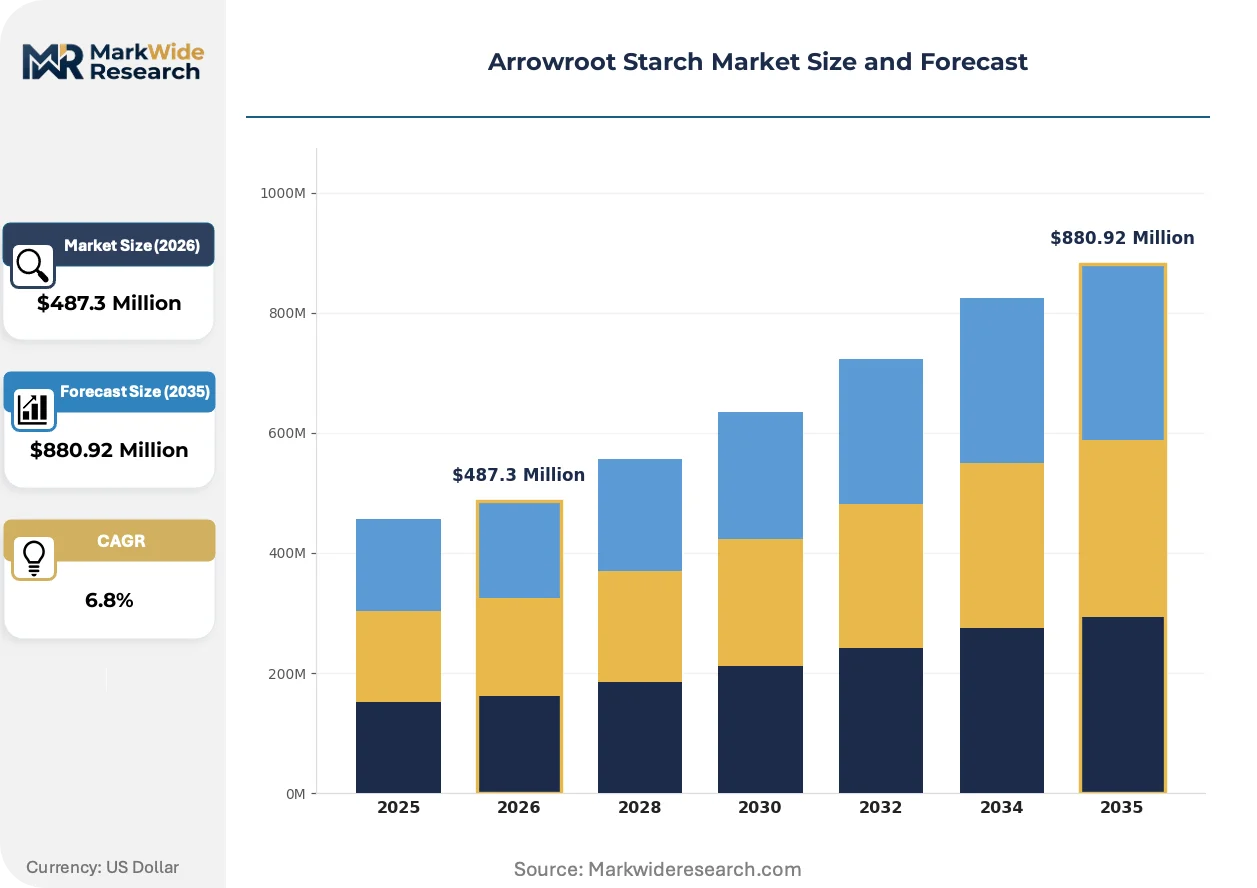
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Pellets, Liquid End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Textiles Form: Organic, Non-Organic, Gluten-Free, Specialty Blends Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | McCormick & Company, Westpoint Naturals, Bob's Red Mill Natural Foods, Frontier Co-op, Starwest Botanicals, NOW Foods, Mountain Rose Herbs, Nature's Way, Authentic Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arrowroot Starch Market Strategic Shifts
Extraction technology advances and procurement model evolution are compressing the gap between tropical origin processing and end-use manufacturer specifications.
Enzymatic extraction protocols are rewriting efficiency benchmarks for arrowroot starch recovery, boosting yield rates from rhizome inputs while reducing water and energy consumption. European pharmaceutical excipient manufacturers are adopting these methods fastest, drawn by pharmaceutical-grade purity requirements. The technology is rewriting competitive positioning between mechanical milling operations and biotech-enabled processors.
REACH chemical safety standards are mandating comprehensive substance registration for imported starches entering EU cosmetic and pharmaceutical channels. Compliance documentation burdens are falling heaviest on small-scale Caribbean processors lacking dedicated regulatory affairs capacity. Organic certification bodies are responding by bundling REACH pre-assessment services into their audit packages.
Direct-to-consumer fulfillment infrastructure is compressing traditional distributor markups in North American retail channels. Specialty food e-commerce platforms are capturing growing share of gluten-free home baker purchases, displacing conventional grocery wholesale relationships. This channel shift concentrates most visibly in subscription box services targeting paleo and allergen-free dietary adherents.
Arrowroot Starch Market Segmentation
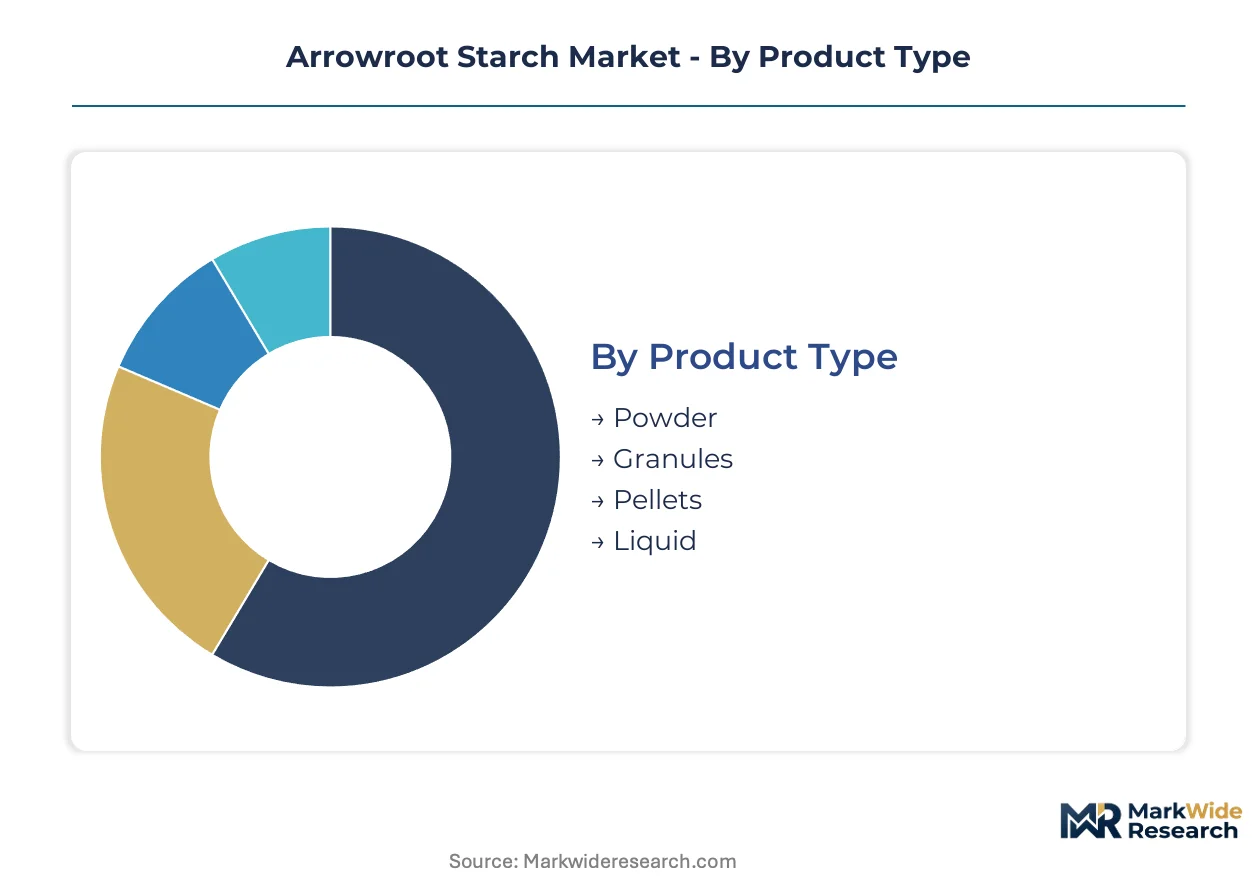
Arrowroot starch procurement decisions pivot on functional specifications, certification requirements, and supply chain reliability. Buyers evaluate gelatinization temperature, amylose content, and organic traceability against end-use performance standards. Segmentation reveals how premium certification tiers command pricing multiples while industrial volume flows through conventional channels.
Product Type:
Purchase volume and application flexibility drive buyer selection across physical formats.
- Powder:Fine white particles with approximately 23% amylose content dissolve rapidly in aqueous systems. Industrial food manufacturers in the United States specify powder for large-scale sauce and gravy production where uniform hydration is critical.
- Granules:Coarse particles offer controlled release characteristics in slow-cooking applications. European pharmaceutical excipient manufacturers favor granules for tablet binding where gradual starch gelatinization improves compression uniformity.
- Pellets:Agglomerated forms reduce dusting during automated handling systems. Animal feed compounders specify pellets for pelleting lines.
- Liquid:Pre-hydrated suspensions eliminate cooking steps in cold-process food manufacturing. Ready-to-drink beverage formulators use liquid arrowroot for instant thickening.
Powder leads on scale; liquid climbs the fastest as cold-process formulations expand.
End Use Industry:
Regulatory scrutiny and certification thresholds separate commercial segments by compliance burden.
- Food & Beverage:Clean-label thickeners and stabilizers for gluten-free, paleo, and allergen-free product lines. FDA Food Safety Modernization Act hazard analysis requirements force documented traceability from Caribbean and Southeast Asian origins.
- Pharmaceuticals:Tablet binders, capsule fillers, and excipient-grade starches meeting USP-NF monographs. NOW Foods operates dedicated clean-room milling facilities serving this channel.
- Cosmetics:Powder bases and absorbent agents in natural personal care formulations. EU REACH chemical safety registration mandates comprehensive substance documentation for imported starches.
- Textiles:Sizing agents and fabric finishing compounds. St. Vincent processors supply traditional textile mills seeking natural alternatives to synthetic polymers.
Food & Beverage dominates volume; Pharmaceuticals posts the steepest expansion trajectory on pharmaceutical-grade purity premiums.
Form:
Certification tier determines pricing architecture and market access eligibility.
- Organic:USDA National Organic Program and EU organic standards compliance with three-year transition documentation. EU Green Deal agricultural standards tighten residue limits, accelerating conversion in Caribbean growing regions.
- Non-Organic:Conventional cultivation without certification premiums. Cost-sensitive industrial applications in Southeast Asian food processing rely on non-organic supply.
- Gluten-Free:Celiac-safe certification with dedicated handling protocols. Major US food brands treat gluten-free status as non-negotiable specification.
- Specialty Blends:Custom formulations combining arrowroot with tapioca, potato, or other starches. Bakery manufacturers specify blends for optimized texture and cost performance.
Non-Organic maintains volume leadership; Organic gains share fastest on EU and US certification pull-through.
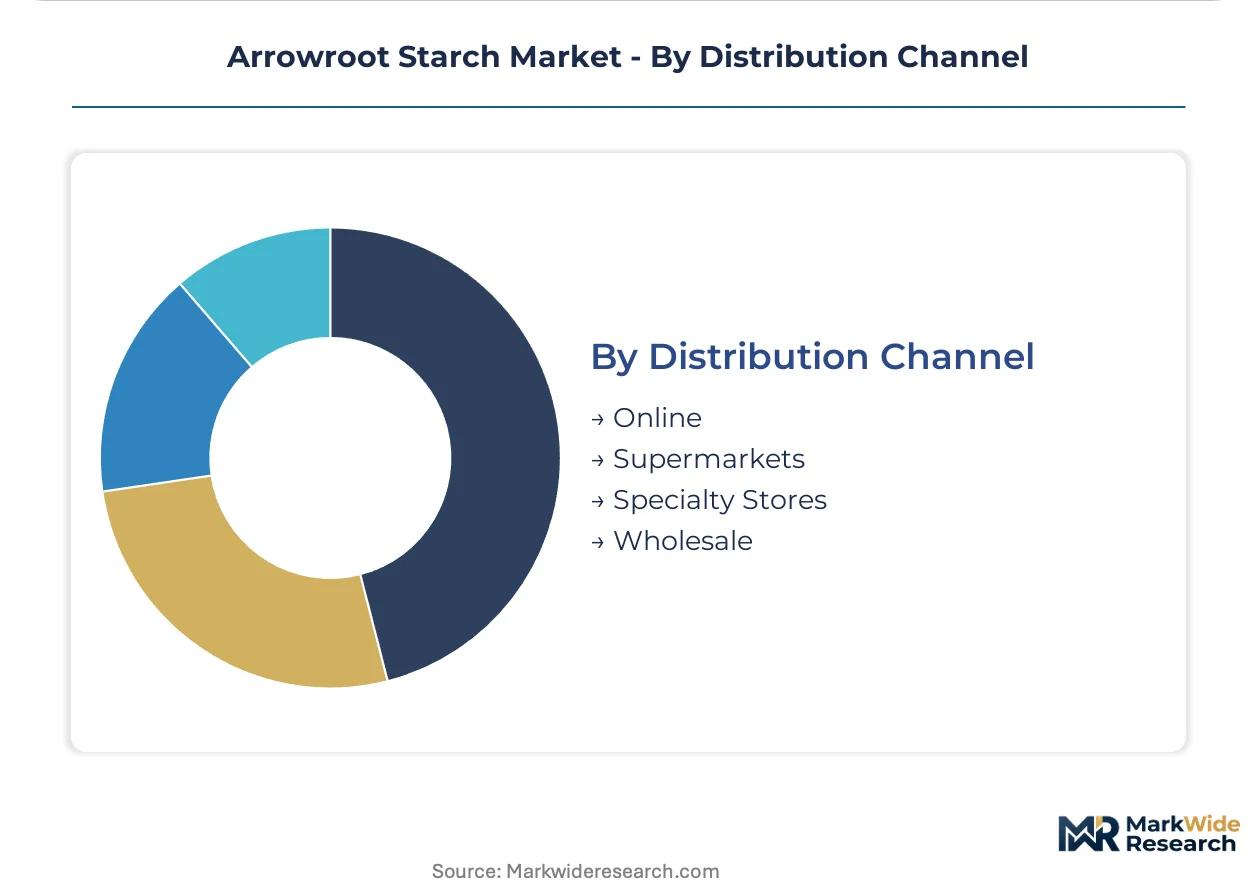
Distribution Channel:
Channel selection reflects buyer scale, urgency tolerance, and technical service requirements.
- Online:Direct-to-consumer fulfillment through specialty food e-commerce platforms. Subscription box services targeting paleo and allergen-free dietary adherents concentrate purchase patterns.
- Supermarkets:Mass retail placement for home baking and cooking applications. Bob's Red Mill Natural Foods anchors this channel through gluten-free specialty positioning.
- Specialty Stores:Health food and natural product retailers with educated staff. Independent retailers in urban US markets drive premium brand discovery.
- Wholesale:Bulk procurement for foodservice and industrial manufacturing. McCormick & Company leverages spice distribution networks to secure preferential arrowroot access.
Wholesale commands industrial volume; Online posts the fastest growth rate as subscription sourcing platforms displace spot purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium pricing for arrowroot starch while St. Vincent and the Grenadines struggles with climate-driven harvest volatility, illustrating how demand concentration and supply fragility operate on separate continents.
United States
Gluten-free bakery expansion and paleo diet adherence pull arrowroot-derived thickeners into premium formulation pipelines. FDA Food Safety Modernization Act hazard analysis requirements force documented traceability from Caribbean origins. Chicago and Minneapolis food manufacturing clusters specify organic-certified powder for large-scale sauce production.
St. Vincent and the Grenadines
Smallholder farming networks supply traditional textile mills and European pharmaceutical excipient manufacturers. USDA National Organic Program transition periods require three years of documented chemical-free cultivation before premium pricing eligibility. Kingstown processors lack digital infrastructure to satisfy EFSA novel food assessment documentation requirements.
Germany
EU Green Deal agricultural standards tighten residue limits on imported starches, accelerating organic arrowroot conversion in supplier countries. REACH chemical safety standards mandate comprehensive substance registration for starches entering cosmetic and pharmaceutical channels. Frankfurt pharmaceutical clusters adopt enzymatic extraction protocols for USP-NF monograph compliance.
Thailand
Southeast Asian food processing relies on non-organic supply for cost-sensitive industrial applications. Monsoon patterns create input cost volatility that compresses processor margins during poor weather cycles. Bangkok milling operations face substitution pressure from tapioca starch offering equivalent functional properties at lower unit economics.
United Kingdom
Specialty food e-commerce platforms capture growing share of gluten-free home baker purchases through subscription box services. EU carbon border adjustment mechanisms will reward low-emission tropical supply chains with preferential market access. London health food retailers drive premium brand discovery for allergen-free dietary adherents.
Arrowroot Starch Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with retail-facing entities commanding margin premiums while bulk suppliers compete on volume throughput. The vendor base clusters around three strategic archetypes: heritage natural foods brands with gluten-free specialty positioning, pharmaceutical-grade clean-room operators, and spice distribution networks securing preferential tropical supply access. Dominant competitive moves include backward integration into Caribbean and Southeast Asian growing regions and portfolio diversification toward pharmaceutical excipient certification.
Among heritage natural foods specialists, Bob's Red Mill Natural Foods anchors North American retail channels, NOW Foods occupies a position within pharmaceutical-grade clean-room milling, and McCormick & Company exemplifies spice distribution leverage for supply chain preferential access. Frontier Co-op and Starwest Botanicals represent the cooperative and botanical sourcing archetypes respectively. These entities collectively illustrate how certification tier and channel focus determine competitive positioning more than scale alone.
| Leading Market Players |
|---|
| McCormick & Company |
| Westpoint Naturals |
| Bob's Red Mill Natural Foods |
| Frontier Co-op |
| Starwest Botanicals |
| NOW Foods |
| Mountain Rose Herbs |
| Nature's Way |
| Authentic Foods |
| Others |
Value Chain & Pricing Dynamics
Smallholder farming networks concentrated in St. Vincent and the Grenadines drive labor-cost differentials that widen spreads between premium organic-certified and conventional economy-tier pricing, as Caribbean processors absorb harvest volatility while US buyers enforce strict traceability premiums.
Pricing Analysis
Capacity additions in Southeast Asian milling operations are reshaping price floors for non-organic powder grades, compressing margins for Caribbean-origin suppliers unable to match unit economics. Three-tier pricing structure across premium organic, standard gluten-free, and economy conventional levels separates certified pharmaceutical-grade from food-service bulk. Price differentiation centers on USDA organic certification status and dedicated gluten-free handling protocols. Pricing pressure stems from tapioca starch substitution in cost-sensitive industrial applications, with Southeast Asian food processors exhibiting highest price sensitivity while US pharmaceutical buyers remain least elastic.
Supply Chain Analysis
Single-source vulnerability sits with St. Vincent and the Grenadines smallholder networks, where extreme weather disrupts collection infrastructure without geographic diversification. Supply draws from St. Vincent and the Grenadines, Thailand, and Indonesia as primary origin points. Raw material dependencies include Maranta arundinacea rhizomes, monsoon-dependent harvest cycles, and organic certification transition periods. Supply chain risk centers on climate-driven harvest volatility compressing processor margins. Distribution runs through wholesale spice networks for industrial volume and subscription e-commerce platforms for retail premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arrowroot starch market functions as a stable compounder, with clean-label certification requirements from FDA and USDA organic programs generating sustained pricing power for qualified suppliers.
For Market Incumbents: Acquire dedicated clean-room milling capabilities to defend pharmaceutical excipient share against enzymatic extraction specialists entering from European markets. Secure backward integration into Caribbean growing regions to capture organic certification premiums and reduce third-party supply concentration risk. Tapioca starch substitution threat intensifies in Southeast Asian industrial channels, requiring certification investment as primary defensive lever. For New Entrants and Emerging Players: Specialty food e-commerce platforms represent the most penetrable channel for premium organic positioning, bypassing established wholesale relationships controlled by heritage brands. Target subscription box services targeting paleo and allergen-free dietary adherents in US urban markets. Cold-process liquid arrowroot formulations offer white-space entry angle with fastest-growing application segment. For Investors and Strategic Acquirers: Valuations sit cheapest among Southeast Asian non-organic processors facing margin compression from tapioca substitution and monsoon volatility. Long-term viability favors certified organic operators with documented traceability systems satisfying EU Green Deal agricultural standards. Signal to watch: EU carbon border adjustment mechanism implementation rewarding low-emission tropical supply chains with preferential market access.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | USDA National Organic Program compliance unlocks premium pricing multiples in US retail channels. |
| Enzymatic Extraction Adoption | European pharmaceutical manufacturers adopt yield-boosting protocols meeting USP-NF monograph standards. |
| Subscription Sourcing Platform Launch | Annual contracted deliveries displace spot purchasing, securing forward financing for certification transitions. |
| Clean-Room Milling Capacity Expansion | Pharmaceutical-grade specifications open high-margin tablet binding and capsule filling channels. |
| Direct-to-Consumer Fulfillment Buildout | Specialty e-commerce platforms capture gluten-free home baker purchases from conventional grocery wholesale. |
Study Parameters
Multiple input streams — primary interviews with tropical starch processors, regulatory affairs specialists, and food manufacturing procurement leads; secondary validation against FDA enforcement data, USDA organic certification records, and EU EFSA novel food assessments; plus customs trade flows from Caribbean and Southeast Asian origins — were reconciled through bottom-up volume triangulation against top-down category spend analysis.
Historical growth trajectories were cross-referenced against panel-based input from ingredient sourcing platform operators and clean-label brand managers across the analysis window. Segmentation dimensions modeled include product form, certification tier, end-use industry, and distribution channel complexity. CAGRs were derived from normalized volume and value progression curves, incorporating pharmaceutical excipient purity premiums and organic conversion timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon border adjustment implementation, monsoon pattern disruption, and tapioca starch substitution acceleration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Beverage Ingredients Market
Ingredients
Coconut Oil Market
Ingredients
Roll-Dried Starch Market
Ingredients
Jasmine Extract Market
Ingredients
North America Fats and Oils Market
Ingredients
North America Gelatin Market
Ingredients
Ground-Nut Oil Market
Ingredients
Europe Protein Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
Modified Maize Starch Market
Ingredients
Virgin Coconut Oil Market
Ingredients
Savory Ingredients Market
Ingredients
Oyster Shell Powder Market
Ingredients
Apple Extract Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
2'-Fucosyllactose (2'-FL) Market