
 Global Starch Recovery Systems Market | 2026-2036
Global Starch Recovery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Starch Recovery Systems Market Intelligence
Direct sales channels from equipment manufacturers to food processing plants is narrowing the influence of regional distributors. GEA Group leverages its extensive service network to support these direct relationships. Alfa Laval competes on the efficiency of its decanter centrifuge technology, while ANDRITZ specializes in complete plant solutions for starch processing.
Starch recovery systems are engineered assemblies that extract and purify starch granules from process wastewater. These systems primarily employ mechanical separation methods, such as centrifugation achieving over 99% recovery, to produce a usable starch slurry or powder. Wet starch recovery holds the largest market share due to its prevalence in potato and tapioca processing. Centrifugation technology remains the standard, though membrane separation offers advantages for smaller-scale operations.
Wastewater discharge standards set by agencies like the U.S. EPA and China's MEE create a compliance-driven need for these systems. Food-contact material regulations, including those from the FDA and the EU's EFSA, govern the construction materials of the equipment. Equipment manufacturers must therefore navigate both environmental and food safety rules. The key decision for end-users involves assessing the payback period of high-capital systems against rising water and effluent treatment costs.
Market Dynamics
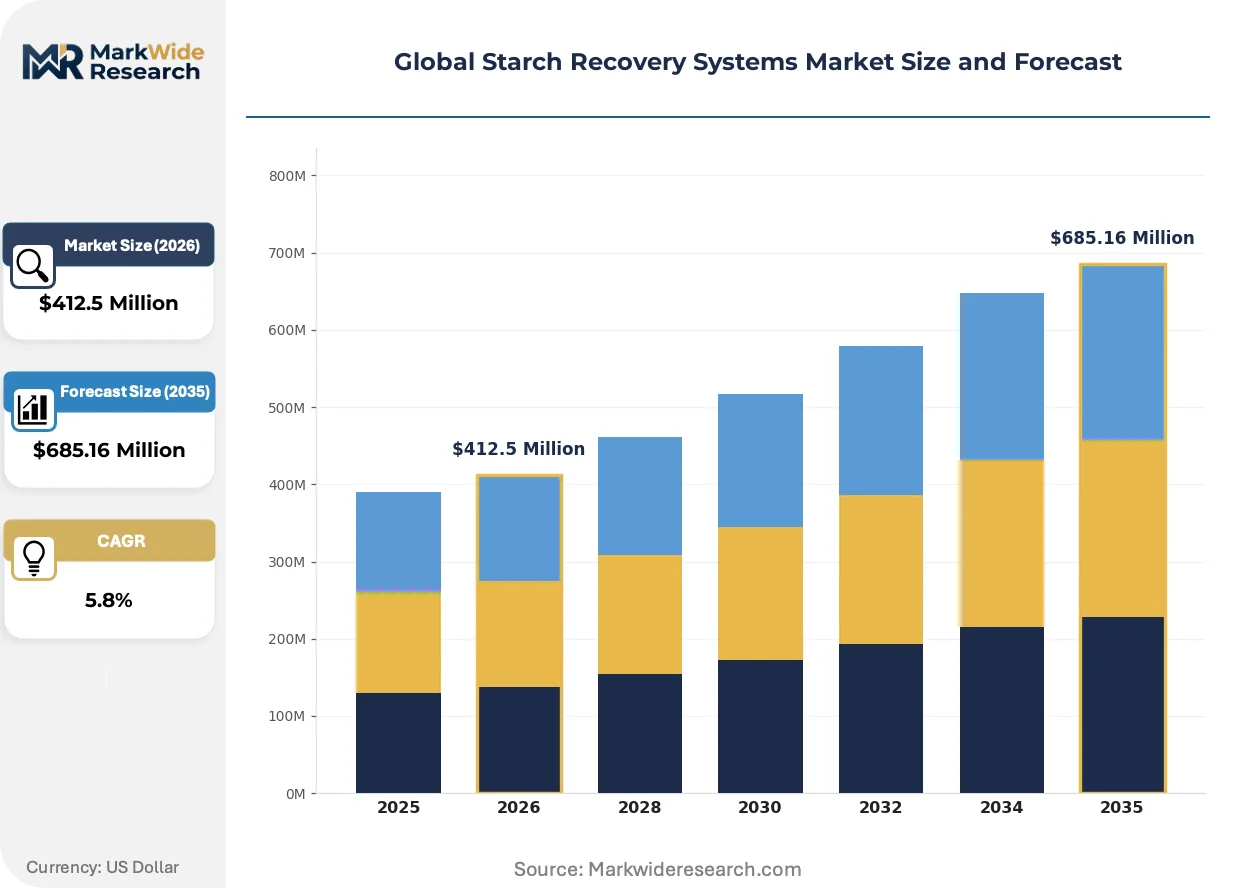
The central structural force shaping the starch recovery systems market is the global pivot towards a circular economy in food production. This shift, driven by regulations and resource scarcity, reframes process wastewater from a disposal liability into a valuable resource stream.
Growth Catalysts
- Wastewater Discharge Regulations:Increasingly stringent effluent standards from environmental agencies like the U.S. EPA and China's Ministry of Ecology and Environment (MEE) compel food processors to install recovery systems as a primary compliance mechanism to reduce organic load.
- Bioethanol Sector Expansion:The growing bioethanol industry, particularly in Brazil's sugarcane processing sector and the U.S. corn ethanol sector, requires efficient starch separation to maximize feedstock conversion and profitability, creating sustained demand for high-capacity systems.
- Circular Economy Policies:Frameworks such as the EU Green Deal incentivize food manufacturers to minimize waste and valorize byproducts. This policy pressure directly supports the business case for investing in starch recovery technology to capture and sell previously discarded material.
Market Restraints
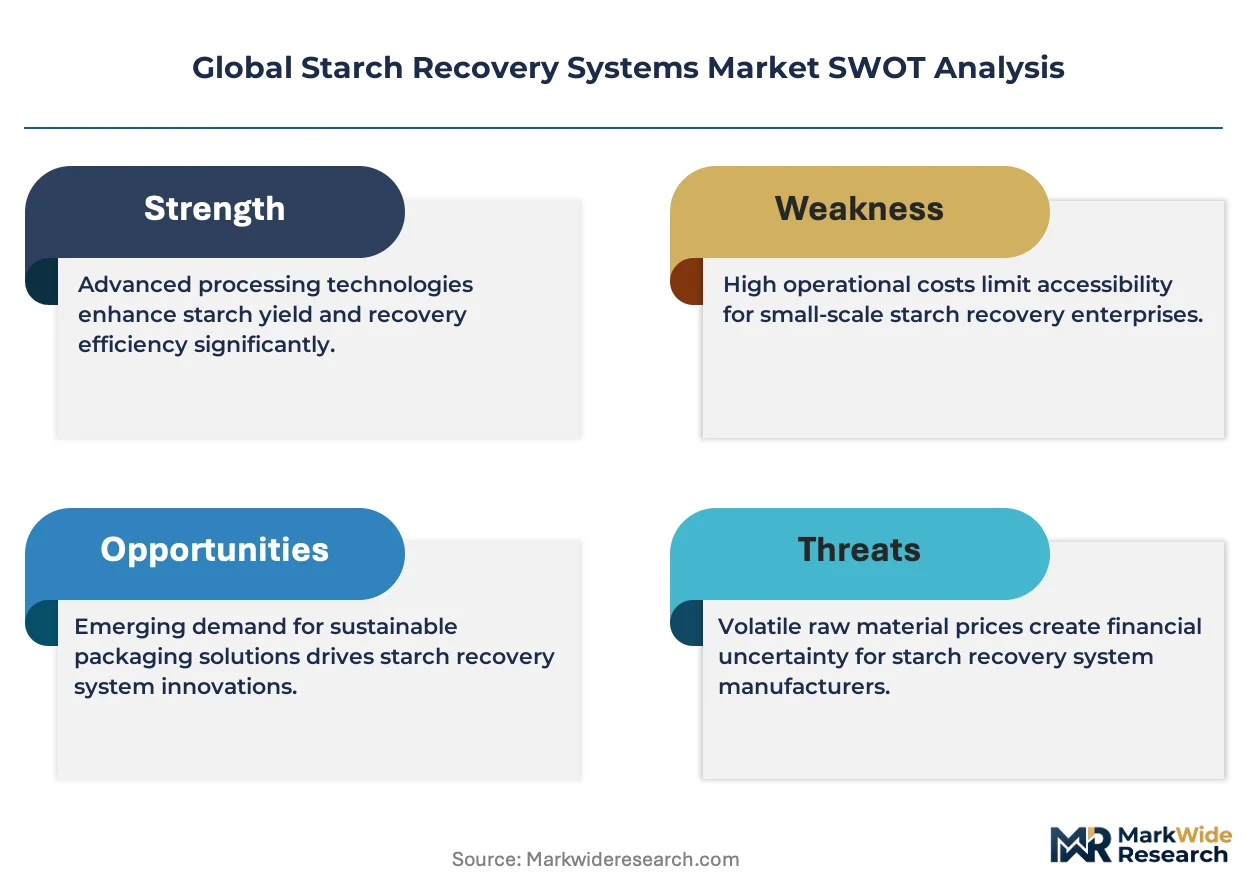
- High Capital Investment:The significant upfront cost of industrial-scale centrifugation and separation equipment presents a substantial financial barrier for small and medium-sized enterprises (SMEs) in the food processing industry, limiting market penetration in fragmented sectors.
- Energy Consumption Costs:Decanter centrifuges, the dominant technology, are energy-intensive. Volatile and rising electricity prices in key manufacturing regions can negatively impact the operational cost-benefit analysis and extend the payback period for these systems.
- Complex System Integration:Retrofitting bulky recovery systems into existing, often space-constrained, food processing facilities poses significant engineering challenges and can lead to costly production downtime during installation and commissioning, deterring some potential adopters.
Strategic Opportunities
- Plant-Based Protein Co-Recovery:Systems can be adapted to isolate valuable plant-based protein fractions from process water alongside starch. This creates a new, high-value revenue stream for food processors, particularly in the pea and legume processing industries.
- Membrane Filtration for Niche Applications:Membrane separation technologies offer a lower-capex, smaller-footprint alternative to centrifuges. This opens opportunities to serve smaller-scale or artisanal producers, such as those in Southeast Asia's tapioca processing sector, who cannot justify large capital outlays.
- Indian Food Processing Modernization:Government initiatives in India, like the Production Linked Incentive (PLI) scheme for the food processing industry, encourage capital investment in efficiency-enhancing technologies, creating a significant growth opportunity for starch recovery system vendors.
Industry Challenges
- Skilled Operator Shortage:The operation and maintenance of sophisticated separation systems require specialized technicians. A scarcity of this trained talent in many agricultural processing regions can lead to suboptimal system performance and increased operational risks for end-users.
- Food-Contact Material Compliance:Equipment must adhere to stringent food-contact material regulations set by bodies like the U.S. FDA and the European Food Safety Authority (EFSA). Navigating these rules adds complexity and cost to equipment design and manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Starch Recovery Systems Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Dry Starch Recovery, Wet Starch Recovery, Enzymatic Recovery, Continuous Starch Recovery Technology: Centrifugation, Filtration, Membrane Separation, Decanter Technology, Gravity Separation Application Sector: Animal Feed Manufacturing, Bioethanol Production, Textile Processing, Paper Manufacturing, Adhesive Production End User: Food Processing Plants, Biofuel Plants, Paper Mills, Chemical Manufacturers, Textile Facilities |
| Companies Covered | GEA Group, Alfa Laval, ANDRITZ, Flottweg SE, Larsson Sweden, Microtec Engineering Group, Myande Group, Nivobahovex, SiccaDania, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Starch Recovery Systems Market Strategic Shifts & Innovations
The market's evolution is defined by a convergence of digital process control and regulatory pressures for resource valorization. This transforms starch recovery from a simple mechanical separation step into an integrated component of a smart, circular food production facility.
Sensor arrays and process automation software are increasingly integrated directly into starch recovery equipment. Large-scale potato, corn, and tapioca processors are the primary adopters, using real-time data to optimize separation efficiency and resource consumption. This trend is digitizing the recovery process, elevating it from a fixed mechanical function to an adaptive, data-driven operation that maximizes yield while minimizing energy and water inputs.
Circular economy mandates, particularly the EU Green Deal's Farm to Fork strategy, are a powerful regulatory driver. The policy directly incentivizes food processors to minimize waste by investing in technologies that capture value from process side streams. Potato and wheat processors in European countries like Germany, France, and the Netherlands are most impacted, accelerating their upgrades to advanced recovery systems to meet environmental targets.
A notable shift from one-time equipment sales toward comprehensive service and operational support contracts is altering procurement patterns. This model displaces the traditional transactional purchase, with food processors increasingly preferring to outsource system maintenance, optimization, and performance guarantees to the equipment manufacturer. This demand for long-term partnerships is particularly visible in Brazil's bioethanol sector, where producers prioritize guaranteed uptime and output.
Global Starch Recovery Systems Market Segmentation
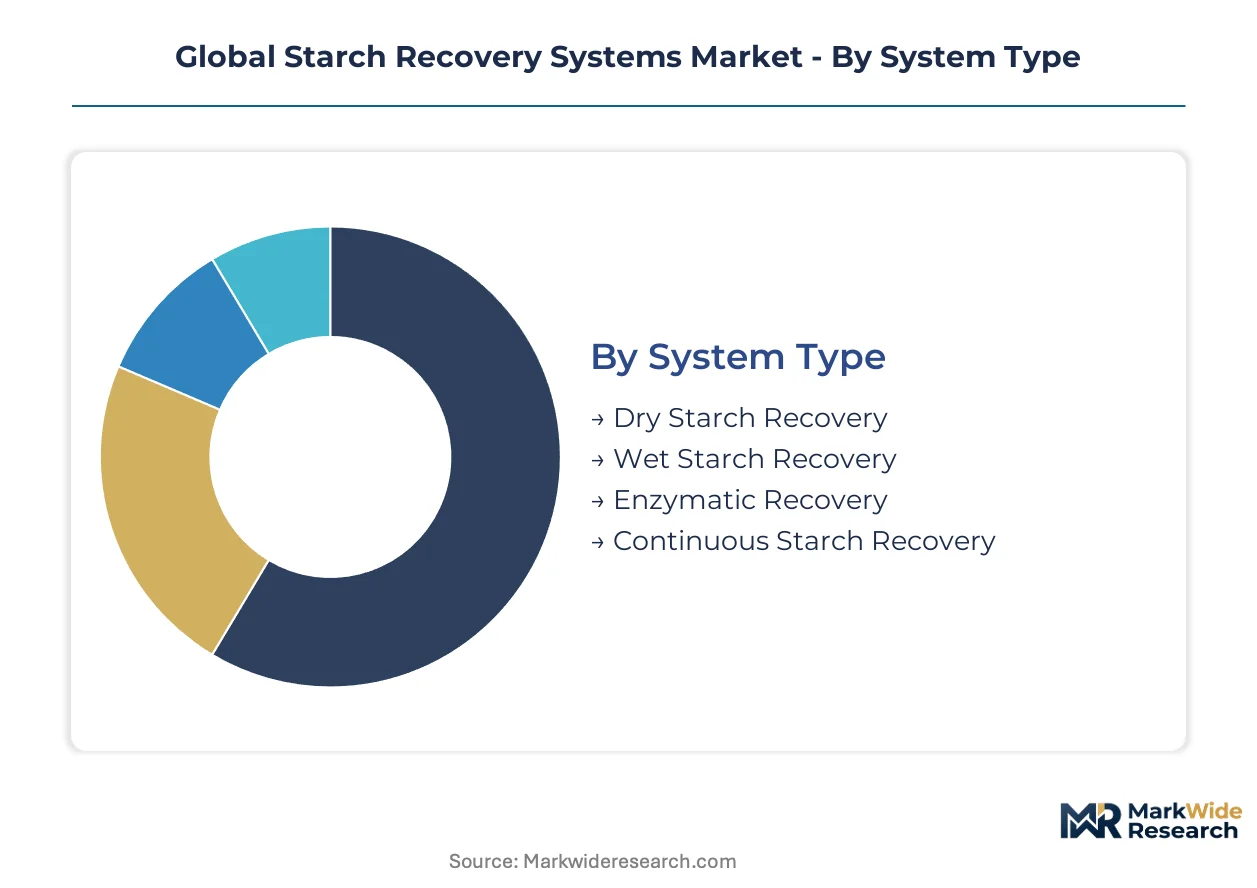
The segmentation of the global starch recovery systems market highlights the diverse technological approaches and end-use applications driving demand. This classification helps differentiate how various industries address wastewater valorization and resource efficiency challenges. Understanding these segments reveals the distinct needs of food processors and industrial manufacturers for starch recovery solutions.
System Type:
The system type spectrum for starch recovery ranges from traditional mechanical methods to advanced biochemical processes, each designed for specific feedstock characteristics and purity requirements.
- Wet Starch Recovery:Extracts starch granules from a liquid slurry, often used in potato and tapioca processing due to high water content in raw materials. This method achieves high recovery rates, producing a usable starch slurry for various industrial applications.
- Continuous Starch Recovery:Integrates multiple separation stages into an uninterrupted process flow, optimizing uptime and throughput for large-scale operations. Bioethanol plants in Brazil increasingly adopt continuous systems for efficiency and maximum feedstock conversion.
- Dry Starch Recovery:Involves physical separation of starch from dry raw materials, suitable for grain processing where water usage is minimized.
- Enzymatic Recovery:Utilizes enzymes to break down non-starch components, enhancing starch purity and yield in specialized applications.
Established volume favors Wet Starch Recovery; emerging adoption favors Continuous Starch Recovery.
Technology:
Starch recovery technologies vary in their separation principles, addressing different particle sizes, process volumes, and purity demands across diverse applications.
- Centrifugation:Employs high-speed rotation to separate starch particles from wastewater based on density differences, achieving over 99% recovery in many food processing operations. This technology forms the backbone of large-scale starch recovery in potato and corn processing.
- Membrane Separation:Utilizes semi-permeable membranes to filter out starch granules from liquid streams, offering advantages in smaller-scale operations due to lower capital expenditure and a compact footprint. This method provides high purity for specialized starch products.
- Filtration:Involves passing starch-laden water through porous media to retain starch particles, commonly used as a pre-treatment step.
- Decanter Technology:A type of centrifuge specifically designed to separate solids from liquids, widely applied in high-volume starch slurry dewatering.
- Gravity Separation:Relies on density differences for starch particles to settle naturally, a simpler method suitable for initial separation in some processes.
The efficiency and capacity needs of end-users primarily dictate technology selection.
Application Sector:
The range of application sectors for recovered starch reflects its versatility, with varying economic values and quality requirements influencing processing choices.
- Bioethanol Production:Utilizes recovered starch as a fermentable sugar source, maximizing feedstock conversion and profitability in facilities like those in the U.S. corn ethanol sector. This sector creates sustained demand for high-capacity starch recovery systems.
- Animal Feed Manufacturing:Incorporates recovered starch into feed formulations, valorizing a byproduct stream and reducing overall waste from food processing operations. This application provides a significant outlet for lower-grade starch.
- Textile Processing:Uses starch as a sizing agent to strengthen yarns and improve weaving efficiency, demanding specific purity levels for optimal performance.
- Paper Manufacturing:Employs starch as a binding agent and surface treatment to enhance paper strength and printability, contributing to product quality.
- Adhesive Production:Formulates starch-based glues for various industrial and packaging applications, leveraging its natural binding properties.
High-volume industrial applications drive significant demand, while specialized uses require tailored recovery solutions.
End User:
End-user segments for starch recovery systems span various industrial operations, each facing distinct regulatory pressures and economic incentives for resource recovery.
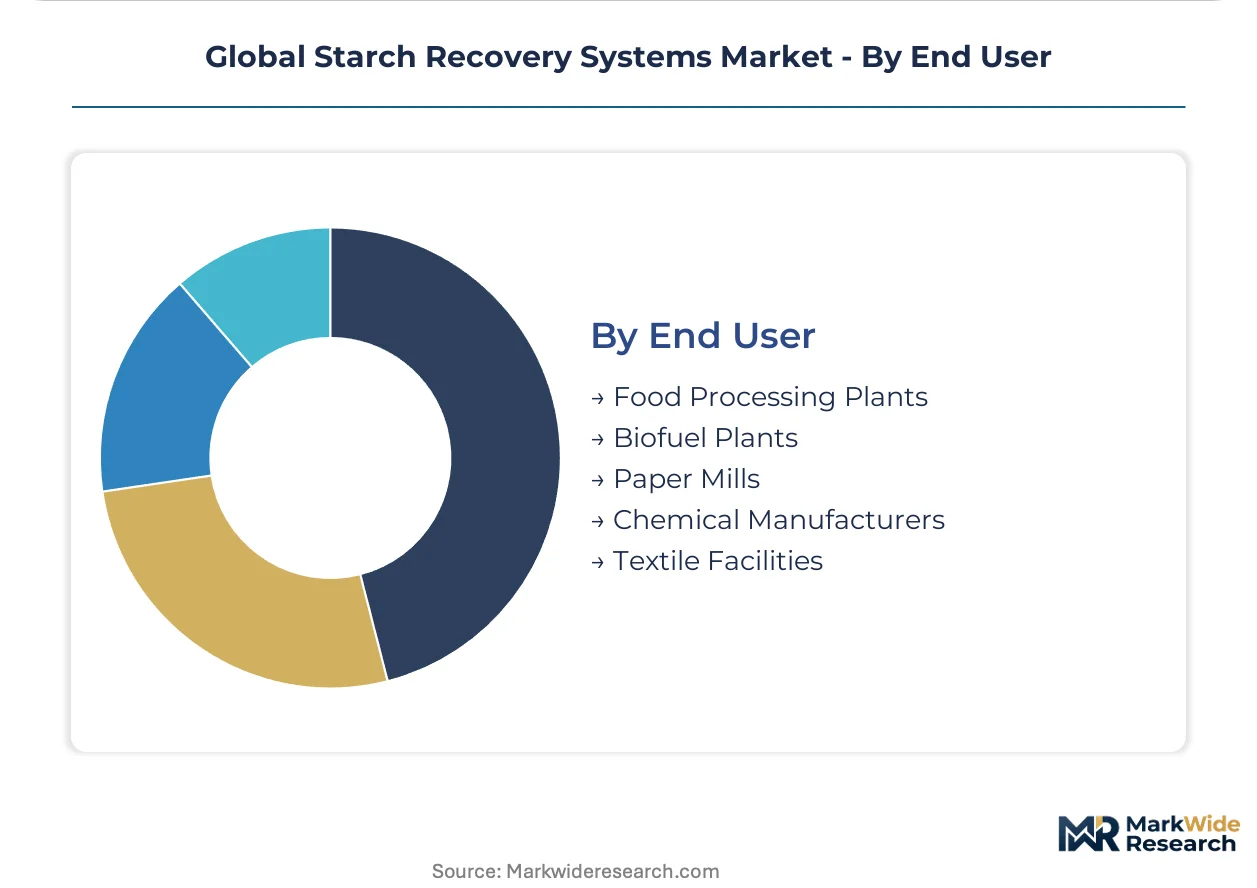
- Food Processing Plants:Install starch recovery systems to comply with stringent wastewater discharge standards from agencies like the U.S. EPA and China's MEE, reducing organic load and operational costs. These facilities include potato, corn, and tapioca processors.
- Biofuel Plants:Implement starch recovery to optimize feedstock utilization and enhance profitability, particularly in the expanding bioethanol industry in Brazil and the United States. They prioritize high-capacity, continuous systems for uninterrupted operation.
- Paper Mills:Integrate starch recovery to recycle starch used in paper production, improving resource efficiency and reducing effluent treatment expenses.
- Chemical Manufacturers:Utilize recovered starch as a raw material for various industrial chemicals, finding value in its polymeric structure.
- Textile Facilities:Employ starch recovery systems to manage wastewater from sizing operations, ensuring compliance with environmental regulations and reducing material loss.
Regulatory compliance and economic valorization are primary motivators for end-user investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between established markets like Germany and rapidly industrializing regions such as Brazil. This disparity influences investment decisions for starch recovery systems. Demand patterns vary significantly across key geographical areas, driven by local regulatory frameworks and specific industrial applications.
Brazil
Demand in Brazil is primarily driven by the expansive sugarcane processing industry, which requires efficient starch separation for bioethanol production. Strict environmental regulations from agencies like ANVISA compel processors to manage wastewater effectively. The São Paulo region, a hub for bioethanol production, shows high adoption rates for continuous starch recovery systems.
United States
The United States market sees significant demand from the corn ethanol sector and large food processing plants. U.S. EPA wastewater discharge standards mandate the reduction of organic load, creating a compliance-driven need for these systems. The Midwest corn belt, with its concentration of ethanol facilities, represents a major market for high-capacity recovery solutions.
China
China's market is propelled by efforts to modernize its food processing sector and reduce industrial wastewater pollution. The Ministry of Ecology and Environment (MEE) enforces stringent environmental protection laws, pushing companies towards recovery technologies. Industrial clusters in the Yangtze River Delta actively invest in advanced systems to meet these evolving standards.
India
India presents a significant growth opportunity due to government initiatives aimed at modernizing the food processing industry and valorizing byproducts. The Production Linked Incentive (PLI) scheme encourages capital investment in efficiency-enhancing technologies, supporting starch recovery system adoption. Food processing hubs in Maharashtra are increasingly implementing these systems to reduce waste and improve resource utilization.
Germany
Germany's demand for starch recovery systems stems from its advanced potato and wheat processing industries, coupled with strong circular economy mandates. The EU Green Deal incentivizes food manufacturers to minimize waste and valorize side streams. Processors in North Rhine-Westphalia, a key industrial region, are upgrading to advanced recovery systems to meet environmental targets and enhance sustainability.
Global Starch Recovery Systems Market Key Industry Players
Global engineering conglomerates and specialized processing equipment manufacturers split the starch recovery systems market. The market exhibits a tiered structure, with large multinational players offering integrated solutions and smaller, specialized firms focusing on niche technologies. Strategic partnerships and technology licensing agreements represent dominant competitive moves among market participants.
Among the global engineering conglomerates, GEA Group and Alfa Laval exemplify providers offering extensive service networks and advanced separation technologies. ANDRITZ, another prominent player, occupies a position specializing in complete plant solutions for complex starch processing operations. These companies anchor the high-capacity segment, catering to large-scale industrial applications.
| Leading Market Players |
|---|
| GEA Group |
| Alfa Laval |
| ANDRITZ |
| Flottweg SE |
| Larsson Sweden |
| Microtec Engineering Group |
| Myande Group |
| Nivobahovex |
| SiccaDania |
| Others |
Cost & Logistics Intelligence
Commodity volatility in raw materials like corn and potatoes determines both pricing tier spreads for starch recovery systems and the supply chain shape for specialized components. This volatility directly impacts operational cost-benefit analyses for end-users.
Pricing Analysis
Configured-to-order pricing for starch recovery systems commands a premium over standard, off-the-shelf units. The dominant pricing structure is project-based, reflecting the custom engineering required for integration into existing food processing lines. Price differentiation stems from the level of automation and after-sales service contracts. Pricing softness affects standard filtration units due to increased competition from regional manufacturers. Bioethanol plants and large food processors exhibit lower price sensitivity for high-capacity, integrated solutions.
Supply Chain Analysis
Export controls on advanced separation technologies limit the flow of high-performance decanter centrifuges to certain regions. Supply concentration for specialized components like high-speed centrifuges and precision membranes centers in Germany, Sweden, and Japan. Raw material dependencies include stainless steel alloys and specific polymers for food-contact parts. A structural risk is the single-source vulnerability for advanced sensor arrays. Distribution runs through direct sales channels from equipment manufacturers, often bypassing regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The starch recovery systems market presents a significant service-attach opportunity. Recurring revenue from optimization software and preventative maintenance contracts is expanding faster than new equipment sales, driven by end-user demand for guaranteed uptime and efficiency.
For Market Incumbents:Entrench market leadership by expanding comprehensive service networks, particularly in high-growth regions like Brazil and India. Invest in advanced process automation R&D to counter emerging membrane technology threats from specialized firms. Deepen vertical integration into specialized component manufacturing to mitigate supply chain disruptions. This defends against margin pressure from commoditized filtration units.
For New Entrants and Emerging Players:Build out niche capabilities in membrane separation technologies for smaller-scale operations in Southeast Asia's tapioca processing sector. Target underpenetrated artisanal producers with lower-capex, compact footprint solutions. A strong go-to-market angle involves offering modular systems with flexible financing options. This addresses the high capital investment restraint for SMEs.
For Investors and Strategic Acquirers:The EU Green Deal reshapes the acquisition landscape, favoring companies with proven circular economy technologies. Long-term viability for starch recovery system providers is strong, driven by persistent wastewater regulations and bioethanol expansion. Target mid-sized specialists possessing proprietary membrane or advanced sensor integration capabilities. Material shifts in global carbon pricing would require updated calibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Driven Optimization Software | Enhances system efficiency and reduces energy consumption for large-scale processors. |
| Expand Service Network in Brazil | Guarantees uptime for critical bioethanol production facilities, securing long-term contracts. |
| Acquire Membrane Technology Specialist | Diversifies product portfolio, addressing smaller-scale and niche application demands. |
| Form Joint Venture for Protein Co-Recovery | Unlocks new high-value revenue streams in plant-based food processing. |
| Invest in Sustainable Material R&D | Ensures compliance with evolving food-contact material regulations and reduces environmental footprint. |
Research Approach
The analysis maps starch recovery systems across food processing, bioethanol production, and textile manufacturing, each validated through extensive primary interviews. Stakeholders included plant managers, process engineers, procurement leads, and environmental compliance officers. Secondary data sources comprised U.S. EPA and China MEE regulatory reports, academic research on starch valorization, and industry association publications. Bottom-up data collection was triangulated with top-down market sizing.
The forecast framework assumes stable regulatory enforcement across the analysis window, while varying feedstock availability and energy prices. Segmentation dimensions modeled include system type, technology, application sector, end-user, and regional demand. Compound annual growth rates were derived from historical trends and projected adoption rates. Key forecast inputs were bioethanol production capacities and food processing wastewater volumes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by disruptive technology developers or major regulatory shifts would shift outcomes. Forecasts reflect assumptions regarding technological evolution and market adoption rates. Material shifts in global trade policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Semi-Auto Egg Tart Forming Machine Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Commercial Tunnel Oven Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Wine Bottling Machine Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Kebab Machine Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Soda Production Machine Market
Food Processing Equipment
Global Conveyor Oven Market