
 2'-Fucosyllactose (2'-FL) Market | 2026-2036
2'-Fucosyllactose (2'-FL) Market Size, Share, and Industry Trends Forecast 2026-2036
2'-Fucosyllactose (2'-FL) Market Insights
Market Context with Strategic Players
Specialized microbial fermentation talent is rotating toward precision biomanufacturing hubs across Europe and North America, tightening labor availability for conventional pharmaceutical glycosylation. Jennewein Biotechnologie GmbH leverages its proprietary bacterial cell factory platform to dominate pharmaceutical-grade 2'-FL supply chains. Glycom A/S anchors the Nordic region's oligosaccharide research corridor through integrated strain development and purification capabilities. DuPont Nutrition & Biosciences competes on manufacturing scale, operating multi-ton fermentation capacity that extends cost advantages in infant formula ingredient markets.
Technical Definition and Structural Segments
2'-Fucosyllactose is a trisaccharide human milk oligosaccharide composed of L-fucose, D-galactose, and D-glucose linked through specific alpha-1,2 and beta-1,4 glycosidic bonds, manufactured primarily via recombinant microbial fermentation using engineered Escherichia coli or yeast strains. Its primary commercial purpose centers on infant nutrition, where 2'-FL mimics bioactive glycan structures present in human breast milk to support gut microbiome colonization and immune modulation in formula-fed infants. Powder formulations lead volume shipments due to superior stability in dry-blend infant formula manufacturing, while liquid concentrates capture margin pools in ready-to-feed premium product lines. The infant end-user segment sustains the dominant revenue share, though adult dietary supplement applications are expanding fastest as gut-brain axis research validates postbiotic mechanisms.
Regulatory Frame and Forward-Looking Close
EFSA novel food authorizations and FDA GRAS notifications constitute the dual regulatory gateway for 2'-FL commercialization, with China's NMPA food ingredient registrations emerging as a third critical access threshold for Asia-Pacific market entry. REACH compliance and FSMA preventive controls further shape manufacturing location decisions, as European and American regulators impose divergent purity and contaminant specifications on fermentation-derived oligosaccharides. Stakeholders must monitor evolving novel food harmonization between EU member states and China's expanding human milk oligosaccharide positive list to anticipate supply chain reconfiguration.
Market Dynamics
Microbial fermentation scale-up economics are compressing unit costs for 2'-FL faster than purification bottlenecks can resolve, creating margin pressure on early movers while opening volume tiers for mid-scale entrants.
Growth Catalysts
- FDA GRAS pathway:Streamlined notifications for human milk oligosaccharides in infant formula accelerate brand incorporation timelines and reduce regulatory uncertainty for US manufacturers.
- Precision fermentation advances:Engineered yeast and bacterial cell factories achieve titers above 20 grams per liter, collapsing cost curves that previously limited commercial viability.
- Gut-brain axis research:Clinical validation of postbiotic mechanisms drives adult dietary supplement demand beyond traditional infant nutrition applications.
Market Restraints
- Purification cost concentration:Chromatographic separation and membrane filtration account for 40-60 percent of production costs, with resin and solvent supply concentrated among German and Japanese specialty chemical suppliers.
- EFSA novel food heterogeneity:Divergent national implementation timelines across EU member states fragment market access and delay pan-European product launches.
- Plant-based oligosaccharide substitutes:Galactooligosaccharides from lactose hydrolysis compete on price in standard infant formula segments where HMO mimicry is not clinically differentiated.
Strategic Opportunities
- China NMPA registration:First-mover approvals under expanded human milk oligosaccharide positive lists unlock access to the world's largest infant formula market.
- Ready-to-feed liquid concentrates:Premium convenience formats command margin premiums in urban US and Western European markets where time-constrained parents dominate.
- Continuous fermentation integration:Coupling cell retention perfusion systems with real-time metabolite monitoring collapses batch variability and enables contract manufacturing scale.
Industry Challenges
- Glycobiology talent scarcity:Specialized expertise in oligosaccharide analytical characterization and regulatory dossier preparation concentrates in Danish and German research clusters, constraining global expansion.
- Multi-jurisdiction dossier complexity:Simultaneous FDA GRAS, EFSA novel food, and NMPA submissions require distinct toxicology packages and strain documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2'-Fucosyllactose (2'-FL) Market |
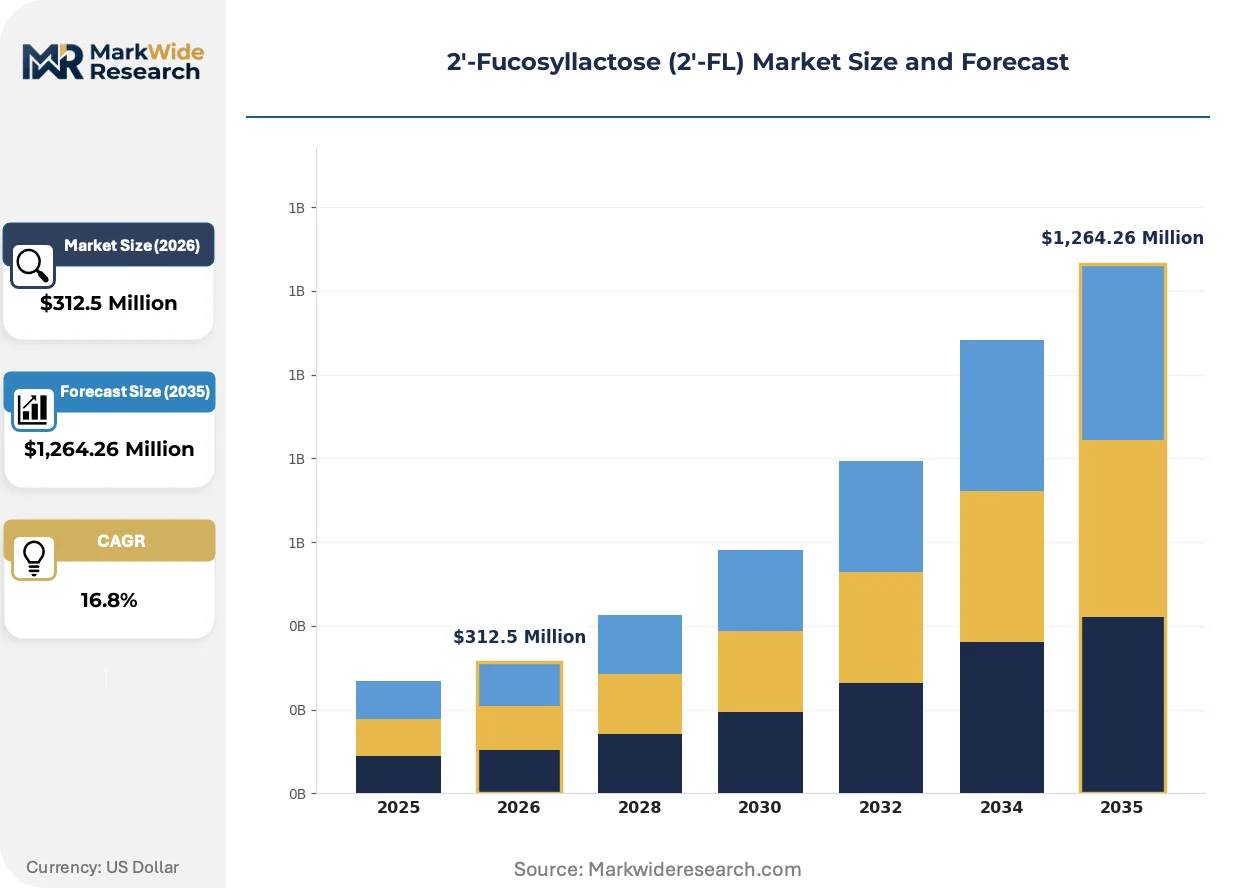
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,264.26 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Granules End User: Infants, Adults, Elderly, Pregnant Women Application: Food & Beverage, Pharmaceuticals, Dietary Supplements, Infant Formula Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Jennewein Biotechnologie GmbH, Glycom A/S, DuPont Nutrition & Biosciences, FrieslandCampina Ingredients, Chr. Hansen Holding A/S, BASF SE, Inbiose NV, Abbott Laboratories, ZuChem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2'-Fucosyllactose (2'-FL) Market Trends and Innovations
Bioprocess intensification and regulatory harmonization efforts are restructuring competitive advantage around manufacturing yield and multi-market approval velocity rather than patent-protected strain ownership alone.
Continuous perfusion fermentation with cell retention devices is decomposing the traditional fed-batch paradigm that dominated first-generation 2'-FL production. Contract manufacturers in the Netherlands and Singapore are adopting these systems to serve multiple brand customers from single facilities. The technology is decomposing capital intensity barriers that previously protected integrated specialists.
EFSA's streamlined novel food assessment procedure for microbial fermentation ingredients compresses evaluation timelines for well-characterized production organisms. This regulatory efficiency reduces time-to-revenue for second-generation entrants using platform chassis strains. Infant formula manufacturers in Germany and Denmark are prioritizing suppliers with existing EFSA approvals to de-risk supply continuity.
Brand procurement teams are consolidating supplier relationships around dual-sourced fermentation capacity with redundant geographic coverage. Long-term offtake agreements with minimum volume guarantees replace spot purchasing in premium infant nutrition segments. This concentration is most visible in the United States, where FDA GRAS status has become a non-negotiable qualification criterion.
2'-Fucosyllactose (2'-FL) Market Segmentation
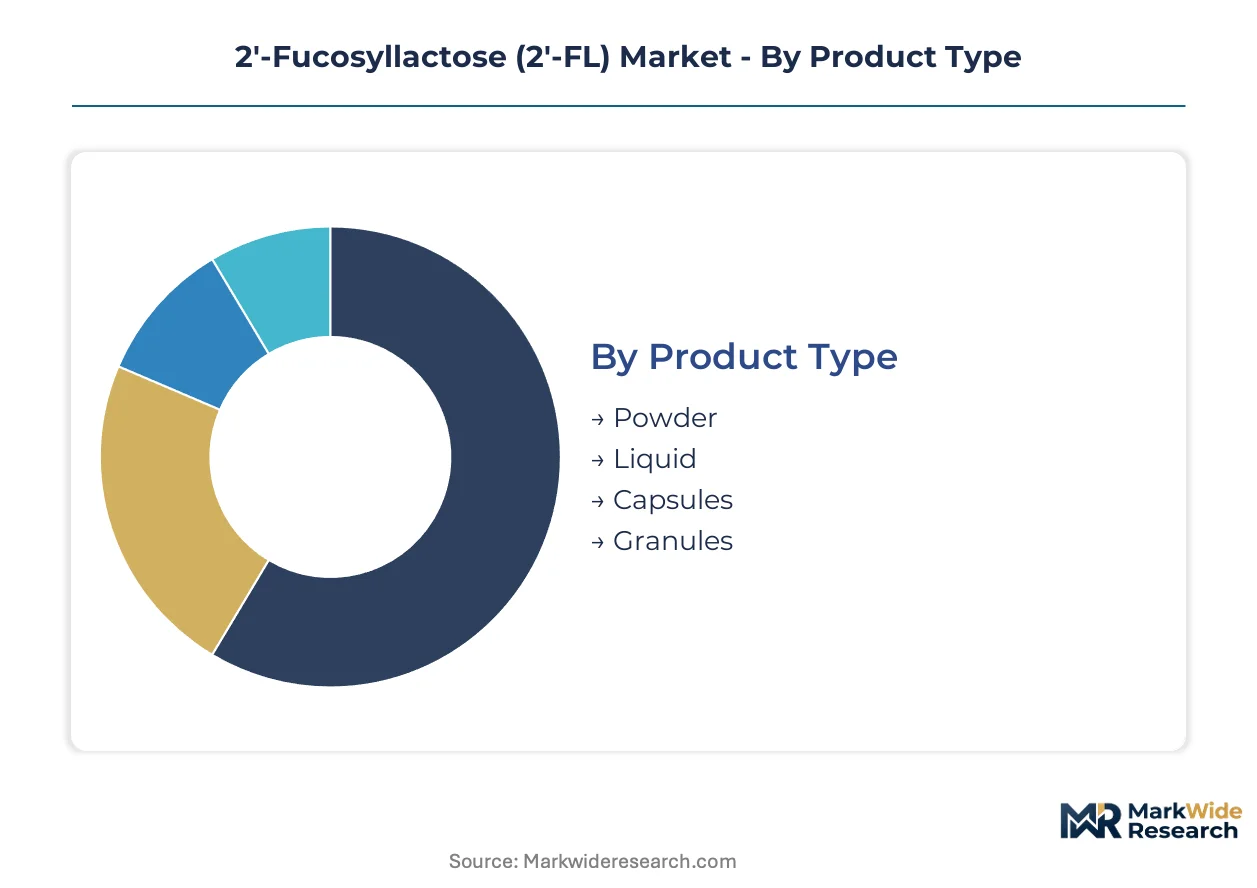
Segmentation in the 2'-FL market reveals how manufacturing constraints and regulatory pathways create divergent margin structures across product formats and end-use categories. Powder formulations dominate volume economics while liquid concentrates capture premium positioning in convenience-driven channels.
Product Type:
Margin pools concentrate in dry-blend formats where stability advantages reduce cold-chain logistics costs, while liquid concentrates command formulation premiums in ready-to-feed applications.
- Powder:Spray-dried crystalline 2'-FL with moisture content below 5% enables ambient storage and bulk blending into infant formula matrices. Dry-blend manufacturers in Germany and Denmark prioritize powder specifications to minimize downstream processing complexity and extend shelf life.
- Liquid:Aqueous concentrates at 20-30% solids content require sterile filling and refrigerated distribution but eliminate reconstitution steps for ready-to-feed infant nutrition products. Urban US parents in time-constrained households drive demand concentration for liquid convenience formats.
- Capsules:Encapsulated 2'-FL for adult dietary supplement applications targets gut-brain axis positioning with standardized dosing precision.
- Granules:Agglomerated particles for direct compression into chewable formats serve pediatric and geriatric compliance segments.
Powder holds installed capacity. Liquid is rotating up the share rankings.
End User:
Application intensity varies sharply across life stages, with neonatal nutrition commanding the strictest purity specifications and adult wellness segments permitting broader formulation flexibility.
- Infants:Formula-fed neonates represent the core clinical validation target for 2'-FL, with bioactive glycan mimicry supporting Bifidobacterium colonization and immune tolerance development. FDA GRAS notifications specifically address infant safety thresholds, creating regulatory moats around this segment.
- Adults:Postbiotic mechanisms in gut-brain axis research are expanding fastest among health-conscious consumers seeking microbiome modulation beyond basic fiber supplementation. NMPA food ingredient registrations in China increasingly cover adult-targeted HMO formulations.
- Elderly:Immunosenescence applications leverage 2'-FL's pathogen decoy function to address infection susceptibility in aging populations.
- Pregnant Women:Prenatal microbiome transfer hypotheses drive niche positioning in maternal health portfolios.
Infants anchor manufacturing investments. Adults are gaining share fastest.
Application:
Regulatory pathway complexity creates tiered entry barriers, with infant formula requiring the most extensive toxicology dossiers and dietary supplements permitting swifter market access.
- Infant Formula:The primary commercial purpose centers on mimicking human milk oligosaccharide profiles in formula-fed neonates, with EFSA novel food authorizations and FDA GRAS notifications constituting dual gateway requirements. Brand manufacturers consolidate supplier relationships around dual-sourced fermentation capacity with redundant geographic coverage.
- Dietary Supplements:Gut-brain axis research validates postbiotic positioning for adult microbiome support, with less stringent purity specifications than infant applications enabling faster formulation iteration. Chinese biotech firms target this segment for initial NMPA registration before advancing to infant-grade approvals.
- Food & Beverage:Functional dairy and beverage applications leverage 2'-FL's clean-label appeal for digestive health positioning in premium consumer products.
- Pharmaceuticals:Drug-device combinations and medical nutrition products explore 2'-FL as an active pharmaceutical ingredient for targeted therapeutic indications.
Infant Formula commands qualification timelines. Dietary Supplements show the steepest expansion trajectory.
Distribution Channel:
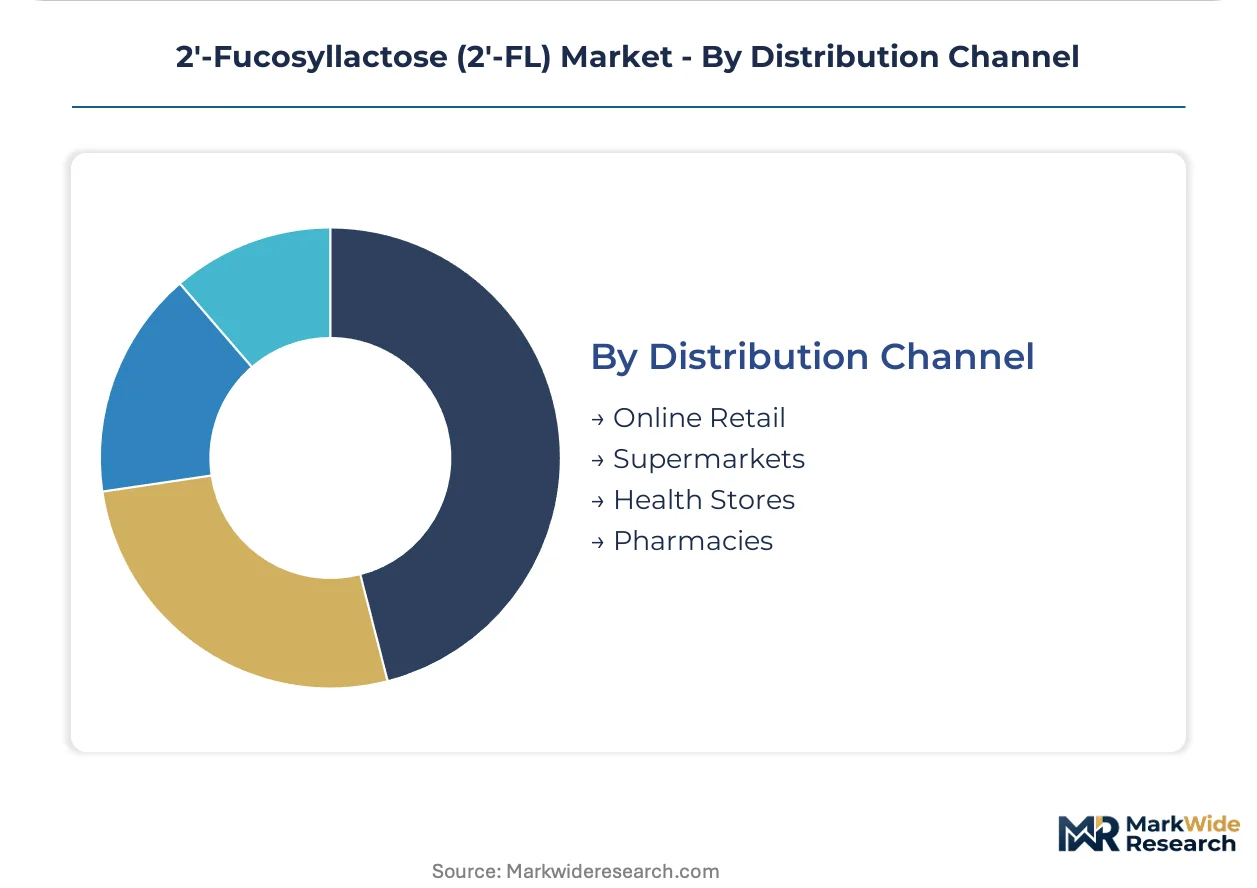
Channel economics reflect customer acquisition costs and regulatory oversight intensity, with pharmacy and health store formats justifying premium pricing through professional recommendation leverage.
- Pharmacies:Professional recommendation channels dominate infant formula sales in Germany and Denmark, where pharmacists influence brand selection for first-time parents. EFSA novel food approval status serves as a trust signal in this consultation-intensive environment.
- Online Retail:Direct-to-consumer platforms enable subscription models for adult dietary supplement replenishment, with Chinese e-commerce ecosystems particularly advanced in HMO ingredient education and cross-border purchasing.
- Supermarkets:Mass-market retail captures standard infant formula volumes where price competition with galactooligosaccharide substitutes limits HMO penetration.
- Health Stores:Specialty retailers target educated consumers seeking premium microbiome support products with transparent supply chain documentation.
Pharmacies hold recommendation authority. Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA GRAS notifications anchor United States demand, while EFSA novel food authorizations and China's NMPA registrations shape access across the two other major consumption centers. Production clusters concentrate where precision fermentation talent and regulatory expertise overlap.
United States
Urban parents in time-constrained households drive ready-to-feed infant formula demand. FDA GRAS notifications for 2'-FL accelerate brand incorporation timelines. Greater Boston hosts contract manufacturing facilities serving multiple infant nutrition brands.
Germany
Pharmacist recommendation channels dominate first-time parent purchasing decisions. EFSA novel food approvals streamline ingredient access for domestic formula manufacturers. North Rhine-Westphalia anchors the country's oligosaccharide research corridor with integrated strain development capabilities.
Denmark
High breastfeeding-to-formula transition rates sustain premium HMO incorporation. EFSA novel food harmonization reduces pan-European launch fragmentation. Copenhagen's precision biomanufacturing hub attracts specialized glycobiology talent from across Scandinavia.
China
Expanding middle-class parents seek premium infant nutrition with clinically validated ingredients. NMPA food ingredient registrations under expanded HMO positive lists unlock market access. Yangtze River Delta biotech firms advance microbial fermentation scale-up economics.
Netherlands
Contract manufacturers serve multiple brand customers from single facilities using continuous perfusion systems. REACH compliance shapes purity specifications for fermentation-derived oligosaccharides. Rotterdam's logistics infrastructure supports cold-chain distribution of liquid concentrate formats.
2'-Fucosyllactose (2'-FL) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated specialists with proprietary bacterial cell factory platforms compete against scale-driven multi-ton fermentation operators. The market consolidates around three strategic archetypes: precision fermentation technology owners, contract manufacturing scale players, and diversified nutrition ingredient portfolios. Dominant competitive moves include long-term offtake agreements with minimum volume guarantees and dual-sourced capacity redundancy.
Among German biotechnology specialists, Jennewein Biotechnologie GmbH exemplifies the integrated precision fermentation archetype. Danish firm Glycom A/S occupies a position within the Nordic oligosaccharide research cluster. DuPont Nutrition & Biosciences represents the scale-driven manufacturing tier with multi-ton fermentation infrastructure.
| Leading Market Players |
|---|
| Jennewein Biotechnologie GmbH |
| Glycom A/S |
| DuPont Nutrition & Biosciences |
| FrieslandCampina Ingredients |
| Chr. Hansen Holding A/S |
| BASF SE |
| Inbiose NV |
| Abbott Laboratories |
| ZuChem Inc. |
| Others |
Pricing and Supply Chain Analysis
Galactooligosaccharide substitution in standard infant formula segments is compressing 2'-FL pricing premiums while simultaneously shifting procurement gravity toward Chinese fermentation scale-ups and European precision biomanufacturing hubs. This input displacement dynamic rewards suppliers with integrated strain platforms and penalizes those dependent on batch-fed legacy processes.
Pricing Analysis
Transatlantic price spreads between FDA GRAS-qualified US supply and EFSA-authorized European product are narrowing as Chinese biotech firms enter with NMPA-registered alternatives. Pricing stratifies across pharmaceutical-grade, infant-nutrition-grade, and dietary-supplement-grade tiers, with certification tier and volume scale as primary differentiation drivers. Cost compression in powder formats is intensifying because microbial fermentation titers above 20 grams per liter are collapsing unit economics. Mass-market infant formula manufacturers exhibit highest price sensitivity, while ready-to-feed premium brands show lowest.
Supply Chain Analysis
Chromatographic resin inventories and membrane filtration lead times are extending to 12-16 weeks, constraining just-in-time procurement for mid-scale entrants. Supply concentrates in Germany, Denmark, and China, with German and Japanese specialty chemical suppliers dominating purification consumables. Raw material dependencies span engineered yeast strains, bacterial cell factory chassis, and pharmaceutical-grade L-fucose. Single-source vulnerability in chromatographic resin supply creates structural risk. Distribution runs through long-term offtake agreements with minimum volume guarantees rather than spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 2'-FL market is recovering from a cyclical trough as precision fermentation titers cross economic viability thresholds and regulatory approval pipelines clear post-pandemic backlogs. This cyclical upswing favors capitalized players with existing dossier approvals.
For Market Incumbents: Compound regulatory moats by accelerating EFSA novel food harmonization across EU member states and securing redundant NMPA registrations before second-generation entrants achieve scale. Threats from plant-based oligosaccharide substitutes in price-sensitive segments demand backward integration into continuous perfusion fermentation capacity in the Netherlands or Singapore to defend cost position. For New Entrants and Emerging Players: FDA GRAS notification fast-tracks offer the most penetrable regulatory pathway for initial market entry, particularly for adult dietary supplement applications where toxicology requirements are less stringent than infant formula. White-space targets include ready-to-feed liquid concentrate formats in urban US markets and gut-brain axis positioning for health-conscious Chinese consumers. A contract manufacturing partnership with established precision biomanufacturing hubs enables asset-light scaling before captive capacity investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation specialists holding proprietary bacterial cell factory platforms but lacking multi-ton manufacturing scale. Long-term viability hinges on 5-10 year regulatory harmonization between EFSA and NMPA frameworks. The signal to watch is consolidation of supplier relationships by major infant formula brands around dual-sourced capacity with redundant geographic coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Perfusion Fermentation Adoption | Cell retention systems with real-time metabolite monitoring collapse batch variability for contract manufacturers. |
| Dual-Jurisdiction Dossier Filing | Simultaneous FDA GRAS and EFSA novel food submissions compress time-to-revenue across Atlantic markets. |
| Long-Term Offtake Agreement Negotiation | Minimum volume guarantees with infant formula brands secure capacity utilization and financing for scale-up. |
| Purification Technology Backward Integration | In-house chromatographic resin regeneration reduces dependency on German and Japanese specialty chemical suppliers. |
| Adult Dietary Supplement Line Extension | Gut-brain axis positioning leverages postbiotic research to access faster NMPA registration pathways in China. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with precision fermentation scientists, infant formula procurement directors, regulatory affairs specialists, and glycobiology analytical chemists; and secondary validation against FDA GRAS notifications, EFSA novel food opinions, NMPA food ingredient registrations, and customs trade data for fermentation-derived oligosaccharides. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates.
Across the projection horizon, the analytical framework segmented by product format, end-user life stage, application regulatory pathway, and geographic approval cluster. CAGRs derived from fermentation titer improvement curves, regulatory approval velocity, and brand incorporation timelines. Industry-specific forecast inputs included EFSA streamlined assessment procedure adoption rates and Chinese biotech firm capacity buildout announcements.
The analysis sits within stated boundaries; outcomes outside sustained precision fermentation yield improvements or regulatory harmonization delays would require recalibration. Forecasts reflect documented assumptions about strain platform maturation and approval pipeline clearance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Seaweed Derivatives Market
Ingredients
Dairy Ingredients Market
Ingredients
Jasmine Extract Market
Ingredients
Aroma Ingredients Market
Ingredients
Pine Needle Oil Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Starch Market
Ingredients
Virginiamycin Market
Ingredients
Xylooligosaccharide Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Baking Ingredients Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Starches/Glucose Market