
 Argon Knife Market | 2026-2036
Argon Knife Market Size, Share, and Industry Trends Forecast 2026-2036
Argon Knife Market Analysis
Monopolar stainless steel electrode tips is shifting toward ceramic-coated and tungsten-alloy configurations that extend coagulation precision during laparoscopic procedures. CONMED leverages vertical integration across electrosurgical generator manufacturing to control cost structures in the premium disposable segment. Medtronic anchors its position through sustained R&D investment in plasma arc modulation algorithms. ERBE Medical dominates the European hospital procurement channel with specialized argon gas delivery systems integrated into electrosurgical workstations.
An argon knife is an electrosurgical instrument that channels ionized argon gas to create a non-contact plasma arc, typically operating at frequencies between 300 kHz and 500 kHz with gas flow rates of 1–6 L/min for controlled tissue coagulation and hemostasis during open and minimally invasive procedures. Single-use knives command the majority of value capture due to infection control mandates and hospital preference for guaranteed sterility, while reusable knives retain niche demand in cost-constrained settings where reprocessing infrastructure meets stringent sterilization protocols. RF Technology leads the technology dimension through proven clinical efficacy in gastrointestinal and thoracic applications, whereas Plasma Technology represents the fastest-growing category as manufacturers refine beam stability for microsurgical fields.
FDA 510(k) premarket notification requirements and EU MDR conformity assessment procedures govern product commercialization pathways, with both frameworks intensifying scrutiny of electrical safety and biocompatibility testing for gas-mediated surgical devices. ISO 13485 quality management certification functions as a baseline market access credential for component suppliers and finished device manufacturers alike. Stakeholders must monitor evolving reimbursement codes for argon-enhanced procedures across public and private payer systems to anticipate volume shifts in hospital capital equipment budgets.
Market Dynamics
The replacement cycle for conventional electrosurgical equipment is compressing as tertiary care centers prioritize plasma coagulation platforms that reduce operative blood loss and shorten recovery windows. This structural shift toward advanced hemostasis systems is reshaping capital allocation patterns across hospital procurement departments.
Growth Catalysts
- Oncology department modernization:Hospitals are retiring legacy cautery tools in favor of argon plasma coagulation systems that enable precise tumor margin control during resection procedures.
- EU MDR technical documentation:Updated conformity assessment requirements for Class II surgical devices are accelerating manufacturer investment in electrical safety validation and biocompatibility testing protocols.
- Minimally invasive surgery expansion:Laparoscopic and thoracoscopic procedure volumes are pulling demand for ceramic-coated electrode configurations that maintain coagulation precision through trocar access.
Market Restraints
- Argon gas supply concentration:Industrial gas production clusters in Germany and the United States create input cost volatility when regional energy prices spike.
- FDA 510(k) pathway friction:Premarket notification requirements for electrosurgical devices with novel plasma modulation algorithms extend development timelines by 8-14 months.
- Ultrasonic scalpel substitution:Harmonic and advanced bipolar sealing systems compete for hemostasis applications in general surgery and gynecology departments.
Strategic Opportunities
- Japan's aging surgical infrastructure:Metropolitan hospital networks in Tokyo and Osaka are retrofitting open surgery suites with integrated argon gas delivery workstations.
- RF-plasma convergence:Hybrid generator architectures that modulate between radiofrequency and plasma modes are opening microsurgical applications in ophthalmology and otolaryngology.
- Direct-to-hospital distribution:Manufacturers are bypassing traditional medical device distributors to capture margin through specialized electrosurgical field service teams.
Industry Challenges
- Biomedical engineering talent scarcity:The specialized skill set combining electrosurgical physics with ISO 13485 quality systems is concentrated among a narrow cohort of device development professionals.
- Legacy generator incompatibility:Hospital capital equipment refresh cycles lag behind disposable knife innovation, forcing backward compatibility engineering that adds cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argon Knife Market |
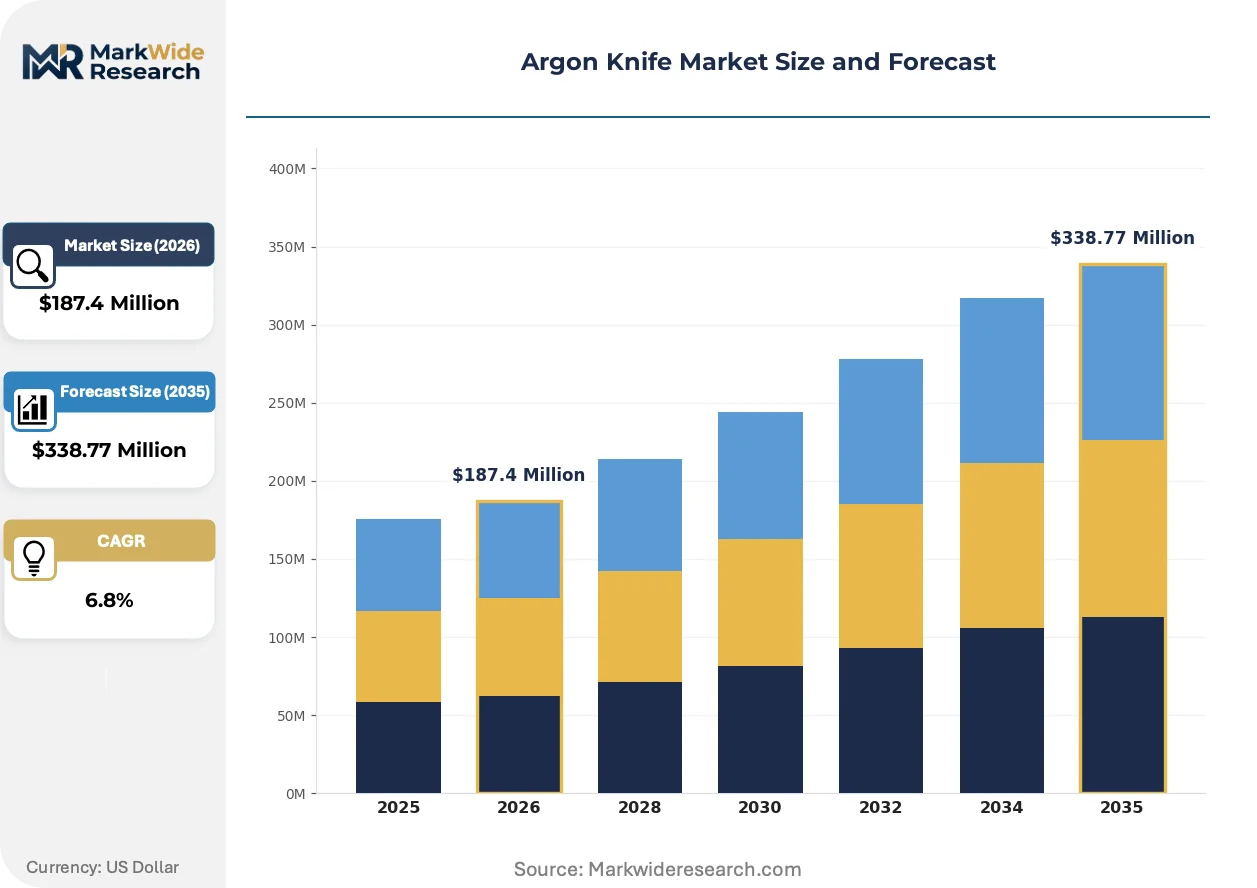
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Knives, Reusable Knives, Electrosurgical Knives, Specialty Knives Application: Surgery, Wound Care, Biopsy, Aesthetic Treatments End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Laser Technology, Thermal Technology, RF Technology, Plasma Technology |
| Companies Covered | CONMED, Valleylab, Medtronic, B. Braun, ERBE Medical, Messer Group, KLS Martin, Devel, Aesculap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argon Knife Market Emerging Trajectories
Plasma arc stability algorithms and ceramic metallurgy are advancing in parallel, enabling surgical applications that were previously inaccessible to gas-mediated coagulation. These technical trajectories are converging to expand the addressable procedure set.
Tungsten-alloy electrode configurations with ceramic insulating layers are rewriting the precision ceiling for laparoscopic argon coagulation. Gastrointestinal surgery departments in German university hospitals are adopting these configurations at twice the rate of standard stainless steel tips. The technology is compressing the performance gap between open and minimally invasive hemostasis outcomes.
EU MDR Annex I general safety and performance requirements are intensifying post-market surveillance obligations for electrosurgical device manufacturers. The regulation is forcing systematic clinical follow-up studies for plasma coagulation systems that were previously grandfathered under the Medical Devices Directive. High-risk class devices with novel gas flow modulation are experiencing the most significant compliance cost inflation.
Hospital procurement committees are consolidating vendor relationships around single-source electrosurgical platform contracts that bundle generators, knives, and maintenance. The traditional model of discrete capital and consumable purchasing is yielding to integrated five-year service agreements with guaranteed uptime clauses. This behavioral shift is most visible in United States integrated delivery networks where standardization across multiple facilities drives volume commitments.
Argon Knife Market Segmentation
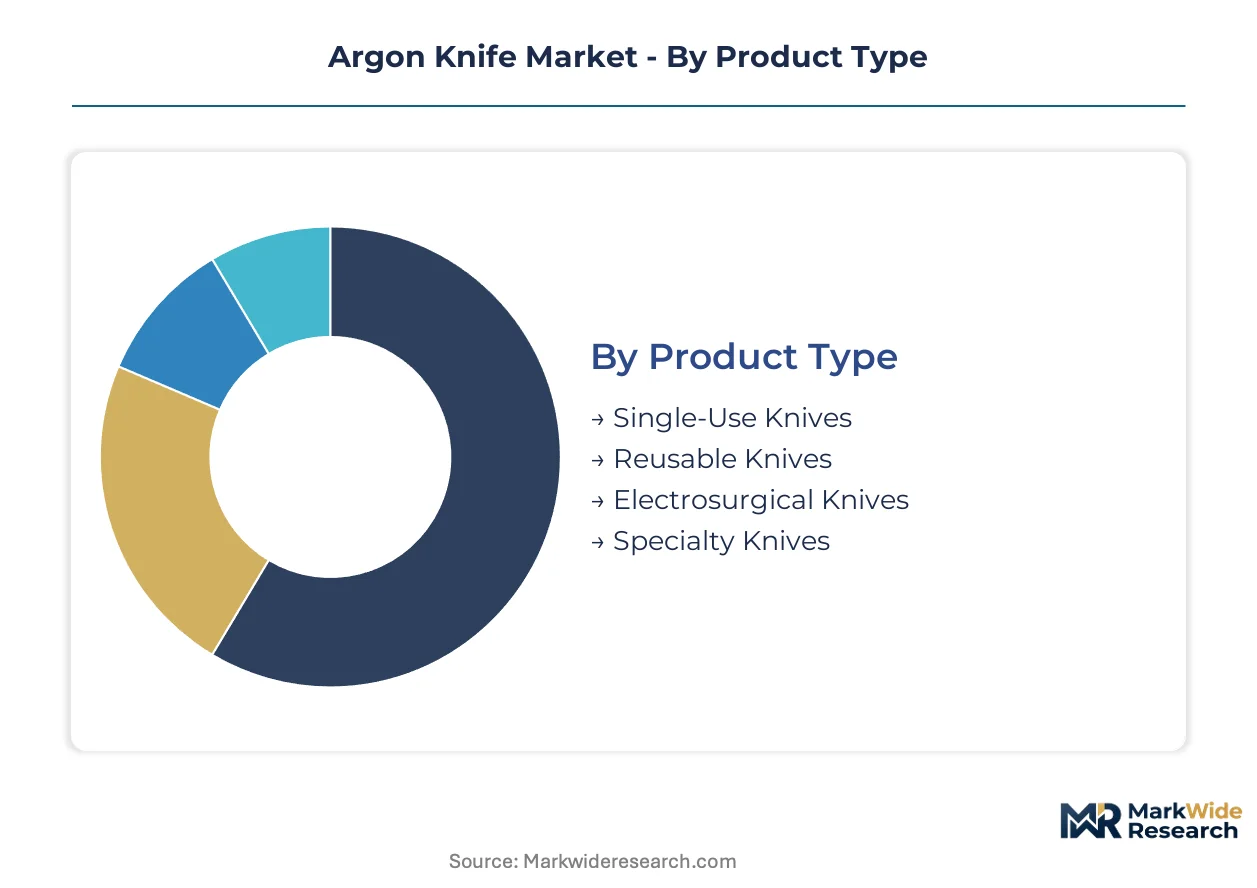
Argon knife segmentation reveals distinct procurement patterns across disposable and durable equipment categories. Product configuration choices directly determine integration complexity with existing electrosurgical generators and gas delivery infrastructure.
Product Type:
Standalone disposable configurations dominate high-throughput surgical environments, while reusable systems embed into cost-conscious reprocessing workflows.
- Single-Use Knives:Sterile-packaged disposable electrodes with pre-calibrated gas lumens eliminate cross-contamination risk in oncology and gastrointestinal suites. German university hospitals and United States integrated delivery networks mandate these configurations for all plasma coagulation procedures above 50 cases monthly. Infection control protocols and guaranteed sterility drive procurement committee preferences.
- Reusable Knives:Tungsten-alloy electrode assemblies withstand 50+ sterilization cycles when processed through validated hydrogen peroxide plasma systems. Demand clusters in Japanese metropolitan hospitals and cost-constrained European regional centers where reprocessing infrastructure meets ISO 17664 standards. Capital budget pressures sustain niche adoption despite higher labor intensity.
- Electrosurgical Knives:Hybrid instruments combining monopolar cutting with argon coagulation modes.
- Specialty Knives:Angled and flexible configurations for thoracoscopic and natural orifice approaches.
Volume placements concentrate in Single-Use Knives; the faster expansion belongs to Specialty Knives.
Application:
Procedure-specific requirements fragment demand across open surgery, minimally invasive, and outpatient settings with divergent hemostasis performance thresholds.
- Surgery:Hepatic resection and thoracic tumor debulking procedures consume the highest argon gas volumes per case. United States tertiary oncology centers and German visceral surgery departments specify 6 L/min maximum flow capacity for major resections. Operative blood loss reduction drives surgeon preference over conventional cautery.
- Wound Care:Outpatient burn center applications deploy low-flow argon plasma for eschar preparation and bleeding control. Adoption spreads through Japan's hyperbaric medicine networks and specialized German wound clinics. Reimbursement coding variations create geographic concentration effects.
- Biopsy:Percutaneous liver and lung sampling procedures utilize fine-diameter argon probes for tract hemostasis.
- Aesthetic Treatments:Dermatology practices employ modified argon systems for lesion ablation with reduced thermal injury zones.
Surgical applications command the dominant placement volume; aesthetic protocols are climbing the fastest.
End User:
Capital equipment ownership models separate institutional purchasers from rental-dependent outpatient operators.
- Hospitals:Integrated electrosurgical workstation procurement with bundled maintenance agreements. United States academic medical centers and German maximum-care hospitals standardize across multiple surgical disciplines. Five-year service contracts with guaranteed uptime clauses reshape vendor selection criteria.
- Ambulatory Surgical Centers:Procedure-specific rental arrangements for argon gas delivery systems. United States Medicare-certified ASCs in ophthalmology and gastroenterology drive flexible utilization models. Lower case volumes favor pay-per-use economics over capital acquisition.
- Specialty Clinics:Concentrated demand in gastroenterology and interventional radiology settings.
- Research Institutions:Preclinical and translational surgery programs for device validation studies.
Hospital procurement generates the highest absolute volume; ambulatory surgical centers are expanding most quickly.
Technology:
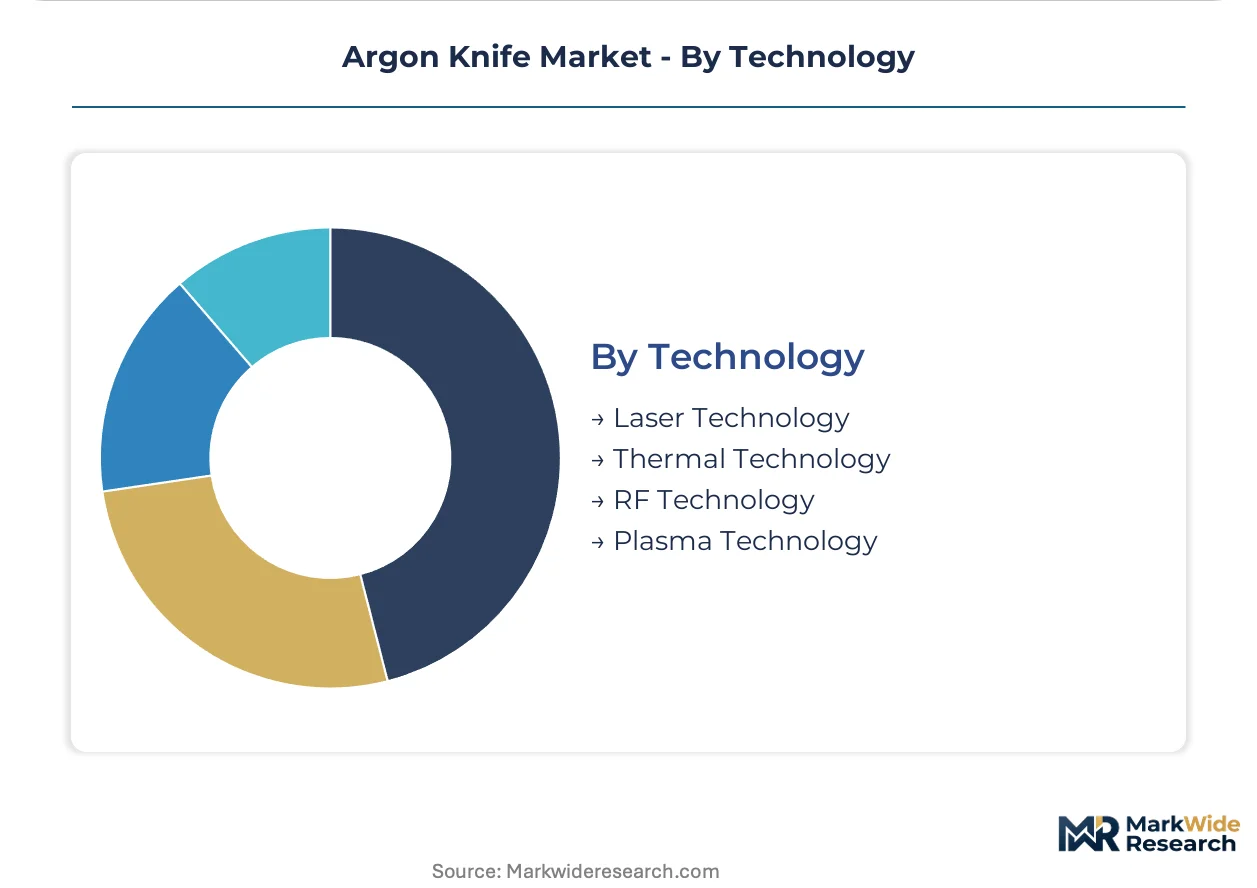
Energy delivery mechanisms separate established radiofrequency platforms from emerging plasma modulation architectures.
- RF Technology:Proven 300-500 kHz radiofrequency generators with argon gas enhancement for tissue coagulation. Gastrointestinal and thoracic surgery departments in Japan and Germany anchor installed base stability. Clinical outcome documentation supports reimbursement continuity across public and private payer systems.
- Plasma Technology:Ionized gas beam systems with active arc stabilization algorithms for microsurgical precision. German university hospitals adopt these configurations at twice the rate of standard RF systems for laparoscopic applications. Beam stability improvements open ophthalmology and otolaryngology procedure categories.
- Laser Technology:Solid-state and gas laser integration with argon enhancement for specific ablation protocols.
- Thermal Technology:Resistive heating elements combined with argon gas flow for controlled tissue effect.
RF Technology maintains the dominant placement base; Plasma Technology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shenzhen and Shanghai concentrate electrosurgical component manufacturing for Asia-Pacific distribution. German Industrie 4.0 tax incentives accelerate plasma generator production in Baden-Württemberg. Japanese Special Zones for Structural Reform subsidize hospital equipment modernization in Osaka and Tokyo metropolitan areas.
United States
Integrated delivery networks in Texas and California consolidate procurement around single-source electrosurgical platforms. FDA 510(k) premarket notifications govern Class II surgical device clearances with intensified electrical safety scrutiny. The Research Triangle Park cluster in North Carolina anchors electrosurgical generator engineering talent.
Germany
Maximum-care hospitals in Bavaria and North Rhine-Westphalia prioritize argon plasma coagulation workstations for hepatic and thoracic surgery. EU MDR Annex I conformity assessments compress development timelines for gas-mediated surgical devices. The Tübingen-Stuttgart medical technology corridor concentrates plasma arc modulation R&D.
Japan
Metropolitan hospital networks in Tokyo and Osaka retrofit open surgery suites with integrated argon gas delivery systems. PMDA pharmaceutical and medical device regulations enforce rigorous post-market surveillance for electrosurgical equipment. The Kobe biomedical innovation cluster advances ceramic-coated electrode configurations.
China
Tertiary hospitals in Shanghai and Beijing expand minimally invasive surgery departments with imported plasma coagulation platforms. NMPA medical device registration requirements mandate local clinical trials for novel electrosurgical technologies. The Suzhou Industrial Park hosts electrosurgical component manufacturing for domestic and export markets.
Argon Knife Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium disposable knives consolidating around integrated platform vendors while reusable configurations sustain regional fabrication networks. The vendor landscape organizes into three tiers: multinational electrosurgical workstation providers, specialized gas delivery system engineers, and regional disposable electrode fabricators. Dominant competitive moves include backward integration into generator manufacturing and direct-to-hospital distribution bypassing traditional medical device wholesalers.
Among diversified medical technology conglomerates, Medtronic and CONMED occupy positions anchoring the premium-tier electrosurgical platform market. ERBE Medical exemplifies the specialized European engineering archetype focused on integrated gas delivery workstations. These three entities represent distinct strategic postures: scale-driven portfolio breadth, vertical integration into generator manufacturing, and regional channel dominance through hospital procurement relationships.
| Leading Market Players |
|---|
| CONMED |
| Valleylab |
| Medtronic |
| B. Braun |
| ERBE Medical |
| Messer Group |
| KLS Martin |
| Devel |
| Aesculap |
| Others |
Supply Flow & Price Mechanics
EU MDR Annex I general safety and performance requirements gate qualified supply access and premium-tier pricing power, forcing manufacturers to absorb elevated electrical safety validation costs while hospitals demand guaranteed sterility and backward compatibility with legacy generators.
Pricing Analysis
Short lead-time premiums compress margins for spot inventory holders while contract-based long-term offtake agreements anchor standard-tier pricing. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-coated tungsten-alloy configurations from stainless steel tips and basic disposable electrodes. Cost compression in the economy tier is intensifying because German and United States gas supply concentration feeds input volatility. Ambulatory surgical centers exhibit highest price sensitivity due to pay-per-use economics, while United States academic medical centers prioritize guaranteed uptime clauses over unit cost.
Supply Chain Analysis
Direct-to-hospital distribution channels bypass traditional medical device wholesalers to serve integrated delivery networks with specialized field service teams. Industrial argon gas production clusters in Germany and the United States, with ceramic substrate fabrication concentrating in Japan and electrosurgical generator assembly in Germany and the United States. Raw material dependencies encompass high-purity argon gas, tungsten-alloy electrode stock, and ceramic insulating substrates. Single-source vulnerability in German industrial gas production creates supply chain risk when regional energy prices spike.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
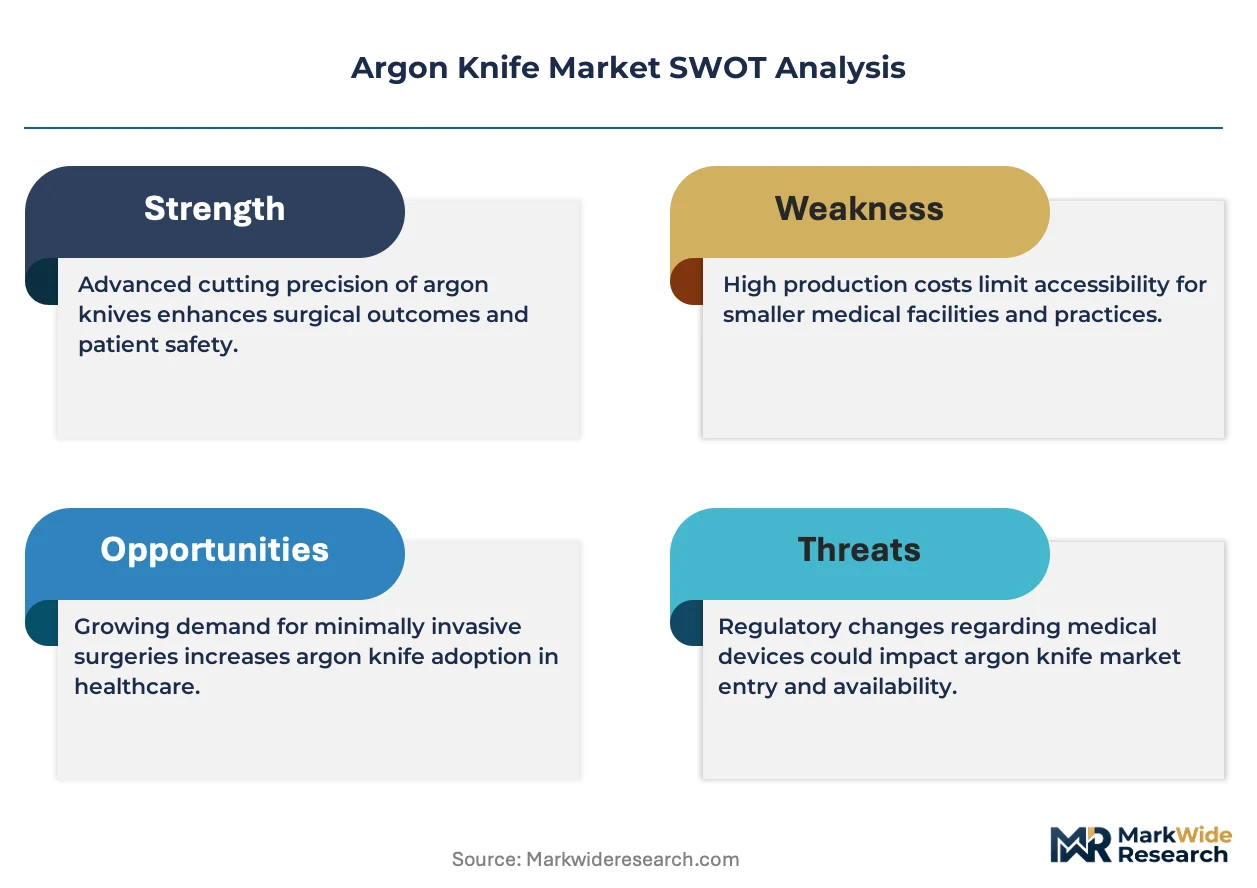
The argon knife market is consolidating around integrated platform vendors as EU MDR compliance costs and backward compatibility engineering requirements force weaker disposable electrode fabricators toward exit or acquisition.
For Market Incumbents: To counter ultrasonic scalpel substitution in general surgery departments, CONMED and ERBE Medical should deepen backward integration into electrosurgical generator manufacturing while locking hospital procurement committees into five-year service agreements with guaranteed uptime clauses. Captive supply of ceramic-coated electrode configurations preserves margin against commodity stainless steel competitors.
For New Entrants and Emerging Players: E-commerce-enabled direct procurement portals offer the lowest-friction route into United States ambulatory surgical center segments where traditional distributor relationships remain underdeveloped. Target Japan's aging surgical infrastructure retrofit programs and wound care outpatient networks where reimbursement coding variations create geographic white space. Specialty knife configurations for thoracoscopic approaches present the most penetrable product category.
For Investors and Strategic Acquirers: FDA 510(k) clearance for novel plasma modulation algorithms is the leading indicator that a target possesses defensible intellectual property and regulatory navigation capability. Mid-cap electrosurgical workstation specialists with ISO 13485 certification and established German hospital procurement relationships represent the optimal acquisition archetype over the coming decade. Monitor EU MDR post-market surveillance obligation fulfillment rates as the critical inflection signal for manufacturing quality discipline.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment accelerates market access for Class II surgical devices. |
| Hospital System Partnership | Bundled generator-knife-maintenance contracts secure volume commitments across United States IDNs. |
| Backward Integration | In-house electrosurgical generator production controls cost structures in premium disposables. |
| Software Companion Development | Plasma arc stability algorithms differentiate beam precision for microsurgical applications. |
| Reimbursement Strategy | Argon-enhanced procedure coding alignment shapes hospital capital equipment budget allocation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and electrosurgical device regulatory affairs specialists. FDA 510(k) premarket notification databases, EU MDR technical documentation repositories, hospital procurement databases, and electrosurgical equipment customs classification records provided validation triangulation against bottom-up manufacturer shipment estimates and top-down healthcare capital expenditure models.
Segment-level modeling operated at product type, application, end user, and technology dimensions across the projection horizon, with geographic granularity at country level for Germany, United States, Japan, and China. CAGRs derived from fitted growth curves applied to base-year volume estimates, incorporating procedure volume trajectories, equipment replacement cycle compression rates, and reimbursement code expansion patterns as industry-specific forecast inputs.
The model holds under stable regulatory enforcement intensity and continued tertiary care center capital investment; deviation in FDA 510(k) pathway duration or EU MDR post-market surveillance cost inflation would shift volume and value trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Industrial Kiln Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Metal Molds Market
Industrial Materials
Plain Bearing Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Industrial Seals Market
Industrial Materials
Acrylic Sheet Market
Industrial Materials
Wire Hoods Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Self Locking Nuts Market
Industrial Materials
Global Melamine Market
Industrial Materials
Plastic Compounding Machinery Market