
 CNS Lymphoma Market | 2026-2036
CNS Lymphoma Market Size, Share, and Industry Trends Forecast 2026-2036
CNS Lymphoma Market Analysis
Specialized neuro-oncology clinical trial expertise is rotating toward blood-brain barrier pharmacology as the critical workforce inflection unlocking pipeline velocity. Roche leverages its deep CNS drug delivery infrastructure to sustain leadership in intrathecal administration platforms. Bristol-Myers Squibb anchors its position through checkpoint inhibitor programs targeting primary CNS lymphoma subtypes. Novartis competes with radioligand therapy assets that extend its oncology footprint into leptomeningeal disease settings.
CNS lymphoma comprises malignant lymphoid cell proliferation within the brain, spinal cord, or meninges, with diffuse large B-cell lymphoma representing the predominant histological subtype requiring methotrexate-based induction protocols capable of achieving therapeutic concentrations behind an intact blood-brain barrier. The condition serves the fundamental clinical purpose of converting an otherwise rapidly fatal infiltrative neurological malignancy into a potentially manageable condition through multimodal systemic and intrathecal intervention. Immunotherapy segments are capturing disproportionate R&D investment as CAR-T constructs and bispecific antibodies demonstrate measurable cerebrospinal fluid responses, while intrathecal administration routes retain structural importance for achieving direct central nervous system drug exposure despite catheter-based delivery complexity. Hospitals as end users dominate procedural volume due to requirements for neurosurgical consultation, radiation oncology coordination, and intensive care monitoring during high-dose methotrexate administration.
FDA orphan drug designation and EMA PRIME eligibility criteria accelerate development timelines for CNS lymphoma therapies by enabling enhanced regulatory dialogue and conditional approval pathways based on single-arm phase II data. The country's national pharmaceutical regulator in Japan, PMDA, applies Sakigake designation to prioritize review of innovative CNS oncology agents, compressing time-to-market for sponsors with domestic clinical development programs. Stakeholders must monitor how evolving blood-brain barrier penetration biomarkers reshape payer evidence requirements and differentiate reimbursement for peripherally administered versus intrathecally delivered therapies.
Market Dynamics
Accelerated regulatory pathways for rare CNS malignancies are compressing development timelines while simultaneously elevating evidence requirements for blood-brain barrier penetration, forcing sponsors to front-load specialized pharmacology expertise.
Growth Catalysts
- FDA Orphan Drug Designation:Enhanced regulatory dialogue and tax incentives reduce clinical program risk for sponsors developing methotrexate-based induction protocols.
- Leptomeningeal Disease Clusters:Academic medical centers in Boston, Heidelberg, and Tokyo are standardizing multimodal treatment protocols that integrate systemic and intrathecal administration routes.
- CAR-T Cerebrospinal Fluid Response:Measurable efficacy signals from cell therapy constructs are redirecting R&D investment toward immunotherapy segments capable of achieving direct CNS exposure.
Market Restraints
- High-Dose Methotrexate Monitoring:Intensive care requirements during administration create capacity constraints at tertiary hospitals and limit procedural volume expansion.
- Catheter-Based Delivery Complexity:Intrathecal administration infrastructure demands neurosurgical consultation and specialized pharmacy compounding that concentrates at academic centers.
- Blood-Brain Barrier Pharmacology Talent Scarcity:Limited workforce expertise in CNS drug delivery slows pipeline velocity for peripherally administered agents.
Strategic Opportunities
- PMDA Sakigake Designation:Japan's priority review pathway compresses time-to-market for sponsors with domestic clinical development programs in CNS oncology.
- Radioligand Therapy Convergence:Combination of targeted radiotherapy with precision diagnostics creates white space in leptomeningeal disease settings previously served by palliative care.
- Biomarker-Driven Reimbursement Differentiation:Emerging penetration biomarkers enable payers to stratify coverage between peripherally administered and intrathecally delivered therapies.
Industry Challenges
- Neuro-Oncology Workforce Rotation:Specialized clinical trial expertise is concentrating at blood-brain barrier research clusters, creating recruitment competition across sponsor programs.
- Cross-Functional Coordination Complexity:Treatment protocols require synchronized radiation oncology, neurosurgery, and medical oncology scheduling that fragments operational efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNS Lymphoma Market |
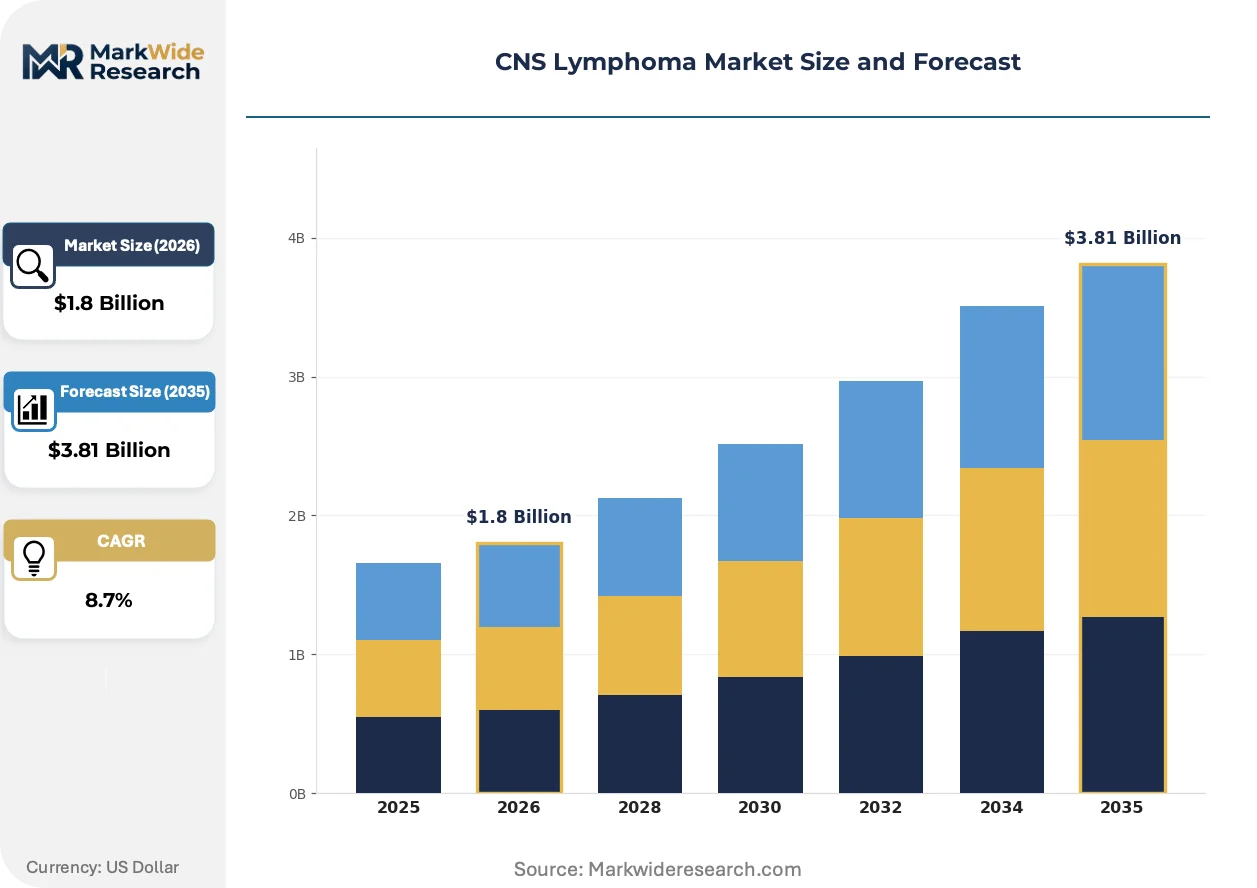
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Targeted Therapy Therapy Area: Primary CNS Lymphoma, Secondary CNS Lymphoma, Relapsed CNS Lymphoma, Newly Diagnosed CNS Lymphoma End User: Hospitals, Specialty Clinics, Outpatient Facilities, Research Institutes Administration Route: Intravenous, Oral, Intrathecal, Subcutaneous |
| Companies Covered | Roche, Bristol-Myers Squibb, Novartis, Gilead Sciences, Johnson & Johnson, AstraZeneca, AbbVie, Amgen, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNS Lymphoma Market Emerging Trajectories
Immunotherapy construct engineering is decomposing traditional boundaries between systemic and intrathecal administration routes, while regulatory biomarker requirements are reshaping how sponsors design CNS penetration studies.
Bispecific antibody platforms targeting CD20-expressing lymphoid cells are decomposing the historical dominance of methotrexate-based induction protocols. Neuro-oncology departments at academic medical centers in the United States and Germany are adopting these constructs for relapsed primary CNS lymphoma cases. The technology is decomposing conventional trial design by enabling single-arm efficacy studies that satisfy FDA accelerated approval criteria.
EMA PRIME eligibility criteria for rare CNS malignancies are compressing phase II-to-approval timelines through enhanced scientific advice and conditional marketing authorization pathways. Sponsors must now demonstrate blood-brain barrier penetration using cerebrospinal fluid pharmacokinetic sampling that exceeds traditional oncology evidence standards. European reference pricing systems are responding by creating distinct reimbursement tiers for agents with validated CNS exposure versus those without.
Hospital procurement committees are consolidating vendor relationships for high-cost immunotherapy agents around centers with established neuro-oncology infrastructure. Integrated delivery networks in the United States are restricting formulary access to institutions with radiation oncology and neurosurgical co-location. This concentration is most visible in tertiary referral patterns that funnel complex CNS lymphoma cases toward designated excellence centers in Boston, New York, and Houston.
CNS Lymphoma Market Segmentation
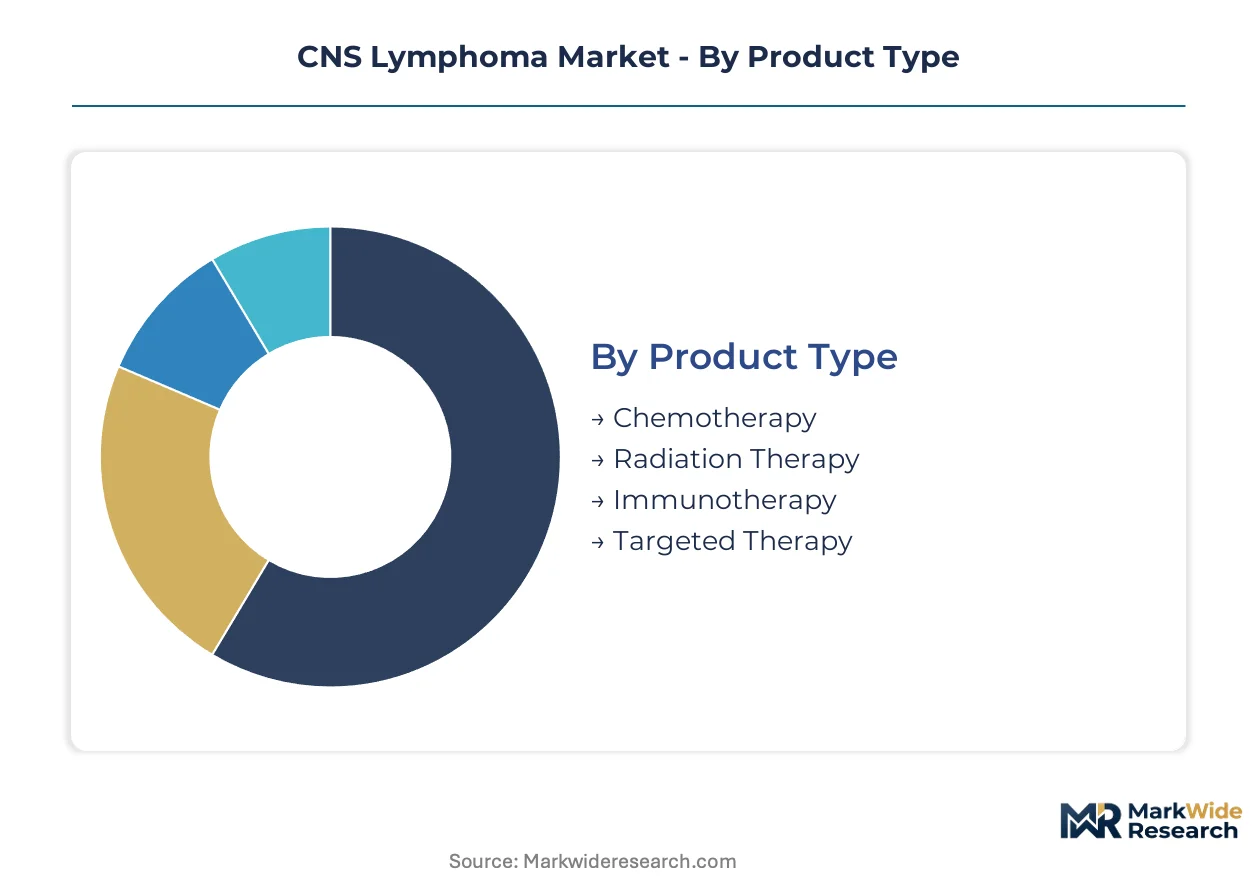
CNS lymphoma treatment modalities fragment across pharmacological mechanisms, disease staging, and care delivery settings. Segmentation reveals how blood-brain barrier penetration requirements concentrate procedural volume at specialized centers while immunotherapy constructs reshape competitive boundaries.
Product Type:
Domestic demand clusters around intrathecal chemotherapy infrastructure in the United States, Germany, and Japan, while immunotherapy development concentrates at export-oriented biologics manufacturers with CNS pharmacology expertise.
- Chemotherapy:Methotrexate-based induction protocols remain the pharmacological backbone, requiring therapeutic concentrations achievable only through high-dose intravenous or intrathecal administration. Demand concentrates at tertiary hospitals in Boston, Heidelberg, and Tokyo where neurosurgical consultation and intensive care monitoring co-locate.
- Immunotherapy:CAR-T constructs and bispecific antibodies redirect R&D investment toward cell therapy platforms capable of measurable cerebrospinal fluid responses. Academic medical centers in the United States and Germany adopt these constructs for relapsed cases, decompressing historical reliance on cytotoxic agents.
- Radiation Therapy:Whole-brain radiotherapy integrates with systemic protocols at specialized neuro-oncology departments.
- Targeted Therapy:Precision agents with validated blood-brain barrier penetration command premium positioning.
Chemotherapy commands the established base. The steepest expansion runs through immunotherapy segments.
Therapy Area:
Cost tier stratification separates curative-intent induction protocols from salvage regimens, with frontline therapy commanding resource concentration at academic centers.
- Primary CNS Lymphoma:Diffuse large B-cell lymphoma confined to the CNS without systemic involvement requires multimodal methotrexate-based induction with consolidated radiotherapy. Treatment protocols at centers in New York, Houston, and Boston standardize this approach through cooperative group trials.
- Relapsed CNS Lymphoma:Recurrence after initial response drives demand for experimental immunotherapy constructs and salvage chemotherapy regimens. Patients funnel toward designated excellence centers with early-phase trial access.
- Secondary CNS Lymphoma:Systemic lymphoma with CNS dissemination requires modified dosing schedules.
- Newly Diagnosed CNS Lymphoma:Initial presentation triggers referral patterns to neuro-oncology hubs.
Primary CNS lymphoma anchors procedural volume. The fastest volume gains emerge in relapsed settings where immunotherapy trials concentrate.
End User:
Supply concentration at hospitals reflects operational requirements for neurosurgical consultation, radiation oncology coordination, and intensive care capacity during high-dose methotrexate administration.
- Hospitals:Tertiary academic medical centers dominate procedural volume through requirements for multidisciplinary coordination. Integrated delivery networks in the United States restrict formulary access to institutions with neurosurgical and radiation oncology co-location.
- Specialty Clinics:Community oncology practices with neuro-oncology affiliations handle stable patients between induction cycles.
- Outpatient Facilities:Limited to low-risk administration and monitoring.
- Research Institutes:Early-phase trial sites concentrate at blood-brain barrier research clusters.
Hospitals retain the structural core. Specialty clinics are expanding fastest as stabilized patients transition to community settings.
Administration Route:
Margin differentiation separates peripherally administered agents from intrathecal delivery, with catheter-based infrastructure creating vendor consolidation at centers with neurosurgical expertise.
- Intrathecal:Direct cerebrospinal fluid delivery via Ommaya reservoir or lumbar puncture achieves therapeutic concentrations impossible through systemic routes. Roche sustains platform leadership through specialized catheter infrastructure and pharmacy compounding protocols.
- Intravenous:High-dose methotrexate with leucovorin rescue remains standard induction, requiring intensive care monitoring for renal clearance and neurotoxicity. Capacity constraints at tertiary hospitals limit procedural expansion.
- Oral:Limited agents demonstrate adequate CNS penetration.
- Subcutaneous:Emerging for maintenance immunotherapy with peripheral efficacy.
Intravenous administration anchors current practice. Intrathecal routes are climbing fastest as penetration biomarkers validate direct CNS exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor the United States as the dominant geography, while EMA PRIME eligibility and PMDA Sakigake designation create parallel regulatory momentum in Europe and Japan.
United States
Academic medical centers in Boston, New York, and Houston drive procedural volume through specialized neuro-oncology infrastructure. FDA orphan drug designation compresses development timelines for CNS malignancies while enabling enhanced regulatory dialogue. The Greater Boston cluster standardizes multimodal treatment protocols integrating systemic and intrathecal administration routes.
Germany
Heidelberg and Berlin anchor blood-brain barrier research concentration with established leptomeningeal disease expertise. EMA PRIME eligibility criteria accelerate phase II-to-approval timelines through conditional marketing authorization pathways. Reference pricing systems create distinct reimbursement tiers for agents with validated CNS exposure versus those without.
Japan
Tokyo and Osaka metropolitan areas concentrate specialized pharmacy compounding and catheter-based delivery infrastructure. PMDA Sakigake designation prioritizes review of innovative CNS oncology agents, compressing time-to-market for sponsors with domestic clinical development programs. The country's national pharmaceutical regulator applies accelerated pathways specifically for rare CNS malignancies.
United Kingdom
London and Manchester tertiary centers coordinate radiation oncology and neurosurgical scheduling for complex cases. NICE technology appraisals increasingly incorporate cerebrospinal fluid pharmacokinetic data into coverage decisions. The NHS England specialized commissioning framework concentrates high-cost immunotherapy access at designated excellence centers.
Switzerland
Basel and Zurich host radioligand therapy development programs extending into leptomeningeal disease settings. Swissmedic maintains alignment with EMA accelerated pathways while offering independent scientific advice for CNS penetration studies. Roche leverages domestic infrastructure to sustain platform leadership in intrathecal administration technologies.
CNS Lymphoma Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated pharmaceutical conglomerates commanding CNS drug delivery infrastructure while biotechnology specialists concentrate immunotherapy construct engineering. The vendor base organizes around three strategic archetypes: platform incumbents with catheter-based infrastructure, cell therapy developers with cerebrospinal fluid response data, and radioligand therapy specialists extending into neuro-oncology. Competitive moves concentrate on M&A for blood-brain barrier pharmacology talent and strategic partnerships for multimodal protocol standardization.
Among Swiss-based pharmaceutical conglomerates, Roche anchors platform leadership through intrathecal administration infrastructure. Bristol-Myers Squibb represents checkpoint inhibitor development targeting primary CNS lymphoma subtypes. Novartis occupies a position in radioligand therapy assets that extend oncology footprints into leptomeningeal disease settings previously served by palliative care.
| Leading Market Players |
|---|
| Roche |
| Bristol-Myers Squibb |
| Novartis |
| Gilead Sciences |
| Johnson & Johnson |
| AstraZeneca |
| AbbVie |
| Amgen |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for specialized catheter-based delivery systems concentrate procurement leverage at academic medical centers with neurosurgical infrastructure, amplifying pricing power for vendors with validated blood-brain barrier penetration platforms.
Pricing Analysis
Geographic price spreads of 40-60% separate United States tertiary centers from European reference-priced markets, with three-tier pricing structure across premium intrathecal platforms, standard high-dose methotrexate regimens, and economy salvage chemotherapy protocols. Price differentiation hinges on FDA breakthrough therapy designation and validated cerebrospinal fluid pharmacokinetic data. Pricing pressure intensifies in standard chemotherapy tiers as biosimilar methotrexate formulations expand formulary access. Community oncology practices exhibit highest price sensitivity, while academic centers with dedicated neuro-oncology infrastructure prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate for high-cost immunotherapy constructs with limited shelf stability, while strategic stockpiling of methotrexate concentrates at tertiary hubs in the United States, Germany, and Japan. Raw material dependencies include pharmaceutical-grade methotrexate API, specialized catheter polymers, and radioligand isotopes. Supply chain risk centers on single-source vulnerability for Ommaya reservoir manufacturing. Distribution runs through integrated delivery networks that restrict formulary access to designated excellence centers with radiation oncology and neurosurgical co-location.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for rare CNS malignancies compress development timelines while elevating evidence requirements, creating asymmetric returns for sponsors with front-loaded blood-brain barrier pharmacology expertise.
For Market Incumbents: Consolidate catheter-based infrastructure through exclusive pharmacy compounding agreements at academic medical centers in Boston, Heidelberg, and Tokyo. Deepen backward integration into specialized polymer sourcing for Ommaya reservoir manufacturing to defend against supply disruption threats from single-source component vendors. For New Entrants and Emerging Players: Anchor in relapsed primary CNS lymphoma settings where immunotherapy trial access concentrates patient flow at designated excellence centers. Target leptomeningeal disease applications previously served by palliative care, leveraging biomarker-driven reimbursement differentiation as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap oncology conglomerates divesting legacy neuro-oncology assets lacking blood-brain barrier penetration validation. Long-term viability hinges on pipeline depth in cerebrospinal fluid-responsive constructs. Watch for EMA PRIME eligibility announcements as inflection indicators for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Single-arm phase II designs satisfy FDA accelerated approval criteria for primary CNS lymphoma subtypes. |
| Regulatory Approval Pathway | EMA PRIME eligibility compresses phase II-to-approval timelines through conditional marketing authorization. |
| Manufacturing Scale-Up | Specialized pharmacy compounding capacity for intrathecal formulations concentrates at academic medical centers. |
| Pipeline Diversification | Radioligand therapy assets extend oncology footprints into leptomeningeal disease settings. |
| Strategic Partnership | Multimodal protocol standardization partnerships with blood-brain barrier research clusters accelerate enrollment velocity. |
Methodological Framework
The analysis maps chemotherapy induction protocols, immunotherapy constructs, and radioligand therapy platforms, each validated through neuro-oncology department heads, regulatory affairs specialists at FDA and EMA, hospital procurement managers, and payer access directors. Secondary sources include FDA orphan drug designation filings, EMA PRIME eligibility decisions, ClinicalTrials.gov protocol registrations, and hospital formulary databases. Bottom-up patient-flow modeling triangulates against top-down pharmaceutical revenue estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product type, therapy area, end user, and administration route, with regional regulatory clusters as a cross-cutting dimension. CAGRs derive from patient incidence projections, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs include blood-brain barrier penetration biomarker validation timelines and intrathecal administration infrastructure expansion rates.
Material uncertainties — regulatory rejection of single-arm efficacy data, supply disruption in catheter manufacturing, and payer non-coverage of peripherally administered agents — sit outside the modeled envelope. Forecasts reflect assumptions about accelerated pathway retention and biomarker adoption curves. Revision becomes warranted when FDA breakthrough therapy designation thresholds for CNS malignancies cross restrictive reinterpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Chiari Malformation Treatment Market
Neurology
Pediatric Neurology Device Market
Neurology
Neurological Biomarkers Market
Neurology
Neuro Critical Care Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Brain Ischemia Market
Neurology
Sweden Neurology Devices Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
CNS Treatment and Therapy Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Cognitive Neuroscience Market
Neurology
Arachnoiditis Market
Neurology
Spasticity Treatment Market
Neurology
Spinal Laminoplasty Market
Neurology
Arachnoiditis Treatment Market
Neurology
Vocal Cord Paralysis Market