
 Status Epilepticus Treatment Market | 2026-2036
Status Epilepticus Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Status Epilepticus Treatment Market Analytics
Hospital procurement of status epilepticus therapies is fragmenting as integrated delivery networks bypass traditional wholesale distributors and contract directly with manufacturers. UCB leverages its established neurology franchise to sustain preferential formulary placement across European hospital systems. Pfizer competes through manufacturing scale that anchors supply security for generic injectable benzodiazepines during shortage periods.
Status epilepticus treatment encompasses pharmacologic and dietary interventions administered to terminate prolonged or recurrent seizure activity without recovery of consciousness, with intravenous lorazepam and diazepam serving as first-line agents per established neurocritical care protocols. The primary purpose centers on preventing neuronal injury, respiratory compromise, and mortality in emergency and intensive care settings. Benzodiazepines occupy the dominant revenue position among product types due to universal first-line guideline endorsement, while intravenous delivery mode commands the steepest margin pool given hospital premium pricing and emergency administration requirements. Anticonvulsants represent the fastest-expanding category as newer parenteral formulations gain protocol adoption for refractory cases.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines for novel anticonvulsant entities, reshaping how Sage Therapeutics and Jazz Pharmaceuticals navigate clinical-to-commercial transitions. The EU AI Act and FDA's evolving digital health guidance create compliance complexity for device-integrated drug delivery systems such as Medtronic's and LivaNova's neuromodulation platforms. Stakeholders must monitor reimbursement divergence between hospital-based acute protocols and emerging homecare administration models.
Market Dynamics
Hospital procurement consolidation and neurocritical care protocol standardization are compressing vendor margins while elevating formulary control power of integrated delivery networks across major acute care markets.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Accelerated review timelines for novel anticonvulsant candidates compress development-to-commercialization cycles, rewarding first-mover entrants with extended market exclusivity windows in refractory status epilepticus segments.
- Neurocritical Care Infrastructure Expansion:Specialized epilepsy monitoring units in Germany, Japan, and the United States drive protocol-driven benzodiazepine consumption and create captive demand for second-line parenteral agents.
- EU AI Act Compliance Framework:Device-integrated drug delivery systems gain regulatory clarity for neuromodulation platforms, enabling cross-border hospital procurement of closed-loop seizure termination technologies.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Injectable benzodiazepine API manufacturing concentrates in Indian and Chinese contract manufacturers, exposing supply security to geopolitical friction and export restriction risk.
- EMA MDR Transition Burden:Medical device components of combination drug-device therapies face recertification complexity, delaying commercialization timelines for next-generation infusion pump integrations.
- Generic Substitution Pressure:Patent-expired lorazepam and diazepam formulations face commoditization, eroding branded pricing power in hospital emergency departments despite clinical guideline preference for specific salt forms.
Strategic Opportunities
- Homecare Administration Models:Subcutaneous benzodiazepine autoinjector development targets post-hospital discharge seizure rescue, opening reimbursement negotiations with Medicare Advantage and commercial payers in the United States.
- Japan PMDA Sakigake Designation:Priority review incentives for innovative anticonvulsants with novel mechanisms of action attract development investment targeting refractory patient populations.
- Digital Health Integration:EEG-integrated closed-loop drug delivery converges with cloud-based seizure prediction algorithms, enabling outcome-based contracting with academic medical centers.
Industry Challenges
- Neurocritical Care Specialist Scarcity:Board-certified epileptologist and neurointensivist training program bottlenecks limit protocol expansion into community hospital settings, constraining addressable market growth.
- Combination Product Regulatory Complexity:Drug-device submissions requiring coordinated FDA Center for Drug Evaluation and Research and Center for Devices and Radiological Health review extend approval timelines and increase development cost exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Status Epilepticus Treatment Market |
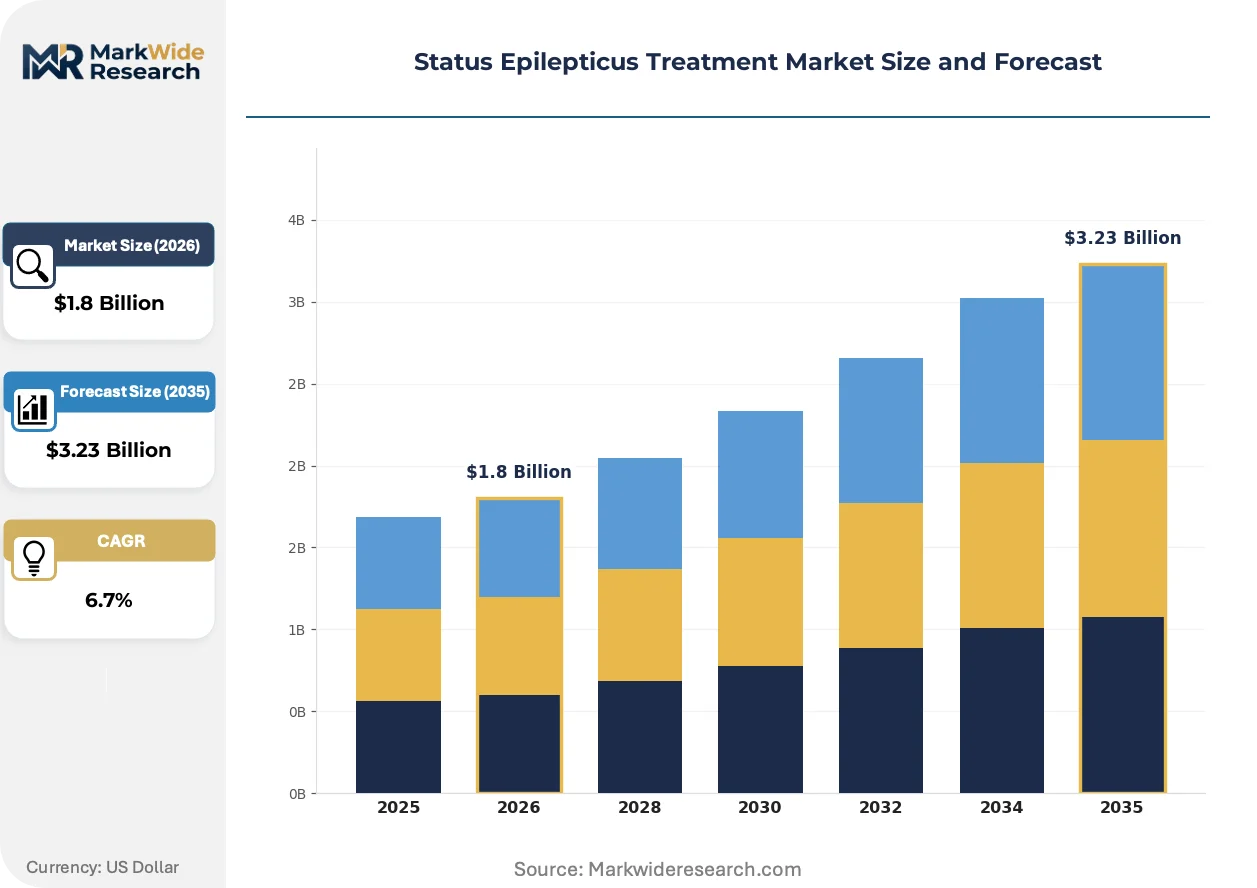
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzodiazepines, Anticonvulsants, Barbiturates, Ketogenic Diet End User: Hospitals, Outpatient Clinics, Homecare, Research Institutions Delivery Mode: Intravenous, Oral, Rectal, Inhalation Treatment Duration: Short-term, Long-term, Acute, Maintenance |
| Companies Covered | UCB, Novartis, GSK, Medtronic, LivaNova, Pfizer, Jazz Pharmaceuticals, Sage Therapeutics, Eisai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Status Epilepticus Treatment Market Evolving Landscape
Technology convergence between parenteral drug delivery and real-time neurophysiological monitoring is restructuring competitive advantage around integrated therapy platforms rather than standalone pharmaceutical agents.
Continuous EEG-guided drug titration systems are migrating from academic medical center research protocols to standard-of-care expectations in level-four epilepsy centers. Neurocritical care units at Johns Hopkins, Cleveland Clinic, and Charité Universitätsmedizin Berlin have adopted these platforms for refractory status epilepticus management. This migration is compressing the window between seizure onset and optimized therapeutic response, displacing weight-based dosing protocols that lack individual pharmacodynamic feedback.
The EU AI Act's risk classification framework for medical devices imposes conformity assessment requirements on machine learning algorithms embedded in seizure detection and drug delivery automation. Manufacturers must demonstrate algorithmic transparency and post-market performance monitoring, elevating compliance costs for European market entry. German hospital procurement offices now require AI Act documentation as a mandatory evaluation criterion in tender specifications.
Integrated delivery networks in the United States are consolidating pharmaceutical purchasing through specialty pharmacy carve-outs and 340B program optimization, bypassing traditional wholesale distribution for high-cost anticonvulsants. Hospital systems including HCA Healthcare and CommonSpirit Health have established direct manufacturer relationships for intravenous benzodiazepine supply security. This concentration is most visible in Texas and Florida markets where neurocritical care bed expansion outpaces general acute care growth.
Status Epilepticus Treatment Market Segmentation
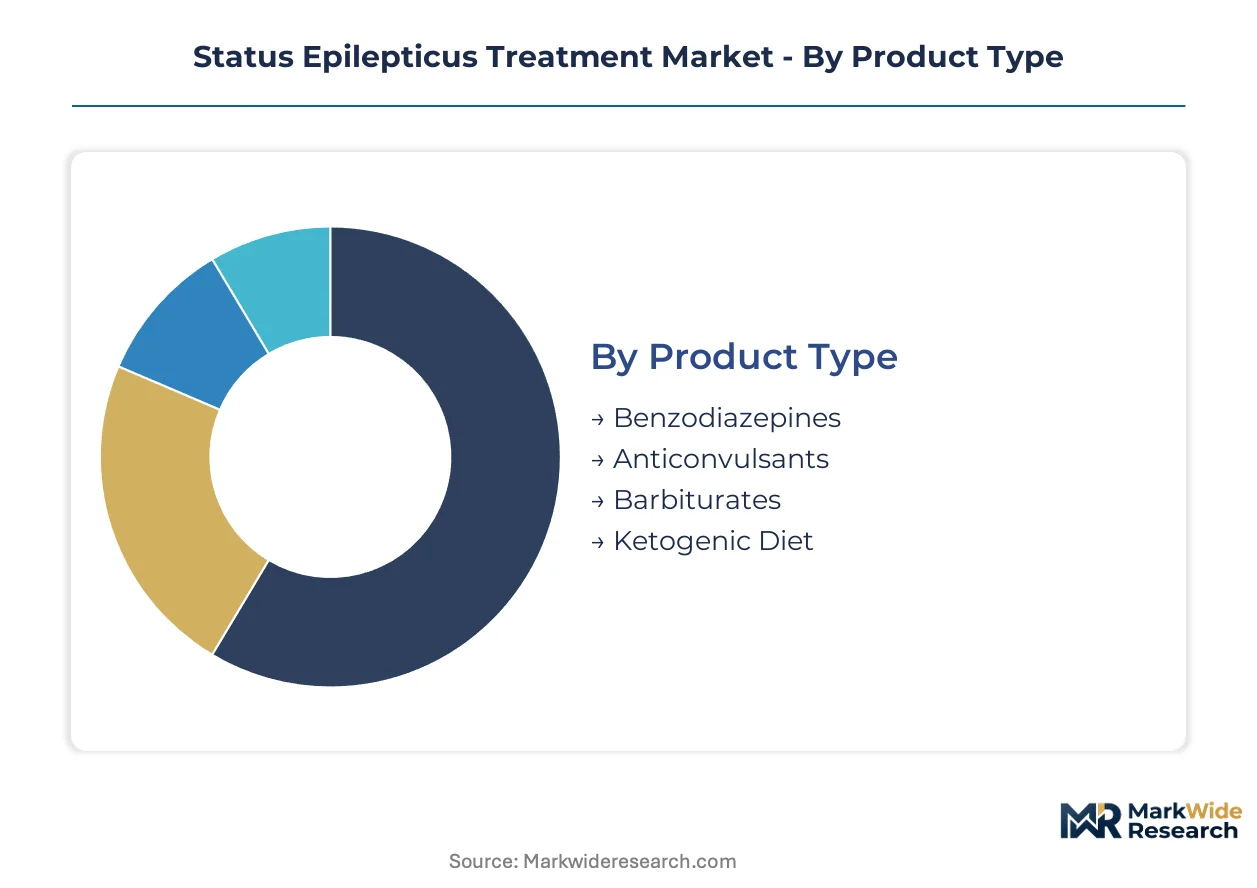
Treatment protocols for status epilepticus fragment across clinical settings and pharmacologic mechanisms, creating distinct margin pools for emergency benzodiazepine administration versus chronic anticonvulsant management. Segmentation reveals how hospital procurement power concentrates in intravenous formulations while homecare and research channels incubate next-generation delivery technologies.
Product Type:
Cost tier stratification separates commodity first-line agents from premium-priced refractory therapies and non-pharmacologic interventions.
- Benzodiazepines:Intravenous lorazepam and diazepam formulations dominate emergency department formularies through universal first-line guideline endorsement. Hospital systems in the United States and Germany anchor procurement volume for these agents, with integrated delivery networks negotiating direct manufacturer contracts to secure supply during shortage periods.
- Anticonvulsants:Parenteral formulations including fosphenytoin, levetiracetam, and valproate serve second-line and refractory status epilepticus protocols. Demand concentrates in level-four epilepsy centers at Johns Hopkins, Cleveland Clinic, and Charité Universitätsmedizin Berlin where continuous EEG monitoring enables individualized drug titration.
- Barbiturates:Pentobarbital and phenobarbital infusions reserve for super-refractory cases requiring induced coma and burst suppression.
- Ketogenic Diet:Metabolic therapy for pediatric refractory epilepsy extends to adjunctive status epilepticus management in specialized neurocritical care units.
Benzodiazepines hold installed capacity. Anticonvulsants is rotating up the share rankings.
End User:
Customer type determines reimbursement pathway complexity and procurement decision authority, from centralized hospital pharmacy committees to individual patient out-of-pocket expenditure.
- Hospitals:Emergency departments and neurocritical care units generate the steepest margin pool through premium intravenous pricing and protocol-driven consumption. Academic medical centers in Japan, Germany, and the United States drive adoption of EEG-integrated drug delivery platforms.
- Outpatient Clinics:Neurology practices manage post-acute seizure rescue and medication optimization for stabilized patients. These settings in Texas and Florida face formulary constraints from Medicare Advantage prior authorization requirements.
- Homecare:Subcutaneous benzodiazepine autoinjector development targets discharge seizure rescue, opening direct-to-patient channels outside traditional hospital procurement.
- Research Institutions:Clinical trial sites for novel anticonvulsant entities concentrate at NIH-funded centers and European Reference Networks for rare and complex epilepsies.
Hospitals hold installed capacity. Homecare is rotating up the share rankings.
Delivery Mode:
Application urgency dictates route selection, with parenteral administration commanding premium pricing for immediate seizure termination versus maintenance oral therapy.
- Intravenous:Direct vascular access enables rapid central nervous system penetration for emergency status epilepticus termination. FDA and EMA manufacturing standards for sterile injectable production create regulatory barriers that protect margin structures for compliant manufacturers.
- Oral:Tablet and liquid formulations serve maintenance anticonvulsant therapy and post-acute seizure prophylaxis. Generic substitution pressure from patent-expired agents compresses branded pricing power in outpatient settings.
- Rectal:Diazepam gel formulations provide community and pre-hospital seizure rescue where intravenous access is unavailable.
- Inhalation:Investigational benzodiazepine aerosol delivery targets rapid non-invasive administration for paramedic and homecare rescue scenarios.
Intravenous holds installed capacity. Inhalation is rotating up the share rankings.
Treatment Duration:
Maturity of clinical indication separates acute emergency intervention from chronic disease management, with distinct regulatory and reimbursement frameworks governing each.
- Acute:Immediate seizure termination protocols spanning minutes to hours define the core addressable market for status epilepticus therapeutics. FDA breakthrough therapy designation accelerates development timelines for novel agents targeting refractory cases.
- Short-term:Hospital-based intensive care management extends from initial seizure control through metabolic stabilization and etiologic diagnosis.
- Maintenance:Chronic anticonvulsant regimens prevent seizure recurrence following acute episode resolution.
- Long-term:Extended neurocritical care for super-refractory status epilepticus requiring anesthetic coma and multimodal monitoring.
Acute holds installed capacity. Long-term is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement power concentrates in the United States and Germany, where neurocritical care infrastructure commands premium pricing for intravenous benzodiazepines, while Japanese reimbursement protocols create distinct margin compression for second-line anticonvulsants.
United States
Integrated delivery networks in Texas and Florida bypass wholesale distributors for direct manufacturer contracts, securing supply security for emergency departments. FDA breakthrough therapy designation accelerates novel anticonvulsant development timelines. Johns Hopkins and Cleveland Clinic anchor adoption of EEG-integrated drug delivery platforms for refractory case management.
Germany
Charité Universitätsmedizin Berlin and university hospitals in Bavaria drive protocol standardization for continuous EEG monitoring. EU AI Act compliance requirements now appear in hospital tender specifications for device-integrated therapies. North Rhine-Westphalia hosts concentrated manufacturing capacity for sterile injectable production serving European hospital systems.
Japan
PMDA Sakigake designation attracts development investment for innovative anticonvulsants targeting refractory populations. METI funding supports neurocritical care unit expansion in Tokyo and Osaka metropolitan areas. Kanto region academic medical centers pilot closed-loop seizure termination technologies with cloud-based monitoring integration.
United Kingdom
NHS England specialized commissioning frameworks concentrate status epilepticus treatment in designated epilepsy centers across London and the Midlands. MHRA post-Brexit regulatory autonomy enables accelerated parallel review with FDA for breakthrough therapies. Greater Manchester and Birmingham hospital systems consolidate pharmaceutical procurement through regional pharmacy collaborative structures.
India
CDSCO manufacturing facility inspections intensify for injectable benzodiazepine API producers supplying European and North American markets. Government hospital procurement through the Central Medical Services Society anchors volume for generic emergency medications. Maharashtra and Gujarat host contract manufacturing organizations serving global sterile injectable demand.
Status Epilepticus Treatment Market Competitive Landscape
Established neurology franchises and manufacturing-scale specialists split the market between formulary control and supply security. The vendor base concentrates around three strategic archetypes: integrated pharmaceutical conglomerates with hospital system relationships, device-integrated therapy platform developers, and generic sterile injectable manufacturers. Competitive positioning hardens through direct procurement contracting with integrated delivery networks and regulatory pathway optimization for breakthrough therapy designations.
Within the integrated pharmaceutical tier, UCB leverages its neurology franchise for preferential European hospital formulary placement, while Pfizer anchors supply security for generic injectable benzodiazepines during shortage periods. Among device-integrated therapy developers, Medtronic and LivaNova occupy positions at the convergence of neuromodulation platforms and closed-loop drug delivery systems.
| Leading Market Players |
|---|
| UCB |
| Novartis |
| GSK |
| Medtronic |
| LivaNova |
| Pfizer |
| Jazz Pharmaceuticals |
| Sage Therapeutics |
| Eisai |
| Others |
Value Network & Pricing Analysis
Indian and Chinese contract manufacturers concentrate active pharmaceutical ingredient production for injectable benzodiazepines, anchoring margin pools in hospital emergency departments where supply security commands premium pricing over commodity alternatives. This upstream concentration forces procurement officers at integrated delivery networks to negotiate direct manufacturer contracts that bypass traditional wholesale distributors during shortage periods.
Pricing Analysis
The customization-premium spread between FDA-designated breakthrough therapies and generic lorazepam formulations exceeds fivefold in hospital emergency departments. Three-tier pricing structure across premium, standard, and economy levels separates patented parenteral anticonvulsants from branded benzodiazepines and commodity injectables. Price differentiation hinges on regulatory certification tier and vertical integration depth, with API-to-finished-dose manufacturers capturing margin expansion. Cost compression in generic injectables is intensifying because integrated delivery networks consolidate purchasing volume through 340B program optimization. Community hospital systems exhibit highest price sensitivity, while academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
Contract manufacturing organizations in Maharashtra and Gujarat hold concentrated capacity for sterile injectable benzodiazepine production serving North American and European hospital systems. Geographic supply concentration centers on India, China, and Germany for API synthesis, finished dose manufacturing, and device-integrated delivery systems respectively. Raw material dependencies draw from specialized solvents, glass vial components, and pre-filled syringe assemblies. Single-source vulnerability persists where FDA-inspected facilities face export restriction risk from geopolitical friction. Distribution runs through direct manufacturer relationships with integrated delivery networks, displacing traditional wholesale channels for high-volume hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where continuous EEG monitoring subscriptions and closed-loop drug delivery maintenance contracts expand faster than standalone pharmaceutical hardware. The recurring-revenue layer from outcome-based contracting with academic medical centers outpaces traditional per-dose pricing growth.
For Market Incumbents: Entrench formulary control through captive supply agreements with Charité Universitätsmedizin Berlin and Johns Hopkins that bundle parenteral benzodiazepines with neuromodulation platform servicing. Deepen backward integration into API manufacturing to offset Indian contract manufacturer concentration risk. Invest in FDA breakthrough therapy designation pathways for refractory status epilepticus segments before generic substitution erodes branded pricing power in emergency departments. For New Entrants and Emerging Players: Texas and Florida community hospital systems represent underpenetrated territory where neurocritical care bed expansion outpaces specialist physician supply. Target outpatient clinic seizure rescue with subcutaneous autoinjector formulations that bypass hospital pharmacy committee gatekeeping. Pursue direct-to-patient channels through Medicare Advantage reimbursement negotiations rather than competing for integrated delivery network formulary slots against entrenched incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic sterile injectable manufacturers that consolidated during prior lorazepam shortage periods. Long-term viability over the next decade hinges on regulatory pathway optimization for device-drug combination products facing EMA MDR recertification complexity. Watch FDA breakthrough therapy designation grants to Sage Therapeutics and Jazz Pharmaceuticals as inflection indicators for refractory segment premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Accelerated review timelines compress development-to-commercialization cycles for novel anticonvulsants. |
| Direct Manufacturer Contracting | Integrated delivery networks in Texas bypass wholesale distributors to secure benzodiazepine supply security. |
| EU AI Act Compliance Investment | German hospital procurement offices now mandate algorithmic transparency documentation in tender specifications. |
| Subcutaneous Autoinjector Development | Post-hospital discharge seizure rescue opens reimbursement negotiations with Medicare Advantage plans. |
| Continuous EEG Platform Integration | Johns Hopkins and Cleveland Clinic adoption validates outcome-based contracting with academic medical centers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov, and hospital formulary databases. Interviews with neurocritical care physicians, hospital procurement managers, regulatory affairs leads, and payer access specialists informed demand-side assumptions. Bottom-up prescription volume modeling triangulates against top-down market sizing from pharmaceutical distribution data and sterile injectable manufacturing capacity disclosures.
Forecast inputs include treatment line progression, administration route adoption curves, patient population severity stratification, and regional regulatory cluster differentiation. Segmentation dimensions span pharmacologic mechanism, delivery mode urgency, end-user procurement authority, and treatment duration intensity. CAGRs derive from protocol-driven consumption elasticity in neurocritical care units and reimbursement pathway evolution for homecare administration models. Supply-side constraints from API manufacturing concentration and EMA MDR transition timelines inform capacity-limited growth scenarios.
Practitioners should monitor FDA breakthrough therapy designation grants, EMA priority medicines pathway decisions, and integrated delivery network consolidation announcements for early signals of competitive positioning shifts. Forecasts reflect assumptions about neurocritical care specialist training pipeline expansion and hospital pharmacy committee formulary control persistence. Quarterly review of benzodiazepine shortage notifications, CDSCO manufacturing facility inspection outcomes, and Medicare Advantage prior authorization requirement changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neuro Critical Care Market
Neurology
China Neurology Devices Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Hepatic Encephalopathy Market
Neurology
North America Neurology Monitoring Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Spinal Laminoplasty Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Coma Diagnosis and Treatment Market
Neurology
Neuroendocrine Carcinoma Market
Neurology
Nerve Repair Market
Neurology
Lewy Body Dementia Treatment Market
Neurology
Global Sciatica Treatment Market
Neurology
Neurology Digital Therapeutics Market
Neurology
Asia-Pacific Neurology Monitoring Market