
 Arachnoiditis Market | 2026-2036
Arachnoiditis Market Size, Share, and Industry Trends Forecast 2026-2036
Arachnoiditis Market Analysis
Software-defined dosing algorithms for intrathecal pumps is restructuring how pharmaceutical and device manufacturers bundle therapy offerings. Pfizer Inc. leverages its analgesic portfolio to anchor long-term corticosteroid supply contracts with hospital systems. Medtronic dominates the neuromodulation hardware layer through its proprietary intrathecal delivery platforms. Stryker competes in surgical decompression instruments used during arachnoiditis intervention procedures.
Arachnoiditis denotes inflammation of the arachnoid membrane surrounding spinal nerves, typically triggered by trauma, infection, or iatrogenic injury during spinal procedures, with diagnosis relying on gadolinium-enhanced MRI and cerebrospinal fluid analysis. The condition primarily demands chronic pain management and neurological preservation in affected patients. Medications and pain management devices command the largest current revenue pools, while intrathecal delivery modes represent the fastest-growing structural segment due to targeted dosing advantages. Surgical procedures occupy a narrower but high-margin niche reserved for progressive neurological deficit cases.
FDA 510(k) and PMA pathways govern neuromodulation device commercialization in the United States, while EMA's MDR framework dictates conformity requirements across European markets. Japan's PMDA imposes additional clinical data standards on intrathecal pump submissions, elevating development costs for foreign entrants. Stakeholders must monitor evolving reimbursement codes for intrathecal therapy across Medicare, NHS England, and Japan's MHLW to anticipate access-driven demand shifts.
Market Dynamics
Software-defined dosing algorithms for intrathecal pumps are restructuring how pharmaceutical and device manufacturers bundle therapy offerings, forcing incumbents to integrate hardware and biologics into unified service contracts.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's abbreviated review process for intrathecal pump modifications accelerates hardware iteration cycles, reducing time-to-market for enhanced delivery systems.
- Hospital pain management consolidation:Integrated delivery networks in the United States are standardizing on single-vendor intrathecal platforms to reduce procurement complexity and training overhead.
- Gadolinium-enhanced MRI protocol diffusion:Improved diagnostic sensitivity enables earlier intervention, expanding the addressable patient pool for chronic pain management devices.
Market Restraints
- Silicone catheter material constraints:Supply concentration among three specialized polymer suppliers creates vulnerability to input cost volatility and quality consistency issues.
- PMDA clinical data requirements:Japan's pharmaceutical and medical device agency demands extended local safety studies, elevating development costs for foreign pump manufacturers.
- Oral opioid substitution threat:Extended-release analgesic formulations compete for moderate arachnoiditis cases, compressing device eligibility to refractory pain populations.
Strategic Opportunities
- Germany's Diagnosis-Related Group recalibration:The G-DRG system is introducing dedicated reimbursement codes for intrathecal therapy, improving hospital margin profiles for pump implantation procedures.
- Bioresorbable catheter materials:Convergence of polymer science and microfabrication enables temporary intrathecal delivery without explantation surgery, opening pediatric and trauma applications.
- Telemedicine-integrated pump monitoring:Remote dosing adjustment protocols reduce specialist visit burden, creating channel access for rural and underserved geographies.
Industry Challenges
- Neurostimulation programming expertise scarcity:Qualified clinical specialists for intrathecal pump titration remain concentrated in major academic medical centers, limiting expansion into community hospital settings.
- ISO 14708 active implantable certification timelines:Extended electromagnetic compatibility testing for next-generation wireless pumps delays commercial launches by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arachnoiditis Market |
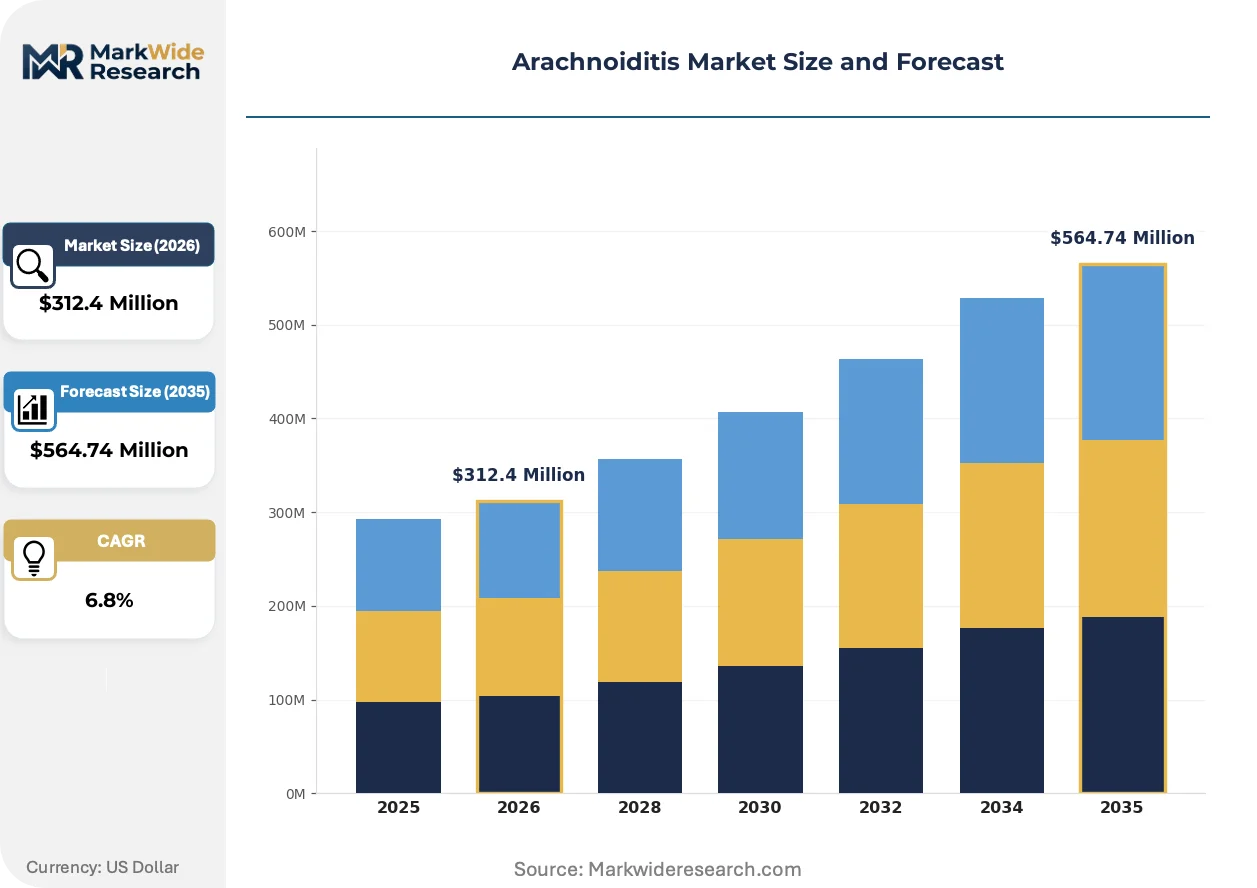
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Physical Therapy, Surgical Procedures, Pain Management Devices End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Settings Delivery Mode: Oral, Injectable, Transdermal, Intrathecal Treatment Approach: Corticosteroids, Antidepressants, Nerve Blocks, Surgery |
| Companies Covered | Pfizer Inc., Stryker, Medtronic, B. Braun Melsungen AG, Novartis AG, Boston Scientific Corporation, Johnson & Johnson, Nevro, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arachnoiditis Market Emerging Trajectories
Closed-loop feedback systems are displacing open-loop intrathecal delivery, enabling real-time cerebrospinal fluid pressure modulation that responds to patient movement and pain episodes without manual intervention.
Closed-loop intrathecal pumps with integrated pressure sensors are electrifying chronic pain management by enabling autonomous dose adjustment based on cerebrospinal fluid dynamics. Academic medical centers in the United States and Germany are piloting these systems for complex regional pain syndrome patients with arachnoiditis comorbidity. The technology is electrifying competitive positioning by compressing the service interval from monthly refill visits to quarterly maintenance, reducing hospital resource consumption.
EMA's Medical Device Regulation (MDR) recertification deadlines are forcing legacy pump manufacturers to rebuild technical documentation for Class III active implantable devices. The regulation demands expanded clinical evidence for long-term biocompatibility, particularly for silicone-based catheter materials in extended intrathecal exposure. European notified bodies are prioritizing review resources toward systems with integrated drug-reservoir authentication features, disadvantaging older platform architectures.
Hospital procurement committees are consolidating vendor relationships for pain management devices, favoring suppliers offering bundled hardware, biologics, and remote monitoring services. This concentration displaces standalone device vendors who lack pharmaceutical partnerships or cloud infrastructure capabilities. The shift is most visible in United States integrated delivery networks and German hospital federations, where total-cost-of-ownership models now dominate capital equipment decisions.
Arachnoiditis Market Segmentation
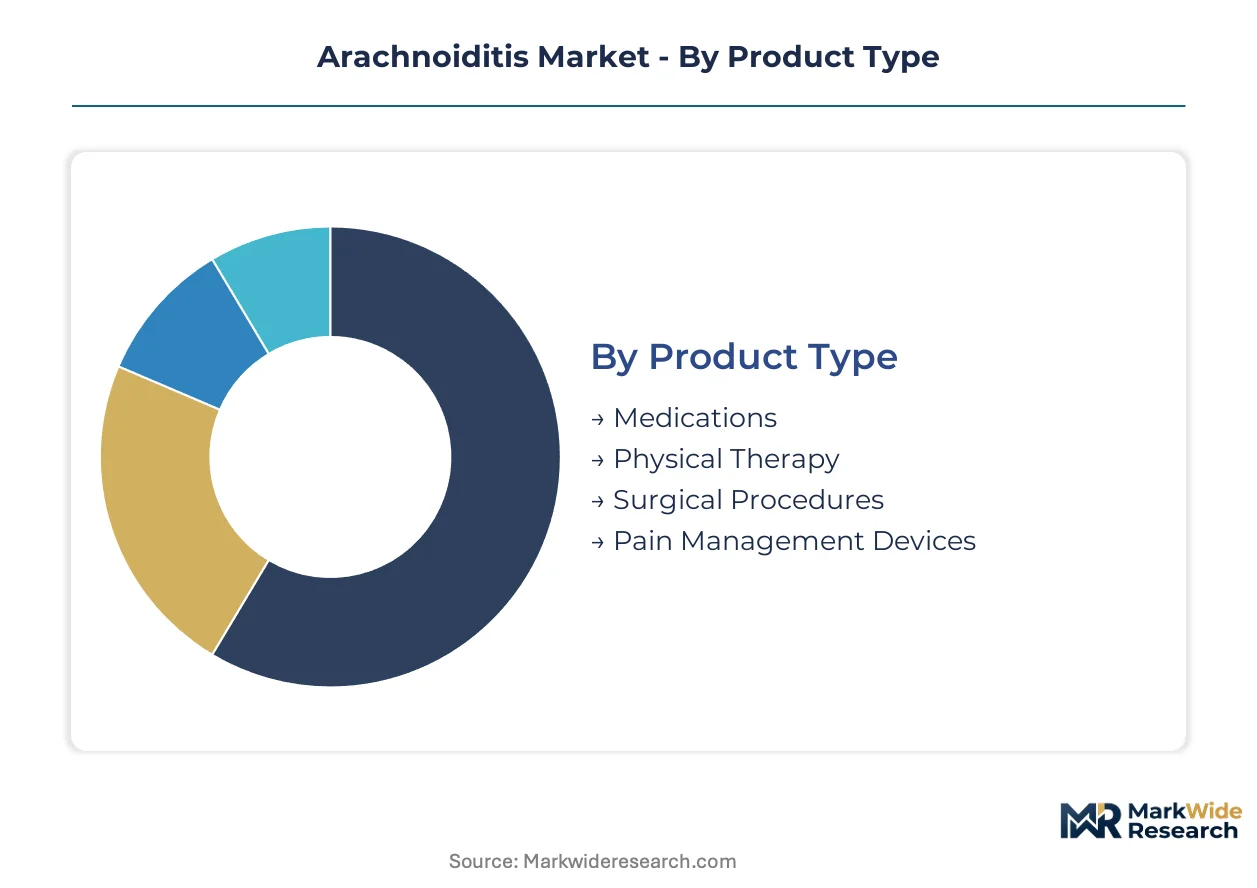
Segmentation in the arachnoiditis market reveals distinct procurement patterns across hardware, pharmaceuticals, and service delivery. Understanding these divisions enables stakeholders to align R&D investment with reimbursement pathways and patient access points.
Product Type:
The customization-to-standardization spectrum spans from patient-programmable hardware to off-patent pharmaceutical formulations, with proprietary device platforms commanding premium positioning against generic drug alternatives.
- Medications:Oral and injectable analgesics, including corticosteroids and neuropathic pain agents, form the volume foundation. Demand clusters in outpatient settings where physicians prioritize formulary compliance and prior authorization simplicity over device complexity.
- Pain Management Devices:Intrathecal pumps and external neuromodulation systems represent the technology frontier. United States hospital systems are consolidating procurement around single-vendor platforms to reduce training overhead and service contract fragmentation.
- Physical Therapy:Structured rehabilitation protocols address functional preservation in early-stage patients.
- Surgical Procedures:Decompression and adhesiolysis interventions serve progressive neurological deficit cases.
Leading the category by volume: Medications. Growing fastest: Pain Management Devices.
End User:
Cost tier stratification separates capital-intensive implantation sites from lower-acuity settings where pharmaceutical management dominates patient pathways.
- Hospitals:Academic medical centers and tertiary facilities perform intrathecal pump implantations and surgical interventions. Germany's hospital federations are standardizing pain management device procurement through G-DRG reimbursement optimization.
- Outpatient Clinics:Specialist pain management practices handle medication titration and pump refill protocols. These settings concentrate in United States metropolitan corridors with high specialist density.
- Rehabilitation Centers:Post-surgical recovery and functional restoration programs.
- Home Care Settings:Remote monitoring integration is expanding pump management beyond traditional clinical boundaries.
Highest procedure margins reside in hospitals. Fastest access expansion: Outpatient Clinics.
Delivery Mode:
Application intensity varies from chronic daily oral administration to episodic interventional delivery, with invasiveness correlating directly to reimbursement complexity and specialist involvement.
- Intrathecal:Direct cerebrospinal fluid delivery via implanted pumps enables targeted dosing with reduced systemic exposure. FDA 510(k) pathway streamlining accelerates hardware iteration for enhanced delivery systems.
- Oral:Extended-release formulations compete for moderate cases, compressing device eligibility to refractory populations.
- Injectable:Nerve blocks and depot formulations provide intermediate intervention options.
- Transdermal:Patch-based delivery offers patient convenience for stable pain regimens.
Intrathecal delivery commands premium positioning. Oral administration retains dominant patient volume.
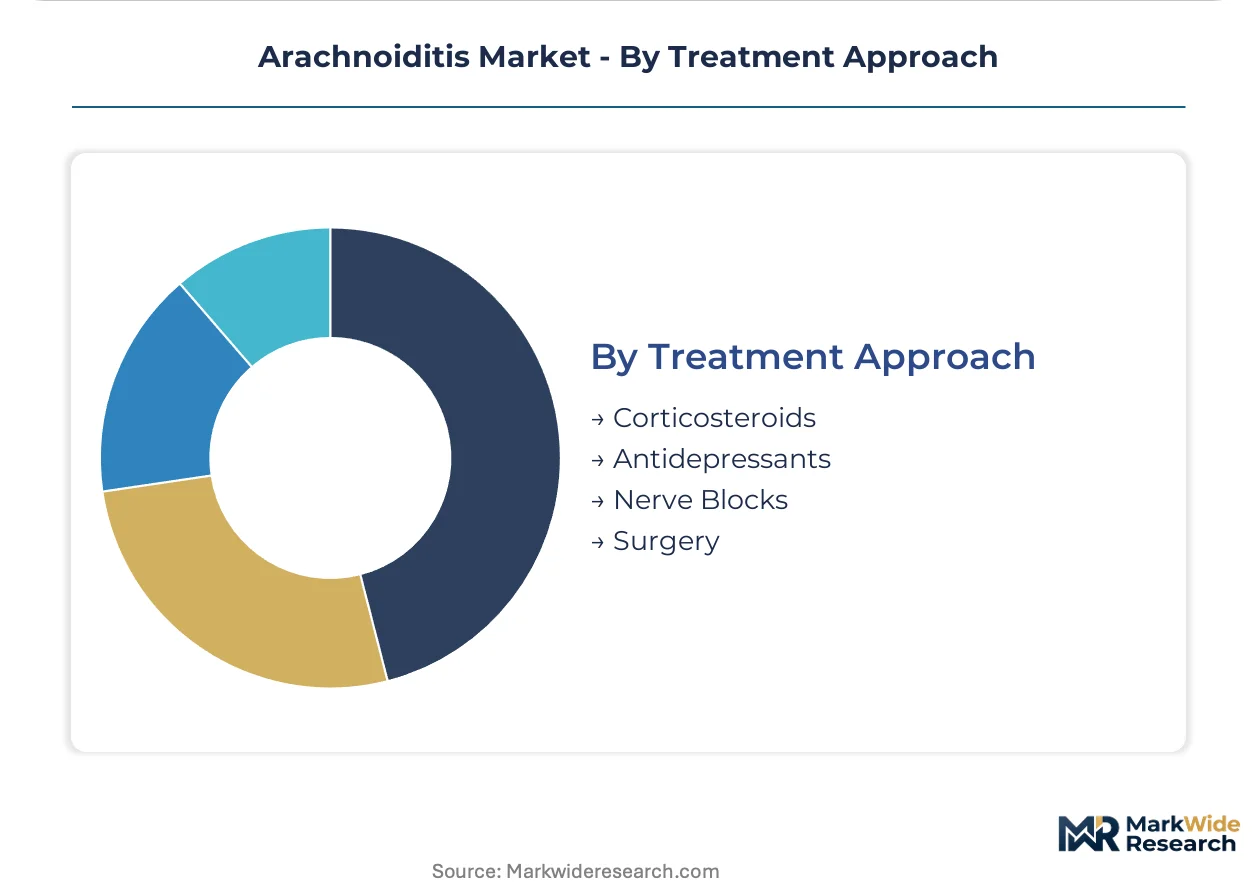
Treatment Approach:
Maturity differentiation separates decades-established corticosteroid protocols from emerging neuromodulation combinations and surgical salvage options.
- Corticosteroids:Epidural and intrathecal formulations remain first-line for inflammatory suppression. Pfizer Inc. leverages its analgesic portfolio to anchor long-term supply contracts with hospital systems.
- Surgery:Decompression and lysis of adhesions address mechanical compression in advanced cases. Stryker competes in surgical instruments used during these intervention procedures.
- Antidepressants:SNRIs and TCAs address neuropathic pain components.
- Nerve Blocks:Diagnostic and therapeutic injections localize pain generators.
Corticosteroids lead by prescription volume. Surgery carries highest per-procedure value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in the United States and Germany, while patient demand clusters in Japan and Western European markets with aging populations and established pain management infrastructure. Consumption patterns diverge sharply from production geography.
United States
Academic medical centers in Boston and Baltimore drive intrathecal pump adoption for complex regional pain syndrome cases. FDA 510(k) pathway streamlining accelerates hardware iteration cycles for neuromodulation devices. The Cleveland Clinic and Mayo Clinic anchor clinical trial networks for closed-loop delivery systems.
Germany
Hospital federations standardize procurement through G-DRG reimbursement optimization for pain management devices. EMA's MDR framework demands expanded clinical evidence for silicone-based catheter biocompatibility. Baden-Württemberg hosts specialized polymer suppliers serving catheter manufacturers.
Japan
Aging demographics expand the addressable pool for chronic pain interventions in Tokyo and Osaka metropolitan corridors. PMDA imposes extended local safety studies on intrathecal pump submissions, elevating foreign entrant costs. Yokohama clusters medical device distributors serving Southeast Asian export markets.
United Kingdom
NHS England reimbursement codes for intrathecal therapy shape hospital capital equipment decisions. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment requirements. London teaching hospitals concentrate specialist programming expertise for pump titration protocols.
Switzerland
Swissmedic maintains stringent active implantable certification timelines for wireless pump platforms. Basel anchors pharmaceutical corticosteroid manufacturing for European supply contracts. Zurich medical centers pilot telemedicine-integrated pump monitoring for rural access expansion.
Arachnoiditis Market Vendor Landscape
Top-tier vendors anchor the neuromodulation hardware layer, while mid-tier pharmaceutical suppliers compete on corticosteroid formulation contracts. The market structure favors integrated players bundling devices, biologics, and service contracts over standalone component vendors. Three archetypes dominate: diversified medtech conglomerates with intrathecal platforms, specialized pain management device manufacturers, and pharmaceutical firms leveraging analgesic portfolios for hospital supply agreements. Competitive moves center on strategic partnerships between hardware and biologics producers, plus backward integration into specialized catheter polymer supply.
Within the diversified medtech tier, Medtronic plc and Boston Scientific Corporation exemplify platform-centric positioning through proprietary delivery systems and neuromodulation hardware. Stryker Corporation occupies a distinct surgical instruments position serving decompression and adhesiolysis procedures. These three companies represent the dominant competitive anchors, with Medtronic and Boston Scientific exemplifying device-biologic bundling strategies while Stryker anchors the interventional surgical segment.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Stryker |
| Medtronic |
| B. Braun Melsungen AG |
| Novartis AG |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Nevro |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Silicone polymer feedstock costs cascade through catheter manufacturing tiers, with specialized elastomer grades commanding premium positioning against commodity alternatives as hospital procurement committees consolidate vendor relationships. This input-cost concentration amplifies pricing power for integrated pump manufacturers while squeezing standalone component suppliers.
Pricing Analysis
Margin tightening in the intrathecal pump segment reflects hospital standardization on single-vendor platforms and bundled service contracts. Three-tier pricing structure across premium closed-loop systems, standard programmable pumps, and economy fixed-rate devices separates hardware tiers by sensor integration and wireless capability. Cost compression accelerates in the medication reservoir category as Pfizer and Novartis compete on corticosteroid supply agreements. Outpatient clinics exhibit highest price sensitivity due to reimbursement code volatility, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Freight cost volatility from Baden-Württemberg polymer suppliers to United States assembly plants elevates landed costs for catheter components, with airfreight premiums during quality audits adding 15-20% to procurement budgets. Manufacturing concentrates in Germany, the United States, and Switzerland for active implantable devices, while Japan hosts specialized pressure sensor fabrication. Silicone elastomer, titanium pump housings, and lithium primary cells constitute critical input dependencies. Single-source vulnerability for medical-grade silicone creates exposure to pharmaceutical-grade polymer allocation decisions. Distribution runs through hospital GPO contracts and specialized neuromodulation distributors serving outpatient pain clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer supply scarcity props pricing for catheter-integrated pump systems, constraining volume expansion until alternative bioresorbable materials achieve regulatory clearance.
For Market Incumbents: Lock in catheter polymer supply through long-term offtake agreements with Baden-Württemberg suppliers before bioresorbable alternatives disrupt material economics. Defend against oral opioid extended-release substitution by embedding dosing algorithms into hospital EMR workflows, creating switching costs that protect intrathecal device eligibility. Prioritize ISO 14708 certification investment to compress electromagnetic compatibility testing timelines for wireless pump launches. For New Entrants and Emerging Players: Capture telemedicine-integrated pump monitoring white space in rural United States corridors where specialist scarcity limits incumbent service reach. Target Germany's G-DRG reimbursement recalibration window to establish presence before hospital federation procurement consolidation hardens. Pursue pediatric trauma applications for bioresorbable catheter platforms, a segment incumbents neglect due to smaller addressable volumes. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier pain management device manufacturers with FDA 510(k) clearances but limited pharmaceutical partnerships, particularly in Switzerland and the United Kingdom where MDR recertification costs strain balance sheets. Five-to-ten year viability hinges on closed-loop algorithm IP and cloud infrastructure capabilities rather than hardware manufacturing scale. Watch PMDA accelerated review pathway announcements as inflection signal for Japan market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Abbreviated review cycles for pump modifications compress competitor response times to 8-12 months. |
| Hospital System Partnership | Integrated delivery network sole-source contracts lock out standalone device vendors from volume procurement. |
| Software Companion Development | Cloud-based dosing algorithms create recurring revenue streams beyond hardware implantation. |
| Reimbursement Strategy | G-DRG code optimization in Germany directly improves hospital margin profiles for pump procedures. |
| CE Marking Pathway | MDR technical documentation rebuilds for silicone biocompatibility evidence delay European launches. |
Methodological Framework
FDA 510(k) filings, EMA MDR technical documentation, and hospital GPO contract databases formed the secondary backbone, supplemented by CMS Medicare reimbursement code analysis and Japan MHLW pricing surveys. Primary interviews with pain management clinicians, biomedical engineers, hospital purchasing committee directors, and intrathecal pump programming specialists validated demand assumptions and procurement timeline estimates. Bottom-up patient pool modeling and top-down device shipment triangulation anchored volume forecasts.
Bottom-up segmentation across product type, end user, delivery mode, and treatment approach dimensions combined with top-down macroeconomic adjustment for healthcare expenditure growth. CAGRs derived from procedure volume trajectories, pricing elasticity estimates, and technology substitution curves across the projection horizon. Intrathecal pump implantation rates by diagnostic category and corticosteroid formulation market shares informed segment-level growth attribution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA regulatory timeline shifts, bioresorbable material clinical trial readouts, and oral opioid reformulation competitive threats. Forecasts reflect documented assumptions on reimbursement stability and specialist training pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Global Neuromarketing Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Labyrinthitis Market
Neurology
Cervical Dystonia Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Status Epilepticus Treatment Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Movement Disorder Market
Neurology
South Korea Neurology Devices Market
Neurology
Spasticity Treatment Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
Grand Mal Seizure Treatment Market
Neurology
Transverse Myelitis Treatment Market
Neurology
Aneurysmal Subarachnoid Hemorrhage Market